
 Instant Water Heater Market | 2026-2036
Instant Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Water Heater Market Analysis
Condensing heat-exchanger technology and smart IoT-enabled temperature control is reshaping how instant water heaters are engineered and serviced. Bosch Thermotechnik GmbH leverages its European manufacturing footprint to dominate high-efficiency gas-fired segments. A. O. Smith Corporation anchors North American distribution through deep wholesale plumbing relationships. Stiebel Eltron specializes in precision electric tankless systems for residential retrofit applications.
An instant water heater is a flow-activated thermal device that heats water on demand without storage, typically achieving thermal efficiency above 90% through gas combustion or electric resistance elements, and serves commercial kitchens, residential bathrooms, and industrial wash stations where space constraints and continuous hot-water availability matter. Electric units lead in urban apartments across Asia-Pacific due to simpler venting requirements and lower installation costs. Heat-pump variants represent the fastest-growing product category as building codes tighten carbon-intensity thresholds. Gas tankless systems retain margin pools in cold-climate markets where flow-rate demands exceed electric capacity.
The US Department of Energy enforces minimum energy factor standards that disqualify non-condensing gas models from federal compliance, while the EU Ecodesign Directive and F-Gas Regulation restrict refrigerant choices in heat-pump water heaters. China's GB standards and MIIT efficiency labeling program mandate standby-loss limits that favor inverter-driven electric designs. Stakeholders must monitor how refrigerant-phaseout timelines and electrification subsidies in major economies redirect R&D spending across heating-technology portfolios.
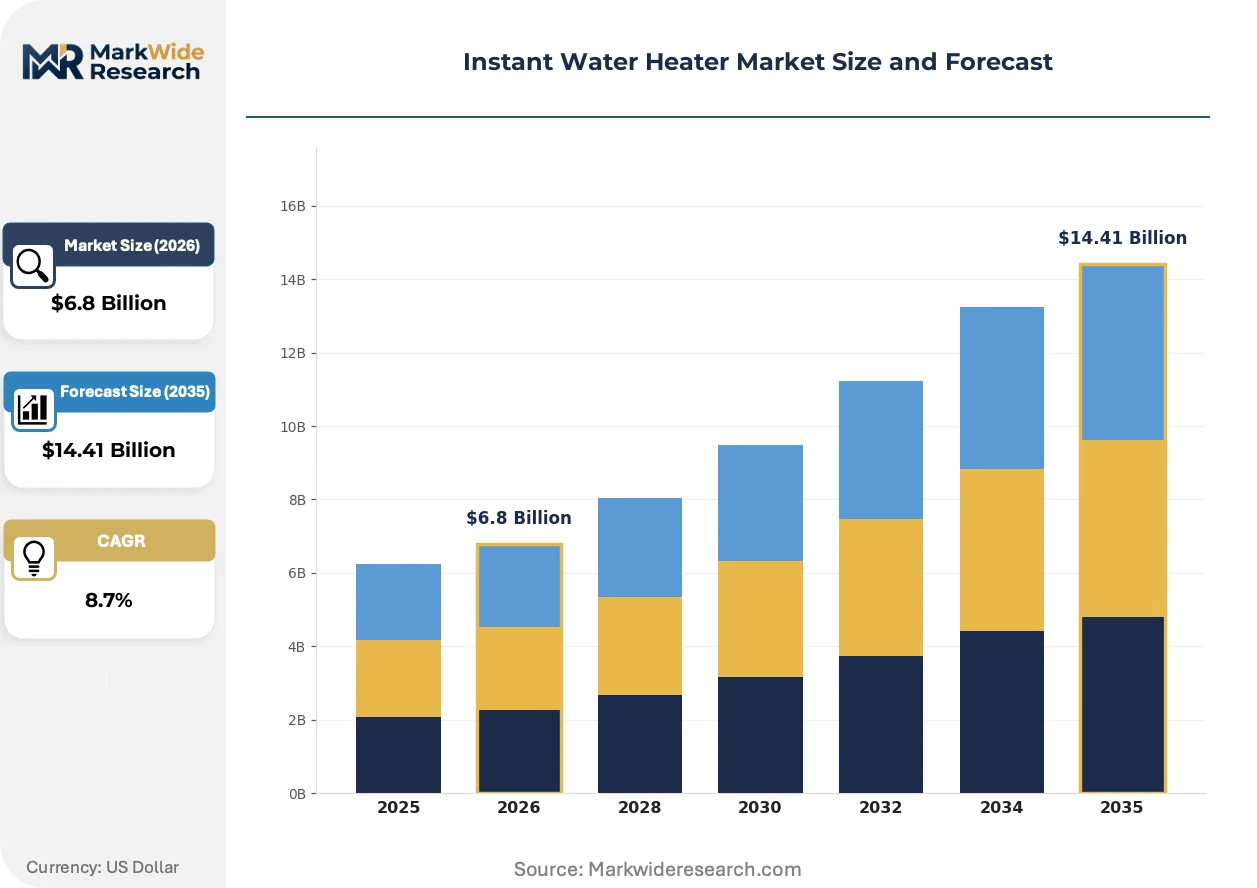
Market Dynamics
Electrification mandates across residential construction codes are compressing the addressable market for gas-fired units while expanding inverter-driven electric and heat-pump categories, forcing manufacturers to reconfigure product portfolios around refrigerant chemistry and power electronics.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants accelerates R&D investment in CO₂ and hydrocarbon heat-pump architectures for water heating applications.
- Urban apartment densification:Compact electric tankless units penetrate high-rise residential stock in India and China where gas venting proves structurally prohibitive.
- Condensing heat-exchanger advances:Secondary heat recovery in gas-fired systems pushes thermal efficiency past 95%, satisfying Ecodesign Directive thresholds in cold-climate European markets.
Market Restraints
- Copper and rare-earth input volatility:Heat-exchanger coils and permanent-magnet motors expose manufacturers to commodity price swings that compress gross margins on electric units.
- Installation skill scarcity:Condensing gas systems demand certified technicians for sealed combustion venting, limiting deployment velocity in markets with fragmented HVAC trades.
- Heat-pump performance ceiling:Ambient temperature sensitivity restricts coefficient-of-performance in northern latitudes, preserving residual demand for combustion backup.
Strategic Opportunities
- US Inflation Reduction Act credits:Residential clean energy tax incentives subsidize heat-pump water heater retrofits, opening margin pools in replacement markets previously dominated by resistance electric.
- IoT-enabled predictive maintenance:Connected diagnostics platforms create recurring revenue streams through subscription service contracts tied to fleet installations in hospitality and healthcare.
- Commercial kitchen electrification:High-temperature sanitization requirements in foodservice drive demand for 180°F-capable electric tankless systems as gas hookup moratoria spread across California and New York municipalities.
Industry Challenges
- Refrigerant certification timelines:Safety approvals for flammable A3 and mildly flammable A2L refrigerants lag product development cycles, delaying heat-pump launches in safety-regulated jurisdictions.
- Legacy electrical infrastructure retrofit:240V/60A circuit requirements for high-capacity electric tankless units trigger panel upgrade costs that stall sales in older residential stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Water Heater Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Solar, Heat Pump Installation Type: Wall-Mounted, Point-of-Use, Centralized, Portable End User: Residential, Commercial, Industrial, Hospitality Heating Technology: Tankless, Tank, Instant, Active |
| Companies Covered | Ariston Thermo S.p.A., Navien, A. O. Smith Corporation, Stiebel Eltron, Bradford White Corporation, Rheem Manufacturing Company, Bosch Thermotechnik GmbH, Takagi, Rinnai Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Water Heater Market Emerging Trajectories
Product engineering in instant water heating is pivoting from thermal efficiency optimization toward system-level integration with building energy management and grid-responsive load control.
Silicon carbide power electronics in inverter-driven electric tankless units is rendering obsolete traditional TRIAC-based phase-control heating elements. Multi-family developers in South Korea and Japan specify these systems for their compatibility with demand-response protocols. The shift compresses component supplier margins while elevating firmware and power-semiconductor vendors in the value chain.
China's GB standards for standby-loss limits tighten incrementally under MIIT supervision, forcing domestic manufacturers toward variable-frequency drive architectures. Export-oriented suppliers must dual-certify products for domestic efficiency labels and EU Ecodesign compliance. The regulatory layering favors vertically integrated producers with in-house inverter design capability.
Building contractors in Germany and the Netherlands now bundle heat-pump water heaters with photovoltaic and battery storage in integrated tenders. This procurement consolidation displaces standalone water heater specifications and compresses distributor margins while rewarding system integrators with project-scale economics. Municipal housing authorities in Copenhagen and Rotterdam pilot these packages in social housing retrofits.
Instant Water Heater Market Segmentation
Instant water heater manufacturers configure product portfolios around four intersecting dimensions: energy source, physical mounting, customer vertical, and thermal architecture. Each dimension carries distinct margin profiles, certification burdens, and installation complexity that shape go-to-market economics.
Product Type:
Use-case spectrum spans compact apartment retrofits requiring simple venting to whole-building decarbonization mandates demanding heat-pump integration.
- Electric:Resistance-element or inverter-driven designs eliminate combustion venting entirely. Urban high-rises in India and China specify these units where gas infrastructure is structurally prohibited, with MIIT efficiency labels favoring variable-frequency architectures.
- Gas:Condensing and non-condensing combustion systems deliver higher flow rates for cold-climate applications. Ecodesign Directive thresholds in Germany and the Netherlands now disqualify non-condensing models, compressing the addressable market to 95%+ efficiency units.
- Solar:Evacuated-tube or flat-plate collector integration with electric backup handles diurnal variability. Installations cluster in Australia's sun-belt housing developments where state-level renewable mandates apply.
- Heat Pump:Refrigerant-based thermal extraction achieves coefficient-of-performance multiples above resistance heating. US Inflation Reduction Act credits subsidize retrofits in replacement markets previously dominated by electric resistance.
Established volume favors Electric; emerging adoption favors Heat Pump.
Installation Type:
Physical mounting determines distribution channel, installation skill requirements, and replacement cycle frequency.
- Wall-Mounted:Compact enclosures fasten to structural surfaces in bathrooms and utility closets. Residential retrofits in Japan and South Korea favor these units for space-constrained multi-family stock.
- Point-of-Use:Undersink or countertop proximity eliminates distribution piping losses. Commercial kitchens in California municipalities specify 180°F-capable electric variants as gas hookup moratoria spread.
- Centralized:Whole-building systems with recirculation loops serve multiple draw points simultaneously. Hospitality properties in Dubai and Saudi Arabia deploy these for peak-demand management in guest room towers.
- Portable:Self-contained camping and outdoor units with propane or battery power. Recreational vehicle OEMs in the US integrate these for off-grid capability compliance with NHTSA safety standards.
Replacement velocity runs highest for Wall-Mounted; specification value concentrates in Centralized.
End User:
Customer verticals separate price-sensitive volume transactions from engineered project sales with extended service contracts.
- Residential:Single-family and multi-family household installations driven by appliance upgrade cycles and new construction electrification codes. China's urbanization programs accelerate household penetration in tier-2 and tier-3 cities.
- Commercial:Office buildings, retail, and institutional facilities with intermittent but high-volume draw patterns. BIS efficiency labeling in India mandates minimum performance standards for commercial-scale electric units.
- Industrial:Process heating and wash station applications requiring continuous high-temperature delivery. Food processing plants in Brazil's São Paulo state specify these for sanitization compliance with ANVISA hygiene regulations.
- Hospitality:Hotels and resorts with extreme peak-demand profiles and guest experience sensitivity. IoT-enabled predictive maintenance platforms create recurring revenue through subscription service contracts in this vertical.
Volume concentration sits with Residential; margin expansion favors Hospitality.
Heating Technology:
Thermal architecture separates instantaneous flow-activated designs from storage-based systems with standby loss profiles.
- Tankless:Flow-activated heat exchangers eliminate standby losses entirely. These units gain share fastest in European markets where Ecodesign Directive standby-loss limits tighten incrementally.
- Tank:Insulated storage vessels with heating element or burner maintenance. Legacy residential stock in the US Midwest retains these for compatibility with existing electrical panels avoiding 240V/60A upgrade costs.
- Instant:Marketing designation overlapping with tankless, often specifying sub-3-second activation times. Premium positioning in South Korean apartment specifications emphasizes this activation performance.
- Active:Heat-pump or solar-thermal systems with powered circulation and control logic. Denmark's municipal housing authorities pilot these in social housing retrofits bundled with photovoltaic and battery storage.
Technology transition favors Tankless; installed base inertia preserves Tank.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports tankless electric units to India and Southeast Asian markets where urban high-rise construction accelerates. German manufacturers ship condensing gas systems to cold-climate European neighbors under Ecodesign Directive harmonization.
China
Tier-2 and tier-3 city urbanization drives household appliance upgrades at scale. MIIT efficiency labeling mandates standby-loss limits that favor inverter-driven electric architectures. Manufacturing clusters in Guangdong province supply export markets across Asia-Pacific with compact wall-mounted units.
Germany
Residential building energy codes compress the addressable market for non-condensing gas models. The EU Ecodesign Directive and F-Gas Regulation redirect R&D spending toward CO₂ heat-pump water heaters. Industrial concentration in North Rhine-Westphalia hosts system integrators bundling heat-pump units with photovoltaic and battery storage.
United States
The Inflation Reduction Act subsidizes heat-pump water heater retrofits in replacement markets previously dominated by resistance electric. DOE minimum energy factor standards disqualify non-condensing gas models from federal compliance. California and New York municipalities spread gas hookup moratoria that electrify commercial kitchen specifications.
India
Urban apartment densification penetrates high-rise residential stock where gas venting proves structurally prohibitive. BIS efficiency labeling mandates minimum performance standards for commercial-scale electric units. Manufacturing activity concentrates in Maharashtra and Gujarat serving domestic demand and regional export.
Japan
Multi-family developers specify silicon carbide inverter-driven systems for demand-response protocol compatibility. METI supervision shapes efficiency standards that accelerate technology transitions. Kanto region housing authorities pilot integrated tenders bundling water heating with building energy management systems.
Instant Water Heater Market Vendor Landscape
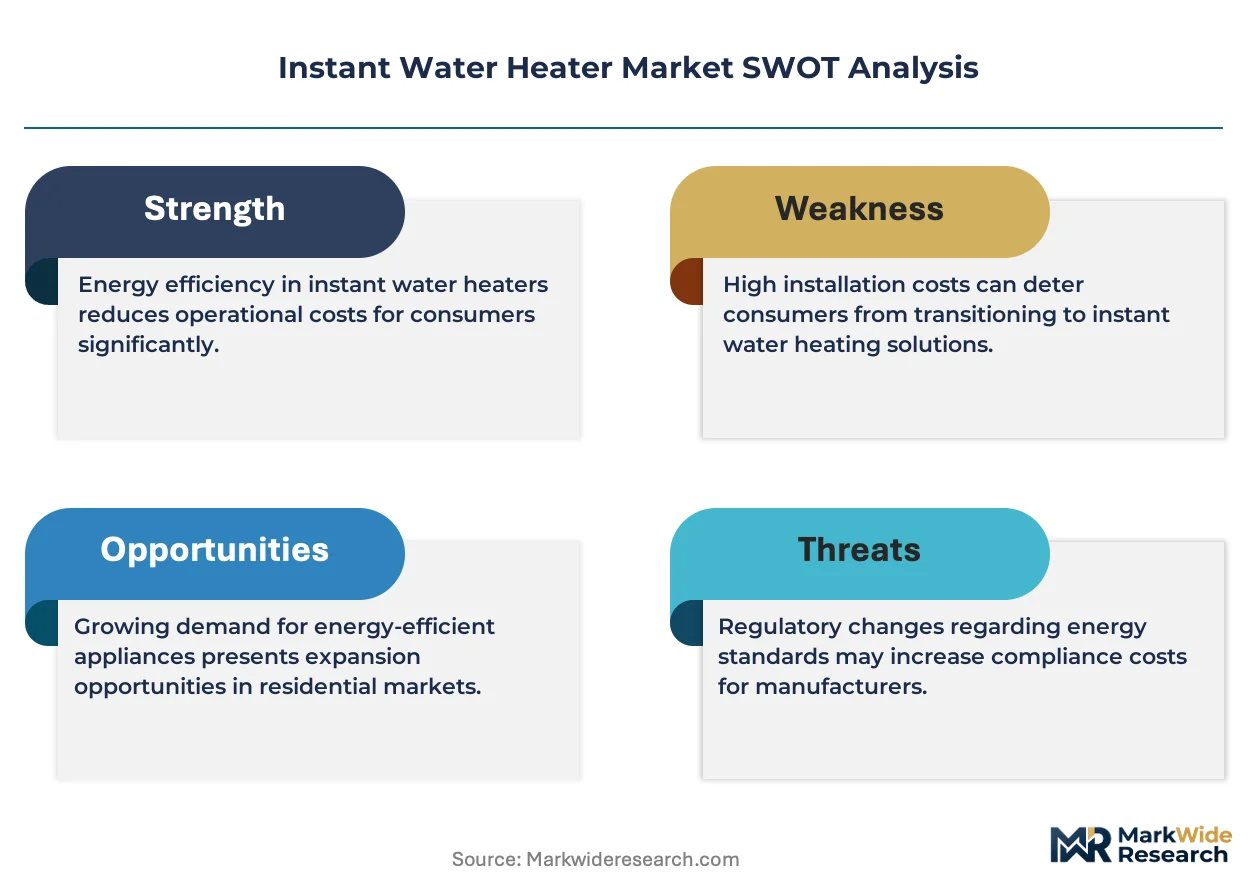
Channel-controlling players compete with product-specialist players across fragmented distribution architectures. The vendor base separates into wholesale plumbing incumbents with deep contractor relationships, vertically integrated heating conglomerates with captive component supply, and precision electric specialists targeting retrofit applications. Dominant competitive moves include portfolio diversification around refrigerant chemistry and power electronics, plus geographic expansion through dual-certification strategies for overlapping regulatory regimes.
Among European-based heating conglomerates, Bosch Thermotechnik GmbH and Ariston Thermo S.p.A. exemplify scale-driven archetypes with manufacturing footprints spanning multiple efficiency regulatory zones. Stiebel Eltron represents the precision-specialist tier focused on electric tankless architectures. These three anchors illustrate how competitive positioning fragments across channel control, technology specialization, and vertical integration depth.
| Leading Market Players |
|---|
| Ariston Thermo S.p.A. |
| Navien |
| A. O. Smith Corporation |
| Stiebel Eltron |
| Bradford White Corporation |
| Rheem Manufacturing Company |
| Bosch Thermotechnik GmbH |
| Takagi |
| Rinnai Corporation |
| Others |
Supply Flow & Price Mechanics
Guangdong province manufacturing clusters for silicon carbide inverters and rare-earth permanent-magnet motors concentrate upstream supply leverage, positioning inverter design capability as the primary margin pool downstream where OEMs compete on MIIT efficiency certification tiers.
Pricing Analysis
Next-generation heat-pump architectures command substantial premiums over legacy resistance-element designs, while condensing gas systems price at mid-tier positioning against non-condensing legacy stock. Three-tier pricing structure across premium certified-heat-pump, standard condensing-gas, and economy resistance-electric levels stratifies the market, with EU Ecodesign Directive compliance tiers and MIIT efficiency labels serving as the primary price differentiation drivers. Cost compression in economy electric segments is intensifying because of copper coil commodity volatility. Residential retrofit buyers in legacy housing stock exhibit highest price sensitivity, while hospitality fleet operators demonstrate lowest sensitivity due to lifecycle cost framing.
Supply Chain Analysis
Contract manufacturing for power electronics concentrates among Taiwan and South Korea foundries, with final assembly capacity clustering in China's Guangdong and Zhejiang provinces. Heat-exchanger copper coil supply draws from Chilean mining output and Chinese semi-fabricated wire producers, while refrigerant chemistry feeds from Japanese and German specialty chemical suppliers. Single-source vulnerability in silicon carbide wafer supply presents structural risk given automotive sector competition for substrate capacity. Distribution runs through wholesale plumbing channels in North America and direct-to-developer specification teams in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as electrification mandates splinter demand across incompatible technology architectures, generating niche specialization openings for regional players with targeted certification portfolios.
For Market Incumbents: Harden market position through captive inverter design capability and dual-certification strategies spanning MIIT efficiency labels and EU Ecodesign compliance. Acquire regional heat-pump specialists in Germany and the Netherlands to secure system-integration bundling relationships with municipal housing authorities. Channel control through wholesale plumbing networks remains the critical defensive lever against direct-to-developer disintermediation.
For New Entrants and Emerging Players: Pursue point-of-use electric tankless penetration in California and New York commercial kitchens where gas hookup moratoria eliminate incumbent gas-fired competition. Target India tier-2 city high-rise residential stock where BIS efficiency mandates create specification windows for certified new entrants. Lead with IoT-enabled predictive maintenance subscriptions to differentiate from transactional hardware competitors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed heating conglomerates holding sub-scale European manufacturing footprints and aging refrigerant technology portfolios. Long-term viability over the coming decade hinges on successful pivot from combustion-centric to heat-pump-centric product mixes. Watch for inflection in US Inflation Reduction Act credit utilization rates as the signal indicating replacement market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | Accelerates market entry for manufacturers lacking CO₂ refrigerant expertise under F-Gas Regulation timelines. |
| Silicon Carbide Inverter Integration | Enables MIIT Tier-1 efficiency certification and demand-response compatibility for South Korean developers. |
| Dual-Certification Manufacturing Footprint | Captures simultaneous access to China's domestic market and EU export channels under harmonized Ecodesign standards. |
| IoT Predictive Maintenance Platform Launch | Creates recurring revenue streams through hospitality fleet subscription contracts tied to uptime guarantees. |
| Refrigerant Chemistry Joint Venture | Secures A2L and hydrocarbon supply chains ahead of safety approval bottlenecks in regulated jurisdictions. |
Methodological Framework
Initial hypotheses were tested against primary input from product engineering directors at heating equipment manufacturers, HVAC contractor network managers, municipal housing authority procurement officers, and commercial kitchen facilities managers, then refined through secondary validation against MIIT efficiency label databases, EU Ecodesign Directive compliance registries, US DOE energy factor certification listings, and customs trade flow records for heat-exchanger copper coil imports. Bottom-up unit shipment estimates by technology segment were triangulated against top-down market value reconstructions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value through segmentation by energy source, heating technology architecture, installation mounting type, and end-use vertical. CAGRs were derived from installed base replacement cycle analysis overlaid with new construction electrification code adoption curves, incorporating refrigerant-phaseout timelines and subsidy program enrollment trajectories as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in residential construction permit issuance, copper futures pricing, or electrification subsidy appropriations would shift the trajectory. Forecasts reflect documented assumptions regarding technology transition rates and regulatory enforcement intensity. Quarterly review of MIIT label issuance volumes, EU heat-pump import statistics, and US IRA credit claim data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
Low Voltage Protection Control Market