
 Composite Line Post Insulators Market | 2026-2036
Composite Line Post Insulators Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Line Post Insulators Market Insights
China is narrowing its supply-demand gap for composite line post insulators through expanded domestic polymer compounding and pultrusion capacity. Siemens Energy leverages captive silicone rubber formulation labs to protect margin pools on 220 kV-plus orders. Hubbell Power Systems anchors North American utility procurement through ANSI-certified dead-end and strain insulator portfolios. NGK Insulators competes with hybrid ceramic-composite designs that bridge traditional porcelain reliability with polymer weight advantages.
Composite line post insulators are cylindrical or conical structural supports manufactured from glass-fiber reinforced plastic cores sheathed in silicone rubber or polymer housings, designed to mechanically suspend or support energized conductors while electrically isolating them from grounded structures. Their silicone rubber sheds provide hydrophobic surfaces that suppress leakage currents under contaminated or humid conditions, making them critical for overhead transmission lines in coastal, desert, and industrial pollution zones. Suspension and strain insulators dominate product type revenue due to their deployment density on high-voltage towers, while dead-end configurations capture premium pricing from specialized terminal station applications. The utilities end user segment sustains the deepest procurement volumes, though industrial microgrid build-outs are expanding the addressable base for medium-voltage pin insulator variants.
IEC 61109 and ANSI C29.11 establish minimum mechanical and electrical performance thresholds that determine product qualification for grid tenders across Europe and North America. India's CEA technical standards and China's GB/T 19519 specifications add national compliance layers that favor localized testing and certification investments. REACH and RoHS frameworks in Europe restrict certain flame retardant additives, pushing compounders toward halogen-free silicone formulations. Stakeholders must monitor evolving grid resilience mandates and material substitution timelines as polymer formulations displace legacy porcelain across voltage classes.
Market Dynamics
State Grid Corporation's ultra-high-voltage transmission build-out is compressing procurement cycles for polymer-based alternatives, forcing compounders to accelerate pultrusion capacity expansion ahead of traditional porcelain phase-out timelines.
Growth Catalysts
- ANSI C29.11 certification mandates:North American utilities now require composite insulator qualification for 115 kV-plus corridor tenders, locking in polymer procurement quotas across transmission operators.
- China's dual carbon goals:MEE directives on grid decarbonization prioritize lightweight composite structures that reduce steel tower mass and embodied carbon in new UHV lines.
- Silicone rubber hydrophobicity:Coastal and desert utilities specify polymer sheds for contamination-resistant performance where porcelain flashover rates spike during humidity cycles.
Market Restraints
- Glass fiber roving supply concentration:Pultrusion-grade E-glass capacity clusters in Chinese and German manufacturing basins, exposing compounders to input volatility during energy price spikes.
- REACH additive restrictions:ECHA halogen-free mandates eliminate legacy brominated flame retardants from silicone formulations, forcing reformulation costs onto European compounders.
- Porcelain residual reliability:Conservative transmission operators in earthquake-prone Japanese corridors retain ceramic-composite hybrids for seismic load assurance.
Strategic Opportunities
- India CEA technical standards:Localization mandates for 66 kV-plus insulator testing create captive demand for domestic polymer compounding and pultrusion joint ventures.
- Industrial microgrid build-outs:Medium-voltage pin insulator variants capture new demand from data center and manufacturing campus self-generation clusters.
- Condition-based monitoring convergence:Embedded fiber-optic strain sensors in FRP cores enable predictive maintenance contracts that bundle hardware with analytics subscriptions.
Industry Challenges
- IEC 61109 type-test duration:5,000-hour multi-stress qualification protocols stretch product development timelines to 18-24 months, freezing capital in pre-revenue inventory.
- Legacy tower retrofit compatibility:Composite insulator hardware interfaces require custom forging for aged steel structures, complicating installation contractor training and tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Line Post Insulators Market |
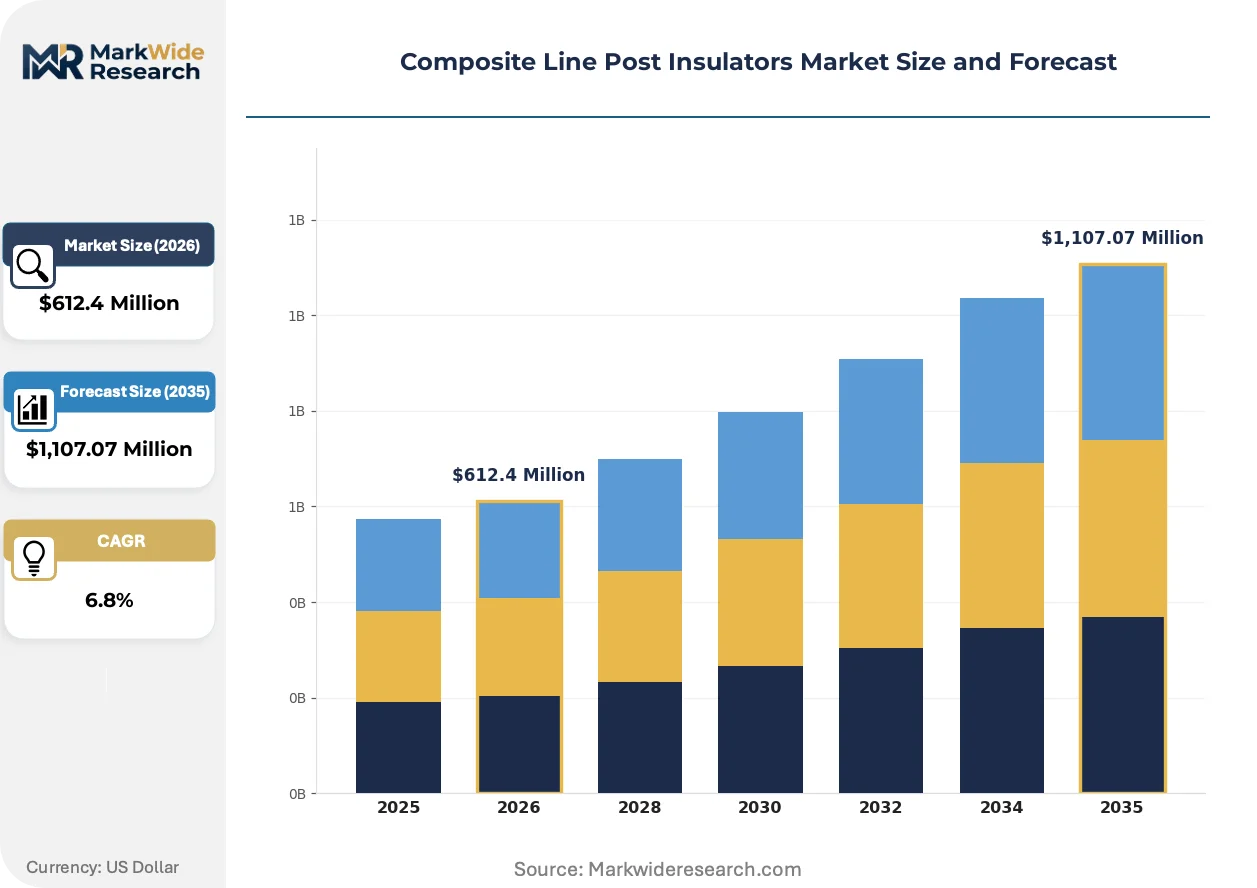
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suspension Insulators, Strain Insulators, Pin Insulators, Dead-End Insulators End User: Utilities, Industrial, Commercial, Residential Material: Polymer, Glass-Fiber Reinforced Plastic, Silicone Rubber, Porcelain Installation Type: Onshore, Offshore, Overhead, Underground |
| Companies Covered | Siemens Energy, Hitachi Energy, Hubbell Power Systems, PFISTERER, TE Connectivity, ABB, NGK Insulators, Seves Group, Lapp Insulators, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Line Post Insulators Market Trends and Innovations
Polymer formulation chemistry and embedded sensing architectures are redrawing competitive boundaries between material suppliers and grid infrastructure vendors.
Room-temperature vulcanized silicone rubber with nano-alumina filler is rendering obsolete traditional HTV silicone in high-pollution corridors. Indian and Middle Eastern utilities specify RTV-coated FRP cores for 132 kV desert lines where sand abrasion degrades conventional sheds. The shift compresses compounder margins on legacy HTV formulations while opening premium pricing for nano-filled custom blends.
REACH and RoHS frameworks in Europe are banning halogenated flame retardants from electrical insulation compounds. ECHA's 2025 sunset dates for decaBDE and HBCDD are forcing silicone formulators toward magnesium hydroxide and phosphorus-based alternatives. German and French transmission operators now require third-party halogen-free certification as a tender gate, privileging compounders with captive testing laboratories.
Utility procurement offices are unbundling hardware supply from installation services, reversing decades of bundled EPC contracting. State Grid Corporation and Southern California Edison now issue separate lots for insulator supply and live-line installation, squeezing margin from turnkey contractors. The fragmentation favors specialized manufacturers with ANSI and GB/T certification depth over integrated construction groups.
Composite Line Post Insulators Market Segmentation
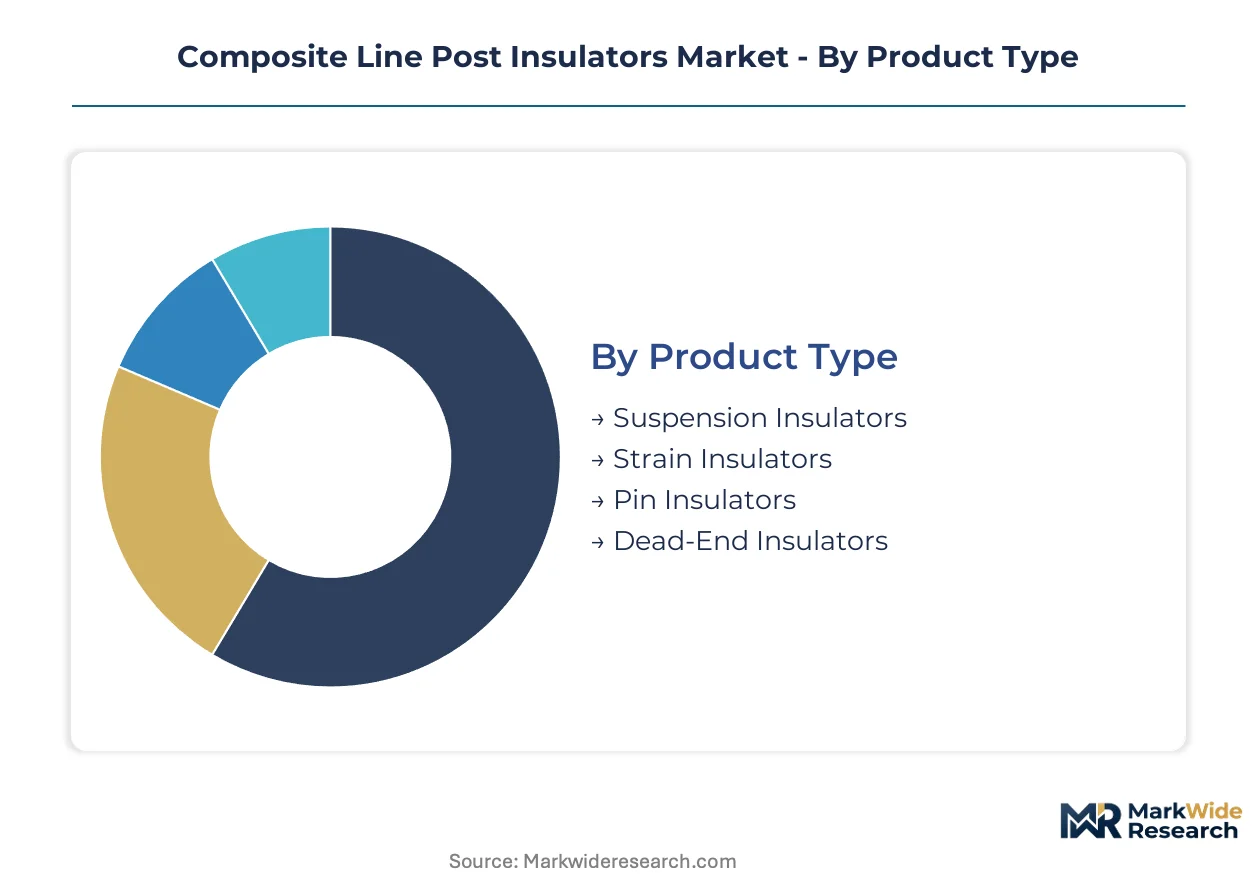
Composite line post insulators serve distinct electrical and mechanical functions across voltage classes and environmental conditions. Segmentation reveals where polymer formulations displace legacy materials and which installation contexts command premium specifications.
Product Type:
Application context determines mechanical load requirements and shed geometry specifications for each configuration.
- Suspension Insulators:These vertical-load-bearing units suspend energized conductors from tower cross-arms through FRP core rods sheathed in hydrophobic silicone rubber sheds. State Grid Corporation deploys suspension strings at 110 kV through 1,000 kV on ultra-high-voltage corridors where reduced tower mass offsets polymer cost premiums.
- Strain Insulators:Designed to withstand longitudinal conductor tension at line angles and dead-ends, these units combine high mechanical strength with compact shed profiles. Indian utilities specify strain configurations for 66 kV and 132 kV rural electrification where right-of-way constraints favor lighter hardware.
- Pin Insulators:Rigid support units for distribution voltages up to 33 kV, manufactured through pultrusion of glass-fiber cores with polymer housings.
- Dead-End Insulators:Terminal station configurations handling maximum mechanical loads at substation take-off points.
Suspension Insulators holds installed capacity. Dead-End Insulators is rotating up the share rankings.
End User:
Customer type dictates procurement scale, certification requirements, and service contract structures.
- Utilities:Transmission and distribution operators account for bulk procurement volumes through multi-year framework agreements. China's provincial grid companies aggregate demand for 220 kV-plus corridors, while European TSOs specify REACH-compliant silicone formulations under ECHA mandates.
- Industrial:Manufacturing campuses and data centers drive medium-voltage demand for microgrid isolation hardware. Petrochemical facilities in the Middle East specify polymer insulators for coastal atmospheric conditions where salt contamination degrades porcelain performance.
- Commercial:Property developers and retail chains procure distribution-class units for on-site substations.
- Residential:Rural electrification programs and suburban housing developments generate fragmented low-voltage demand.
Utilities holds installed capacity. Industrial is rotating up the share rankings.
Material:
Compound chemistry determines hydrophobic performance, tracking resistance, and regulatory compliance trajectories.
- Polymer:Thermoplastic and thermoset formulations including EPDM and cycloaliphatic epoxy compete on cost in distribution applications. Indian compounders localize polymer compounding under CEA technical standards that mandate domestic testing for 66 kV-plus ratings.
- Glass-Fiber Reinforced Plastic:Pultruded E-glass cores provide tensile strength exceeding 1,000 MPa for mechanical load-bearing functions. German manufacturers anchor European FRP supply through captive roving conversion capacity.
- Silicone Rubber:Room-temperature vulcanized and high-temperature vulcanized grades dominate transmission-class specifications for pollution resistance.
- Porcelain:Alumina-based ceramic retains share in seismic zones and legacy tower retrofits where conservative operators prioritize decades of field performance data.
Silicone Rubber holds installed capacity. Glass-Fiber Reinforced Plastic is rotating up the share rankings.
Installation Type:
Environmental exposure and accessibility constraints shape housing geometry and hardware corrosion protection.
- Onshore:Overhead transmission across terrestrial corridors represents the dominant deployment context. Chinese UHV projects specify onshore composite insulators with extended creep distances for desert pollution zones.
- Offshore:Substation platforms and coastal wind farms demand salt-fog-resistant shed designs with enhanced hydrophobicity retention. North Sea operators require IEC 61109 type-testing for marine atmospheric conditions.
- Overhead:Conventional tower-mounted configurations span the voltage spectrum from distribution to ultra-high-voltage.
- Underground:Cable termination applications in urban substations and tunnel installations.
Onshore holds installed capacity. Offshore is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pultrusion-grade E-glass capacity clusters in Chinese and German manufacturing basins, exposing compounders to input volatility during energy price spikes. State Grid Corporation's ultra-high-voltage transmission build-out compresses procurement cycles for polymer-based alternatives ahead of traditional porcelain phase-out timelines.
China
State Grid Corporation continues expanding ultra-high-voltage transmission infrastructure across western provinces. MEE directives on grid decarbonization prioritize lightweight composite structures that reduce steel tower mass and embodied carbon in new UHV lines. Xinjiang and Gansu corridors host concentrated manufacturing clusters for domestic polymer compounding and pultrusion capacity expansion.
Germany
Transmission system operators specify REACH-compliant silicone formulations under ECHA mandates for halogen-free certification. ECHA's 2025 sunset dates for decaBDE and HBCDD force silicone formulators toward magnesium hydroxide and phosphorus-based alternatives. Bavarian and North Rhine-Westphalian manufacturing basins anchor European FRP supply through captive roving conversion capacity.
India
Rural electrification programs and 66 kV-plus corridor build-outs drive strain insulator demand in Maharashtra and Gujarat. CEA technical standards mandate localization for insulator testing, creating captive demand for domestic polymer compounding joint ventures. Tamil Nadu and Karnataka host emerging pultrusion facilities serving southern grid expansion.
United States
North American utilities now require ANSI C29.11 composite insulator qualification for 115 kV-plus corridor tenders. Southern California Edison and Texas grid operators issue separate procurement lots for insulator supply and live-line installation. Midwest manufacturing clusters concentrate dead-end and strain insulator production for utility framework agreements.
Japan
Conservative transmission operators in earthquake-prone corridors retain ceramic-composite hybrids for seismic load assurance. METI resilience mandates favor hybrid designs that bridge traditional porcelain reliability with polymer weight advantages. Chubu and Kansai industrial zones maintain specialized testing facilities for seismic qualification protocols.
Composite Line Post Insulators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material formulation and pultrusion. The vendor base organizes around three archetypes: integrated energy technology conglomerates with captive silicone labs, specialized electrical hardware manufacturers with ANSI and IEC certification depth, and regional compounders serving localized grid standards. Consolidation pressures concentrate among mid-tier pultrusion operators facing 18-24 month IEC 61109 qualification timelines. Dominant competitive moves include backward integration into E-glass roving supply and strategic partnerships for embedded fiber-optic sensing capabilities.
Among European-based platform integrators, Siemens Energy and ABB exemplify archetypes with captive formulation infrastructure for high-voltage specifications. Hubbell Power Systems anchors North American utility procurement through ANSI-certified portfolio depth. These three occupy positions spanning integrated energy systems, specialized electrical hardware, and regional certification leadership.
| Leading Market Players |
|---|
| Siemens Energy |
| Hitachi Energy |
| Hubbell Power Systems |
| PFISTERER |
| TE Connectivity |
| ABB |
| NGK Insulators |
| Seves Group |
| Lapp Insulators |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor transmits freight cost volatility directly into landed silicone rubber pricing, amplifying spreads between German compounders and Chinese integrated manufacturers while compressing margins for mid-tier pultrusion operators lacking captive E-glass supply.
Pricing Analysis
ANSI C29.11 dictates the pricing tier structure across North American procurement, separating IEC-certified premium specifications from economy-grade distribution-class units. Price differentiation rests on certification depth and volume scale, with utility framework agreements commanding standard-tier positioning while spot purchases for industrial microgrids absorb premium markups. Cost compression in the economy tier is intensifying as Indian compounders localize under CEA mandates. Data center developers exhibit highest price sensitivity, whereas State Grid Corporation demonstrates lowest sensitivity due to total-cost-of-ownership procurement models.
Supply Chain Analysis
Extended payment terms from German transmission system operators now stretch to 180 days, forcing pultrusion specialists into supply-chain finance facilities anchored by E-glass roving inventories. Manufacturing gravity centers on China, Germany, and India, with raw material dependencies spanning pultrusion-grade E-glass, high-purity silicone rubber, and nano-alumina fillers. Single-source vulnerability concentrates in Chinese E-glass capacity during energy price spikes. Distribution runs through utility procurement offices unbundling hardware from installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The composite line post insulators market represents high-growth infrastructure disruption as polymer formulations displace century-old porcelain across ultra-high-voltage corridors, with MEE decarbonization directives and ANSI certification mandates creating irreversible procurement inflections.
For Market Incumbents: Build formulation moats through captive silicone rubber laboratories that lock in 220 kV-plus specification control. Siemens Energy and Hubbell Power Systems anchor positions through ANSI and IEC certification depth, but emerging Indian compounders threaten margin pools via CEA-mandated localization. Incumbents should deepen backward integration into E-glass roving supply and accelerate embedded fiber-optic sensing R&D to bundle predictive maintenance contracts that resist hardware commoditization. For New Entrants and Emerging Players: Establish a beachhead in India's 66 kV-plus rural electrification segment where CEA technical standards create captive demand for domestic polymer compounding joint ventures. Tamil Nadu and Karnataka pultrusion clusters offer manufacturing access with lower qualification barriers than European REACH compliance. Target data center microgrid isolation hardware through direct engagement with hyperscaler procurement teams seeking medium-voltage pin insulator variants for campus self-generation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with halogen-free silicone formulation capabilities ahead of ECHA's decaBDE sunset enforcement. Long-term viability hinges on 5-10 year grid decarbonization trajectories across Chinese and European transmission build-outs. Acquisition targets should display captive testing laboratory infrastructure and GB/T or ANSI certification depth. The signal to watch is State Grid Corporation procurement lot unbundling velocity, which accelerates margin capture by specialized manufacturers over integrated EPC contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into E-Glass Supply | Pultrusion specialists secure roving conversion capacity against Chinese energy price volatility. |
| Halogen-Free Silicone Formulation Certification | German compounders meet ECHA mandates ahead of decaBDE sunset dates. |
| Embedded Fiber-Optic Sensing Development | FRP core manufacturers bundle predictive maintenance analytics with hardware supply. |
| CEA-Mandated Localization Joint Venture | Foreign compounders capture Indian 66 kV-plus procurement through domestic testing facilities. |
| Utility Procurement Unbundling Response | Specialized manufacturers displace turnkey contractors via ANSI-certified portfolio depth. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IEC 61109 type-test documentation, ECHA regulatory filings, and utility procurement databases. Interviews engaged transmission planning officers at State Grid Corporation and Southern California Edison, polymer compounding technical directors in Bavaria and Tamil Nadu, and EPC contractor procurement leads. Secondary validation drew from FERC interconnection queues, CEA technical standards publications, and customs data tracking E-glass roving trade flows. Bottom-up unit economics triangulated against top-down grid investment forecasts.
Forecast inputs incorporate voltage-class segmentation, material chemistry trajectories, and installation-type deployment patterns across the projection horizon. The analytical framework models silicone rubber versus polymer versus hybrid ceramic-composite substitution curves, pultrusion capacity expansion timelines, and regulatory compliance phase-ins. CAGRs derive from utility capital expenditure trajectories, industrial microgrid build-out rates, and offshore wind farm interconnection backlogs. Grid resilience mandates and material substitution timelines inform scenario-weighted outputs.
Sensitivities concentrate around E-glass energy cost spikes, REACH additive restriction enforcement timing, and UHV corridor construction pace in western China. Forecasts reflect documented assumptions regarding polymer formulation maturation and certification protocol durations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
Unitary Heaters Market