
 United Kingdom Electric Vehicle Charging Equipment Market | 2026-2036
United Kingdom Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Electric Vehicle Charging Equipment Market Insights
Market Overview
UK charge point manufacturing is consolidating around a handful of scale producers with established grid integration capabilities. BP Pulse leverages its forecourt real estate to anchor rapid charging corridors along major motorways. Pod Point sustains residential market penetration through partnerships with housebuilders and property developers. InstaVolt competes on speed of deployment, specializing in DC fast charging sites with high-utilization positioning.
Electric vehicle charging equipment comprises hardware systems that convert grid electricity into formats suitable for battery electric vehicles, typically spanning power outputs from 3.7 kW AC domestic units to 350 kW DC rapid chargers with liquid-cooled cable assemblies. These systems incorporate power electronics, communication protocols, and safety interlocks to manage energy transfer, billing authentication, and grid load balancing. DC fast chargers command premium positioning due to higher component costs and complex thermal management requirements, while home chargers represent the volume base driven by residential electrification mandates. Smart charging connectivity segments are gaining structural importance as utilities implement time-of-use tariffs and vehicle-to-grid pilot programs.
The Office for Product Safety and Standards enforces electrical safety compliance for charge point installations, while Ofgem regulates grid connection standards and connection pricing for high-capacity sites. The UK government's Electric Vehicle Infrastructure Strategy shapes local authority procurement frameworks and mandates for new-build residential provision. Stakeholders must monitor how forthcoming smart charging regulations reshape hardware specification requirements and interoperability obligations.
Market Dynamics
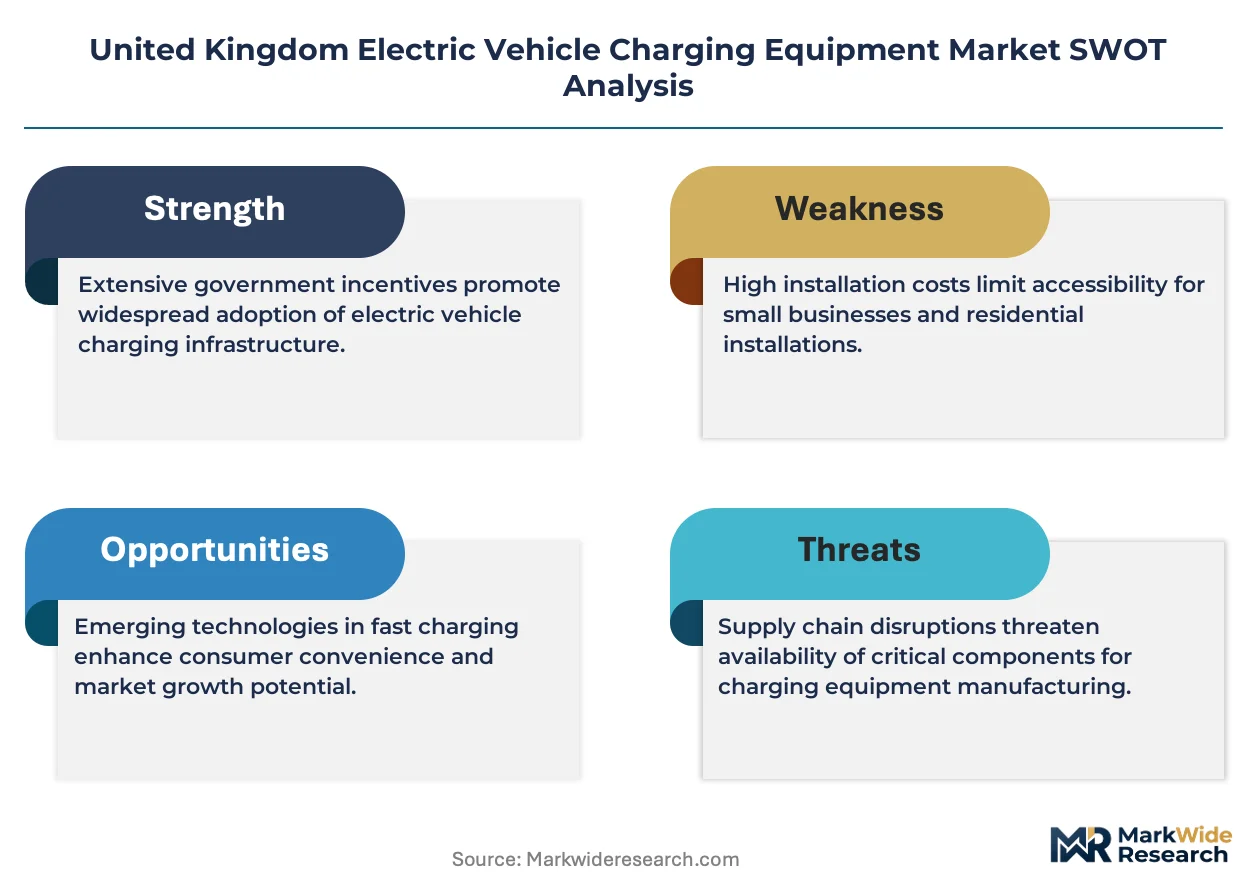
The UK Electric Vehicle Charging Equipment Market is experiencing structural pressure from grid capacity constraints as distribution network operators struggle to process connection applications for high-power sites within commercially viable timeframes. This bottleneck is forcing hardware manufacturers to prioritize smart load management capabilities and modular power scaling architectures that defer peak demand spikes.
Growth Catalysts
- Zero Emission Vehicle Mandate:The UK government's phased ban on new internal combustion engine sales creates legally binding demand floors for fleet electrification infrastructure across logistics and delivery operators.
- Building Regulations Part S:Mandatory charge point provision in new residential developments ensures baseline hardware deployment volumes regardless of near-term EV adoption rates.
- Logistics fleet electrification:Parcel carriers and grocery delivery networks are committing to depot-based charging hubs with multi-megawatt power requirements, driving orders for high-capacity DC hardware.
Market Restraints
- Copper and silicon carbide supply concentration:Power electronics manufacturers face input cost volatility as semiconductor foundry capacity for automotive-grade components remains concentrated in East Asian supply chains.
- Grid connection queue delays:Distribution network operators in Greater London and the West Midlands report 18-24 month lead times for substation upgrades, freezing site development timelines.
- Interoperability certification friction:The UK's smart charging regulations impose evolving protocol requirements that extend product validation cycles before market entry.
Strategic Opportunities
- Workplace charging underpenetration:Commercial real estate in secondary UK cities retains significant installation gaps as employers lag residential and public infrastructure deployment.
- Vehicle-to-grid convergence:Bidirectional charging hardware paired with domestic battery storage creates integrated energy asset propositions for utilities seeking distributed flexibility resources.
- On-street residential provision:Local authority procurement frameworks for lamp-post and bollard charging address the 40% of UK households lacking off-street parking.
Industry Challenges
- Electrical installation skill shortages:Qualified charge point installer capacity constrains deployment velocity as training pipeline output fails to match permit application volumes.
- Legacy estate electrical capacity:Commercial depot sites require costly distribution board upgrades to support megawatt-scale charging, compressing project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Electric Vehicle Charging Equipment Market |
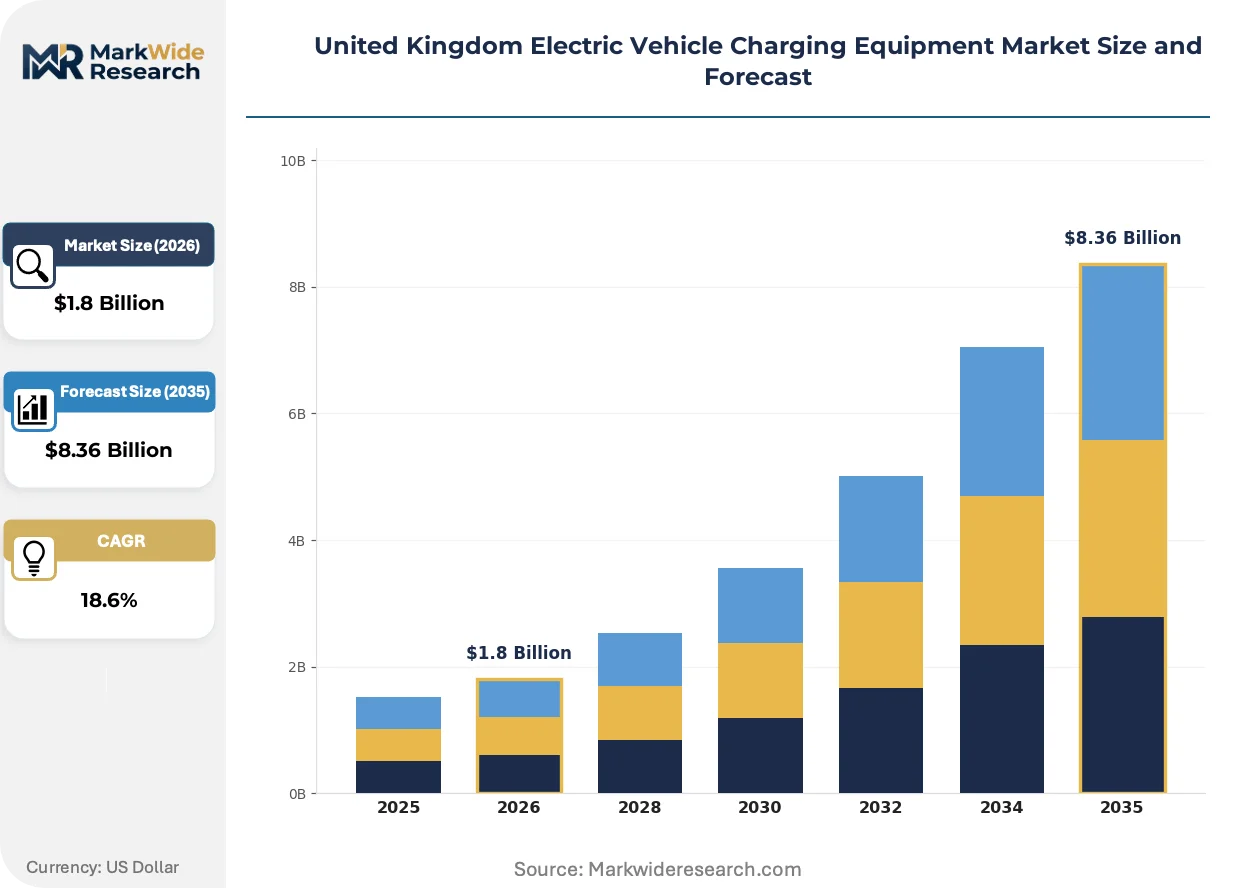
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Home Chargers, Public Chargers End User: Residential Users, Commercial Fleets, Public Transportation, Charging Network Providers Installation Type: Wall-mounted, Free-standing, Embedded, Portable Connectivity: Wired, Wireless, Smart Charging, Conventional |
| Companies Covered | Char.gy, CityEV, Alfen, EVBox, Pod Point, BP Pulse, Ubitricity, ABB, InstaVolt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Electric Vehicle Charging Equipment Market Trends and Innovations
Hardware architectures in the UK Electric Vehicle Charging Equipment Market are pivoting toward software-defined power management as grid constraints and time-of-use tariffs reshape operational requirements. This shift elevates connectivity and control layer investments relative to pure power electronics.
Liquid-cooled cable assemblies are integrating thermal management directly into high-power charging hardware, enabling sustained 350 kW output without conductor degradation. Fleet operators with depot charging requirements are adopting these systems to minimize vehicle dwell time during shift changes. The technology is integrating predictive maintenance algorithms that monitor coolant flow rates and temperature differentials to preempt cable replacement cycles.
Ofgem's connection pricing reforms are reshaping commercial viability assessments for rapid charging sites by introducing locational signals that penalize grid-stressed areas. Developers are responding with battery-buffered charging stations that limit peak import capacity. The regulation most affects motorway service area operators who must now factor constraint management costs into site selection models.
Fleet procurement patterns are consolidating around multi-year service contracts that bundle hardware, installation, energy supply, and maintenance into single operational expenditures. This displaces traditional capital purchase models among logistics operators seeking balance sheet efficiency. The shift is most visible in grocery and parcel delivery verticals where vehicle utilization rates demand guaranteed uptime commitments from infrastructure providers.
United Kingdom Electric Vehicle Charging Equipment Market Segmentation
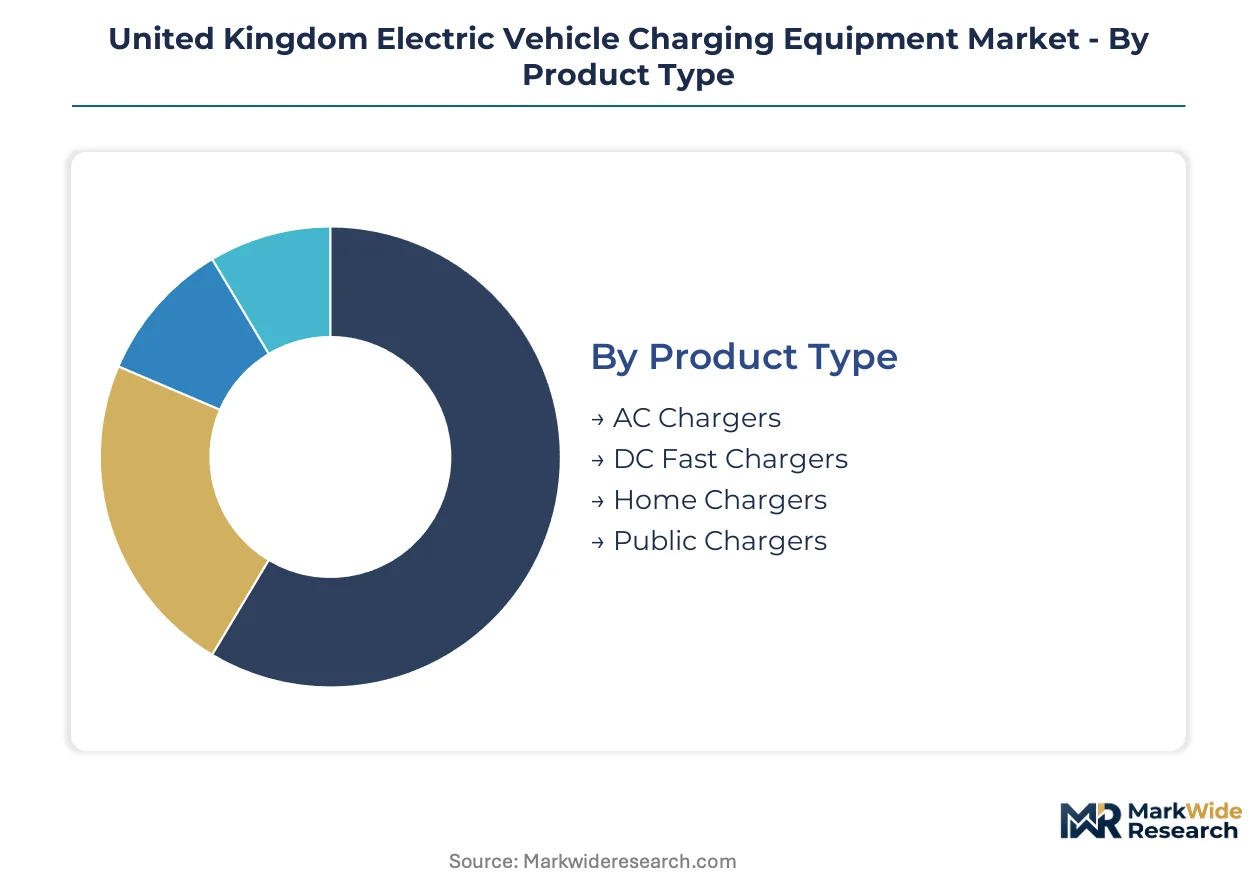
Segmentation in the UK Electric Vehicle Charging Equipment Market reveals how hardware specifications, installation constraints, and user requirements fragment procurement patterns. Distribution network capacity and regulatory mandates reshape which segments capture deployment volume across residential, commercial, and public contexts.
Product Type:
Supply concentration around high-power electronics manufacturing favors scale producers with established semiconductor sourcing relationships for DC fast charging components.
- AC Chargers:These units convert grid alternating current to vehicle-compatible direct current at power levels typically spanning 3.7 kW to 22 kW. Residential installations in Greater London and the West Midlands corridor concentrate demand as Building Regulations Part S mandates drive new-build provision. Grid connection simplicity and lower installation costs sustain volume leadership despite slower charge speeds.
- DC Fast Chargers:Direct current systems bypass onboard vehicle conversion, delivering 50 kW to 350 kW through liquid-cooled cable assemblies. Motorway service areas and fleet depots anchor demand as logistics operators prioritize minimized dwell time. Silicon carbide power modules and complex thermal management elevate unit costs and consolidate manufacturing around specialized producers.
- Home Chargers:Single-phase or three-phase units designed for private residential parking spaces. Pod Point partnerships with housebuilders dominate channel access.
- Public Chargers:Multi-user infrastructure deployed in retail parks, street locations, and workplace sites. Local authority procurement frameworks shape competitive access.
Today's leader: AC Chargers. Tomorrow's challenger: DC Fast Chargers.
End User:
Application-specific power requirements and utilization patterns determine hardware specification priorities across user categories.
- Residential Users:Overnight charging needs favor lower-power AC units with smart scheduling capabilities to exploit time-of-use tariffs. The 40% of UK households lacking off-street parking creates persistent gaps addressed through lamp-post and bollard solutions.
- Commercial Fleets:Parcel carriers and grocery delivery networks anchor multi-megawatt depot installations with guaranteed uptime requirements. Battery-buffered systems and predictive maintenance contracts displace capital purchase models as operators seek operational expenditure alignment.
- Public Transportation:Bus and coach electrification drives high-power opportunity charging at termini and en-route locations. Municipal procurement timelines extend validation cycles.
- Charging Network Providers:BP Pulse and InstaVolt compete on site acquisition speed and grid connection execution. Ofgem's locational pricing reforms reshape site viability assessments.
Commercial Fleets are expanding most quickly; Residential Users retain volume dominance through regulatory floor effects.
Installation Type:
Physical mounting constraints and electrical capacity limitations at host sites determine hardware form factor selection.
- Wall-mounted:Space-efficient bracket systems for residential garages and commercial building facades. Standard electrical installation training pipelines support deployment velocity.
- Free-standing:Pedestal or canopy-mounted units for car parks and forecourts without adjacent wall structures. Higher foundation and civil works costs compress project returns.
- Embedded:Underground or flush-mounted systems for aesthetic-sensitive locations and pedestrian zones. Complex maintenance access elevates lifecycle costs.
- Portable:Mobile units for temporary deployment and emergency charging services. Limited power output constrains commercial viability.
Wall-mounted units dominate residential penetration; Free-standing systems gain share in commercial estate retrofit.
Connectivity:
Margin structures concentrate in control layer investments as grid constraints elevate software-defined power management importance.
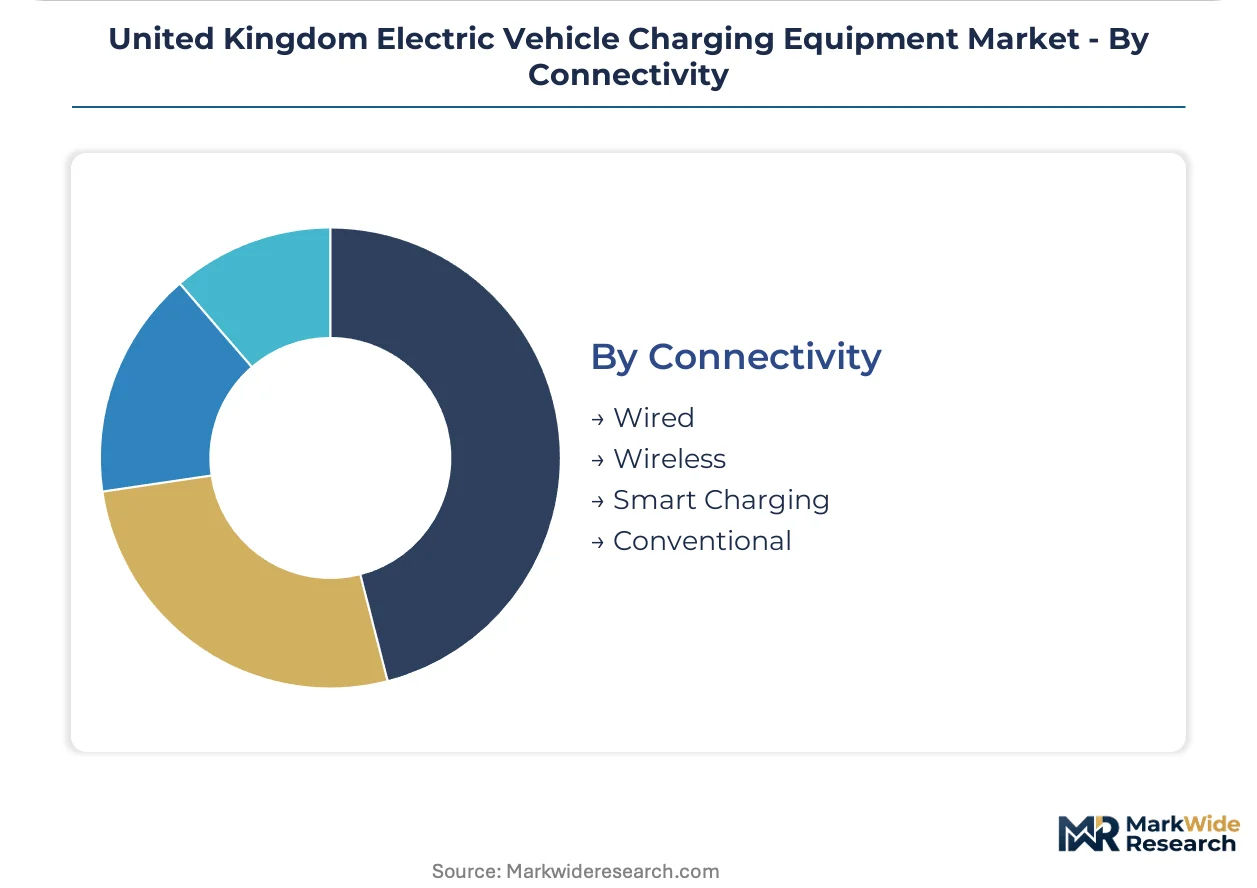
- Smart Charging:Bidirectional communication enables demand response, time-of-use optimization, and vehicle-to-grid integration. Utilities pilot distributed flexibility resource aggregation through domestic battery and EV asset combinations.
- Wired:Physical Ethernet or powerline connections provide reliable data transmission for billing authentication and remote monitoring. Installation labor adds marginal cost.
- Wireless:Inductive or resonant coupling systems eliminate cable handling but suffer efficiency losses and higher capital costs. Early deployment concentrates in premium fleet demonstrations.
- Conventional:Basic plug-and-charge functionality without network connectivity. Regulatory phase-out timelines in the UK mandate smart capability for new installations.
Smart Charging holds steepest expansion trajectory; Conventional connectivity faces regulatory obsolescence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in UK electric vehicle charging equipment concentrate manufacturing investment where grid connection standards and building code mandates create compliance cost differentials. Scotland and Wales leverage streamlined permitting to attract hardware assembly facilities, while England's density drives installation volume. Northern Ireland's cross-border energy protocols shape unique procurement frameworks.
Greater London
Transport for London's zero-emission zone expansion and Ultra Low Emission Zone penalties compel fleet electrification across delivery and logistics operators. The Greater London Authority mandates rapid charging provision in all new commercial developments above threshold floor areas. Docklands and Park Royal industrial estates host the densest depot charging clusters as last-mile operators consolidate electrification hubs.
West Midlands
Birmingham's Clean Air Zone enforcement and Coventry's battery manufacturing investments create synchronized demand for high-power charging infrastructure. Ofgem's regional network pricing reforms disadvantage this grid-constrained corridor, extending connection timelines for rapid charging sites. Solihull and Warwickshire logistics parks anchor multi-megawatt fleet installations serving automotive supply chains.
Scotland
Transport Scotland's public charging network targets and zero-emission vehicle grant schemes accelerate municipal procurement cycles. The Scottish Government's building standards require enhanced electrical capacity in new residential developments beyond English minimums. Glasgow and Edinburgh city centres concentrate on-street charging deployment addressing tenement housing without off-street parking.
North West England
Greater Manchester's Clean Air Plan implementation drives commercial fleet transition timelines with mandated electrification milestones. BEIS-funded charging infrastructure pilots target underserved motorway corridors connecting Liverpool and Manchester. Cheshire and Lancashire distribution centres anchor grocery and parcel network depot charging at scale.
Wales
The Welsh Government's Llwybr Newydd transport strategy embeds charging accessibility targets into local development plans. Building regulations in Wales mandate higher electrical capacity provisions than English equivalents, reducing retrofit costs. Cardiff and Newport corridors concentrate rapid charging investment along the M4 motorway spine serving cross-border freight flows.
United Kingdom Electric Vehicle Charging Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined power management and vehicle-to-grid integration capabilities. UK charge point manufacturing consolidates around scale producers with grid integration capabilities and semiconductor sourcing relationships. Three archetypes dominate: forecourt-anchored rapid charging networks, residential-focused installation specialists, and fleet depot solution providers. Competitive moves concentrate on strategic partnerships with property developers and multi-year service contract structures displacing capital purchase models.
Within the forecourt-anchored tier, BP Pulse leverages its motorway real estate portfolio for rapid charging corridor positioning. Pod Point exemplifies the residential-specialist archetype through housebuilder partnership channels. InstaVolt occupies the high-utilisation rapid deployment segment with DC fast charging site concentration. These three anchors represent distinct go-to-market configurations without overlapping core territory.
| Leading Market Players |
|---|
| Char.gy |
| CityEV |
| Alfen |
| EVBox |
| Pod Point |
| BP Pulse |
| Ubitricity |
| ABB |
| InstaVolt |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer costs cascade through DC fast charger manufacturing, concentrating margin pressure on UK assemblers who lack captive semiconductor sourcing and must absorb foundry pricing volatility through tiered hardware offerings.
Pricing Analysis
Distributor margins compress as fleet procurement consolidates around multi-year service contracts bundling hardware, installation, and maintenance. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled 350 kW systems from air-cooled 150 kW units and basic AC residential chargers. Price differentiation hinges on smart charging certification grade and thermal management sophistication. Pricing pressure stems from copper and power electronics input cost volatility. Commercial fleets exhibit lowest price sensitivity due to uptime guarantees; residential installers face highest sensitivity as housebuilders optimize construction cost budgets.
Supply Chain Analysis
Dual-sourcing requirements from UK charge point assemblers mandate qualified semiconductor suppliers across Taiwan, Germany, and the United States for automotive-grade silicon carbide modules. Power electronics manufacturing draws from East Asian foundry capacity for MOSFETs and IGBTs, while cable assemblies source copper from Chilean and Zambian mining operations. Single-source vulnerability concentrates in liquid-cooled cable thermal management subassemblies where German and Japanese suppliers dominate. Distribution runs through electrical wholesalers and direct OEM relationships to fleet operators and network developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Electric Vehicle Charging Equipment Market functions as a regulatory compounder where Building Regulations Part S and the Zero Emission Vehicle mandate create legally binding demand floors regardless of near-term EV adoption velocity.
For Market Incumbents: Anchor market position through backward integration into power electronics assembly and captive semiconductor sourcing relationships. Defend against modular entrant architectures by accelerating smart charging certification ahead of Ofgem's evolving protocol requirements. Prioritize grid integration capabilities as distribution network operators extend connection timelines. For New Entrants and Emerging Players: Begin with workplace charging installations in secondary UK cities where commercial real estate penetration lags residential and public infrastructure deployment. Target lamp-post and bollard charging for the 40% of UK households lacking off-street parking. Pursue local authority procurement frameworks as the primary channel access mechanism. For Investors and Strategic Acquirers: Consolidation pressure builds where electrical installation skill shortages constrain deployment velocity and qualified installer networks become scarce strategic assets. Long-term viability favors vertically integrated players with grid connection execution capabilities and multi-year service contract books. Monitor Ofgem connection pricing reform implementation as the inflection signal for site viability assessments and capital allocation efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Charging Certification Investment | Ofgem protocol compliance accelerates product validation cycles and market entry timelines. |
| Battery-Buffered Station Deployment | Locational pricing penalties in grid-stressed corridors reshape motorway service area economics. |
| Installer Network Acquisition | Qualified electrical capacity scarcity constrains deployment velocity and captures permit flow. |
| Vehicle-to-Grid Hardware Development | Bidirectional charging integration creates utility-facing distributed flexibility resource propositions. |
| Housebuilder Partnership Expansion | Building Regulations Part S mandates secure baseline residential volume regardless of adoption rates. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each region combined through structured interviews with charge point manufacturers, distribution network operators, fleet procurement directors, and electrical installation contractors. Secondary validation draws from Ofgem regulatory filings, BEIS infrastructure strategy documents, Transport for London zero-emission zone expansion notices, and local authority procurement framework disclosures. Bottom-up installation volume estimates triangulate against top-down market sizing from hardware shipment data and grid connection application records.
Rate-of-change decomposition separates volume growth from unit value evolution across the analysis window. Segmentation dimensions modeled include product type tier, end-user category, installation form factor, and connectivity protocol standard. CAGR derivation incorporates fleet electrification commitment timelines, residential construction permit flows, and public charging network expansion targets. Forecast inputs include substation upgrade capacity constraints from distribution network operators and smart charging regulation implementation schedules.
Several conditions sit outside the modeled scope, including cross-border energy protocol changes affecting Northern Ireland, unforeseen raw material trade restrictions, and accelerated vehicle-to-grid technology disruption. Forecasts reflect assumptions about regulatory timeline adherence and grid investment pacing. Deviation in Ofgem connection pricing reform implementation or Building Regulations Part S enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market