
 Europe Brushless DC Motors Market | 2026-2036
Europe Brushless DC Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Brushless DC Motors Market Analytics
Market Context
German precision motor manufacturing is broadening its output footprint across Nordic and Benelux automation markets. Siemens AG leverages its industrial automation platform to anchor large-scale brushless DC deployments in automotive assembly lines. Maxon specializes in compact high-torque designs that dominate medical robotics and aerospace actuator segments. Bosch Group extends its powertrain electronics expertise into integrated motor-drive systems for electric vehicle thermal management.
Technical Definition and Structural Segments
Brushless DC motors employ permanent magnet rotors with electronically commutated stator windings, eliminating mechanical brushes to achieve efficiencies exceeding 90% and operational lifespans above 20,000 hours in continuous duty cycles. These motors convert electrical energy into precise mechanical motion for applications requiring variable speed control, high starting torque, and minimal electromagnetic interference. The low-power product category leads unit volume across consumer electronics and portable medical devices, while the sensorless technology segment captures the fastest expansion as algorithmic rotor-position estimation reduces hardware cost and failure points in cost-sensitive automotive HVAC and pump applications. Integrated motor-drive combinations concentrate margin pools where semiconductor and mechanical engineering competencies overlap, particularly in robotics and factory automation end uses.
Regulatory Framework and Outlook
The EU Ecodesign Directive and F-Gas Regulation mandate minimum efficiency thresholds for motors deployed in refrigeration, ventilation, and industrial process equipment across member states. CE marking requirements under the Machinery Directive enforce electromagnetic compatibility and safety standards that shape product development priorities for OEM suppliers. REACH compliance constrains magnet material sourcing, particularly rare earth elements in permanent magnet formulations. Stakeholders must monitor the EU AI Act's emerging classification rules for autonomous motor control systems and decide whether to front-load adaptive control algorithm certification or defer investment pending implementing guidance.
Market Dynamics
The EU Green Deal is compressing motor efficiency timelines across European industrial supply chains, forcing OEMs to abandon induction motor architectures in favor of electronically commutated designs ahead of regulatory deadlines.
Growth Catalysts
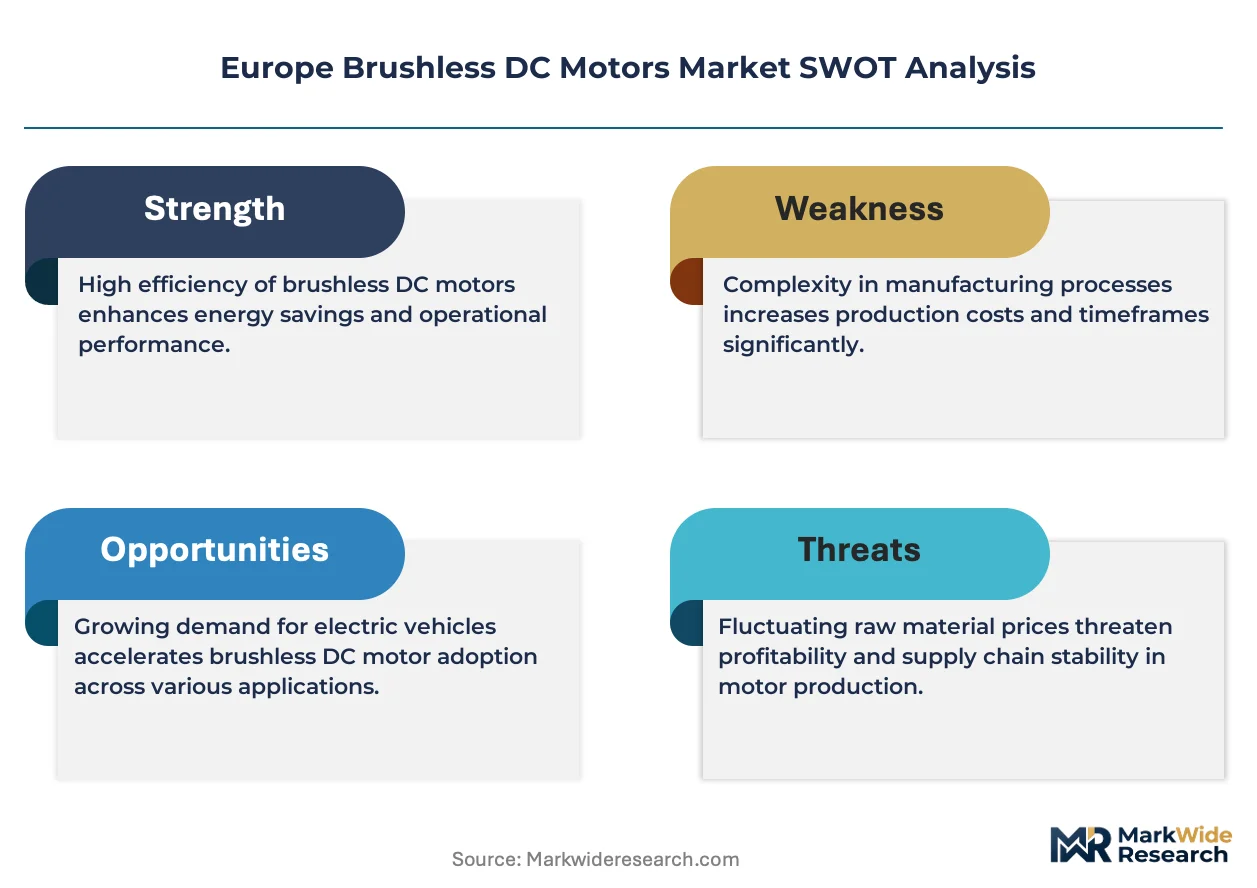
- F-Gas Regulation phase-down:Refrigeration and HVAC OEMs across Germany, France, and Italy are retrofitting compressor systems with high-efficiency brushless DC motors to meet 2027 refrigerant containment mandates.
- Sensorless control algorithms:Elimination of Hall-effect sensors reduces BOM cost and failure modes in automotive thermal management pumps, accelerating adoption among Tier-1 suppliers serving German EV platforms.
- Benelux automation density:Warehouse robotics deployments in the Netherlands and Belgium are consuming compact high-torque motors for articulated joint actuation, creating concentrated demand clusters.
Market Restraints
- Rare earth magnet dependency:Neodymium and dysprosium supply routes through Chinese processing facilities expose European motor manufacturers to price volatility and export restriction risks.
- REACH compliance burden:ECHA substance restrictions on magnet coatings and winding insulation materials extend qualification cycles by 8-14 months for new product introductions.
- Induction motor installed base:Legacy motor populations in Eastern European industrial facilities create replacement inertia, delaying upgrade cycles despite efficiency incentives.
Strategic Opportunities
- Polish manufacturing expansion:Lower labor and facility costs in Silesian industrial zones attract motor assembly operations serving Central European automation OEMs.
- EU AI Act certification:Early movers in adaptive motor control algorithms can establish de facto standards for autonomous drive systems in collaborative robotics.
- Integrated motor-drive architectures:Convergence of GaN power semiconductors with compact motor housings enables new form factors for surgical tool and drone propulsion applications.
Industry Challenges
- Embedded software talent scarcity:Field-oriented control firmware development requires specialized expertise in real-time motor control that competes with automotive and aerospace hiring pools.
- CE marking timeline compression:Machinery Directive electromagnetic compatibility testing creates bottlenecks as notified body capacity fails to match product launch velocities.
- Legacy PLC integration friction:Retrofitting brushless DC systems into decades-old Siemens S7 and Rockwell Automation architectures demands custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Brushless DC Motors Market |
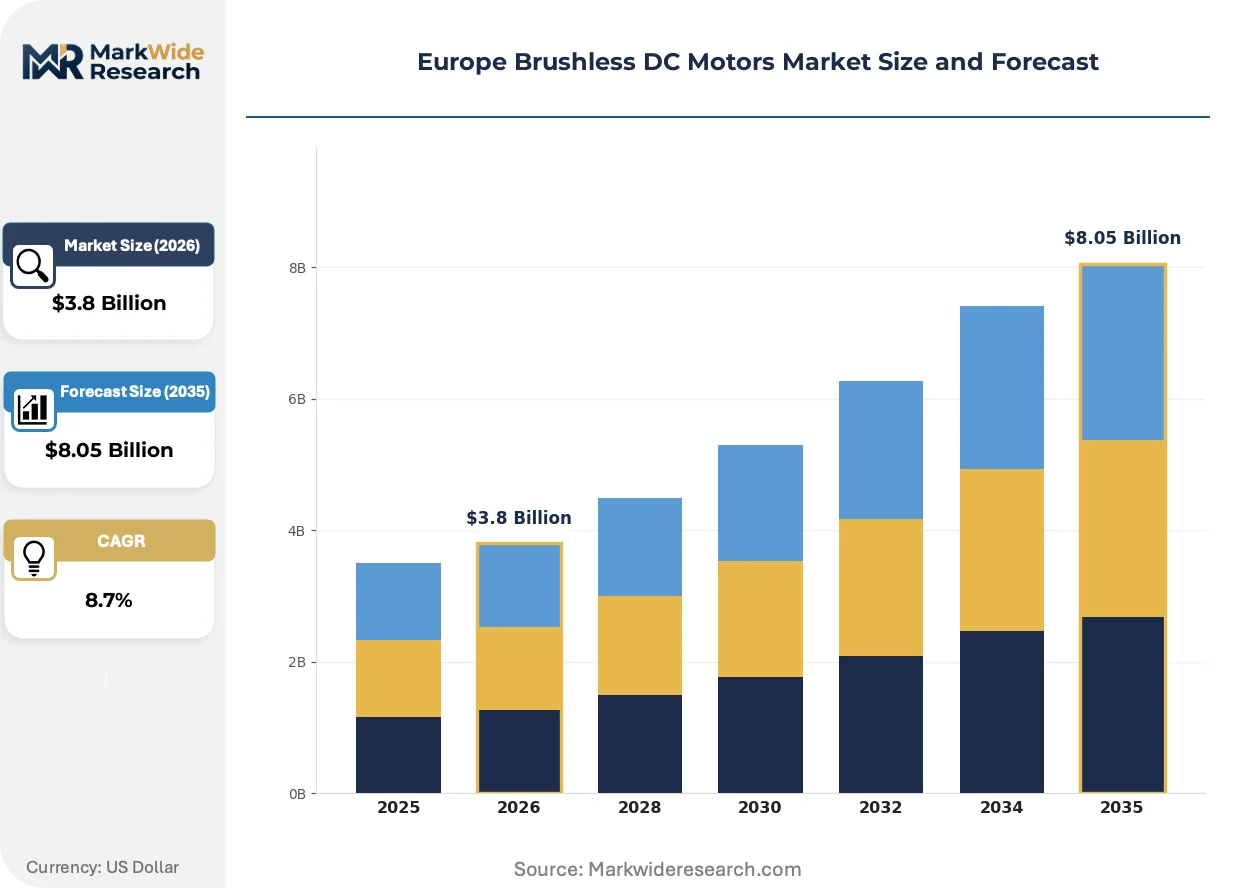
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power, Low-Power, Integrated, Modular Application: Automotive, Robotics, HVAC, Consumer Electronics End User: Manufacturers, OEMs, Service Providers, Retailers Technology: Sensor-based, Sensorless, Direct Drive, Field-Oriented |
| Companies Covered | Nanotec Electronic GmbH & Co. KG, Delta Line, Faulhaber, Siemens AG, Orbex Group, Maxon, Bühler Motor GmbH, Bosch Group, Portescap, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Brushless DC Motors Market Evolving Landscape
Algorithmic rotor position estimation and wide-bandgap power electronics are converging to eliminate mechanical sensors and thermal losses that previously constrained motor system miniaturization.
Sensorless field-oriented control is overtaking Hall-sensor commutation in cost-sensitive automotive auxiliary applications. German powertrain suppliers are deploying these architectures in electric water pumps and oil circulation systems. The elimination of position sensors compresses unit costs while improving mean-time-between-failures metrics in thermal cycling environments.
REACH substance restrictions are reshaping magnet supply chain configurations across European motor manufacturing. ECHA candidate list updates constrain hexavalent chromium coatings and certain epoxy formulations used in rotor assemblies. Medical device and aerospace motor segments are accelerating qualification of alternative coating chemistries to maintain CE marking eligibility.
Buyer concentration among German automotive OEMs is compressing supplier negotiation cycles and unbundling traditional component-plus-service contracts. Tier-2 motor manufacturers now face direct specification authority from vehicle platform teams rather than through historical distributor relationships. This pattern is most pronounced in Stuttgart and Munich manufacturing corridors where EV thermal management sourcing decisions centralize.
Europe Brushless DC Motors Market Segmentation
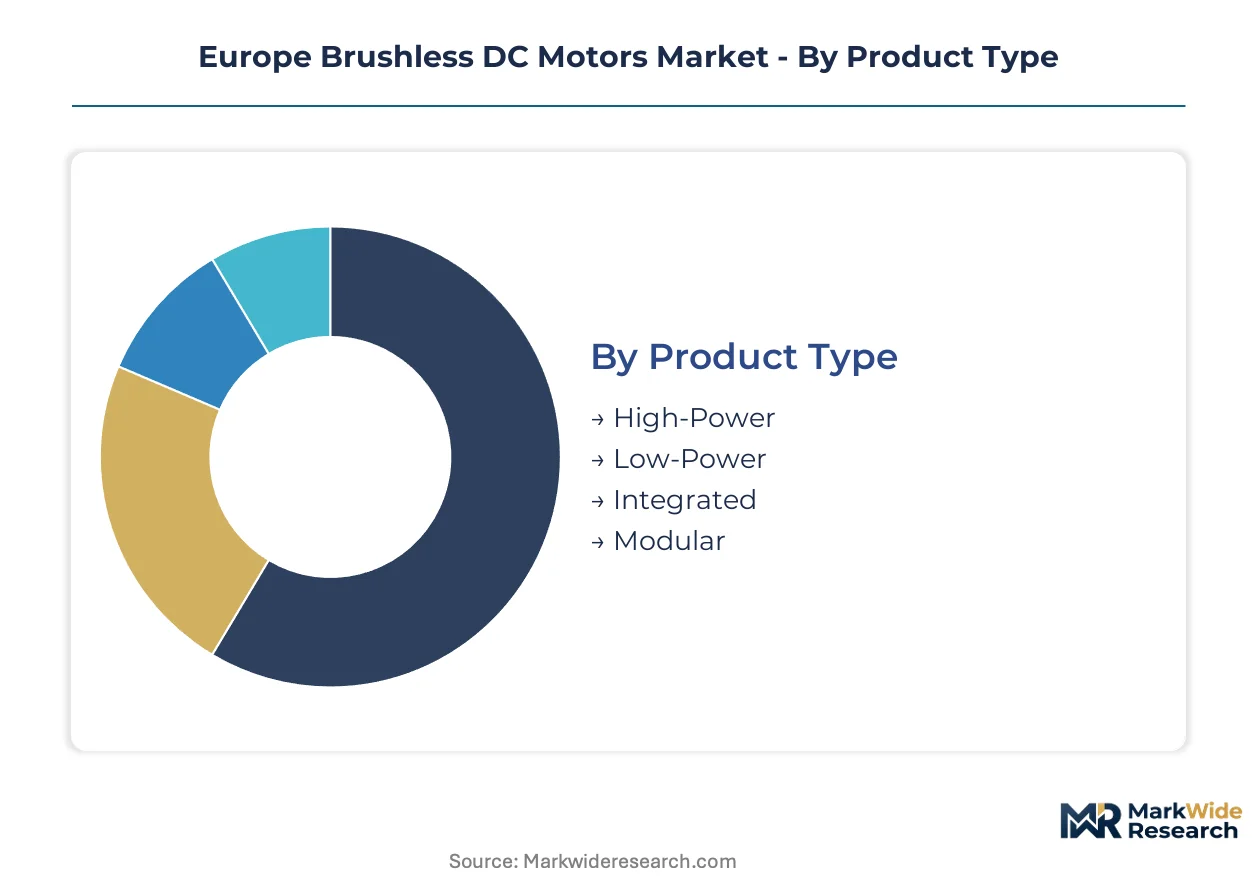
Brushless DC motor architectures vary dramatically in magnet material intensity, semiconductor integration, and control firmware complexity. Capital allocation decisions across these dimensions determine competitive positioning in European industrial supply chains.
Product Type:
High-power designs demand the steepest upfront investment in rare earth magnet procurement and thermal management infrastructure.
- High-Power:Permanent magnet rotors rated above 1kW require substantial neodymium-dysprosium procurement commitments and liquid cooling system integration. German automotive powertrain suppliers concentrate demand here for electric axle drives, though magnet price volatility from Chinese processing facilities constrains margin stability.
- Low-Power:Compact ferrite-magnet designs below 100W dominate unit volume across portable medical devices and consumer electronics. Nordic automation clusters in Denmark and Sweden absorb significant shipments for laboratory instrumentation and precision positioning stages.
- Integrated:Motor-drive combinations embed GaN power semiconductors and control algorithms within sealed housings.
- Modular:Separable rotor-stator assemblies enable field serviceability and customization for specialized machinery.
Most installed capacity flows through Low-Power. Expansion is steepest in Integrated.
Application:
Automotive qualification cycles impose the longest development timelines and highest certification costs among end-use categories.
- Automotive:Thermal management pumps and electric power steering systems require ISO 26262 functional safety compliance and AEC-Q200 component qualification. Stuttgart and Munich manufacturing corridors centralize specification authority for German EV platforms, compressing supplier negotiation leverage.
- Robotics:Articulated joint actuation demands high torque density with minimal cogging torque for smooth trajectory tracking. Benelux warehouse automation deployments in the Netherlands and Belgium create concentrated demand clusters for compact frameless motor designs.
- HVAC:Refrigeration compressor retrofits accelerate under F-Gas Regulation phase-down mandates.
- Consumer Electronics:Drone propulsion and personal care devices prioritize weight minimization over service life.
Automotive commands the highest average selling prices. Robotics is gaining share fastest.
End User:
OEMs extract the most value from co-development relationships and exclusive supply agreements.
- Manufacturers:Industrial equipment builders specify custom winding configurations and shaft geometries for integration into pumps, fans, and conveyor systems. Polish Silesian industrial zones attract motor assembly operations serving Central European automation demand.
- OEMs:German automotive and medical device platform teams increasingly bypass distributors to specify motors directly, unbundling traditional component-plus-service contracts and compressing supplier margins.
- Service Providers:Maintenance contractors drive aftermarket demand for drop-in replacement units.
- Retailers:Distributor channels serve fragmented small-volume buyers with limited technical specification capability.
OEMs concentrate procurement volume. Manufacturers show the steepest order growth.
Technology:
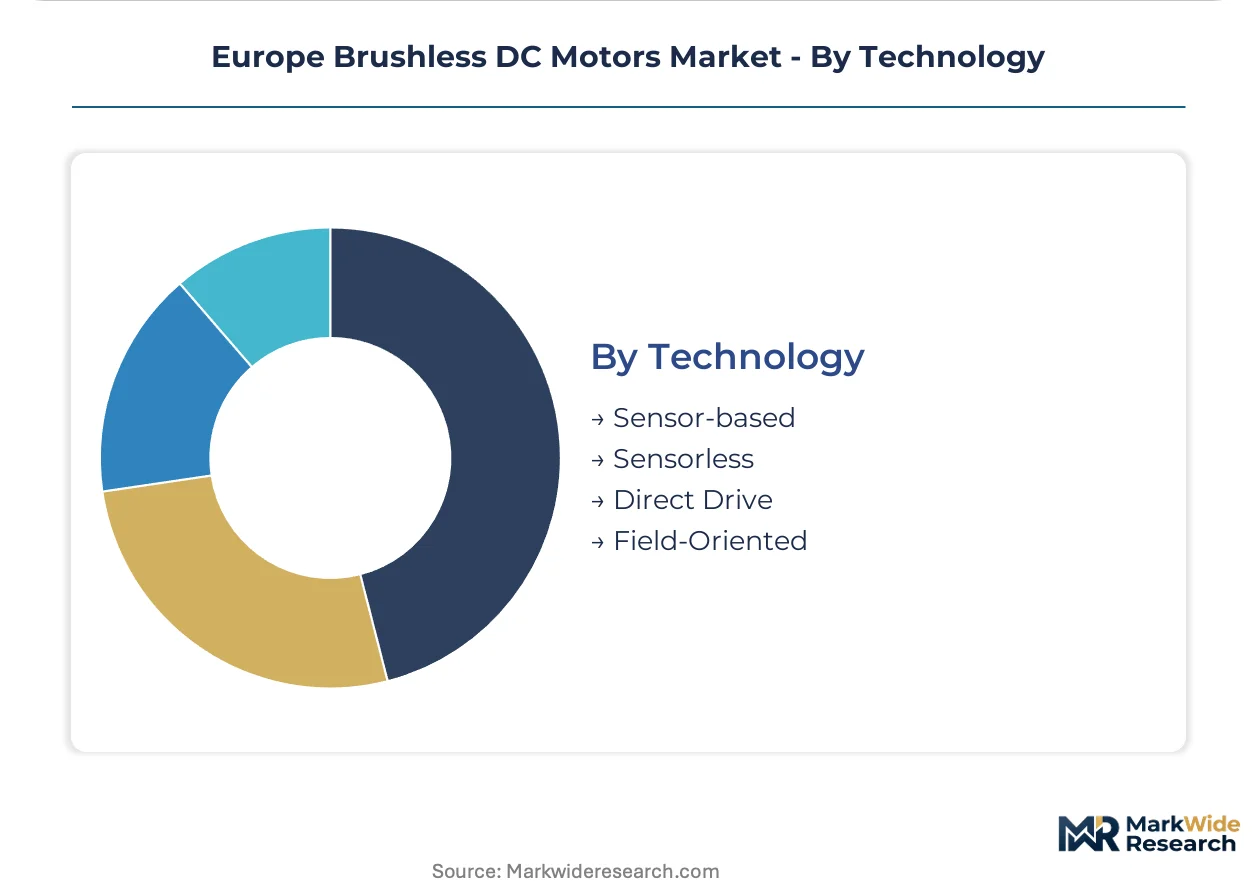
Sensorless architectures eliminate Hall-effect components and their associated failure modes, reducing bill-of-material costs.
- Sensor-based:Hall-effect and encoder feedback systems deliver precise rotor position data for medical robotics and aerospace actuators where trajectory accuracy is non-negotiable. Maxon and similar specialists dominate this segment with compact high-torque designs.
- Sensorless:Algorithmic rotor-position estimation via back-EMF sensing or high-frequency injection eliminates hardware cost and thermal cycling failure points. German Tier-1 suppliers deploy these architectures in automotive HVAC and pump applications.
- Direct Drive:Elimination of gearboxes reduces backlash and maintenance in precision motion stages.
- Field-Oriented:Vector control algorithms enable independent torque and flux regulation for dynamic performance.
Sensor-based retains installed base dominance. Sensorless is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the steepest market share in European brushless DC motor procurement, while Poland captures the fastest manufacturing relocation momentum as labor costs diverge across Central Europe.
Germany
Automotive powertrain electrification and industrial automation anchor demand in Stuttgart and Munich manufacturing corridors. The EU Green Deal compresses efficiency timelines for motor retrofits in refrigeration and HVAC equipment. Bavarian precision engineering clusters concentrate R&D investment for sensorless control algorithms serving Tier-1 automotive suppliers.
Poland
Silesian industrial zones attract motor assembly operations from German OEMs seeking cost arbitrage on labor and facility overhead. REACH compliance requirements extend qualification cycles for magnet coatings and winding materials. Warsaw-based logistics hubs coordinate distribution into Baltic states and Eastern European automation markets.
Netherlands
Warehouse robotics deployments in Rotterdam and Eindhoven generate concentrated demand for compact high-torque frameless motors. F-Gas Regulation mandates accelerate compressor retrofits in commercial refrigeration infrastructure. Randstad logistics networks enable just-in-time delivery to Benelux automation OEMs.
France
Aerospace actuator requirements in Toulouse and Paris-Saclay clusters sustain demand for precision motion control systems. ECHA substance restrictions on hexavalent chromium coatings reshape magnet supply chain configurations. Auvergne-Rhône-Alpes industrial zones host medical device manufacturers specifying compact motor designs for surgical robotics.
Italy
Industrial machinery builders in Lombardy and Emilia-Romagna specify custom winding configurations for pump and fan integration. CE marking requirements under the Machinery Directive enforce electromagnetic compatibility testing protocols. Northern Italian automation corridors channel procurement volume toward German and Polish motor suppliers.
Europe Brushless DC Motors Market Competitive Landscape
German producers anchor the premium-tier segment; Swiss and Austrian specialists hold positions in precision motion control applications. Market structure exhibits moderate consolidation with distinct capability stratification between integrated motor-drive architects and component specialists. Three archetypes dominate: industrial automation platform vendors, compact high-torque specialists, and automotive powertrain integrators. Capacity expansion in Central European manufacturing zones and strategic partnerships for rare earth magnet sourcing represent the dominant competitive moves.
Within the industrial automation tier, Siemens AG exemplifies platform-scale deployment capabilities. Maxon and Faulhaber occupy positions among precision motion specialists serving medical robotics and aerospace actuator segments. These three entities represent divergent strategic postures: integrated system architecture, compact torque density optimization, and miniature motor miniaturization respectively.
| Leading Market Players |
|---|
| Nanotec Electronic GmbH & Co. KG |
| Delta Line |
| Faulhaber |
| Siemens AG |
| Orbex Group |
| Maxon |
| Bühler Motor GmbH |
| Bosch Group |
| Portescap |
| Others |
Value Network & Pricing Analysis
GaN semiconductor integration into compact motor-drive housings compresses manufacturing costs while concentrating procurement leverage among German and Polish assembly operations. The EU Green Deal's efficiency mandates accelerate this transition by penalizing legacy induction motor architectures and rewarding electronically commutated designs with higher margin capture.
Pricing Analysis
Capacity additions in Poland are reshaping price floors for standard-efficiency brushless DC motors serving Central European automation OEMs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified automotive units from industrial-grade designs and unbranded aftermarket replacements. Price differentiation hinges on certification grade and volume scale, with German automotive OEMs extracting steepest discounts through direct specification authority. Cost compression in the economy tier is intensifying because Silesian assembly operations compete on labor arbitrage. Small industrial equipment builders show highest price sensitivity; medical robotics and aerospace buyers prioritize torque density over unit cost.
Supply Chain Analysis
Freight cost escalation from Chinese rare earth processing facilities to European magnet manufacturers is reshaping sourcing economics for neodymium-dysprosium formulations. Magnet supply concentrates in China, with secondary processing capabilities in Germany and Japan. Raw material dependencies span rare earth elements, copper winding stock, and silicon steel laminations. Single-source vulnerability runs through Chinese export licensing for heavy rare earths. Distribution runs through direct OEM relationships for automotive and medical segments, with distributor channels serving fragmented industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe brushless DC motors market compounds steadily as regulatory efficiency mandates force replacement cycles across installed industrial populations. This structural demand driver insulates volume growth from cyclical capital expenditure volatility.
For Market Incumbents: Anticipate margin compression from Polish cost competitors by accelerating sensorless control algorithm development and securing captive rare earth supply through offtake agreements with alternative processing facilities. Defensive positioning requires front-loading EU AI Act certification for autonomous motor control systems before implementing guidance crystallizes compliance costs. Capacity discipline in high-power automotive segments preserves pricing power against Silesian entrants. For New Entrants and Emerging Players: The F-Gas Regulation in the Netherlands and Belgium opens a window for compressor retrofit specialists targeting commercial refrigeration infrastructure with drop-in brushless DC replacements. Polish Silesian industrial zones offer the most penetrable geography for assembly operations serving Central European automation demand. A go-to-market angle through direct relationships with Benelux warehouse robotics OEMs bypasses entrenched German distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among modular motor specialists with field-serviceable architectures and established CE marking pathways. Long-term viability over the coming decade rests on magnet supply chain resilience and embedded software differentiation. Acquisition targets should demonstrate qualification progress with REACH-compliant coating chemistries. The signal to watch is ECHA candidate list expansion affecting hexavalent chromium alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Sensorless Control Algorithm Development | Eliminates Hall-effect sensors and their failure modes in automotive thermal management pumps. |
| Rare Earth Supply Agreement | Secures neodymium-dysprosium procurement outside Chinese processing concentration. |
| Polish Manufacturing Footprint | Captures labor cost arbitrage for standard-efficiency motor assembly serving Central Europe. |
| EU AI Act Certification Pathway | Establishes de facto standards for autonomous drive systems in collaborative robotics. |
| Integrated Motor-Drive Architecture Launch | Converges GaN semiconductors with compact housings for surgical tool applications. |
Research Methodology
Direct dialogue with motor control firmware engineers, Tier 1 automotive procurement leads, industrial automation OEM technical directors, and ECHA regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from EU Ecodesign Directive implementing measures, F-Gas Regulation phase-down schedules, REACH candidate list updates, and customs trade data for rare earth element flows. Bottom-up unit demand modeling triangulated against top-down industrial automation capex forecasts.
Market size outputs reflect segmentation across power rating tiers, application categories, and technology architectures over the projection horizon. The analytical framework modeled sensorless versus sensor-based adoption curves, integrated versus modular form factor preferences, and automotive versus industrial end-use splits. CAGRs derived from regression analysis against historical efficiency regulation impacts and correlated industrial production indices. Forecast inputs incorporated magnet price volatility scenarios and semiconductor lead time assumptions.
Revisions become necessary when Chinese export restrictions on heavy rare earths materialize, when EU AI Act implementing guidance alters certification timelines, or when GaN semiconductor supply constraints disrupt integrated motor-drive production. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Global Air Insulated Switchgear Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Magnetic Ballast Market