
 Europe Gas Insulated Switchgear Market | 2026-2036
Europe Gas Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gas Insulated Switchgear Market Insights
Aftermarket service revenue is rewriting how European switchgear manufacturers capture lifetime value from installed base contracts. Siemens AG leverages its digital service platforms to extend maintenance agreements across aging transmission infrastructure. ABB Ltd. anchors its competitiveness through predictive diagnostics bundled with retrofit programs. Schneider Electric SE differentiates by controlling spare parts logistics networks that reduce utility downtime.
Europe Gas Insulated Switchgear refers to metal-enclosed power distribution apparatus that uses sulfur hexafluoride or engineered gas mixtures as dielectric insulation, typically rated from 72.5 kV to 800 kV, with sealed tank designs enabling compact footprint deployment in space-constrained substations. The technology serves primarily to interrupt fault currents, isolate equipment sections, and protect grid stability in high-density urban and industrial environments. High voltage systems occupy the dominant margin pool due to offshore wind collector platforms and cross-border interconnector investments, while digital solution technology is expanding fastest as utilities deploy sensor-embedded GIS for real-time condition monitoring. Medium voltage installations remain mature across European manufacturing corridors, though modular product configurations are gaining traction in distributed generation tie-in projects.
The EU Green Deal and F-Gas Regulation are forcing manufacturers to certify reduced global warming potential alternatives, while CE marking and IEC 62271 standards govern product access across member states. ECHA's scrutiny of fluorinated gases is reshaping R&D allocation toward vacuum-interrupter hybrids and clean air insulation. Stakeholders must monitor how national grid operators reconcile procurement timelines with evolving material compliance deadlines.
Market Dynamics
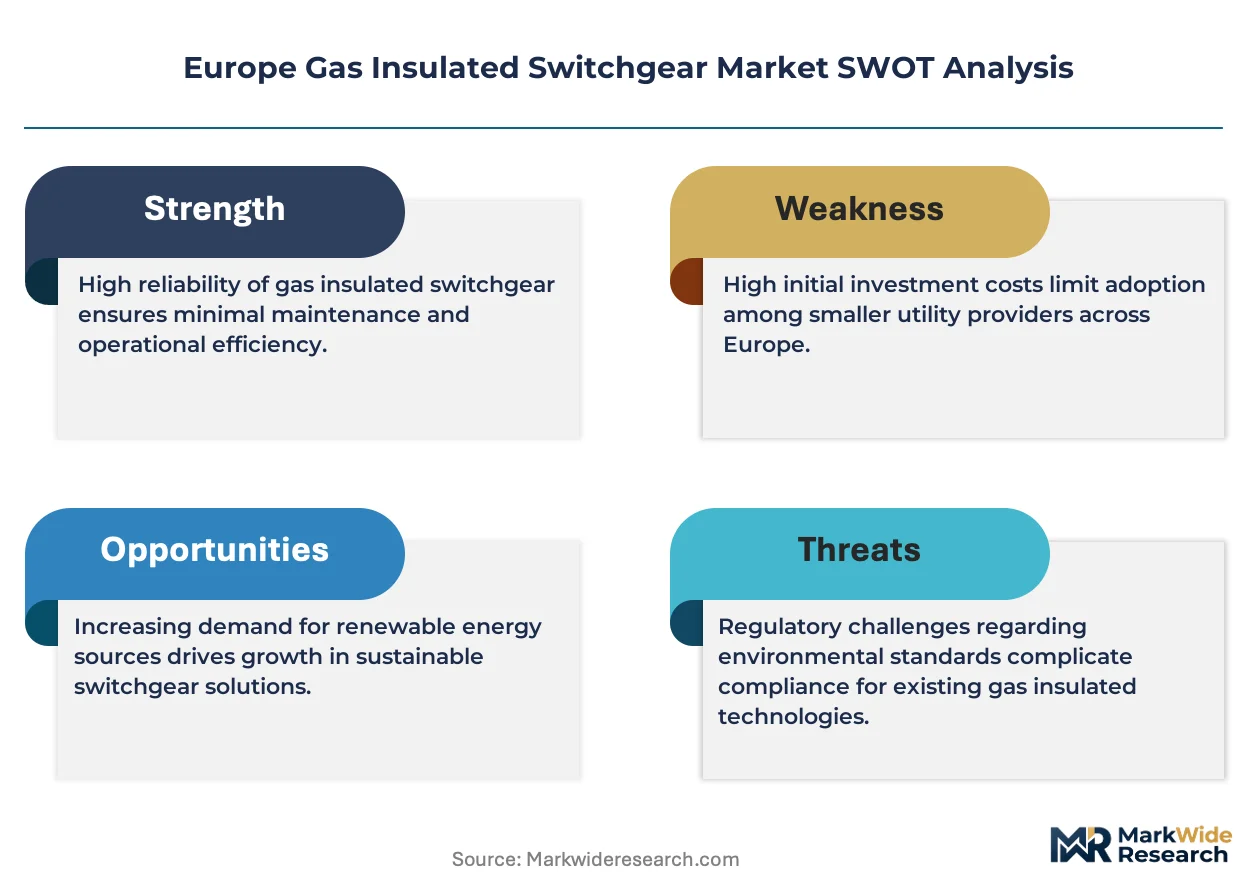
EU F-Gas Regulation is forcing sulfur hexafluoride phase-down schedules that compress R&D timelines and reshape insulation technology roadmaps across European switchgear manufacturing.
Growth Catalysts
- Offshore Wind Interconnection:North Sea wind collector platforms require compact 145 kV to 420 kV GIS installations that withstand corrosive marine environments. Grid operators in Germany and Denmark are procuring sealed-tank designs for converter stations.
- REACH Compliance Deadlines:ECHA scrutiny of fluorinated greenhouse gases is accelerating certification programs for clean air and vacuum-interrupter hybrid systems. Manufacturers are securing CE marking ahead of 2030 material restrictions.
- Urban Land Scarcity:Space-constrained substations in Paris, Milan, and Barcelona are specifying double-busbar GIS configurations that reduce footprint by 70% versus air-insulated alternatives. Municipal utilities favor indoor installations.
Market Restraints
- SF6 Gas Supply Concentration:European production of sulfur hexafluoride concentrates among three chemical manufacturers, exposing switchgear assemblers to input price volatility and quota allocation disputes.
- High Voltage Certification Barriers:IEC 62271-203 type testing for 550 kV and 800 kV ratings requires 18-24 month validation cycles at accredited laboratories, delaying product commercialization.
- Copper and Aluminum Price Volatility:Conductor materials constitute 25-30% of GIS bill-of-materials, with LME price swings compressing margin predictability for fixed-price EPC contracts.
Strategic Opportunities
- Polish Grid Modernization:PSE SA's 2030 transmission investment plan targets 400 kV corridor expansion, creating procurement windows for hybrid insulation systems in a market historically dependent on air-insulated switchgear.
- Digital Twin Integration:Sensor-embedded GIS with IEC 61850 protocol compatibility enables predictive maintenance revenue streams. Utilities in the Netherlands are piloting real-time partial discharge monitoring.
- Retrofit and Lifecycle Extension:Aging 1970s-1980s installations across France and Belgium require circuit breaker replacement without full substation reconstruction, opening modular upgrade pathways.
Industry Challenges
- SF6 Handling Certification Shortage:F-gas qualified technicians are concentrated among German and Austrian service organizations, creating bottlenecks for installation and decommissioning workflows.
- Legacy Control System Integration:Digital GIS deployments must interface with SCADA architectures designed for electromechanical relays, requiring protocol translation gateways that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gas Insulated Switchgear Market |
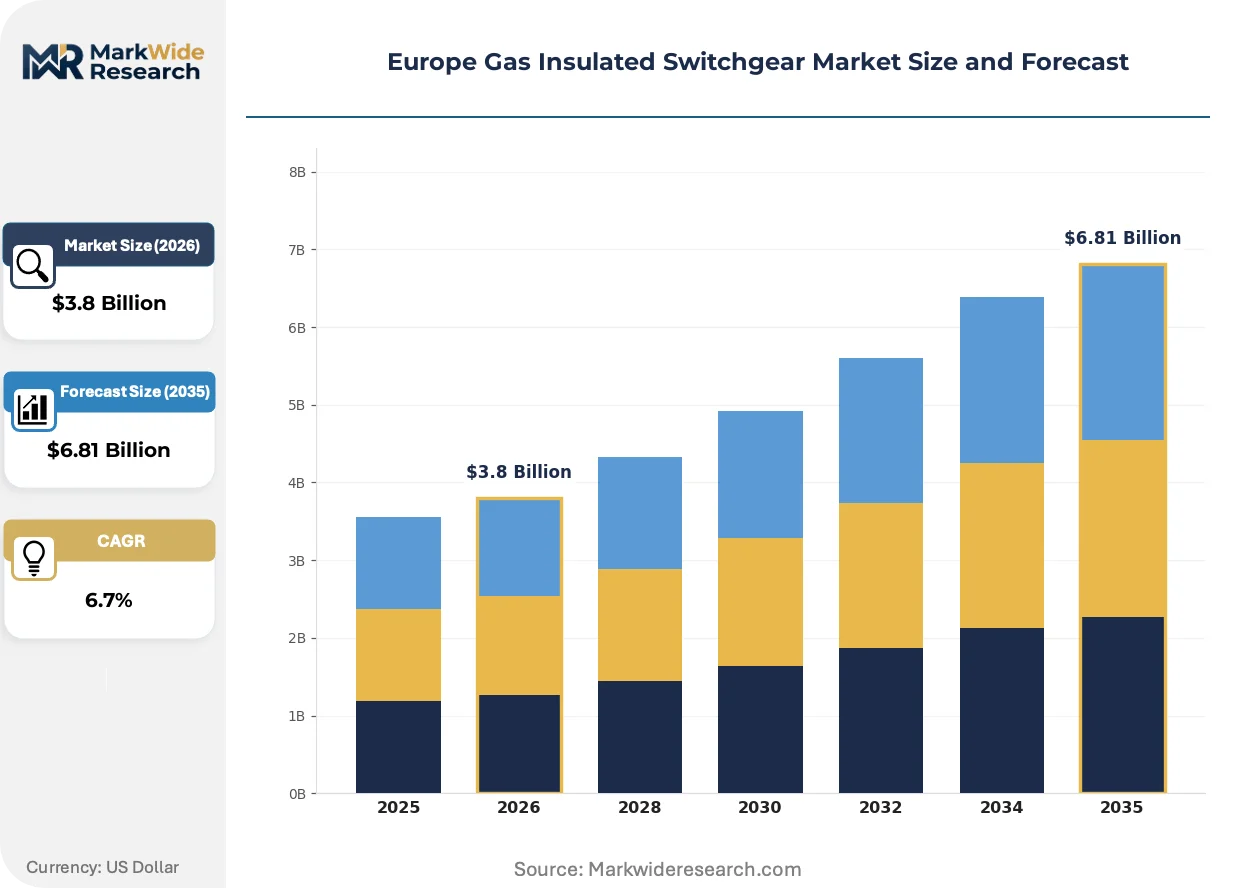
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Modular Installation Type: Indoor, Outdoor, Hybrid, Underground End User: Utilities, Industrial, Commercial, Transportation Technology: Hybrid System, Compact System, Smart Grid, Digital Solution |
| Companies Covered | Hitachi Energy, Eaton Corporation, Siemens AG, Fuji Electric, Mitsubishi Electric Corporation, ABB Ltd., General Electric Company, Toshiba International Corporation, Schneider Electric SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gas Insulated Switchgear Market Trends and Innovations
Insulation medium substitution is accelerating technology divergence between established SF6-dependent product lines and emerging clean air platforms, with regulatory compliance timelines dictating R&D resource allocation.
Clean air insulation technology is migrating from niche demonstration projects to serial production for 72.5 kV through 170 kV ratings. Scandinavian utilities in Norway and Sweden are specifying dry air dielectric for onshore substations to preempt national carbon accounting requirements. The technology is migrating from proof-of-concept installations to standardized product catalogs, compressing the competitive window for conventional SF6 designs in medium-voltage segments.
F-Gas Regulation amendment proposals are tightening permissible sulfur hexafluoride leakage rates and mandating comprehensive life-cycle reporting. Manufacturers must now certify global warming potential reductions across entire product portfolios rather than individual units. High voltage system producers are responding by accelerating vacuum interrupter development for 245 kV applications previously considered technically unfeasible.
Utility procurement departments are consolidating vendor panels and demanding 15-20 year total cost of ownership guarantees that internalize maintenance, gas handling, and end-of-life decommissioning. Traditional equipment-only sales models are yielding to performance-contracting frameworks in Germany and Austria. This behavioral shift is most visible among municipal Stadtwerke utilities that lack in-house high-voltage engineering expertise and prefer outcome accountability from OEM service organizations.
Europe Gas Insulated Switchgear Market Segmentation
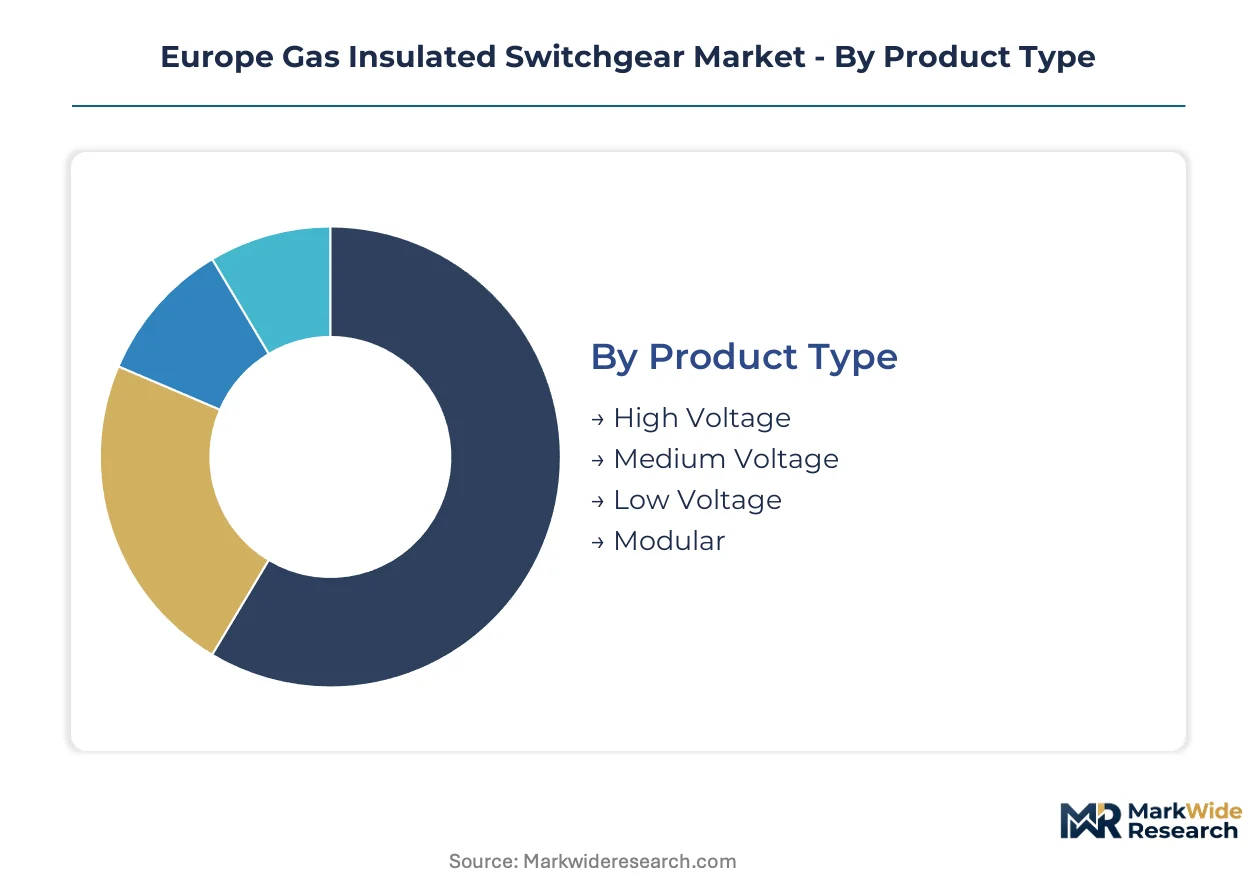
Segmentation in the Europe Gas Insulated Switchgear Market reveals distinct service intensity profiles across product tiers. High voltage installations demand specialized decommissioning protocols and gas recovery services, while digital solution deployments create recurring software maintenance revenue streams that reshape manufacturer-customer relationships.
Product Type:
After-sales service intensity varies sharply across voltage ratings, with high voltage systems requiring certified SF6 handling technicians and medium voltage units emphasizing modular replacement programs.
- High Voltage:Sealed-tank designs rated 245 kV to 800 kV dominate offshore wind collector platforms and cross-border interconnectors. German and Danish grid operators specify these for North Sea converter stations where marine corrosion resistance is mandatory.
- Medium Voltage:Compact 72.5 kV to 145 kV configurations serve urban substations in Paris and Milan. Municipal utilities prioritize footprint reduction over customization, driving standardized catalog offerings.
- Low Voltage:Industrial facility deployments in the Ruhr Valley and northern Italy favor plug-and-play integration with existing protection systems.
- Modular:Factory-assembled bay extensions enable phased substation expansion without complete shutdowns, appealing to Polish and Romanian transmission operators.
High Voltage holds the largest share; momentum sits with Modular configurations as utilities defer capital commitments.
Installation Type:
Cost tier differentiation separates premium indoor specifications from economy outdoor deployments, with underground installations commanding specialized civil engineering margins.
- Indoor:Climate-controlled halls in dense European cities eliminate weather-related insulation degradation. Barcelona and Vienna utilities specify double-busbar layouts for critical load centers.
- Outdoor:Open-air 420 kV yards persist in rural France and Spain where land constraints are minimal and aesthetic objections rare.
- Hybrid:Partially enclosed designs balance protection with ventilation, gaining traction in Belgian industrial parks.
- Underground:Subsurface vault installations in Amsterdam and Hamburg address severe surface scarcity, requiring specialized moisture sealing and access logistics.
Indoor specifications dominate revenue; Underground is climbing the fastest as cities densify.
End User:
Customer type determines procurement sophistication, with utilities demanding lifecycle cost guarantees and industrial buyers prioritizing delivery speed over service bundling.
- Utilities:Transmission system operators in Germany and Austria negotiate 15-20 year total cost of ownership contracts. Stadtwerke municipal utilities lack high-voltage engineering depth, outsourcing accountability to OEM service organizations.
- Industrial:Chemical and steel producers in the Netherlands and Belgium specify rapid-deployment GIS for process-critical power feeds, accepting higher capital outlay for minimized downtime.
- Commercial:Data center operators in Frankfurt and Dublin prioritize compact footprint and electromagnetic compatibility certification.
- Transportation:Railway electrification authorities in France and Switzerland procure ruggedized designs for traction substation environments.
Utilities command the dominant revenue pool; Commercial is gaining share fastest on data center construction.
Technology:
Application focus separates established hardware platforms from emerging digital overlays, with smart grid integration requiring protocol compatibility investments.
- Hybrid System:Vacuum interrupter and clean air insulation combinations address F-Gas Regulation compliance. Scandinavian utilities in Norway and Sweden specify these for national carbon accounting alignment.
- Compact System:Reduced-phase-spacing designs achieve 70% footprint reduction versus air-insulated alternatives, specified for Milan and Barcelona urban substations.
- Smart Grid:IEC 61850 protocol integration enables automated fault isolation and self-healing network architectures, piloted by Dutch distribution operators.
- Digital Solution:Sensor-embedded GIS with real-time partial discharge monitoring creates predictive maintenance revenue streams. Netherlands utilities lead deployment of condition-based asset management.
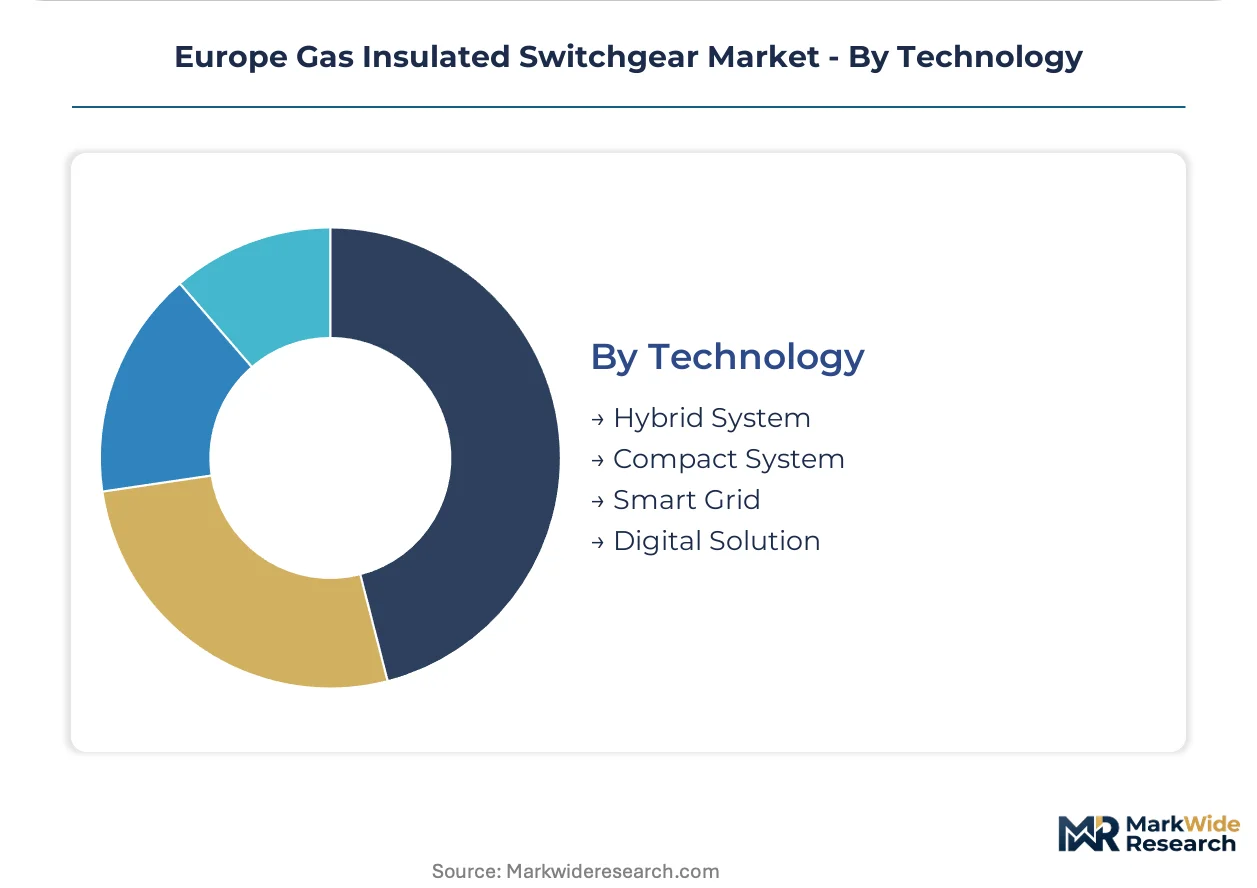
Compact System retains the largest installed base; Digital Solution shows the steepest expansion trajectory as sensor costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European switchgear manufacturing concentrates in Germany and Switzerland, with component supply chains radiating through Austria and northern Italy. This geographic clustering shapes procurement patterns across transmission utilities from the North Sea to the Mediterranean.
Germany
Transmission system operators TenneT and 50Hertz procure sealed-tank GIS for North Sea offshore wind converter stations. The F-Gas Regulation mandates sulfur hexafluoride phase-down schedules that compress R&D timelines for domestic manufacturers. Siemens AG anchors production in Bavaria, supplying 420 kV installations to Hamburg's urban substations.
France
RTE Réseau de Transport d'Électricité modernizes aging 1970s substations in the Paris region with modular bay extensions. ECHA scrutiny of fluorinated greenhouse gases accelerates certification programs for clean air alternatives. Alstom Grid facilities in Grenoble prototype vacuum-interrupter hybrids for 145 kV ratings.
United Kingdom
National Grid ESO procures compact GIS for London's constrained urban substations where footprint reduction is mandatory. The UK's post-Brexit alignment with IEC 62271 standards maintains CE marking equivalence for continental suppliers. Hitachi Energy maintains service operations in Staffordshire for North Sea offshore platforms.
Denmark
Energinet specifies marine-rated GIS for Kriegers Flak and other Baltic Sea wind collector platforms. National carbon accounting requirements drive specification of dry air dielectric systems in onshore substations. Vestas Wind Systems collaborates with switchgear suppliers on integrated turbine-to-grid solutions in Aarhus.
Poland
PSE SA's 2030 transmission investment plan targets 400 kV corridor expansion across the central grid backbone. EU cohesion funds accelerate procurement windows for hybrid insulation systems historically dependent on air-insulated switchgear. ABB Ltd. and local partners establish service capabilities in Warsaw for lifecycle maintenance contracts.
Europe Gas Insulated Switchgear Market Competitive Landscape
Integrated electrical conglomerates and specialized high-voltage equipment fabricators split the market between turnkey project execution and component supply. Siemens AG and ABB Ltd. anchor the premium tier through vertical control over gas handling and digital service platforms. Schneider Electric SE occupies the mid-market through standardized catalog offerings. Mitsubishi Electric Corporation and Fuji Electric compete on cost-optimized export configurations. Competitive intensity centers on predictive maintenance bundling and SF6 alternative certification timelines.
Within the integrated conglomerate tier, Siemens AG and ABB Ltd. exemplify full-lifecycle service positioning, while Schneider Electric SE represents modular standardization archetypes. Hitachi Energy and Mitsubishi Electric Corporation occupy positions as Asia-Pacific-origin multinationals with European manufacturing footprints. Eaton Corporation and General Electric Company sit within the industrial power management specialist category. Toshiba International Corporation and Fuji Electric anchor the export-oriented equipment supply segment. These nine named entities, alongside regional specialists aggregated under "Others," constitute the competitive set profiled in this analysis.
| Leading Market Players |
|---|
| Hitachi Energy |
| Eaton Corporation |
| Siemens AG |
| Fuji Electric |
| Mitsubishi Electric Corporation |
| ABB Ltd. |
| General Electric Company |
| Toshiba International Corporation |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
SF6 gas supply concentration among three European chemical manufacturers exposes switchgear assemblers to input price volatility and quota allocation disputes, compressing margin predictability for fixed-price EPC contracts while simultaneously dictating the three-tier pricing structure across premium certified, standard catalog, and economy import configurations.
Pricing Analysis
F-Gas Regulation dictates the pricing tier structure by imposing escalating compliance costs on sulfur hexafluoride-dependent product lines. Three-tier pricing separates CE-marked premium systems with full lifecycle service bundling from standard catalog offerings with limited warranties and economy imports lacking certified gas handling support. Price differentiation rests on certification grade and after-sales service depth. Cost compression in the economy tier is intensifying because municipal utilities in Poland and Romania prioritize capital expenditure minimization over operational reliability. Industrial buyers in the Netherlands exhibit lowest price sensitivity due to process-critical uptime requirements.
Supply Chain Analysis
Tariff exposure between Germany and China dominates raw material procurement risk for conductor components. Manufacturing gravity centers on Germany, Switzerland, and Austria, with sealed-tank fabrication and gas processing equipment drawing from specialized Bavarian and Baden-Württemberg supplier clusters. Copper and aluminum conductors, sulfur hexafluoride gas, and vacuum interrupter assemblies constitute critical input dependencies. Single-source vulnerability concentrates in certified SF6 handling equipment where F-gas qualified technician training capacity constrains service throughput. Distribution runs through authorized OEM service organizations and specialized high-voltage EPC contractors with direct utility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards organizations that control scarce F-gas certification capacity and proprietary clean air insulation intellectual property, with competitive advantage accruing to those who internalize gas handling logistics rather than outsourcing to fragmented service networks.
For Market Incumbents: Harden defensible positions by accelerating backward integration into SF6 gas recovery and recycling infrastructure, securing captive supply of fluorinated gases ahead of tightening EU quota allocations. Deepen vertical control over digital service platforms that lock municipal utilities into multi-year predictive maintenance contracts, neutralizing price competition from economy-tier imports. For New Entrants and Emerging Players: Establish a beachhead in Poland's 400 kV corridor expansion by partnering with local EPC contractors for hybrid insulation system deployment, leveraging EU cohesion fund procurement windows where incumbent relationships remain underdeveloped. Target modular bay extension retrofits across France and Belgium's aging 1970s substation infrastructure, offering rapid installation timelines that incumbent OEMs cannot match due to backlog congestion. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors clean air technology specialists with proven 170 kV+ product certification. Long-term viability hinges on intellectual property portfolios addressing F-Gas Regulation compliance deadlines rather than legacy SF6-dependent revenue streams. Watch for inflection signals in Scandinavian utility procurement patterns where national carbon accounting requirements are tightening fastest.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Air Insulation Certification | CE marking for 245 kV vacuum-interrupter hybrids opens German and Danish offshore wind procurement. |
| Digital Service Platform Integration | Sensor-embedded GIS with IEC 61850 compatibility captures recurring revenue from Dutch distribution operators. |
| SF6 Gas Recovery Infrastructure | Captive recycling capacity insulates margins from quota volatility under EU F-Gas Regulation phase-down schedules. |
| Modular Retrofit System Development | Factory-assembled bay extensions address French and Belgian lifecycle extension demand without full substation rebuilds. |
| Scandinavian Utility Partnership | Dry air dielectric specifications in Norway and Sweden preempt national carbon accounting compliance requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with transmission system operator planning officers, high-voltage EPC contractor project managers, OEM aftermarket service heads, and municipal utility procurement leads; and secondary validation against IEC 62271 certification databases, EU F-Gas Regulation compliance filings, ENTSO-E transmission investment plans, and customs trade data for conductor material flows. Bottom-up triangulation across equipment shipment records and top-down reconciliation with grid investment announcements anchored volume estimates.
Forecast inputs span voltage rating tiers, installation type specifications, end-user procurement sophistication levels, and technology adoption curves for digital solution deployments across the analysis window. Segmentation modeling incorporated product type, installation configuration, customer category, and insulation medium technology dimensions. CAGRs were derived from logistic diffusion curves fitted to regulatory compliance timelines and utility capital expenditure patterns, with offshore wind interconnection targets and F-Gas Regulation phase-down schedules as primary demand drivers.
Stress conditions across SF6 gas quota allocation severity, copper and aluminum price volatility bands, and high-voltage certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and grid operator procurement continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
North America Alternating Current (AC) Drive Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Copper Ground Rod Market