
 HV Bushing Market | 2026-2036
HV Bushing Market Size, Share, and Industry Trends Forecast 2026-2036
HV Bushing Market Outlook
Maintenance and lifecycle service contracts are shifting how HV bushing vendors monetize installed bases beyond initial equipment sales. ABB Ltd. leverages its global service network to anchor long-term utility relationships. Siemens differentiates through digital condition-monitoring integrations that extend asset visibility. Hubbell Incorporated specializes in North American utility specifications, occupying a defensible position in regional procurement frameworks.
High-voltage bushings are insulated electrical conductors designed to carry current through grounded barriers such as transformer tanks or switchgear enclosures, typically rated above 52 kV and constructed with oil-impregnated paper, resin, or composite housings to manage electric field distribution and environmental exposure. Their primary purpose is to ensure reliable power transfer while preventing flashover or insulation failure in substation and transmission infrastructure. Composite bushings are gaining share against porcelain alternatives due to superior contamination performance and reduced weight, concentrating margin pools with manufacturers that control resin formulation and fiber-winding processes. Renewable energy end users represent the fastest-growing demand channel, driven by offshore wind and solar farm interconnections requiring specialized bushings for variable load conditions.
IEC 60137 and CIGRE technical brochures establish global benchmark requirements for bushing insulation coordination and testing protocols, while national regulators such as India's CEA and China's SAMR enforce localized certification that shapes market access for imported equipment. The EU F-Gas Regulation and REACH compliance frameworks increasingly influence material selection for bushings containing oil or synthetic insulating fluids, pushing reformulation investments across European supply chains. Stakeholders must monitor evolving grid code harmonization between regions, as divergent standards threaten to fragment product platforms and inflate compliance costs for multinational suppliers.
Market Dynamics
Composite resin formulations are displacing porcelain across high-voltage transmission corridors, concentrating manufacturing margin pools with suppliers that control fiber-winding automation and silicone housing chemistry. This material transition reshapes procurement specifications, service lifecycle economics, and regional competitive positioning simultaneously.
Growth Catalysts
- Grid Modernization Mandates:India's CEA and China's SAMR are enforcing accelerated replacement cycles for aging porcelain installations, expanding tender volumes for composite alternatives in 765 kV and 800 kV corridors.
- Offshore Wind Interconnection:Specialized bushings for variable load conditions and salt spray exposure are capturing procurement priority from North Sea developers and Asia-Pacific floating wind projects.
- IEC 60137 Harmonization:Standardized insulation coordination protocols are reducing technical barriers for composite bushing adoption across multi-vendor substation architectures.
Market Restraints
- Epoxy Resin Supply Concentration:Three Asian chemical conglomerates control over 70 percent of cycloaliphatic amine hardeners, creating input cost volatility for Western bushing manufacturers.
- REACH Compliance Burden:EU F-Gas Regulation and ECHA substance restrictions are forcing reformulation investments that extend European product development timelines by 18-24 months.
- Porcelain Asset Inertia:Established utilities in Germany, Japan, and the US retain decades of operational experience with ceramic bushings, slowing composite substitution despite superior contamination performance.
Strategic Opportunities
- Digital Condition Monitoring Integration:Fiber optic partial discharge sensors and dissolved gas analysis modules are converging with bushing hardware, enabling predictive maintenance contracts that extend vendor revenue streams.
- India Transmission Buildout:Green Energy Corridors and inter-regional HVDC links are creating dedicated procurement channels for 400 kV and 765 kV composite bushings with localized content requirements.
- Retrofit Service Contracts:Aging transformer fleets in North America and Europe require bushing replacement without full asset retirement, opening aftermarket channels distinct from greenfield equipment sales.
Industry Challenges
- Composite Winding Technician Scarcity:Automated fiber placement and vacuum pressure impregnation expertise concentrates in a handful of European and Japanese equipment suppliers, constraining manufacturing scale-up.
- Type Test Certification Timelines:IEC 60137 long-duration voltage endurance and seismic qualification protocols require 12-18 month validation cycles that delay product launches and lock working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HV Bushing Market |
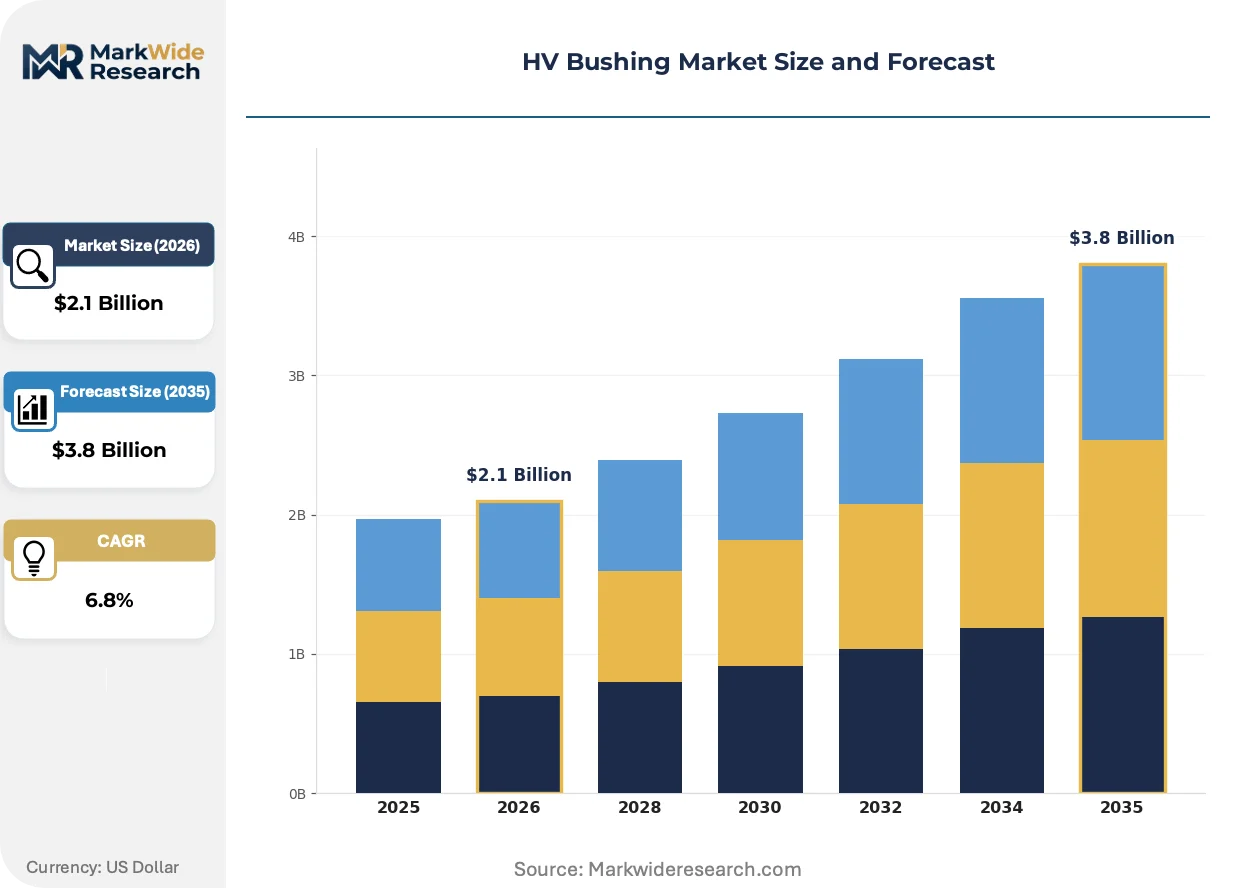
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor, Indoor, Plug-in, Dead-front Material: Ceramic, Composite, Silicone, Porcelain End User: Utilities, Industrial, Renewable Energy, Transportation Application: Transmission, Distribution, Power Generation, Substation |
| Companies Covered | ABB Ltd., Siemens, General Electric, Hubbell Incorporated, Eaton, Nexans, ELANTAS GmbH, Crompton Greaves, Trench Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HV Bushing Market Strategic Shifts
Silicone rubber housing technology is expanding into voltage classes and environmental conditions previously dominated by porcelain, while digital monitoring integration and procurement model evolution reshape how value is captured across the bushing lifecycle.
Silicone rubber composite housings with hydrophobic surface properties are expanding into ultra-high voltage applications above 800 kV, where their superior contamination flashover resistance and reduced weight enable compact substation designs. Offshore wind developers in the North Sea and Asia-Pacific are specifying these materials for platform-mounted transformers exposed to salt spray and humidity cycling. The technology is expanding into a structural wedge against porcelain incumbents by compressing total installed cost and maintenance intervals simultaneously.
EU F-Gas Regulation and REACH substance restrictions are accelerating material substitution across European supply chains, prohibiting certain synthetic insulating fluids and mandating extended producer responsibility for end-of-life handling. Bushing manufacturers are reformulating oil-impregnated paper insulation and silicone housing chemistries to maintain dielectric performance under stricter environmental compliance. German and French transmission system operators are now requiring full material disclosure and circularity documentation in procurement tenders.
Utility procurement departments are unbundling equipment supply from installation and long-term service, creating discrete contract vehicles for condition monitoring, predictive analytics, and replacement scheduling. This purchasing pattern disrupts traditional bundled sales models and favors vendors with established field service networks and digital platform capabilities. The shift is most visible in North American investor-owned utilities and Nordic transmission system operators with centralized asset management functions.
HV Bushing Market Segmentation
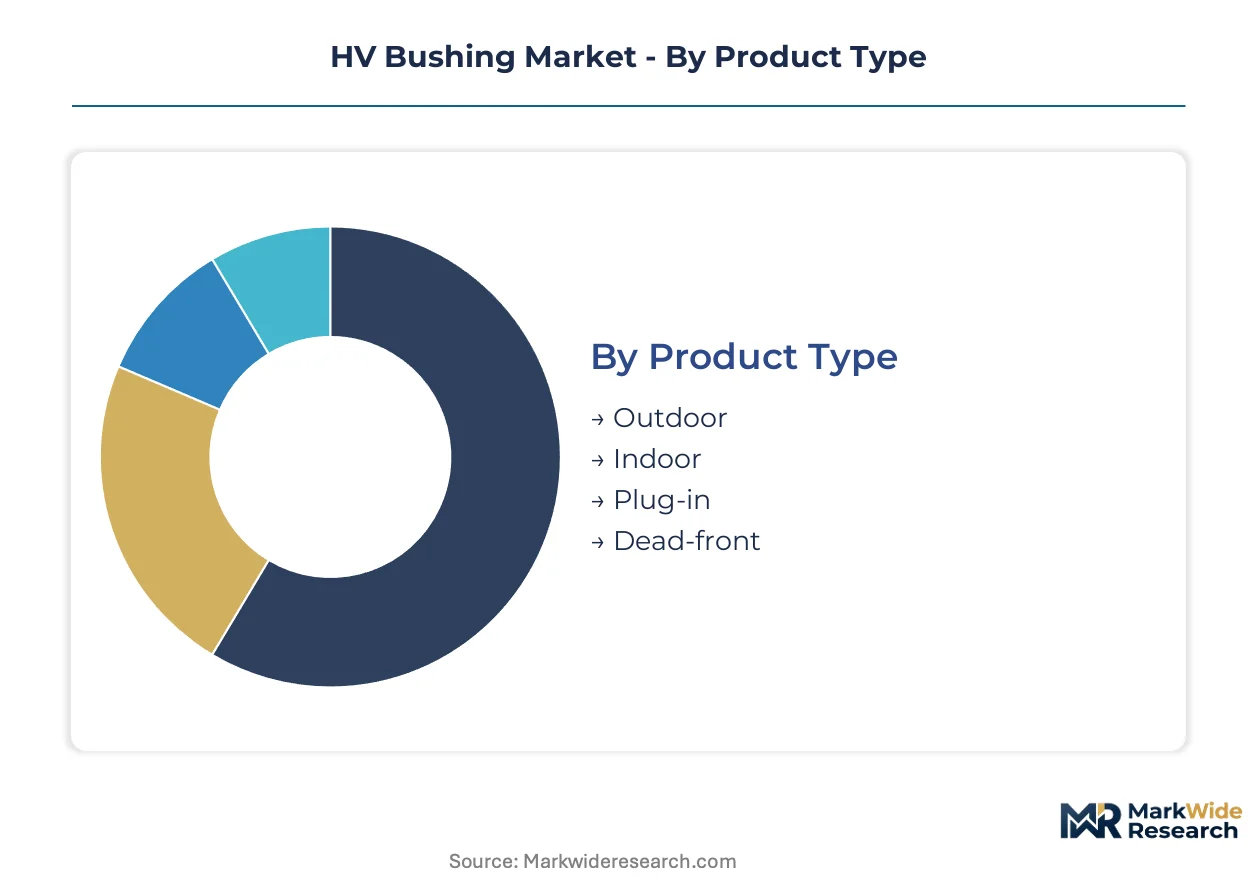
HV bushing procurement specifications diverge sharply across voltage classes, environmental exposure, and grid architecture requirements. Segmentation reveals how material transitions and application-specific load profiles concentrate margin pools with specialized manufacturers.
Product Type:
Customization intensity spans from standardized indoor installations to engineered outdoor configurations for extreme contamination zones.
- Outdoor:Silicone rubber housings with hydrophobic surface properties dominate coastal and industrial pollution corridors. Demand concentrates in India's Green Energy Corridors and China's 765 kV transmission buildouts where contamination flashover resistance determines specification. Salt spray exposure from North Sea offshore wind platforms accelerates composite substitution against porcelain legacy stock.
- Indoor:GIS-compatible compact designs with SF6 insulation integration serve space-constrained urban substations in Japan and South Korea. Specification tightness around partial discharge limits favors established suppliers with automated fiber-winding capabilities.
- Plug-in:Modular connection systems for mobile substations and emergency grid restoration.
- Dead-front:Touch-safe enclosures for underground distribution networks in dense European urban centers.
Most installed capacity flows through Outdoor. Expansion is steepest in Plug-in.
Material:
Cost tier stratification separates commodity porcelain from premium composite formulations with proprietary resin chemistry.
- Composite:Epoxy-impregnated fiber structures with silicone rubber weather sheds capture procurement priority above 400 kV. Weight reduction enables compact substation designs in Germany and France where seismic qualification and transportation constraints favor lighter alternatives.
- Silicone:Hydrophobic housing chemistry with self-cleaning surface properties targets offshore wind interconnection in the North Sea and Asia-Pacific floating platforms. Salt spray cycling resistance extends maintenance intervals beyond porcelain benchmarks.
- Ceramic:Alumina-based structures retain share in established networks with decades of operational experience.
- Porcelain:Legacy installations in Germany, Japan, and the US face accelerated replacement cycles driven by CIGRE technical guidance on contamination performance.
Volume concentrates in Porcelain legacy base. Margin expansion concentrates in Composite.
End User:
Customer type determines contract structure, from bundled EPC arrangements to unbundled service-centric procurement.
- Utilities:Centralized transmission system operators in India and China drive tender volumes for 765 kV and 800 kV corridors. India's CEA mandates localize content requirements that reshape supplier qualification criteria.
- Renewable Energy:Offshore wind developers in the North Sea and solar farm interconnectors require specialized bushings for variable load conditions. IEC 60137 harmonization reduces technical barriers for multi-vendor substation architectures.
- Industrial:Petrochemical and steel sector captive power plants with high reliability requirements.
- Transportation:Railway electrification and metro traction substations with space and weight constraints.
Procurement volume flows through Utilities. Steepest expansion trajectory appears in Renewable Energy.
Application:
Application maturity separates standardized distribution specifications from engineered transmission solutions with extended qualification protocols.
- Transmission:Ultra-high voltage corridors above 400 kV require type-tested designs with 12-18 month IEC 60137 validation cycles. India's inter-regional HVDC links and China's 800 kV projects concentrate demand for composite alternatives with seismic and pollution performance credentials.
- Substation:Transformer and switchgear integration points where digital condition monitoring convergence creates predictive maintenance revenue streams. Fiber optic partial discharge sensors extend vendor service contracts beyond equipment sale.
- Distribution:Medium voltage networks with standardized procurement and shorter replacement cycles.
- Power Generation:Generator step-up transformers with thermal cycling and vibration resistance requirements.
Most capital deployment flows through Transmission. Fastest share gain occurs in Substation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's CEA mandates accelerated porcelain replacement cycles while India's Green Energy Corridors concentrate tender volumes for composite alternatives, revealing how regulatory timing and infrastructure age diverge procurement patterns across major Asian markets.
China
State Grid Corporation drives 800 kV ultra-high voltage corridor buildouts through western provinces. SAMR enforces localized certification requirements that reshape supplier qualification criteria for imported equipment. Manufacturing clusters in Shandong and Jiangsu provinces concentrate fiber-winding automation capabilities for domestic composite bushing production.
India
Green Energy Corridors and inter-regional HVDC links create dedicated procurement channels for 765 kV composite bushings. CEA mandates localize content requirements that favor domestic assembly partnerships over direct imports. Industrial corridors in Gujarat and Maharashtra host emerging bushing fabrication facilities serving western and southern transmission networks.
Germany
Transmission system operators retain decades of operational experience with porcelain legacy stock, slowing composite substitution despite superior contamination performance. EU F-Gas Regulation and REACH compliance frameworks force reformulation investments that extend product development timelines. Manufacturing concentration in Bavaria and Baden-Württemberg supplies specialized bushings for North Sea offshore wind interconnection projects.
United States
Aging transformer fleets in the Midwest and Northeast require bushing replacement without full asset retirement, opening aftermarket channels distinct from greenfield equipment sales. FERC grid reliability standards influence procurement specifications for investor-owned utilities. Regional manufacturing presence in the Ohio River Valley and Texas Gulf Coast serves North American utility procurement frameworks.
Japan
GIS-compatible compact designs with SF6 insulation integration serve space-constrained urban substations in Tokyo and Osaka metropolitan areas. METI efficiency standards shape specification tightness around partial discharge limits. Industrial clusters in the Chubu region around Nagoya maintain automated fiber-winding capabilities for premium composite bushing production.
HV Bushing Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated electrical equipment conglomerates controlling transmission-tier procurement while regional fabricators capture distribution and retrofit service contracts. Market structure concentrates around three strategic archetypes: resin chemistry specialists with proprietary formulation control, field service network operators monetizing long-term maintenance contracts, and utility-specification incumbents anchored in regional procurement frameworks. Competitive moves center on digital condition-monitoring integration partnerships and backward integration into cycloaliphatic amine hardener supply chains.
Within the integrated conglomerate tier, ABB Ltd. and Siemens occupy positions exemplifying global service network scale and digital platform capabilities respectively. Hubbell Incorporated represents the utility-specification incumbent archetype with concentrated presence in North American procurement frameworks. These three anchors demonstrate how vendor positioning stratifies across bundled equipment sales versus unbundled service-centric contract vehicles.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens |
| General Electric |
| Hubbell Incorporated |
| Eaton |
| Nexans |
| ELANTAS GmbH |
| Crompton Greaves |
| Trench Group |
| Others |
Value Chain & Pricing Dynamics
India's CEA-mandated localize content requirements for 765 kV transmission corridors are forcing Western manufacturers to establish domestic assembly partnerships, compressing margins on imported composite bushings while elevating price premiums for resin-chemistry specialists with captive hardener supply.
Pricing Analysis
Capacity additions in China's Shandong and Jiangsu provinces are reshaping price floors for epoxy-impregnated fiber structures. Three-tier pricing structure across premium certified, standard IEC-compliant, and economy porcelain-replacement tiers separates vendors by type-test certification status and automated fiber-winding capability. Cost compression in the standard tier is intensifying because Indian and Chinese utilities are consolidating tender volumes. Distribution utilities in emerging markets exhibit highest price sensitivity, while North Sea offshore wind developers accept premium positioning for salt-spray-qualified silicone housings.
Supply Chain Analysis
Single-source vulnerability sits with three Asian chemical conglomerates controlling cycloaliphatic amine hardener supply. Manufacturing concentration centers on China, Germany, and India for fiber-winding automation and silicone housing production. Raw material dependencies draw from epoxy resin formulations, glass fiber rovings, and hydrophobic silicone rubber compounds. Tariff exposure threatens Western manufacturers importing finished bushings into India's protected procurement framework. Distribution runs through utility tender channels, EPC contractor specifications, and aftermarket service contracts for aging transformer fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite bushing margins are expanding as silicone housing chemistry and digital condition-monitoring integration command premium positioning, while resin formulation control captures value from cycloaliphatic amine supply concentration.
For Market Incumbents: Acquire automated fiber-winding equipment suppliers to secure manufacturing scale-up capacity against technician scarcity constraints. Deepen backward integration into cycloaliphatic amine hardener supply chains to offset input cost volatility from Asian chemical conglomerates. Anchor long-term utility relationships through predictive maintenance platform deployments that extend revenue streams beyond equipment sales. For New Entrants and Emerging Players: Capture India's Green Energy Corridor retrofit opportunities where CEA localize content requirements disadvantage direct importers. Target North American aftermarket service contracts for aging transformer fleets in the Midwest and Northeast, where bundled digital monitoring integration remains underpenetrated. Lead with unbundled service-centric procurement models that disrupt traditional equipment-plus-installation bundling. For Investors and Strategic Acquirers: Asymmetric upside sits with resin-chemistry specialists with proprietary formulation control and established IEC 60137 type-test certification libraries. Long-term viability hinges on positioning for the 800 kV ultra-high voltage buildout cycle and offshore wind interconnection wave across the North Sea and Asia-Pacific. Monitor CIGRE technical brochure revisions on contamination performance as the signal for accelerated porcelain replacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardener Supply | Cycloaliphatic amine captive production insulates Western manufacturers from Asian supply concentration. |
| Digital Condition Monitoring Integration | Fiber optic partial discharge sensors extend vendor revenue into predictive maintenance contracts. |
| India Localization Partnership | CEA-mandated content requirements reshape supplier qualification for Green Energy Corridor tenders. |
| Offshore Wind Certification Investment | Salt-spray-qualified silicone housings capture procurement priority from North Sea developers. |
| Automated Fiber-Winding Scale-Up | Vacuum pressure impregnation expertise constraints lift with European and Japanese equipment supplier partnerships. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility procurement officers, transformer OEM technical directors, EPC contractor specification engineers, and resin chemistry R&D leads with secondary validation from IEC 60137 certification databases, CIGRE technical brochure archives, and national regulator filings with India's CEA and China's SAMR. Bottom-up tender volume aggregation and top-down grid investment flow analysis were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to documented replacement cycle data and greenfield transmission corridor commissioning schedules. Segmentation modeling spanned voltage class, material chemistry, end-user procurement structure, and application-specific load profiles. CAGRs were derived from utility capital expenditure trajectories, renewable energy interconnection pipelines, and composite substitution rates against porcelain legacy stock. Forecast inputs incorporated offshore wind capacity additions and HVDC link development timelines.
Regulatory timing shifts, raw material supply disruptions, and grid code harmonization delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on localization mandate enforcement and type-test certification timeline stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
Load Bank Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
North America Alternating Current (AC) Drive Market
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market