
 Electrodialysis System Market | 2026-2036
Electrodialysis System Market Size, Share, and Industry Trends Forecast 2026-2036
Electrodialysis System Market Insights
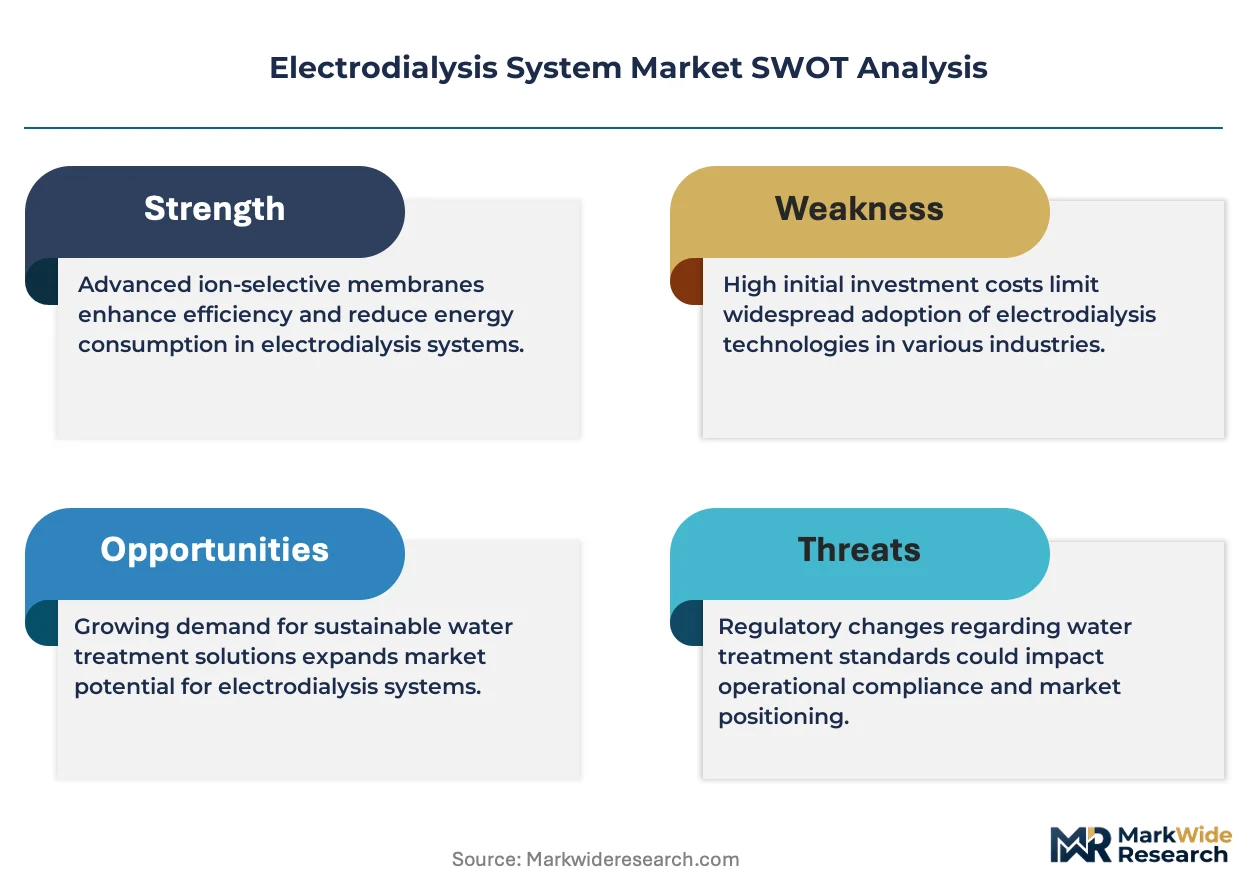
Industrial end users is rotating toward electrodialysis for zero-liquid-discharge wastewater recovery, displacing conventional thermal evaporators in chemical processing plants. PCCell GmbH leverages its German engineering base to dominate high-performance membrane stack supply for European desalination projects. Saltworks Technologies sustains technology leadership in hybrid electrodialysis-crystallization systems for lithium brine refining. Evoqua Water Technologies LLC anchors North American municipal contracts through integrated service contracts spanning membrane replacement and remote monitoring.
An electrodialysis system employs ion-selective membranes and direct current electric fields to separate dissolved salts from aqueous solutions, typically operating at voltages below 2 V per cell pair with membrane pore sizes in the nanometer range to enable monovalent-divalent ion selectivity. Continuous systems capture the largest installed base in municipal desalination due to lower operating labor requirements, while hybrid systems represent the fastest-expanding category as food and beverage processors seek combined demineralization-concentration functionality. Specialty chemicals applications concentrate margin pools where pharmaceutical-grade salt splitting commands premium membrane replacement cycles.
EPA effluent limitation guidelines and EU F-Gas Regulation restrict energy-intensive thermal separation methods, directly expanding electrodialysis eligibility in industrial discharge compliance. REACH registration requirements for membrane polymers influence material selection timelines and supplier qualification protocols across European manufacturing. ISO 9001 quality management and NSF/ANSI 61 drinking water system certifications shape procurement specifications for municipal buyers. Stakeholders must monitor membrane fouling mitigation advances and power supply efficiency gains to defend capital project returns against competing reverse osmosis bids.
Market Dynamics
Industrial discharge compliance deadlines are compressing project timelines, forcing municipal and chemical sector buyers to accelerate membrane replacement cycles and prioritize energy-efficient separation architectures over thermal alternatives.
Growth Catalysts
- EU F-Gas Regulation:Stringent limits on fluorinated greenhouse gases in industrial processes are disqualifying conventional evaporators and expanding eligibility for electrodialysis in German and Dutch chemical corridors.
- Lithium brine refining:Battery-grade lithium carbonate specifications are tightening, driving adoption of hybrid electrodialysis-crystallization systems for direct extraction from South American salars.
- Zero-liquid-discharge mandates:Food and beverage processors in California and Texas face evaporative discharge restrictions, rotating capital toward closed-loop electrodialysis recovery systems.
Market Restraints
- Ion-exchange membrane supply concentration:High-performance perfluorinated membrane production clusters in Japan and Germany, creating single-source vulnerability for stack assemblers.
- Capital intensity of hybrid systems:Integrated electrodialysis-crystallization configurations require 40-60% higher upfront investment than standalone reverse osmosis, limiting mid-scale industrial adoption.
- Reverse osmosis substitution threat:Spiral-wound membrane cost declines and energy recovery device improvements are narrowing the efficiency gap in low-salinity municipal applications.
Strategic Opportunities
- Pharmaceutical-grade salt splitting:cGMP-certified electrodialysis for active pharmaceutical ingredient manufacturing commands premium service contracts and recurring membrane replacement revenue.
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic lithium refining incentives are creating first-mover openings for brine concentration technology suppliers.
- Convergence with electrochemical oxidation:Combined electrodialysis-EO systems for simultaneous desalination and organics destruction are penetrating specialty chemicals wastewater treatment.
Industry Challenges
- Membrane fouling expertise gap:Scaling and organic fouling mitigation requires specialized electrochemist talent scarce outside established European and Japanese engineering centers.
- NSF/ANSI 61 certification timelines:Drinking water system approvals for new membrane polymers extend 18-24 months, delaying product launches for municipal buyers.
- Legacy DCS integration complexity:Electrodialysis stack voltage control systems require custom programming to interface with existing plant distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrodialysis System Market |
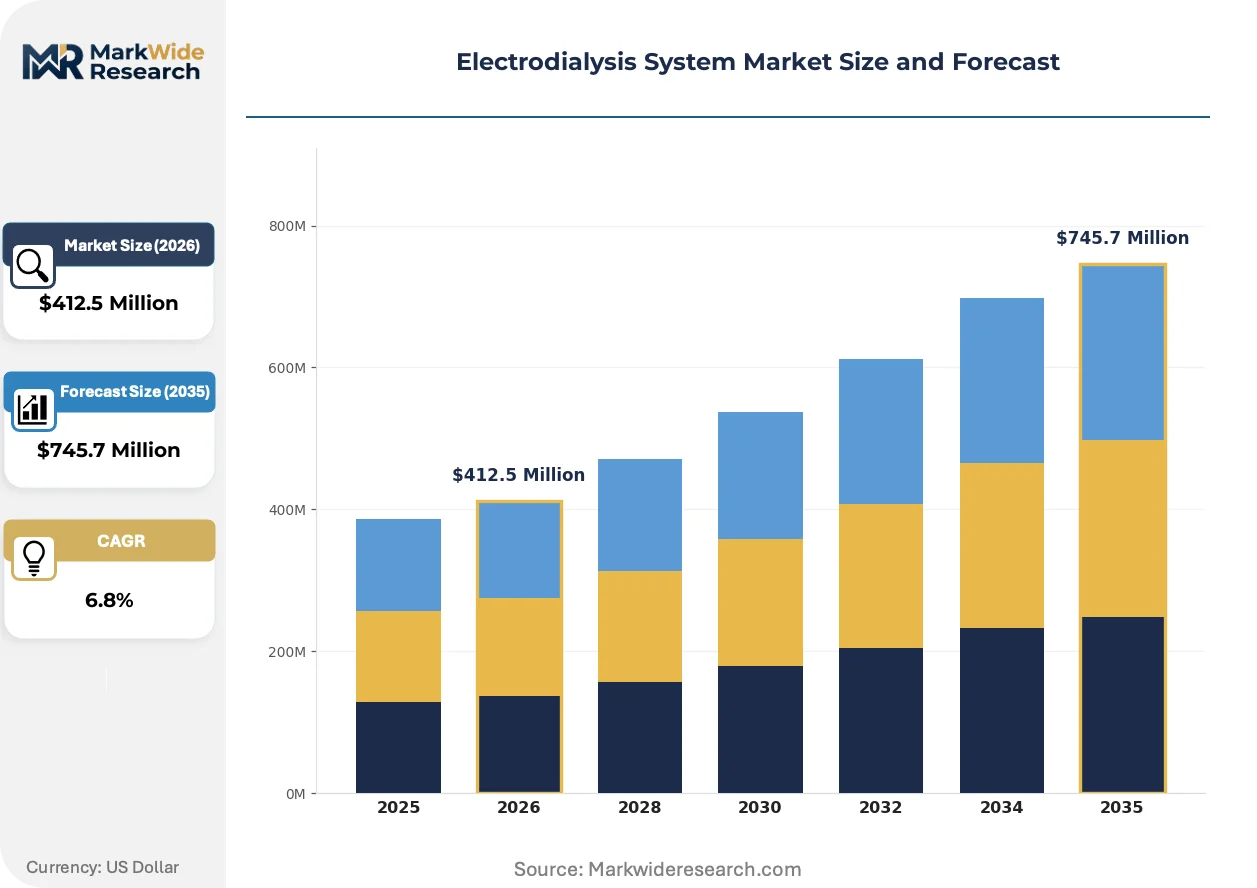
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Systems, Hybrid Systems, Compact Systems Application: Water Desalination, Wastewater Treatment, Specialty Chemicals, Food & Beverage Processing End User: Municipal Water Treatment, Industrial, Agriculture, Research Institutions Technology: Ion Exchange Membranes, Electrodialysis Stack, Power Supply, Monitoring Systems |
| Companies Covered | PCCell GmbH, Saltworks Technologies, ASTOM Corporation, MEGA a.s., Evoqua Water Technologies LLC, GE Corporation, Eurodia Industrie, AGC Engineering Co., Ltd., SnowPure, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrodialysis System Market Trends and Innovations
Bipolar membrane electrodialysis is advancing from pilot to commercial scale, enabling direct acid-base generation without salt feedstock and reshaping process economics for chemical manufacturers.
Monovalent-selective anion exchange membranes with nanometer-scale pore architecture are displacing conventional membrane stacks in lithium refining applications. Chinese battery material producers are adopting these membranes at accelerating pace to meet battery-grade lithium hydroxide purity specifications. The technology is compressing incumbent thermal crystallization equipment margins and forcing evaporator manufacturers to defend position through energy efficiency claims.
REACH registration requirements for perfluorinated membrane polymers are extending material qualification timelines and reshaping European supplier procurement protocols. Industrial buyers now require full substance dossier documentation before stack replacement contracts, compressing vendor switching flexibility. German chemical processors along the Rhine corridor are most affected, with several facilities accelerating membrane inventory builds ahead of anticipated regulatory bottlenecks.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts across North American municipal desalination. Cities now separately procure membrane stacks, power electronics, and remote monitoring services, compressing integrated vendor margins and opening entry points for specialized stack suppliers. California water districts are leading this disaggregation, driven by procurement transparency mandates and desire to optimize component replacement cycles independently.
Electrodialysis System Market Segmentation
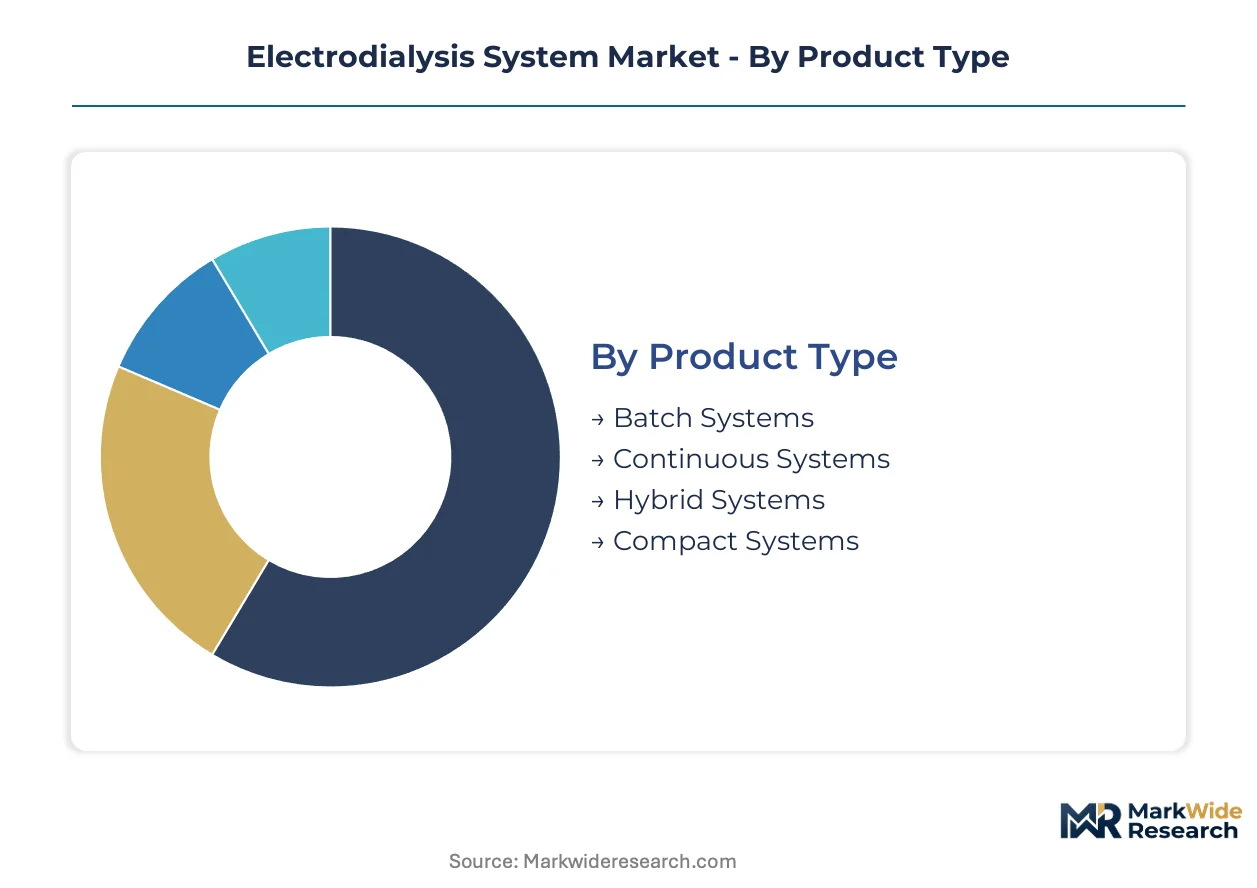
Electrodialysis system segmentation reveals divergent margin structures across operational architectures and end-use applications. Technology choices determine membrane replacement revenue cycles, while application focus shapes certification requirements and procurement timelines.
Product Type:
Margin pools concentrate in configurations enabling process intensification and reduced labor intensity for industrial operators.
- Batch Systems:Intermittent operation with manual loading cycles suits laboratory-scale salt splitting and pilot validation work. Pharmaceutical manufacturers in Switzerland deploy these units for active pharmaceutical ingredient salt conversion, constrained by batch cycle throughput ceilings.
- Continuous Systems:Automated feed-and-bleed architectures with minimal operator intervention dominate municipal desalination installations. German water utilities along the Rhine corridor specify these configurations for brackish water treatment, driven by EPA and EU discharge compliance deadlines compressing project timelines.
- Hybrid Systems:Integrated electrodialysis-crystallization platforms command premium pricing for lithium brine concentration. South American salar operators adopt these for direct lithium extraction, climbing the fastest as battery-grade carbonate specifications tighten.
- Compact Systems:Skid-mounted pre-engineered units reduce field installation costs for remote agricultural and small industrial sites. Containerized delivery suits Australian mining camps requiring rapid deployment.
Continuous systems hold installed capacity. Hybrid systems are rotating up the share rankings.
Application:
Application segmentation tracks regulatory pressure intensity and purity specification stringency across end-use sectors.
- Water Desalination:Brackish groundwater and seawater demineralization for municipal supply. California water districts disaggregate procurement across membrane stacks and power electronics, compressing integrated vendor margins.
- Wastewater Treatment:Zero-liquid-discharge recovery systems for chemical processing effluent. Texas and California food processors face evaporative discharge restrictions, rotating capital toward closed-loop recovery architectures.
- Specialty Chemicals:Pharmaceutical-grade salt splitting and acid-base generation command premium service contracts. cGMP-certified electrodialysis for active pharmaceutical ingredient manufacturing generates recurring membrane replacement revenue at elevated margins.
- Food & Beverage Processing:Combined demineralization-concentration for dairy and juice applications. Bipolar membrane configurations enable direct acid-base generation without salt feedstock, reshaping process economics for ingredient manufacturers.
Water desalination anchors historical deployment. Specialty chemicals is expanding most quickly on purity premium capture.
End User:
Customer type determines procurement sophistication, with municipal buyers emphasizing certification compliance and industrial operators prioritizing total cost of ownership.
- Municipal Water Treatment:City and regional water authorities procuring under public tender rules. NSF/ANSI 61 drinking water system certifications shape specifications, with approval timelines extending 18-24 months for new membrane polymers.
- Industrial:Chemical, pharmaceutical, and electronics manufacturers requiring high-purity process water. German industrial clusters along the Rhine corridor drive demand concentration, affected by REACH registration requirements for perfluorinated membrane polymers.
- Agriculture:Irrigation water desalination for high-value crop production. Israeli greenhouse operators deploy compact systems for brackish groundwater treatment, constrained by energy cost sensitivity.
- Research Institutions:Universities and national laboratories conducting membrane development and process optimization. Japanese electrochemist talent scarcity outside established engineering centers limits specialized fouling mitigation expertise.
Industrial end users dominate revenue contribution. Municipal water treatment is gaining share fastest on Green Deal funding acceleration.
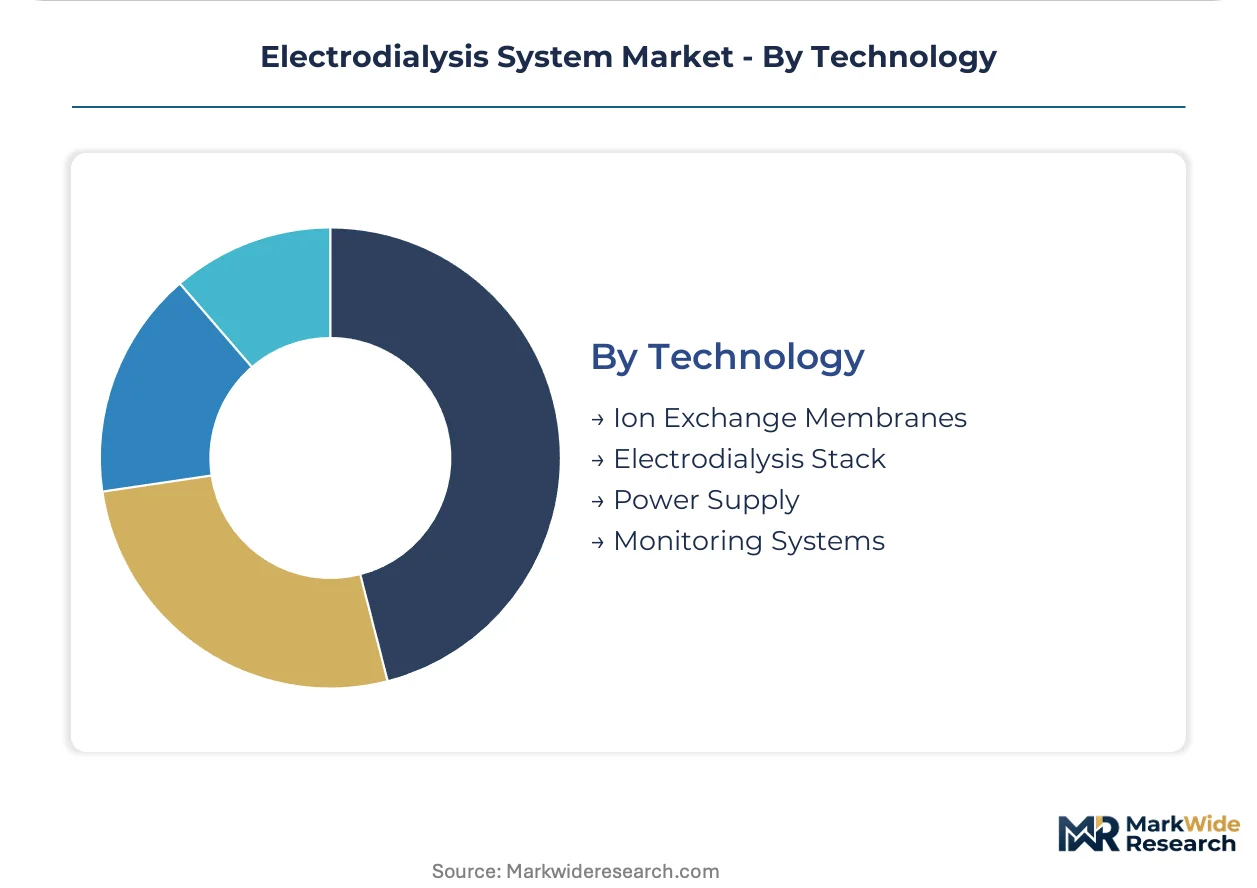
Technology:
Technology stack segmentation separates hardware components with divergent replacement cycles and supplier qualification barriers.
- Ion Exchange Membranes:Perfluorinated and hydrocarbon-based selective barriers with nanometer-scale pore architecture. Monovalent-selective anion exchange variants displace conventional stacks in lithium refining, with production concentration in Japan and Germany creating single-source vulnerability.
- Electrodialysis Stack:Modular membrane-cell assemblies with alternating cation and anion exchange layers. PCCell GmbH leverages German engineering base to dominate high-performance stack supply for European desalination projects.
- Power Supply:Rectifier systems delivering direct current below 2 V per cell pair. Efficiency gains in power electronics defend capital project returns against competing reverse osmosis bids.
- Monitoring Systems:Remote voltage, current, and fouling detection platforms. Service unbundling across North American municipal contracts fragments traditional equipment-plus-maintenance agreements, opening entry points for specialized monitoring suppliers.
Ion exchange membranes capture the highest replacement revenue. Monitoring systems is climbing the share rankings on digital service unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water treatment authorities and chemical processors in Germany, the United States, Japan, China, and India concentrate procurement activity for electrodialysis membrane stacks and integrated systems.
Germany
Industrial clusters along the Rhine corridor demand high-purity process water for pharmaceutical and specialty chemical manufacturing. The EU F-Gas Regulation accelerates displacement of thermal evaporators with electrodialysis architectures. BASF and Bayer facilities in Ludwigshafen and Leverkusen specify German-engineered membrane stacks for zero-liquid-discharge compliance.
United States
California water districts disaggregate procurement across membrane stacks, power electronics, and remote monitoring services. EPA effluent limitation guidelines compress project timelines for municipal brackish water treatment. Texas food processors face evaporative discharge restrictions, rotating capital toward closed-loop recovery systems in the Permian Basin.
Japan
Perfluorinated ion-exchange membrane production concentrates among specialized chemical manufacturers serving battery material and electronics sectors. METI industrial water recycling directives tighten discharge standards for semiconductor fabrication. Osaka-based engineering centers retain scarce electrochemist talent for fouling mitigation expertise.
China
Battery-grade lithium hydroxide specifications drive adoption of monovalent-selective anion exchange membranes for brine refining. Dual carbon goals and MEE wastewater discharge standards pressure chemical processors toward energy-efficient separation. Qinghai and Sichuan salar operators deploy hybrid electrodialysis-crystallization systems for direct lithium extraction.
India
PLI scheme incentives for advanced chemistry cell manufacturing create first-mover openings for brine concentration technology suppliers. Central Electricity Authority water reuse mandates affect thermal power plant cooling systems. Gujarat and Maharashtra industrial corridors evaluate compact electrodialysis units for textile dyehouse effluent recovery.
Electrodialysis System Market Competitive Landscape
Player mix skews toward European membrane engineering specialists and North American integrated water service providers, with Japanese material suppliers anchoring the ion-exchange membrane tier. Strategic archetypes separate into stack fabricators with captive membrane supply, hybrid system integrators combining electrodialysis with crystallization, and unbundled service providers capturing remote monitoring revenue. Dominant competitive moves include backward integration into perfluorinated polymer production and geographic expansion through local assembly partnerships.
Within the European engineering tier, PCCell GmbH and Eurodia Industrie exemplify stack fabrication specialists leveraging regional chemical industry relationships. Saltworks Technologies occupies a position among hybrid system integrators, while Evoqua Water Technologies LLC anchors the North American service-contract segment. ASTOM Corporation and AGC Engineering Co., Ltd. sit within the Japanese material-and-component supply tier. These five names represent the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| PCCell GmbH |
| Saltworks Technologies |
| ASTOM Corporation |
| MEGA a.s. |
| Evoqua Water Technologies LLC |
| GE Corporation |
| Eurodia Industrie |
| AGC Engineering Co., Ltd. |
| SnowPure, LLC |
| Others |
Pricing and Supply Chain Analysis
Monovalent-selective anion exchange membrane substitution for conventional electrodialysis stacks is redrawing supply geography toward Japanese and German polymer producers while compressing pricing economics for incumbent membrane assemblers facing raw material indexation clauses.
Pricing Analysis
Cost-plus contracts with perfluorinated polymer indexation dominate membrane stack procurement, linking final pricing to fluorochemical feedstock benchmarks. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and municipal-grade certification levels separates premium cGMP-certified systems from standard brackish water configurations. Cost compression in municipal-grade stacks is intensifying because California water districts disaggregate procurement across component suppliers. Industrial chemical processors show lowest price sensitivity due to zero-liquid-discharge compliance deadlines, while agricultural buyers in Israel and Australia exhibit highest sensitivity to energy-linked operating cost escalations.
Supply Chain Analysis
Inbound logistics costs from Yokohama and Hamburg ports constrain just-in-time membrane delivery to European and North American stack assemblers, with container availability fluctuations amplifying inventory carrying requirements. Perfluorinated ion-exchange membrane production concentrates in Japan and Germany, while electrodialysis stack fabrication clusters in Germany and the Czech Republic. Supply chains draw from specialty fluoropolymer resins, precision-machined titanium electrodes, and rectifier power electronics. Single-source vulnerability in high-performance membrane polymers creates structural risk for stack manufacturers dependent on Asahi Kasei or Chemours supply allocations. Distribution runs through direct OEM contracts for large industrial projects and specialized water treatment distributors for municipal and compact system segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrodialysis system market is exiting a capital expenditure trough as EU F-Gas Regulation compliance deadlines and battery-grade lithium refining capacity builds trigger replacement cycle acceleration.
For Market Incumbents: Compound membrane replacement revenue through captive service contracts spanning remote monitoring and predictive fouling analytics. Deepen backward integration into perfluorinated polymer production to defend margin position against Japanese material suppliers. Prioritize NSF/ANSI 61 certification maintenance for municipal procurement eligibility as regulatory timelines extend. For New Entrants and Emerging Players: Lead with compact system configurations for India's textile dyehouse effluent recovery segment, where PLI scheme incentives and CEA water reuse mandates concentrate demand. Target Gujarat and Maharashtra industrial corridors with skid-mounted pre-engineered units. Pursue local assembly partnerships to circumvent inbound logistics bottlenecks and tariff exposure. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid system integrators combining electrodialysis with crystallization capability for lithium brine refining. Long-term viability hinges on exposure to battery material supply chains rather than municipal water treatment cyclicality. Monitor South American salar operator capital commitment announcements as inflection indicator for hybrid system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Perfluorinated Polymers | Captive membrane supply reduces exposure to Asahi Kasei and Chemours allocation constraints. |
| Hybrid System Platform Development | Integrated electrodialysis-crystallization configurations capture lithium brine refining premium pricing. |
| Remote Monitoring Service Unbundling | Digital service separation opens recurring revenue streams as California districts fragment procurement. |
| NSF/ANSI 61 Certification Investment | Drinking water system approvals secure municipal eligibility despite 18-24 month timeline delays. |
| Local Assembly Partnership Expansion | Regional fabrication mitigates Yokohama-Hamburg logistics chokepoints and tariff exposure. |
Research Methodology
Cross-validation between executive interviews at membrane stack fabricators and regulatory filing analysis anchors the qualitative findings. Primary fieldwork encompassed plant engineers at German chemical processors, procurement leads at California water districts, technical directors at lithium brine operators, and aftermarket service heads at integrated water treatment providers. Secondary validation drew from EPA effluent limitation guidelines, EU F-Gas Regulation implementation documents, METI industrial water recycling directives, and REACH registration databases for perfluorinated polymers. Bottom-up stack demand modeling triangulated against top-down municipal capital expenditure surveys.
Sensitivity analysis around membrane replacement cycle assumptions and power supply efficiency gains informs the analytical framework. Segmentation dimensions span operational architecture, application purity requirements, end-user procurement sophistication, and technology component replacement cycles. CAGRs derive from installed base growth rates and average selling price trajectory modeling across the projection horizon. Industry-specific inputs include lithium carbonate specification tightening timelines and EU Green Deal funding disbursement velocity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of F-Gas limits and battery-grade lithium purity standards would require recalibration. Forecasts reflect assumptions regarding membrane fouling mitigation technology maturation and power electronics cost curves. Geopolitical disruption to Japanese fluoropolymer supply or abrupt reverse osmosis efficiency breakthroughs represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
North America Power Inverter Market