
 Power Strip Market | 2026-2036
Power Strip Market Size, Share, and Industry Trends Forecast 2026-2036
Power Strip Market Intelligence
The gap between basic surge suppression and intelligent load management is narrowing as semiconductor costs fall and embedded connectivity becomes standard. Schneider Electric leverages its building-automation heritage to bundle power strips into integrated energy-management systems for commercial clients. Belkin International anchors its position through consumer-channel dominance and accessory ecosystems that extend beyond power delivery into device charging and home networking.
A power strip is an electrical distribution device comprising multiple socket outlets mounted on a common housing, typically rated for 15-20 ampere circuits with copper bus bars and thermoplastic or metal enclosures designed for overcurrent protection and spatial consolidation of plug-in loads. Surge protectors and smart power strips now command the strongest margin pools as buyers trade up from commodity multi-outlet strips toward connected units with energy-monitoring chipsets and wireless control protocols. USB power strips represent the fastest-growing product type, driven by proliferation of USB-C powered consumer electronics and declining reliance on wall-wart adapters in residential and educational settings.
UL standards in the United States, CE marking under the EU Low Voltage Directive, and China's GB standards enforced by SAMR collectively dictate enclosure flame ratings, cord gauge minimums, and surge-suppression joule thresholds that determine market access. The EU F-Gas Regulation and evolving Ecodesign requirements are pushing manufacturers toward halogen-free plastics and more efficient standby circuitry, reshaping material selection and design validation cycles. Stakeholders must monitor how interoperability standards for smart home protocols reshape which connectivity modules get designed into next-generation power distribution accessories.
Market Dynamics
The power strip market is being restructured by the convergence of embedded connectivity and tightening standby power mandates, as semiconductor integration transforms commodity electrical accessories into networked energy nodes.
Growth Catalysts
- Residential smart home installations:Homeowners in China, the United States, and Germany are replacing legacy multi-outlet strips with intelligent load management systems that enable remote switching and consumption tracking.
- EU Ecodesign Directive:Mandatory standby power limits are forcing manufacturers to redesign power supply circuits, creating replacement demand for non-compliant legacy inventory across European distribution channels.
- USB-C standardization:The universal charging protocol is collapsing demand for proprietary wall-wart adapters, driving educational institutions and hospitality operators toward integrated USB power strips.
Market Restraints
- Copper price volatility:Bus bar and conductor materials represent substantial input cost exposure, compressing margins for manufacturers without long-term commodity hedging arrangements.
- Supply concentration in Chinese semiconductor packaging:Connectivity chipsets and energy-monitoring ASICs flow through a narrow supplier base, creating vulnerability to regional logistics disruptions.
- Technical limitation in legacy circuit compatibility:Smart power strips require neutral wire presence for powered electronics, excluding installation in older residential electrical systems lacking grounded three-conductor wiring.
Strategic Opportunities
- Underpenetrated commercial building retrofits:Small and medium enterprises in Germany and the United States remain reliant on basic surge suppressors, presenting white space for managed power distribution as a service.
- Regulatory tailwind from F-Gas Regulation:Halogen-free plastic mandates are accelerating material substitution, rewarding early movers with compliant enclosure designs ahead of enforcement deadlines.
- Technology convergence of power delivery and home networking:Power strips integrating Wi-Fi mesh nodes or Powerline Ethernet are capturing shelf space in consumer electronics retail.
Industry Challenges
- Certification timeline compression:UL 1363 and IEC 61643 surge testing protocols require extended validation cycles, delaying product launches as standards evolve for connected device categories.
- Integration complexity with building management systems:Facility managers demand BACnet or Modbus protocol compatibility, forcing firmware development investments beyond traditional electrical accessory capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Strip Market |
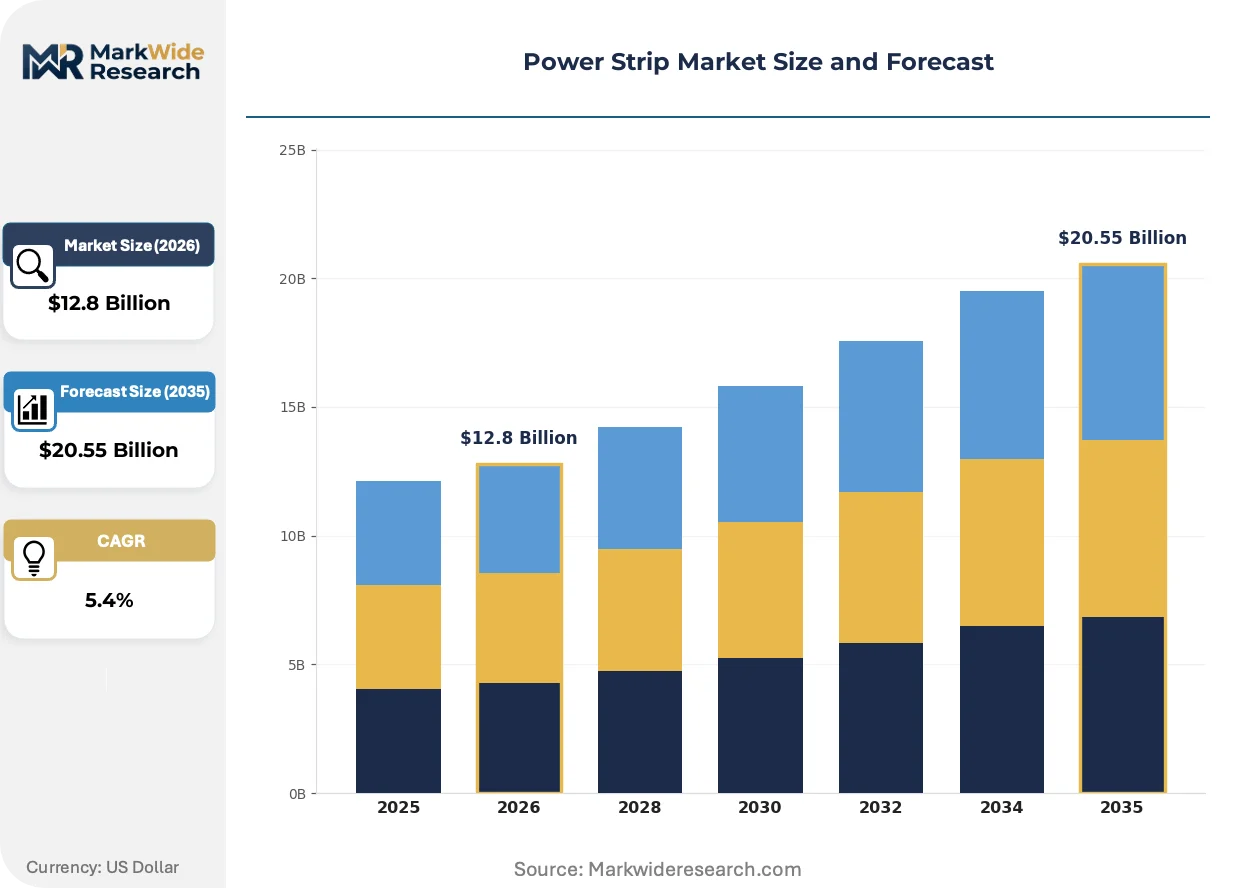
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surge Protectors, Smart Power Strips, Multi-Outlet Strips, USB Power Strips Material: Plastic, Metal, Fire-retardant Materials, Impact-resistant Materials Feature: Overload Protection, Energy Monitoring, Wireless Control, Child Safety Lock End User: Residential, Commercial, Industrial, Educational |
| Companies Covered | General Electric Company, Panasonic Corporation, Schneider Electric, Siemens, ABB, Belkin International, Leviton Manufacturing, Eaton, Legrand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Strip Market Strategic Shifts & Innovations
Product architecture is fragmenting along intelligence gradients, with semiconductor integration enabling functional expansion far beyond original power distribution purposes.
GaN (gallium nitride) switching technology is collapsing the physical volume required for high-wattage USB power delivery, enabling manufacturers to embed 100W charging ports within standard strip footprints without thermal compromise. Consumer electronics retailers are accelerating shelf rotation toward GaN-equipped models. The technology is collapsing the premium pricing tier that previously separated compact adapters from integrated strip solutions.
China's GB standards enforcement through SAMR is tightening flame-retardant specifications for thermoplastic enclosures, disqualifying legacy ABS formulations from market access. Manufacturers are accelerating halogen-free TPU and PC-ABS blend qualifications to maintain import eligibility. The regulatory pressure is most acute for exporters targeting residential channels where certification documentation faces heightened scrutiny.
Educational procurement officers are consolidating vendor relationships through cooperative purchasing agreements, displacing fragmented school-by-school acquisition patterns. Regional buying consortia in the United States are awarding multi-year contracts to suppliers offering energy-monitoring dashboards as standard. This concentration is most visible in public K-12 districts where facility budgets are centrally administered.
Power Strip Market Segmentation
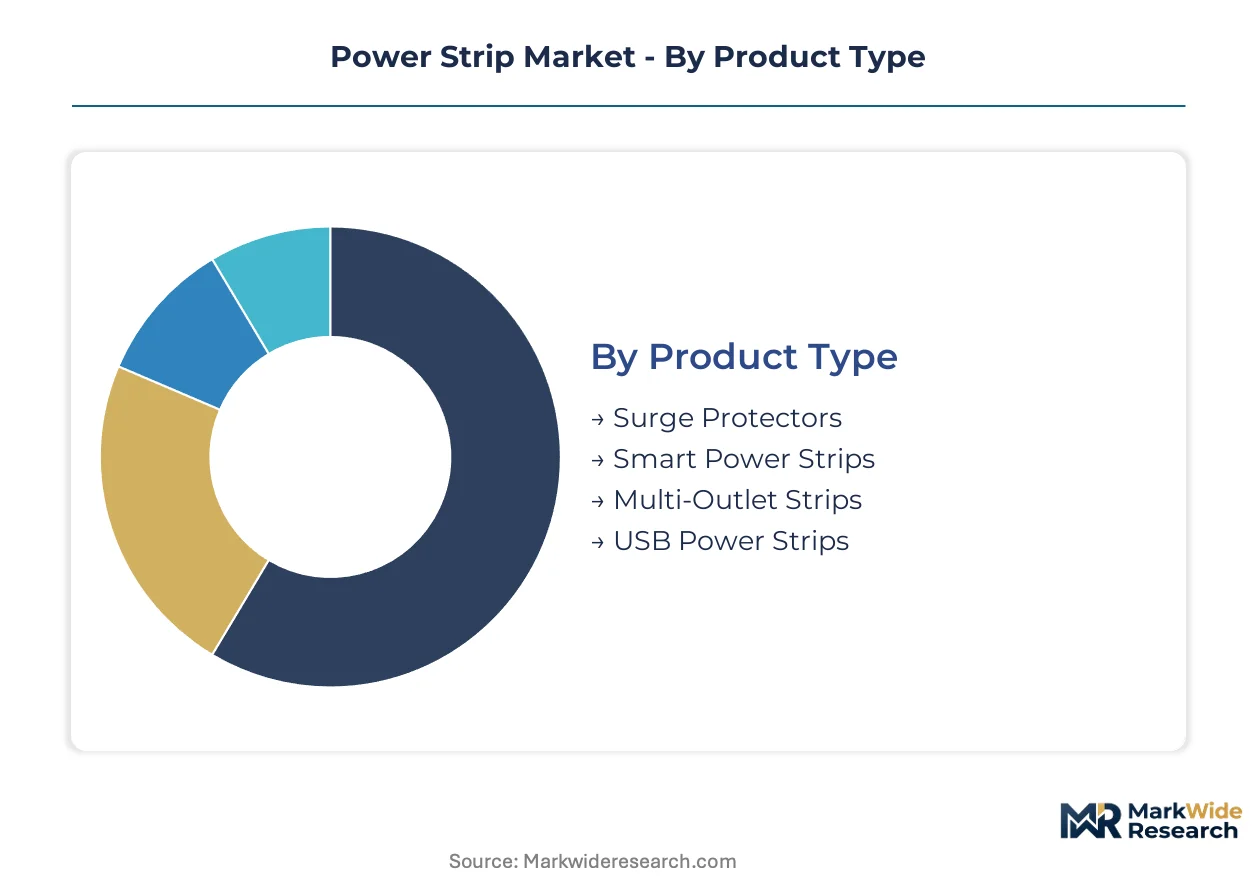
Power strip segmentation reflects divergent margin profiles across intelligence tiers and enclosure specifications. Semiconductor integration and regulatory material mandates are fragmenting what was historically a commoditized product category into distinct value pools with separate certification requirements and channel strategies.
Product Type:
Cost tier differentiation separates legacy commodity strips from connected units carrying embedded electronics and software stacks.
- Surge Protectors:Metal-oxide varistor arrays and gas discharge tubes shunt transient voltage spikes away from connected equipment. Residential buyers in the United States specify joule ratings above 2000 for home theater installations, while commercial procurement in Germany prioritizes IEC 61643-11 compliance for data center applications.
- Smart Power Strips:ARM-based microcontrollers and Wi-Fi/Bluetooth modules enable remote switching, scheduling, and consumption analytics through mobile applications. Demand concentrates in Chinese smart home ecosystems and US consumer electronics retail where utility rebate programs subsidize intelligent load management devices.
- Multi-Outlet Strips:Basic copper bus bar construction without surge suppression or connectivity features serves price-sensitive bulk procurement in hospitality and educational settings.
- USB Power Strips:Integrated buck converters and USB-C PD controllers eliminate wall-wart clutter for consumer electronics charging. Adoption accelerates in university dormitories and co-working spaces.
Surge Protectors hold installed capacity. USB Power Strips is rotating up the share rankings.
Material:
Application-driven enclosure specifications balance flame retardancy, mechanical durability, and electromagnetic shielding requirements.
- Plastic:Acrylonitrile butadiene styrene and polycarbonate blends dominate residential channels due to colorability and cost position. China's GB 4943.1 enforcement through SAMR is disqualifying halogen-containing formulations, forcing compound reformulation for export eligibility.
- Metal:Aluminum and steel housings provide electromagnetic interference shielding and physical vandalism resistance. Industrial facilities in Germany specify IP-rated metal enclosures for factory floor deployment where chemical exposure and impact damage threaten polymer integrity.
- Fire-retardant Materials:Phosphorus-based and nitrogen-based intumescent additives elevate UL 94 V-0 ratings without halogen content. Regulatory pressure from EU F-Gas Regulation and REACH restrictions is accelerating substitution in European-bound production.
- Impact-resistant Materials:Thermoplastic polyurethane overmolding and reinforced polyamide compounds withstand drop testing and crush loads for construction site and outdoor event applications.
Plastic maintains volume leadership. Fire-retardant Materials is climbing the fastest as compliance deadlines approach.
Feature:
Customer type determines which functional premiums command price realization versus which capabilities remain table stakes.
- Overload Protection:Thermal circuit breakers and bimetallic strips interrupt current flow during sustained overcurrent conditions. Residential codes in the United States increasingly mandate integrated protection as a condition of insurance coverage.
- Energy Monitoring:Current transformers and hall-effect sensors feed real-time wattage data to smartphone dashboards. Commercial building managers in Germany deploy these strips for ISO 50001 energy management certification compliance.
- Wireless Control:Zigbee, Z-Wave, and Matter protocol stacks enable integration with broader smart home and building automation systems. Matter certification is becoming a gating factor for retail placement in North American consumer electronics channels.
- Child Safety Lock:Tamper-resistant shutter mechanisms block foreign object insertion into unused outlets. Educational procurement specifications in the United States require this feature for K-12 classroom installations.
Overload Protection holds installed capacity. Energy Monitoring is gaining share fastest among feature premiums.
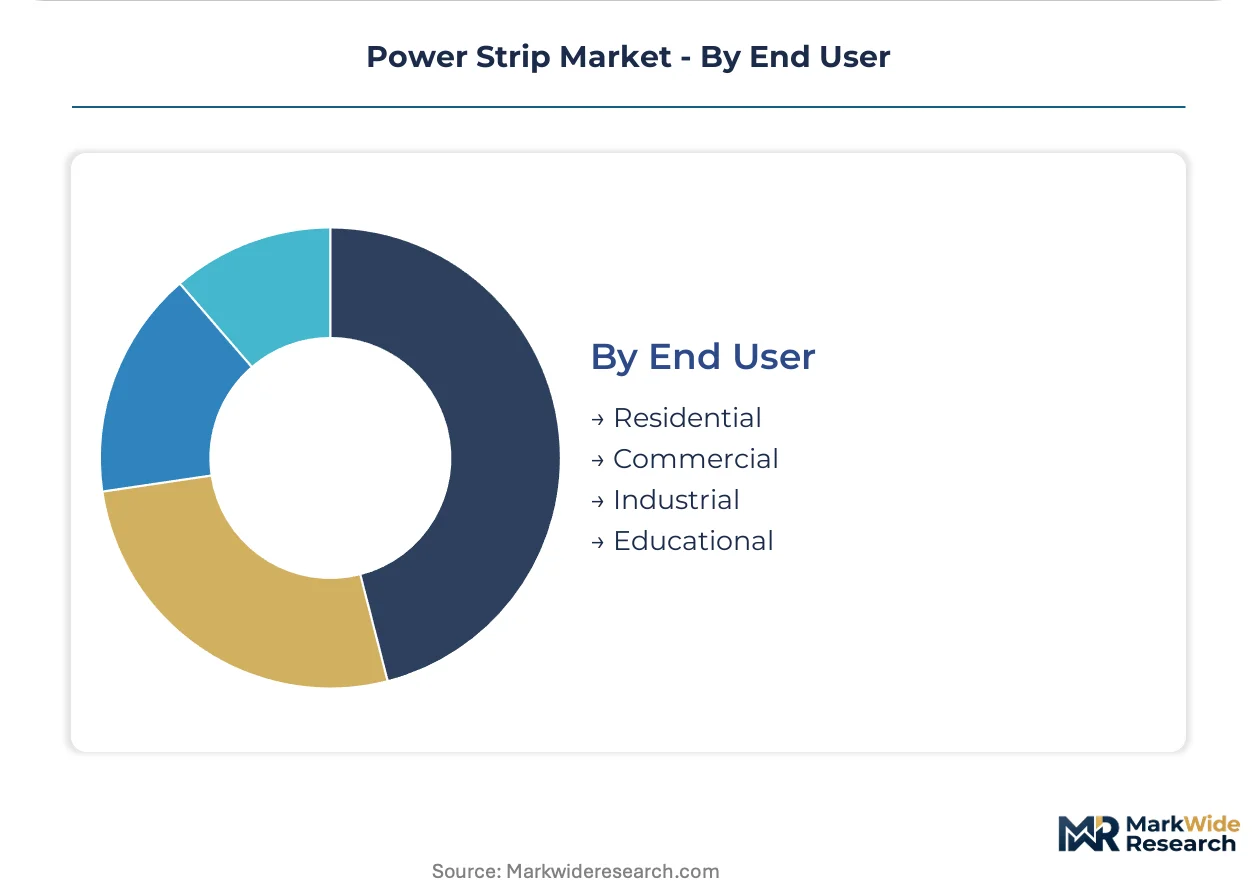
End User:
Volume concentration varies sharply across customer types with divergent replacement cycles, specification authority, and price elasticity.
- Residential:Individual homeowners purchase through retail and e-commerce with replacement driven by smart home upgrade cycles and USB-C device proliferation. Chinese consumers lead intelligent strip adoption through Xiaomi and Huawei ecosystem integration.
- Commercial:Facility managers and IT departments specify managed power distribution for office buildings, retail locations, and hospitality properties. German Mittelstand companies represent underpenetrated white space for power-as-a-service business models.
- Industrial:Heavy-duty specifications with high ampacity, extreme temperature tolerance, and chemical resistance serve manufacturing floors and outdoor installations. Metal enclosure requirements dominate this segment.
- Educational:Cooperative purchasing agreements and centralized facility budgets in US public school districts are consolidating vendor relationships toward suppliers offering energy dashboards and multi-year service contracts.
Residential holds installed capacity. Commercial is rotating up the share rankings as building automation penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential smart home adopters in China, the United States, and Germany drive replacement demand for legacy multi-outlet strips, while commercial facility managers in each market pursue energy-monitoring specifications for building automation integration.
China
Smart home ecosystem integration through Xiaomi and Huawei platforms accelerates intelligent power strip adoption in residential channels. SAMR enforces GB 4943.1 flame-retardant specifications that disqualify halogen-containing ABS formulations from import eligibility. Shenzhen and Dongguan manufacturing clusters concentrate semiconductor packaging and enclosure fabrication for export-bound production.
United States
Utility rebate programs subsidize intelligent load management devices, driving consumer electronics retail placement of connected strips. UL 1363 surge testing protocols mandate extended validation cycles for product launches. The Southeast and Texas corridors host distribution centers serving bulk educational procurement through cooperative purchasing agreements.
Germany
Mittelstand companies represent underpenetrated white space for power-as-a-service business models in commercial building retrofits. The EU Ecodesign Directive enforces mandatory standby power limits, forcing circuit redesigns for European market access. Bavaria and North Rhine-Westphalia industrial zones concentrate metal enclosure fabrication for factory-floor specifications.
Japan
Consumer electronics retail channels prioritize compact GaN-equipped USB power delivery solutions for residential densification. METI efficiency standards tighten standby power thresholds for electrical accessories. The Kanto region around Tokyo anchors premium product development and certification laboratory capacity.
India
Educational institutions and co-working spaces drive USB-C integrated strip adoption as wall-wart adapter replacement accelerates. BIS certification requirements for electrical accessories create compliance barriers for unorganized sector imports. Maharashtra and Karnataka manufacturing corridors develop assembly capacity for price-sensitive multi-outlet strips.
Power Strip Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions defined by certification depth and connectivity integration. The vendor base fragments across consumer electronics retail, electrical wholesale, and direct commercial procurement channels with divergent margin structures. Three strategic archetypes dominate: diversified electrical equipment conglomerates with building-automation heritage, consumer-accessory specialists with ecosystem bundling capabilities, and regional fabricators serving price-sensitive bulk procurement. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure semiconductor supply and certification laboratory access.
Among diversified electrical equipment conglomerates, Schneider Electric and Siemens occupy positions exemplifying building-automation bundling strategies. Belkin International anchors the consumer-accessory specialist archetype through retail channel dominance and device-charging ecosystem extension. These three companies represent distinct competitive vectors: industrial system integration, consumer electronics retail placement, and smart home protocol interoperability.
| Leading Market Players |
|---|
| General Electric Company |
| Panasonic Corporation |
| Schneider Electric |
| Siemens |
| ABB |
| Belkin International |
| Leviton Manufacturing |
| Eaton |
| Legrand |
| Others |
Cost & Logistics Intelligence
Copper price volatility functions as the dominant risk vector, compressing margin structures across all intelligence tiers while simultaneously forcing geographic consolidation of bus bar fabrication toward hedged supplier networks in China and Vietnam. This commodity exposure dictates both the spread between premium GaN-equipped strips and economy multi-outlet units and the backward integration imperatives reshaping enclosure supply.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate procurement between enclosure fabricators and OEM assemblers, insulating neither party from spot market spikes. Price differentiation rests on certification grade—UL 1363 validation commands substantial premiums over basic CE-marked alternatives—and volume scale, with educational cooperative purchasing agreements extracting double-digit concessions. Pricing pressure stems from semiconductor cost deflation collapsing the premium attached to connectivity modules. Residential consumers through e-commerce channels exhibit highest price sensitivity, while German Mittelstand facility managers prioritize energy-monitoring specifications over unit economics.
Supply Chain Analysis
Upstream feedstock flows from Chilean copper concentrate through Chinese smelters to Dongguan and Shenzhen stamping operations, with secondary refining in Germany for European-bound metal enclosures. Thermoplastic resins draw from Saudi petrochemical complexes and South Korean polycarbonate producers, creating dual-source redundancy for flame-retardant formulations. Single-source vulnerability concentrates in ARM-based microcontroller packaging, where Taiwan and South Korea facilities anchor global capacity. Distribution runs through Shenzhen export hubs for consumer electronics retail, diverting to Hamburg and Rotterdam for European electrical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power strip market reads as a service-attach opportunity where energy-monitoring dashboards and multi-year facility management contracts expand recurring revenue faster than hardware replacement cycles.
For Market Incumbents: Entrench through captive supply of GaN semiconductor modules and certification laboratory partnerships that compress rival launch timelines. Schneider Electric and Belkin International must defend against white-label entrants from Shenzhen by locking Southeast distribution centers into exclusive logistics arrangements. Vertical integration into halogen-free compound formulation insulates margin position as EU F-Gas enforcement tightens.
For New Entrants and Emerging Players: Build out managed power distribution as a service targeting German Mittelstand commercial retrofits, the most penetrable white space where incumbent building-automation bundling remains thin. Educational procurement consortia in the United States present second-tier entry through cooperative purchasing agreements that favor energy-dashboard inclusion. Go-to-market execution should anchor on direct facility manager engagement rather than retail channel buildout.
For Investors and Strategic Acquirers: Specialist connectivity firmware developers with Matter protocol certification and BACnet integration capabilities represent the priority acquisition archetype for medium-term consolidation plays. Long-term viability hinges on semiconductor supply security and regulatory compliance velocity rather than manufacturing scale alone. Watch for BIS enforcement tightening in India as the inflection signal separating organized from unorganized sector competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Module Integration | Collapses thermal footprint for 100W USB-C delivery, enabling premium tier repositioning in consumer electronics retail. |
| Matter Protocol Certification | Secures placement in North American smart home ecosystems where interoperability gates shelf access. |
| Halogen-Free Material Transition | Preempts EU F-Gas and China GB 4943.1 enforcement deadlines, preserving export eligibility. |
| Energy Dashboard Development | Captures ISO 50001 compliance budgets from German commercial building managers pursuing certification. |
| Cooperative Purchasing Alignment | Locks multi-year vendor relationships with US K-12 districts consolidating procurement through regional consortia. |
Research Approach
A standing panel of electrical accessory procurement managers, smart home platform engineers, semiconductor packaging specialists, and facility management consultants provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation through UL certification databases, SAMR GB standards filings, EU Ecodesign Directive implementation notices, and customs trade records. Bottom-up unit shipment modeling triangulated against top-down value estimates derived from channel revenue disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product intelligence tier, enclosure material compliance grade, end-user vertical, and regional regulatory cluster. CAGRs emerged from fitted growth curves applied to replacement cycle data and smart home penetration trajectories. Forecast inputs incorporated utility rebate program budgets, semiconductor cost curves, and copper futures market sentiment.
Sensitivities concentrate around copper price spike magnitude, Matter protocol adoption velocity, and BIS certification timeline compression in India. Forecasts reflect documented assumptions regarding regulatory enforcement schedules and technology substitution rates. Cross-checking against IEA building energy efficiency benchmarks and UL certification issuance statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
AC Residential Switchgear Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market