
 Global Electric Motors Household Appliances Market | 2026-2036
Global Electric Motors Household Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Motors Household Appliances Market Intelligence
The capital-intensity divergence between integrated motor manufacturers and component assemblers is rotating competitive advantage toward firms with in-house magnet and lamination capabilities. Nidec Corporation leverages its vertical control over rare-earth magnet supply chains to sustain cost leadership in brushless DC platforms. Siemens AG anchors its position through precision winding automation and energy-efficiency certifications that dominate European OEM procurement.
Electric motors for household appliances convert electrical energy into mechanical torque through electromagnetic induction, with brushless DC variants employing permanent magnet rotors and electronic commutation to achieve efficiency ratings exceeding ninety percent in variable-speed refrigeration compressors. AC induction motors still occupy the largest installed base across washing machines and air conditioners due to mature supply chains and lower unit costs, though permanent magnet synchronous designs are capturing margin pools in premium appliance tiers where energy labeling drives consumer choice. Stepper motor applications remain concentrated in precision dosing systems and smart appliance actuators where positional accuracy commands price premiums.
The US DOE appliance efficiency standards, the EU Ecodesign Directive, and China's GB motor efficiency grades collectively mandate minimum performance thresholds that disqualify conventional induction motors from new product platforms. REACH restrictions on rare-earth processing and the EU F-Gas Regulation linking compressor motor efficiency to refrigerant phase-downs are reshaping magnet sourcing and thermal design requirements. Stakeholders must monitor regulatory divergence between efficiency-first jurisdictions and cost-sensitive emerging markets when allocating R&D and manufacturing footprint decisions.
Market Dynamics
The permanent magnet motor transition is compressing incumbent induction architectures while rare-earth supply concentration in China creates procurement leverage for vertically integrated manufacturers over component assemblers.
Growth Catalysts
- EU Ecodesign Directive efficiency mandates:Minimum performance thresholds for residential refrigeration compressors are disqualifying conventional induction motors from new product platforms, forcing OEM redesign cycles.
- Brushless DC motor technology:Electronic commutation systems achieving efficiency ratings exceeding ninety percent in variable-speed applications are capturing design wins across climate-control equipment.
- China's GB motor efficiency grades:Domestic appliance manufacturers face tiered compliance deadlines that accelerate permanent magnet synchronous motor adoption in washing machines and air conditioners.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings concentrate input risk for motor manufacturers lacking captive magnet supply or long-term offtake agreements.
- REACH restrictions on rare-earth processing:European chemical registration requirements are creating compliance friction for magnet sourcing, extending qualification timelines for new motor platforms.
- AC induction motor installed base:Mature supply chains and lower unit costs in washing machines sustain incumbent technology preference among cost-optimized OEM tiers.
Strategic Opportunities
- India appliance electrification:Rising household penetration of refrigerators and air conditioners creates demand for high-efficiency compressor motors as grid infrastructure expands.
- Smart appliance actuator convergence:Integration of stepper motors with IoT-enabled dosing systems opens precision control applications in connected laundry and kitchen equipment.
- US DOE appliance efficiency standards:Successive tightening of federal minimum efficiency requirements creates regulatory tailwind for permanent magnet motor substitution in residential HVAC.
Industry Challenges
- Precision winding automation skill scarcity:Manufacturing engineers with expertise in automated coil insertion and tension control for high-slot-fill permanent magnet motors command wage premiums that constrain capacity expansion.
- Dual certification timeline compression:Simultaneous UL and CE mark pursuit for new motor platforms extends time-to-revenue as test protocols diverge on thermal cycling and insulation endurance.
- Legacy inverter compatibility:Retrofitting permanent magnet motors into existing appliance control architectures requires firmware recalibration that fragments engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Motors Household Appliances Market |
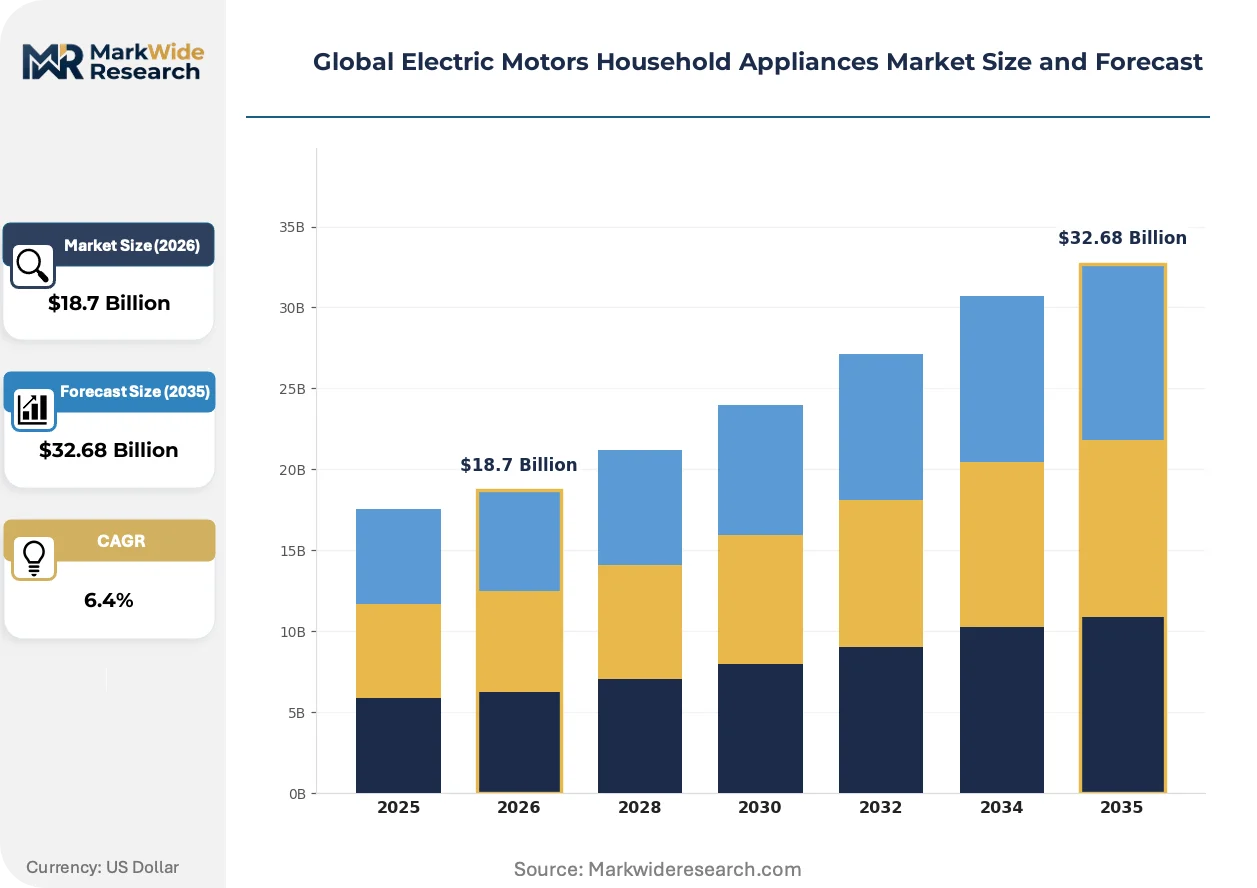
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Universal Motors, Brushless DC Motors, Stepper Motors Technology: Induction, Synchronous, Permanent Magnet, Switched Reluctance, Hysteresis Application: Refrigerators, Washing Machines, Air Conditioners, Vacuum Cleaners, Blenders End User: Residential Consumers, Commercial Facilities, Hospitality Sector, Educational Institutions |
| Companies Covered | ABB Ltd., ebm-papst, Nidec Corporation, AMETEK Inc., Regal Rexnord Corporation, Johnson Electric Holdings Limited, Panasonic Corporation, MinebeaMitsumi Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Motors Household Appliances Market Strategic Shifts & Innovations
Motor architecture is splitting along efficiency-performance axes as regulatory minimums harden and premium tiers chase variable-speed optimization, with supply chain control over magnetic materials becoming the decisive competitive variable.
Permanent magnet synchronous motor technology is bifurcating the residential compressor market. These motors employ rare-earth rotor magnets and field-oriented control algorithms to deliver part-load efficiency gains unattainable by induction designs. European OEM procurement specifications now mandate permanent magnet platforms for A+++ energy-labeled refrigeration, compressing induction motor share to economy-tier replacements and emerging market exports.
The EU F-Gas Regulation is linking compressor motor efficiency to refrigerant phase-down schedules. Lower-global-warming-potential alternatives like R600a and R290 demand optimized thermal management that permanent magnet motors provide through variable-speed operation. US OEMs serving export markets are pre-emptively adopting European efficiency benchmarks to maintain platform commonality, accelerating technology transfer across regulatory jurisdictions.
Appliance OEM sourcing departments are consolidating motor supplier rosters to capture volume-scale pricing and technical integration support. Long-term agreement structures with Nidec, Siemens, and specialized wound-field manufacturers are displacing spot procurement for compressor and fan motor categories. This concentration is most visible in Germany and the United States, where procurement teams prioritize single-source relationships for brushless DC platforms requiring joint firmware development.
Global Electric Motors Household Appliances Market Segmentation
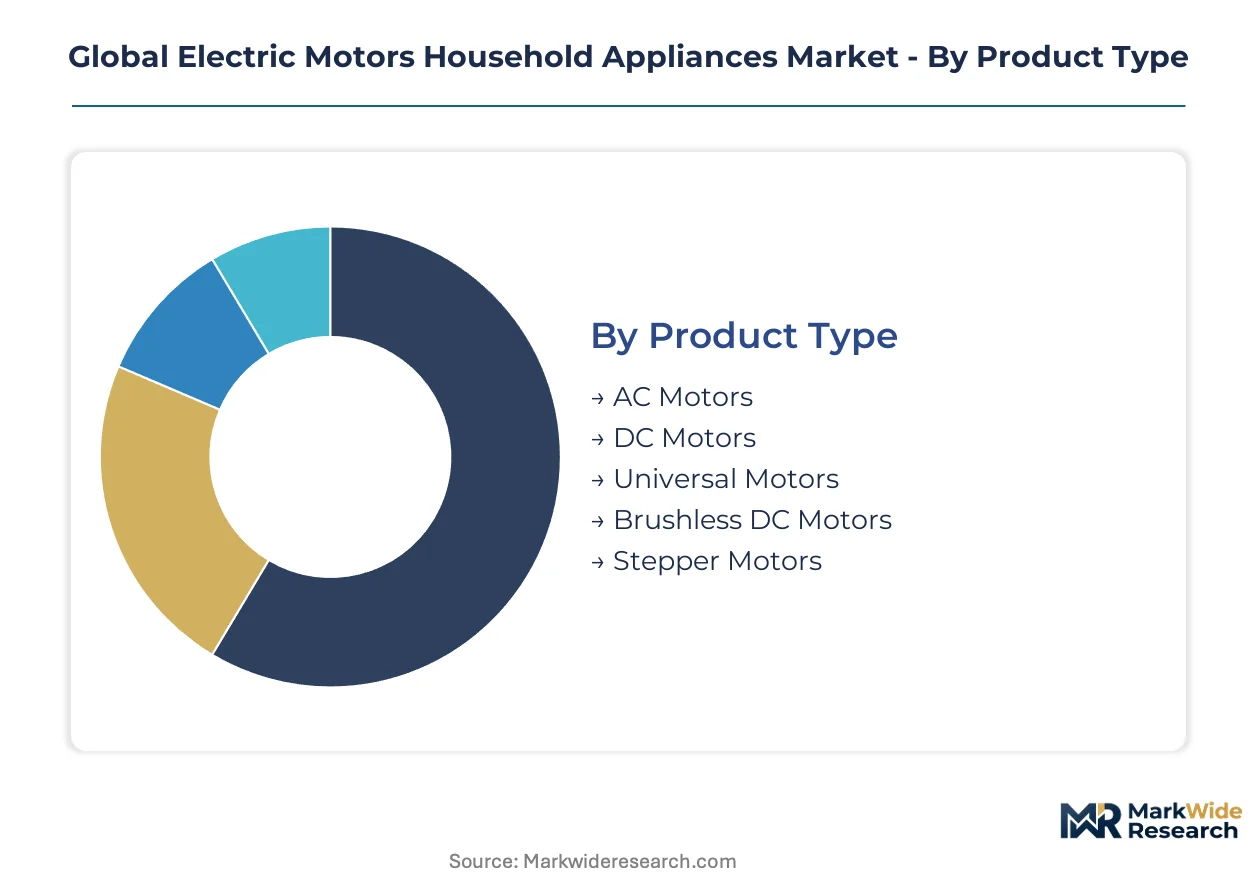
Segmentation in household appliance motors tracks how efficiency regulations and channel structures reshape procurement decisions. OEMs route high-efficiency platforms through premium retail chains while cost-optimized variants flow through builder-grade and replacement channels.
Product Type:
Channel mix varies sharply by motor architecture, with brushless DC and stepper motors flowing through OEM direct procurement while AC and universal motors dominate aftermarket and white-label supply chains.
- Brushless DC Motors:Permanent magnet rotors with electronic commutation achieve efficiency ratings exceeding ninety percent in variable-speed refrigeration compressors. Demand concentrates in European A+++ labeled appliances and US DOE-compliant HVAC systems where efficiency mandates disqualify induction alternatives.
- AC Motors:Single-phase induction designs with squirrel-cage rotors maintain cost leadership in washing machine agitator drives and fixed-speed fan applications. Volume remains anchored in emerging market OEM tiers and replacement part distribution where procurement prioritizes unit economics over efficiency premiums.
- DC Motors:Brushed commutator architectures serve low-torque auxiliary functions in appliance control systems and damper actuators.
- Universal Motors:Series-wound designs with high starting torque dominate vacuum cleaner and blender categories where compact size and speed variability outweigh efficiency concerns.
- Stepper Motors:Hybrid permanent magnet constructions enable precision dosing in smart appliance actuators and connected laundry systems.
By volume, AC motors lead. By growth pace, brushless DC is ahead.
Technology:
Cost tier alignment separates mature induction platforms from premium permanent magnet and emerging switched reluctance architectures targeting efficiency thresholds.
- Permanent Magnet:Rare-earth rotor magnets with field-oriented control deliver part-load efficiency gains unattainable by induction designs. European OEM specifications now mandate permanent magnet platforms for A+++ refrigeration, compressing induction share to economy-tier replacements.
- Induction:Mature squirrel-cage designs with laminated steel stators sustain lowest unit costs across washing machine and air conditioner installed bases. Procurement from China and India favors induction for cost-optimized OEM tiers despite efficiency penalties.
- Synchronous:Reluctance-assisted designs bridge efficiency gaps in mid-tier climate-control equipment where permanent magnet cost premiums encounter resistance.
- Switched Reluctance:Magnet-free rotors with salient pole geometry attract R&D investment from manufacturers seeking rare-earth supply chain independence.
- Hysteresis:Specialized synchronous designs serve precision timing applications in appliance control subsystems with minimal market penetration.
Permanent magnet commands the highest margins. Switched reluctance is expanding most quickly as magnet cost volatility intensifies.
Application:
Geographic concentration of appliance manufacturing determines motor specification regionalization, with European and North American platforms diverging from emerging market designs.
- Refrigerators:Compressor motors face the steepest efficiency mandates under EU Ecodesign Directive and US DOE standards. Variable-speed permanent magnet designs now dominate new platform development in Germany, the United States, and Japan.
- Air Conditioners:Outdoor unit fan motors and compressor drives split between induction legacy platforms and permanent magnet inverter-ready designs. China's GB efficiency grades accelerate permanent magnet adoption in domestic manufacturing.
- Washing Machines:Drum drive motors retain induction dominance in cost-sensitive markets while direct-drive permanent magnet platforms capture premium European and Korean OEM specifications.
- Vacuum Cleaners:Universal motor prevalence persists due to high-speed requirements and compact form factors, though brushless DC entrants target cordless battery-powered segments.
- Blenders:Universal and DC motor mixes serve speed-variable food processing with minimal efficiency regulation pressure.
Refrigeration applications lead technology transition. Air conditioning is gaining share fastest as heat pump electrification accelerates.
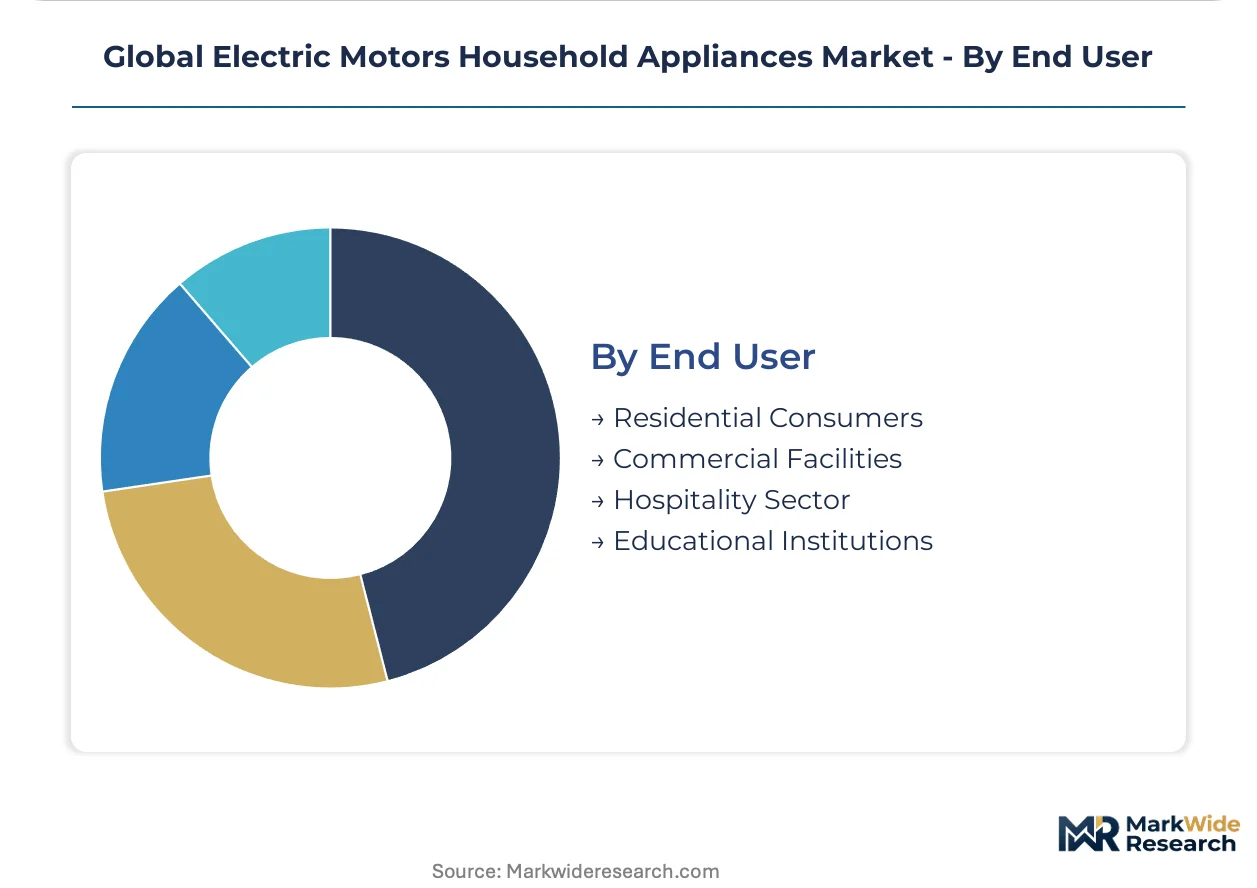
End User:
Customer type segmentation tracks procurement scale and specification authority, with residential consumers exercising choice through energy labeling while institutional buyers negotiate direct OEM relationships.
- Residential Consumers:Individual households select appliances based on energy label visibility and retail price positioning. EU A+++ and US ENERGY STAR certifications drive permanent magnet motor preference in replacement purchases.
- Commercial Facilities:Laundromats, multi-unit residential operations, and food service establishments prioritize lifecycle cost over first cost. Procurement teams specify permanent magnet inverter-driven systems for high-utilization equipment.
- Hospitality Sector:Hotel and restaurant chains negotiate fleet-scale appliance procurement with efficiency performance guarantees embedded in service contracts.
- Educational Institutions:University and school district purchasing cooperatives balance capital budget constraints against sustainability procurement policies.
Residential channels move the highest unit volumes. Commercial facilities are expanding fastest as service-contract pricing models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with European buyers accepting efficiency premiums and emerging market purchasers prioritizing unit economics. Germany and the United States absorb technology cost premiums through regulatory compliance and energy labeling visibility. China's domestic market splits between coastal efficiency mandates and inland price sensitivity.
United States
Residential HVAC electrification and heat pump retrofits drive permanent magnet motor procurement for compressor and fan applications. The US DOE appliance efficiency standards mandate successive efficiency threshold increases that disqualify induction motor platforms from new product development. Manufacturing clusters in the Midwest and Southeast concentrate motor assembly operations serving domestic OEMs and export markets.
Germany
Premium appliance OEMs specify A+++ energy-labeled refrigeration platforms that mandate brushless DC compressor motors with field-oriented control. The EU Ecodesign Directive and F-Gas Regulation impose simultaneous efficiency and refrigerant phase-down requirements that reshape thermal design specifications. Industrial concentration in Baden-Württemberg and Bavaria hosts precision winding automation and magnet integration facilities.
China
Domestic appliance manufacturing scale and GB motor efficiency grades accelerate permanent magnet synchronous motor adoption in washing machines and air conditioners. The MIIT dual carbon goals and tiered compliance deadlines force domestic OEMs toward variable-speed platforms. Manufacturing gravity concentrates in the Yangtze River Delta and Pearl River Delta where magnet processing and motor assembly integrate.
Japan
Direct-drive permanent magnet motor platforms capture premium washing machine specifications from Korean and Japanese OEMs targeting efficiency differentiation. METI energy conservation standards and JIS certification requirements maintain technical barriers for imported motor platforms. Industrial clusters in Nagoya and Osaka anchor precision manufacturing for compressor and fan motor categories.
India
Rising household refrigerator and air conditioner penetration creates demand for high-efficiency compressor motors as grid infrastructure expands into tier-two and tier-three cities. BIS efficiency labeling and state-level electricity subsidy reforms nudge procurement toward permanent magnet platforms despite first-cost premiums. Manufacturing investment concentrates in Gujarat and Maharashtra where domestic OEMs and contract assemblers scale motor production.
Global Electric Motors Household Appliances Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with vertical control over magnet supply chains and precision winding automation determining margin capture. The market structure rewards backward integration into rare-earth processing and lamination stamping while penalizing component assemblers exposed to input volatility. Three archetypes dominate: magnet-integrated Japanese conglomerates, European precision automation specialists, and Chinese scale manufacturers. Competitive moves center on long-term offtake agreements for magnet supply and joint firmware development with appliance OEMs.
Within the integrated tier, Nidec Corporation and Siemens AG anchor distinct geographic and technical positions. Nidec exemplifies magnet supply chain verticality, while Siemens represents European precision automation and certification dominance. Johnson Electric Holdings Limited occupies a specialist position in precision actuator and stepper motor applications for smart appliance convergence. These three companies illustrate how competitive advantage flows from supply chain control rather than assembly scale alone.
| Leading Market Players |
|---|
| ABB Ltd. |
| ebm-papst |
| Nidec Corporation |
| AMETEK Inc. |
| Regal Rexnord Corporation |
| Johnson Electric Holdings Limited |
| Panasonic Corporation |
| MinebeaMitsumi Inc. |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for rare-earth magnet supply lock in both procurement access and cost visibility for motor manufacturers serving EU Ecodesign Directive and US DOE compliance deadlines. These contract structures insulate vertically integrated firms from neodymium price swings while exposing component assemblers to spot market volatility.
Pricing Analysis
After-sales service revenue from replacement compressor motors and extended maintenance contracts drives lifetime value capture for OEM motor suppliers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by efficiency certification grade and volume commitment. Pricing pressure stems from REACH compliance costs and rare-earth processing qualification timelines that extend new platform development cycles. Emerging market OEM tiers exhibit highest price sensitivity, while European A+++ appliance manufacturers accept efficiency premiums.
Supply Chain Analysis
Rare-earth magnet processing concentration in China's Jiangxi and Inner Mongolia provinces creates single-source vulnerability for permanent magnet motor production. Motor manufacturing draws from neodymium-iron-boron magnets, silicon steel laminations, and copper winding materials. Tariff exposure on Chinese magnet exports threatens cost structures for non-integrated assemblers. Distribution runs through OEM direct procurement channels for brushless DC platforms and aftermarket parts distributors for induction motor replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by appliance replacement demand following efficiency mandate tightening across major regulatory jurisdictions.
For Market Incumbents: Compound defensive positioning through backward integration into rare-earth magnet supply and precision winding automation capacity expansion in Germany or the United States. Nidec Corporation's captive magnet sourcing demonstrates how upstream control neutralizes input volatility threats from Chinese supply concentration. Certification investment in simultaneous UL and CE mark pursuit protects against dual-timeline compression risks. For New Entrants and Emerging Players: Lead with switched reluctance motor architectures targeting rare-earth supply chain independence as a differentiated value proposition. India's expanding refrigerator and air conditioner penetration offers the most penetrable geography where grid infrastructure growth supports efficiency premium acceptance. Joint firmware development partnerships with mid-tier appliance OEMs provide a viable go-to-market angle against entrenched supplier relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive magnet supply over component assemblers. Long-term viability across the next decade hinges on regulatory divergence between efficiency-first jurisdictions and cost-sensitive emerging markets. Acquisition targets should display precision winding automation capabilities and established European OEM procurement relationships. The signal to watch is EU F-Gas Regulation enforcement intensity linking compressor motor efficiency to refrigerant phase-down schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium sourcing insulates Nidec Corporation and integrated peers from Chinese export tariff exposure. |
| Precision Winding Automation Scale-Up | Automated coil insertion capacity expansion in Baden-Württemberg addresses skill scarcity constraining permanent magnet motor output. |
| Dual Certification Investment | Simultaneous UL and CE mark pursuit compresses time-to-revenue for brushless DC platforms serving transatlantic OEMs. |
| Joint Firmware Development Partnerships | Embedded control algorithm collaboration with appliance OEMs locks in single-source supplier status for inverter-ready motors. |
| Switched Reluctance R&D Expansion | Magnet-free rotor architectures attract investment from manufacturers seeking supply chain independence from Chinese rare-earth processing. |
Research Approach
Cross-validation between OEM procurement manager interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork engaged motor manufacturing executives, appliance platform engineers, rare-earth supply specialists, and aftermarket distribution heads across Germany, China, and the United States. Secondary validation drew from US DOE appliance standards documentation, EU Ecodesign Directive implementing measures, China MIIT GB efficiency grade publications, and SEC filings from listed motor manufacturers. Bottom-up unit shipment modeling and top-down market value reconciliation triangulate volume estimates.
Sensitivity analysis around rare-earth price scenarios and regulatory timeline assumptions stress-tests projection robustness across the analysis window. Segmentation modeling incorporates motor architecture type, magnet technology grade, application category, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves applied to efficiency mandate implementation schedules and appliance replacement cycle data. Compressor motor efficiency thresholds and heat pump electrification penetration serve as industry-specific demand drivers.
Underlying assumptions cover continued EU Ecodesign Directive enforcement, stable China rare-earth export policy, and US DOE standard ratchet mechanisms, with deviation risk concentrated in trade policy shifts and alternative motor technology breakthroughs. Practitioners should keep alternative scenarios live as REACH chemical registration requirements and F-Gas Regulation phase-down schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Refrigerator Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Built-In Hobs Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Australia Washing Machine Market