
 Built-In Hobs Market | 2026-2036
Built-In Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Built-In Hobs Market Outlook
European appliance manufacturing capacity is realigning toward induction-dominant output as gas infrastructure phases down. Bosch leverages its captive motor and power electronics supply to control cost curves in premium induction lines. Electrolux AB anchors Nordic and Baltic markets through localized assembly and cold-climate reliability engineering. Samsung competes on smart kitchen ecosystem integration, linking hobs to its broader connected appliance platform.
Built-in hobs are flush-mounted cooking surfaces installed directly into countertops, typically operating at power ratings from 1.2 kW to 3.7 kW per burner zone with ceramic glass, stainless steel, or enameled steel surface materials. Their primary purpose is to deliver controlled thermal energy for food preparation while preserving counter continuity and kitchen workflow efficiency. Induction hobs represent the fastest-growing product category as electromagnetic coil technology displaces conventional resistive heating in new construction and renovation pipelines. The hospitality end-user segment concentrates margin pools through demand for heavy-duty gas and hybrid configurations in professional kitchens. Smart technology features, including Wi-Fi connectivity and automated pan detection, are shifting from premium positioning toward mid-tier standard equipment.
EU Ecodesign regulations and REACH compliance frameworks enforce strict energy efficiency thresholds and material substance restrictions on imported cooking appliances. CE marking requirements under the EU's Gas Appliances Regulation and Low Voltage Directive govern market access for electric and gas hob categories sold across member states. FDA food contact surface standards apply to US-bound products with enamel or ceramic coatings. Stakeholders must monitor evolving electrification building codes and utility rebate programs that directly influence consumer replacement cycles and specification priorities.
Market Dynamics
Electromagnetic induction coil systems are displacing resistive heating elements as the dominant thermal transfer mechanism in new kitchen construction and renovation pipelines. This technology shift compresses replacement cycles while elevating power electronics and glass-ceramic substrate specifications across manufacturer portfolios.
Growth Catalysts
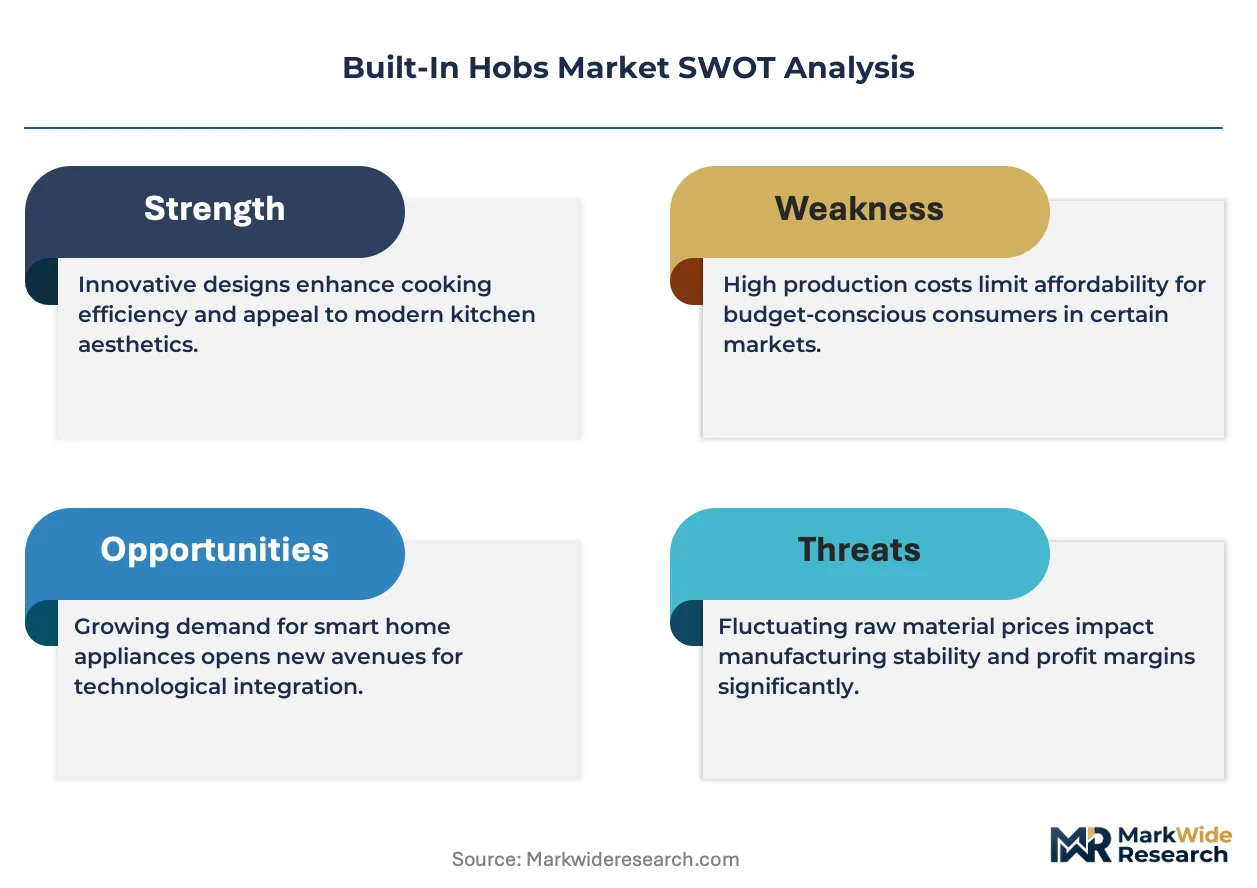
- EU Ecodesign mandates:Energy efficiency thresholds under the Ecodesign Directive are accelerating induction hob specification in residential retrofit projects. Member states enforce minimum performance standards that favor electromagnetic over gas combustion systems.
- Residential renovation spending:Premium household buyers in Germany, France, and the Netherlands are prioritizing flush-mounted cooking surfaces during kitchen modernization. This demand concentration pulls high-margin induction configurations through distribution channels.
- Smart kitchen integration:Wi-Fi connectivity and automated pan detection are migrating from premium positioning toward mid-tier standard equipment. Sensor-embedded coil arrays enable remote monitoring and energy optimization.
Market Restraints
- Copper and ferrite magnet cost volatility:Induction coil assemblies depend on copper winding and ferrite core materials subject to commodity price swings. Input cost instability compresses margin predictability for power electronics-integrated product lines.
- Gas infrastructure lock-in:Existing residential gas connections in Southern and Eastern European markets create switching friction. Building code grandfathering and utility connection subsidies prolong conventional hob replacement cycles.
- Technical compatibility constraints:Induction systems require ferromagnetic cookware, excluding aluminum and copper vessel owners from upgrade paths without ancillary expenditure.
Strategic Opportunities
- Hybrid gas-induction configurations:Dual-fuel surface designs capture transitional demand from gas-dependent households seeking partial electrification. This product architecture bridges infrastructure constraints while positioning for full induction conversion.
- Professional hospitality retrofit:Heavy-duty induction and hybrid systems penetrate commercial kitchen renovation cycles. Restaurant and hotel operators seek thermal precision and reduced ventilation loads.
- Utility rebate programs:Electrification incentives from national energy agencies subsidize consumer replacement decisions. Rebate-eligible SKUs command preferential shelf placement and sales force attention.
Industry Challenges
- Power electronics engineering scarcity:Inverter design and electromagnetic compatibility expertise concentrates among limited specialist talent pools. Manufacturers compete for embedded systems engineers capable of optimizing coil driver efficiency.
- CE marking complexity:Conformity assessment under the EU's Low Voltage Directive and Gas Appliances Regulation demands multi-standard testing protocols. Certification timeline extension delays product launch windows.
- Legacy countertop integration:Retrofit installation requires precise cutout modification and substrate reinforcement. Installer skill variability generates service quality inconsistency and warranty claim exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Built-In Hobs Market |
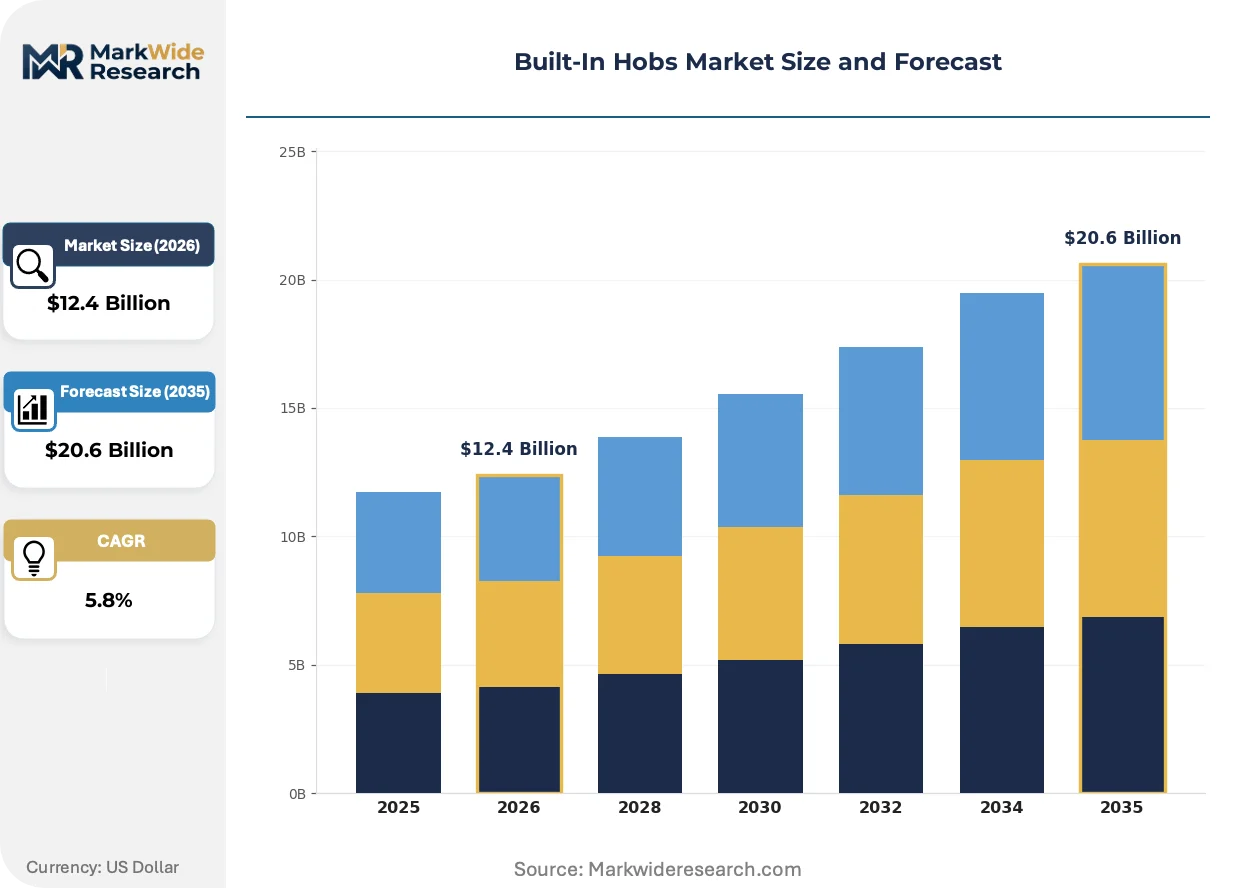
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Hobs, Electric Hobs, Induction Hobs, Hybrid Hobs End User: Household, Commercial, Hospitality, Institutions Size: Compact, Standard, Large, Extra Large Feature: Self-Cleaning, Smart Technology, Timer Function, Safety Lock |
| Companies Covered | Haier Group Corporation, Bosch, BSH Home Appliances Group, Smeg, Samsung, Whirlpool Corporation, LG Electronics Inc., Siemens, Electrolux AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Built-In Hobs Market Strategic Shifts
Active matrix sensor arrays and connected appliance architectures are redefining thermal control precision and kitchen workflow integration. These developments compress the boundary between cooking equipment and residential energy management systems.
Induction coil topology with distributed sensing nodes is decentralizing thermal management from centralized burner zones to surface-wide adaptive heating. Premium residential buyers in Germany and Scandinavia specify full-surface induction systems that detect pan position and size automatically. This architecture eliminates fixed burner geometry constraints while enabling simultaneous multi-vessel operation at variable power density.
REACH substance restrictions and RoHS material compliance are forcing reformulation of solder alloys and coating compounds used in coil assemblies and control modules. Manufacturers must validate alternative metallurgy and enamel formulations without compromising thermal cycling durability. The regulatory burden falls heaviest on mid-tier suppliers lacking captive materials science laboratories.
Specification decisions increasingly consolidate around energy labeling visibility and total cost of ownership calculations rather than upfront equipment expenditure. Retail channel buyers in France and Belgium now prioritize A-rated induction systems with verified standby power consumption. This behavioral pivot elevates transparent efficiency certification above aesthetic or brand preference in purchase criteria.
Built-In Hobs Market Segmentation
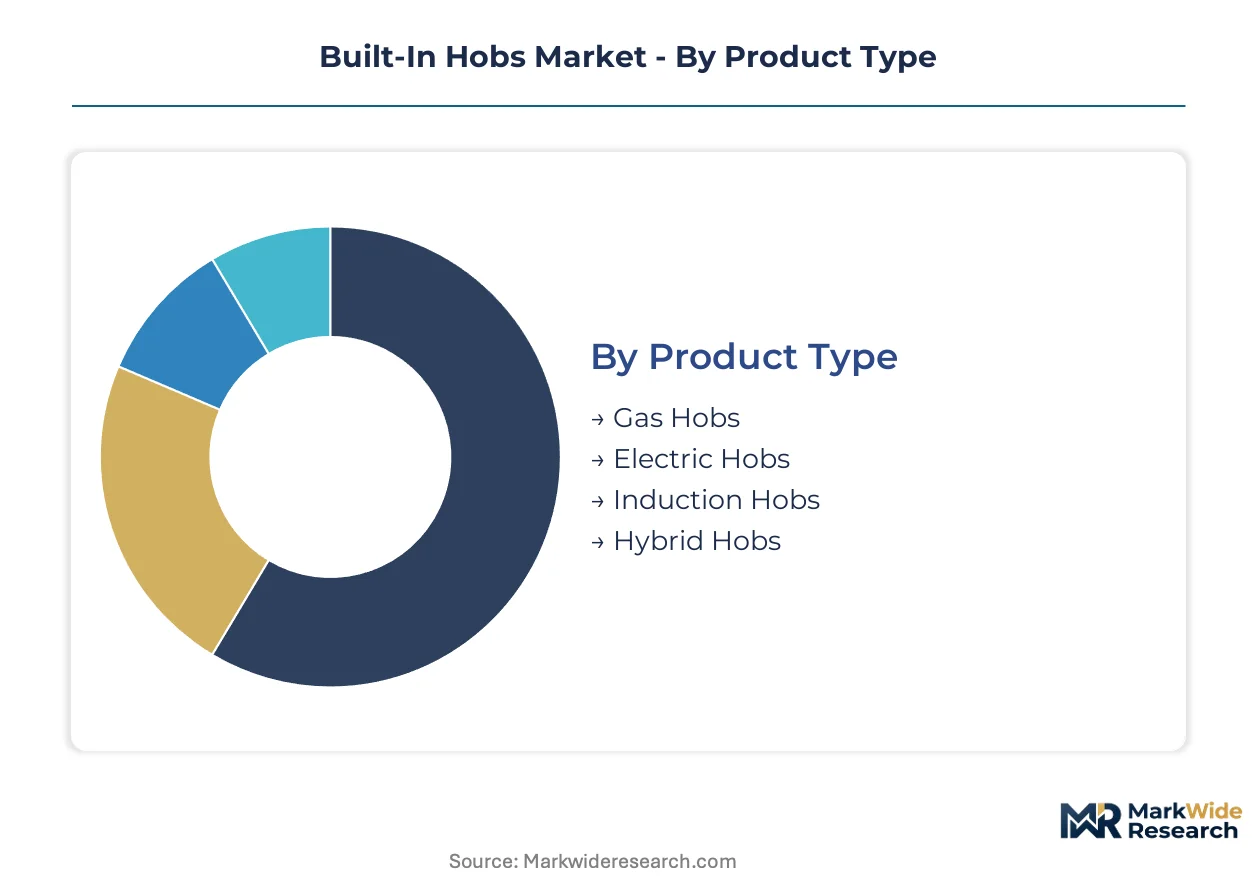
Built-in hobs manufacturers configure product portfolios around four intersecting dimensions that determine specification requirements, margin structures, and channel access. Each segmentation axis carries distinct engineering constraints and regulatory exposure that shape competitive positioning.
Product Type:
Supply concentration for coil assemblies and power electronics varies sharply across thermal transfer technologies, creating divergent sourcing strategies and margin profiles.
- Induction Hobs:Electromagnetic coil systems with ferrite cores and inverter-driven power electronics deliver thermal efficiency above 90%. German and Dutch residential renovation pipelines favor these systems under EU Ecodesign mandates, though copper and ferrite magnet cost volatility compresses margin predictability.
- Gas Hobs:Burner assemblies with cast iron or brass flame spreaders operate through regulated natural gas or LPG combustion. Southern and Eastern European markets retain substantial installed bases where building code grandfathering prolongs replacement cycles.
- Electric Hobs:Resistive heating elements beneath ceramic glass or enameled steel surfaces serve budget-conscious replacement demand. These systems face specification erosion as induction efficiency thresholds tighten.
- Hybrid Hobs:Dual-fuel configurations combining gas burners with induction zones capture transitional demand from households seeking partial electrification. This architecture bridges infrastructure constraints while positioning portfolios for full induction conversion.
Today's leader: Induction Hobs. Tomorrow's challenger: Hybrid Hobs.
End User:
Application-specific duty cycles and performance requirements drive divergent engineering priorities and certification pathways across customer categories.
- Hospitality:Heavy-duty configurations with reinforced glass-ceramic substrates and continuous-duty coil ratings serve restaurant and hotel kitchen renovation cycles. Operators prioritize thermal precision and reduced ventilation loads over upfront equipment expenditure.
- Household:Residential buyers in premium renovation segments specify flush-mounted surfaces with smart connectivity and automated pan detection. France and Belgium now prioritize A-rated systems with verified standby power consumption in retail channels.
- Commercial:Institutional foodservice operations in corporate cafeterias and catering facilities demand standardized configurations with simplified maintenance protocols.
- Institutions:Educational and healthcare facilities require compliance with public procurement frameworks and extended warranty terms.
Household volume anchors current revenue. Hospitality margins attract portfolio investment.
Size:
Countertop cutout standards and kitchen workflow patterns determine dimensional specification distribution across regional markets.
- Standard:60cm width configurations with three to four burner zones dominate European replacement cycles and align with prevalent cabinet dimensions.
- Large:70-80cm surfaces accommodate simultaneous multi-vessel operation in spacious kitchen layouts.
- Compact:30-45cm widths serve urban apartments and secondary cooking stations with space-constrained installations.
- Extra Large:90cm and above configurations target luxury residential and professional hospitality segments with full-surface induction arrays.
Standard dimensions command manufacturing scale. Extra Large specifications extract premium positioning.
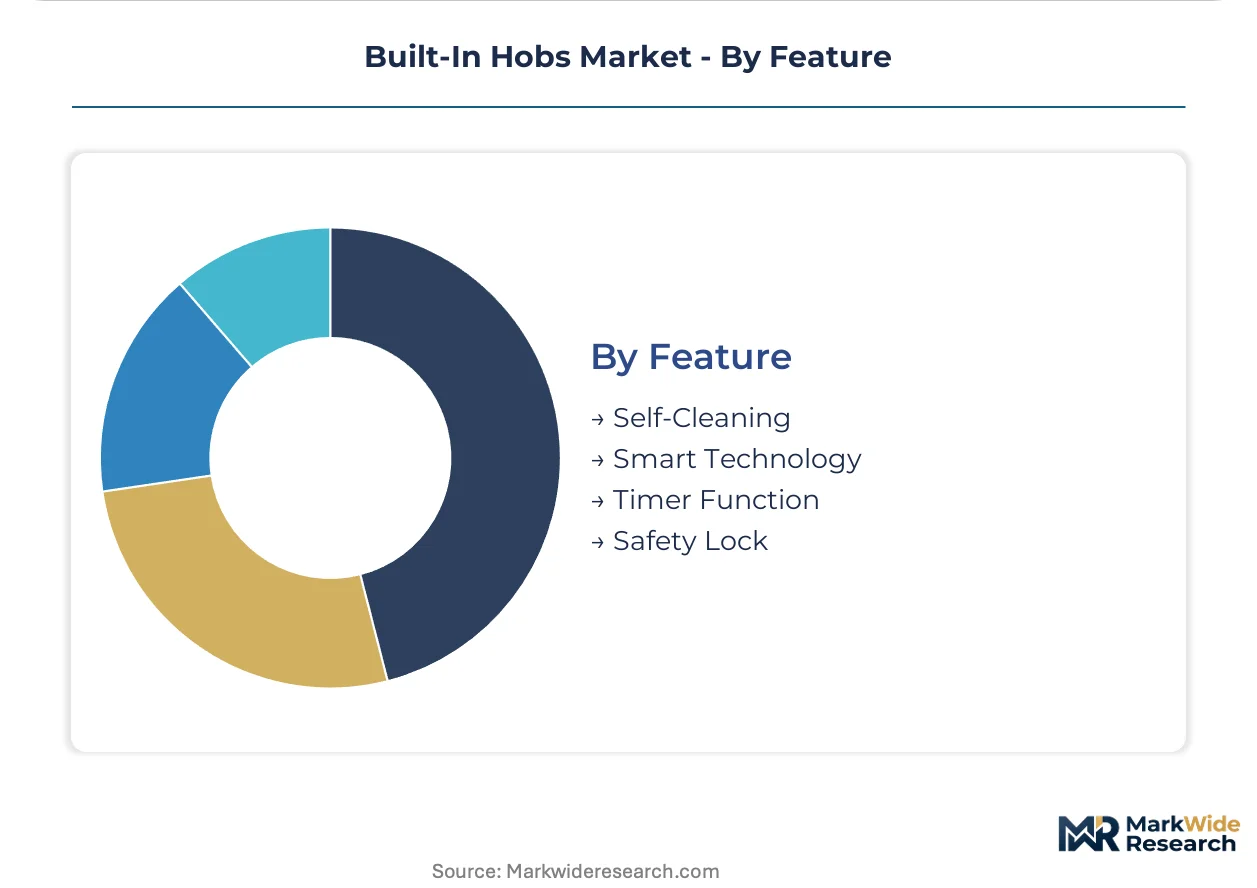
Feature:
Functional differentiation migrates from premium positioning toward mid-tier standard equipment as sensor costs decline and connectivity infrastructure matures.
- Smart Technology:Wi-Fi-enabled coil arrays with remote monitoring and energy optimization integrate with residential energy management systems. Samsung and connected appliance platforms drive ecosystem integration requirements.
- Timer Function:Programmable shutoff and delayed start capabilities address safety and convenience expectations across price tiers.
- Safety Lock:Child protection mechanisms and residual heat indicators satisfy regulatory requirements under EU safety directives.
- Self-Cleaning:Pyrolytic or catalytic surface treatments reduce maintenance burden in high-utilization environments.
Smart Technology features gain fastest adoption. Safety Lock becomes baseline compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in residential kitchen renovation spending, while Italy retains substantial gas infrastructure that slows induction conversion relative to Northern European neighbors.
Germany
Renovation pipelines in Berlin and Munich drive specification of A-rated induction systems with verified standby consumption. The Bundesamt für Wirtschaft und Ausfuhrkontrolle administers utility rebate programs that subsidize consumer replacement decisions. Manufacturing clusters in North Rhine-Westphalia concentrate captive power electronics production for premium coil assemblies.
France
Retail channel buyers in Paris and Lyon prioritize energy labeling visibility over brand preference in purchase criteria. ANSM and national energy agencies enforce compliance frameworks aligned with EU Ecodesign Directive thresholds. Assembly operations in Auvergne-Rhône-Alpes serve Southern European distribution networks with localized product configurations.
United Kingdom
London and Southeast England concentrate demand for flush-mounted smart kitchen integration linking hobs to residential energy management systems. Building regulations under the Future Homes Standard accelerate electrification specifications in new construction. Midlands manufacturing bases supply standardized configurations for institutional foodservice procurement frameworks.
Italy
Building code grandfathering in Rome and Milan prolongs conventional gas hob replacement cycles despite efficiency mandates. Regional utility subsidies preserve connection incentives that create switching friction for residential consumers. Northern industrial districts around Milan maintain specialized output of heavy-duty gas configurations for hospitality retrofit segments.
Netherlands
Amsterdam and Rotterdam households specify full-surface induction arrays with automated pan detection and position-independent heating. The Dutch Emissions Authority enforces strict electrification timelines that compress replacement cycles ahead of EU baseline requirements. Eindhoven-region electronics clusters supply sensor-embedded coil driver components to OEM assembly lines.
Built-In Hobs Market Competitive Environment
German producers anchor the premium tier through captive component supply and cold-climate engineering specialization; Asian electronics conglomerates hold ecosystem integration positions through connected appliance platforms. Market structure concentrates around three strategic archetypes: diversified home appliance conglomerates with full kitchen portfolios, power electronics specialists with captive coil assembly capacity, and smart home ecosystem integrators leveraging connectivity infrastructure. Competitive moves center on backward integration into ferrite magnet and copper winding supply, plus strategic partnerships with utility rebate program administrators.
Within the diversified conglomerate tier, Haier Group Corporation and BSH Home Appliances Group exemplify scale-driven positioning across thermal transfer technologies. Samsung occupies a distinct ecosystem-integrator position, leveraging connectivity infrastructure to link hobs with broader residential energy management platforms. These three anchors represent divergent strategic vectors: Chinese manufacturing scale, German engineering specialization, and Korean electronics ecosystem integration.
| Leading Market Players |
|---|
| Haier Group Corporation |
| Bosch |
| BSH Home Appliances Group |
| Smeg |
| Samsung |
| Whirlpool Corporation |
| LG Electronics Inc. |
| Siemens |
| Electrolux AB |
| Others |
Value Chain & Pricing Dynamics
Copper winding and ferrite core materials flow from commodity markets through power electronics integrators to three-tier pricing structures across premium, standard, and economy levels. German and Dutch buyers absorb elevated coil assembly costs through utility rebate offsets, while Southern European distributors compress margins to maintain gas hob volume.
Pricing Analysis
Distributor margins in the 25-35% range separate premium induction lines with captive inverter production from standard-tier imports with outsourced coil assemblies. Price differentiation hinges on CE marking tier and after-sales service bundling. Cost compression in the mid-tier intensifies because Chinese power electronics exports erode European assembly premiums. Budget-conscious replacement buyers in Italy and Spain exhibit highest price sensitivity, whereas Dutch full-surface induction adopters prioritize energy labeling over upfront expenditure.
Supply Chain Analysis
EU Ecodesign local-content preferences are reshaping sourcing toward North Rhine-Westphalia power electronics clusters and Eindhoven sensor-embedded coil suppliers. Ferrite magnet supply draws from China and Vietnam, while copper winding rests on German and Polish metal processing. Single-source vulnerability concentrates in ferrite core supply from Asian ceramics specialists. Distribution runs through kitchen retail chains and construction contractor channels with installer certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between German rebate-subsidized replacement cycles and Italian gas infrastructure lock-in, where regulatory lag extends conventional product viability. The cost differential in power electronics assembly favors early electrification positioning in Northern European markets.
For Market Incumbents: Hedge against copper and ferrite cost volatility through backward integration into coil winding capacity or long-term magnet supply agreements. Defensive consolidation should prioritize captive inverter design talent pools threatened by Asian electronics conglomerates. Channel control through certified installer networks protects service quality consistency and warranty exposure in retrofit-heavy markets. For New Entrants and Emerging Players: Begin with hybrid gas-induction configurations targeting Italian and Spanish transitional demand where building code grandfathering prolongs gas connection viability. The most penetrable white space sits in professional hospitality retrofit segments seeking reduced ventilation loads. A go-to-market angle anchored to utility rebate program eligibility commands preferential retail shelf placement. For Investors and Strategic Acquirers: Consolidation pressure builds where power electronics engineering scarcity concentrates among limited specialist talent pools. Long-term viability over a decade horizon favors acquirers of coil driver design capabilities and cold-climate reliability engineering expertise. The signal to watch is utility rebate program expansion or contraction as electrification policy inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Magnet Supply | Captive magnet sourcing insulates Bosch and BSH from Asian ceramics price volatility. |
| Utility Rebate Program Partnership | BAFA eligibility secures preferential channel positioning for German OEM induction lines. |
| Full-Surface Induction Product Launch | Distributed sensor arrays capture Dutch and Scandinavian premium renovation demand. |
| Hybrid Configuration Platform Expansion | Dual-fuel designs bridge Italian gas infrastructure constraints while preserving electrification optionality. |
| Smart Kitchen Ecosystem Integration | Samsung's connected appliance platform locks in London and Southeast England residential buyers. |
Study Parameters
Coverage spans Germany, France, the Netherlands, Italy, and the United Kingdom, with primary inputs from each market. Appliance manufacturing executives, kitchen retail category buyers, certified installation contractors, and power electronics R&D directors contributed structured interviews. Secondary validation drew from EU Ecodesign Directive filings, CE marking databases, Bundesamt für Wirtschaft und Ausfuhrkontrolle rebate program records, and national energy agency electrification roadmaps. Bottom-up shipment data triangulated against top-down renovation spending estimates.
Granularity-level modeling disaggregated volume and value across product type, end user, size, and feature dimensions at the country level. Thermal transfer technology migration curves, utility rebate program eligibility thresholds, and countertop cutout standard adoption rates informed the analytical framework across the analysis window. CAGRs derived from segment-level replacement cycle compression and electrification policy trajectory.
Several conditions sit outside the modeled scope, including abrupt natural gas price shocks, building code revision timelines, and ferrite magnet export restriction scenarios. Forecasts reflect assumptions about Ecodesign Directive enforcement consistency and rebate program continuity. Supply chain disruption or regulatory acceleration in Southern Europe could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
Australia Washing Machine Market
Home Appliances
Residential Washing Machine Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Electrical Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Bahrain Small Home Appliances Market