
 South America Hair Conditioner Market | 2026-2036
South America Hair Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
South America Hair Conditioner Market Analytics
Capital-intensity divergence between multinational labs and local manufacturers is reorganizing competitive dynamics in the South America Hair Conditioner Market. L'Oréal S.A. leverages its dedicated Rio de Janeiro innovation hub to sustain formulation leadership for humid climates. Natura & Co anchors its position through captive sourcing of Amazonian bioactives. Grupo Boticário competes via dense retail penetration across Brazil's secondary cities.
Hair conditioner denotes a cationic surfactant-based cosmetic preparation designed to deposit conditioning agents onto hair cuticles, typically containing fatty alcohols, silicones, or plant-derived lipids at pH 3.0 to 5.0 to restore manageability after cleansing. Its primary commercial purpose centers on reducing friction-induced damage while enhancing aesthetic properties for consumer and professional styling applications. Cream formulations dominate volume through salon and retail channels, while sulfate-free variants capture expanding margin pools as ingredient-conscious consumers migrate from conventional surfactant systems. E-commerce customer segments exhibit the fastest structural expansion, though retail chains still occupy the largest absolute revenue position across the region.
ANVISA governs cosmetic safety and ingredient disclosure requirements in Brazil, while Argentina's national pharmaceutical regulator enforces parallel standards for cross-border product registration. REACH-aligned frameworks in Chile and Peru create incremental compliance burdens for imported formulations. Stakeholders must monitor evolving mercosur harmonization talks and decide whether to consolidate regional formulation platforms or maintain country-specific product registrations.
Market Dynamics
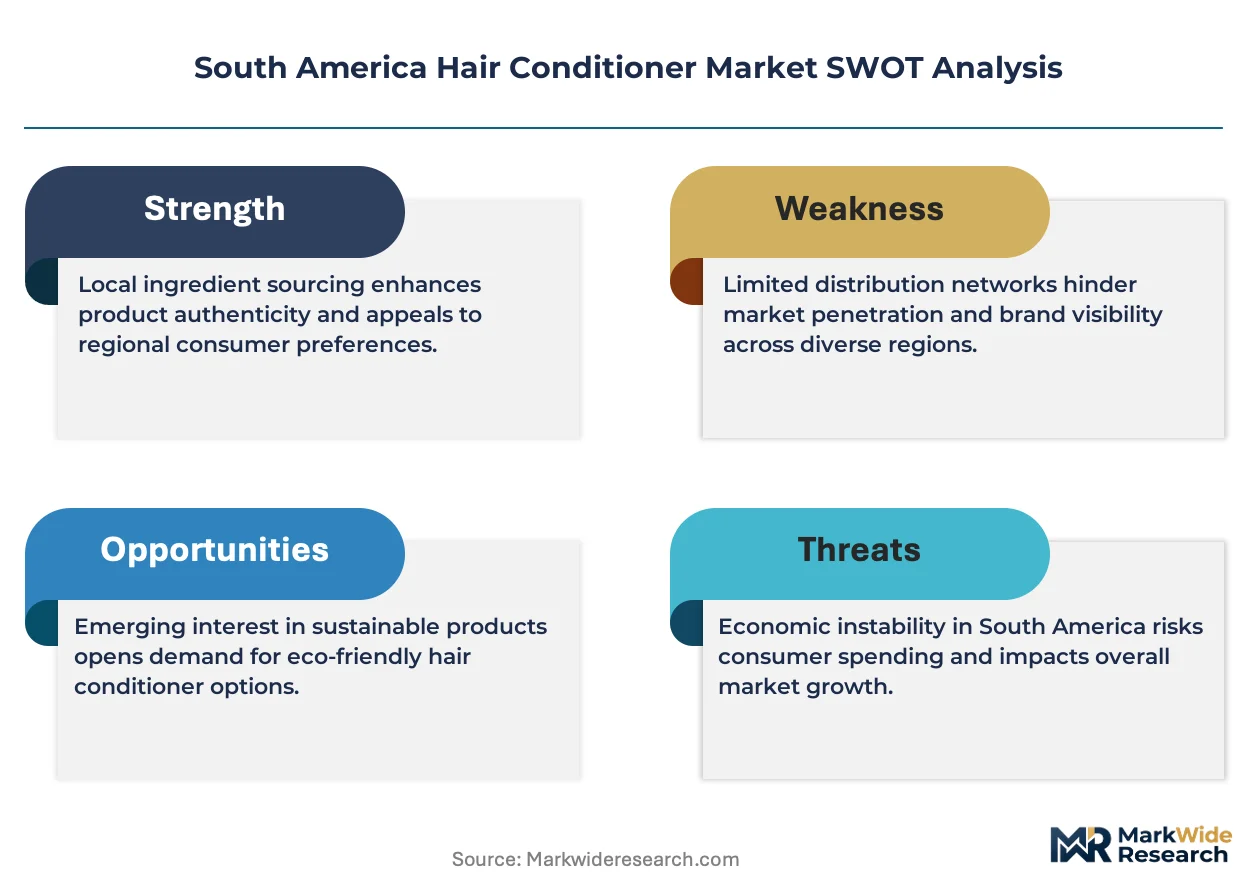
ANVISA's tightened cosmetic ingredient standards are forcing Brazilian manufacturers to reformulate entire product lines, while Amazonian bioactive sourcing constraints concentrate supply power among vertically integrated regional players.
Growth Catalysts
- Professional salon channel expansion:Brazil's urban salon sector drives premium formulation adoption through technical training programs and exclusive distribution partnerships.
- ANVISA ingredient transparency mandates:Brazil's national health surveillance agency requires expanded disclosure of conditioning agent compositions, accelerating clean-label product development.
- Sulfate-free surfactant migration:Ingredient-conscious consumers in São Paulo and Rio de Janeiro are switching from conventional cationic systems to milder alternatives.
Market Restraints
- Amazonian bioactive supply concentration:Captive sourcing of plant-derived lipids from the Brazilian Amazon creates dependency on specific regional harvest cooperatives.
- REACH-aligned compliance costs:Chile and Peru impose incremental registration burdens on imported silicone and fatty alcohol formulations.
- Input cost volatility:Fatty alcohol prices fluctuate with palm oil commodity markets, compressing margin stability for mid-tier manufacturers.
Strategic Opportunities
- Argentine cross-border registration:Argentina's national pharmaceutical regulator enforces parallel cosmetic standards, creating first-mover advantages for compliant Brazilian exporters.
- E-commerce channel penetration:Direct-to-consumer platforms capture structural expansion in customer segments underserved by traditional retail chains.
- MERCOSUR harmonization talks:Pending regional regulatory convergence would enable consolidated formulation platforms across Brazil, Argentina, Paraguay, and Uruguay.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in humid-climate cationic surfactant design remains concentrated in multinational innovation hubs.
- Legacy retail dependency:Dense penetration through Brazil's secondary cities requires sustained trade investment despite channel mix shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Hair Conditioner Market |
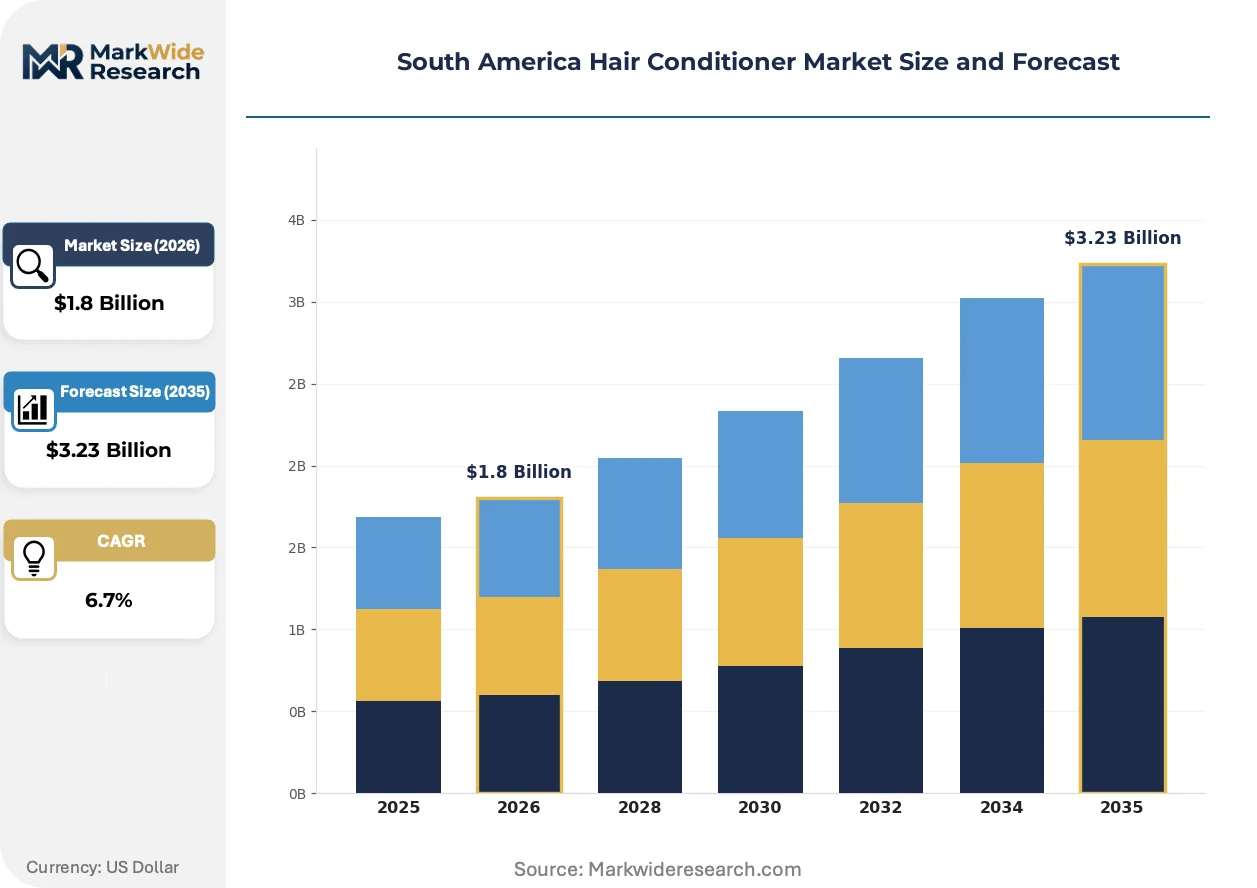
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Gel, Spray, Leave-in Formulation: Sulfate-free, Natural, Organic, Moisturizing Customer Type: Salons, Individual Consumers, Retail Chains, E-commerce Packaging Type: Tubes, Bottles, Jars, Pouches |
| Companies Covered | L'Oréal S.A., The Procter & Gamble Company, Unilever PLC, Colgate-Palmolive Company, The Estée Lauder Companies Inc., Kao Corporation, Natura & Co, Grupo Boticário, Henkel AG & Company, KGaA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Hair Conditioner Market Evolving Landscape
Conditioner technology is pivoting toward climate-adaptive formulations and transparent supply chains, with regulatory pressure and professional salon requirements accelerating material substitution cycles.
Plant-derived cationic conditioning agents extracted from Brazilian babassu and murumuru oils are displacing conventional quaternary ammonium compounds in premium salon formulations. Professional stylists in São Paulo's high-humidity corridor adopt these bioactives for superior cuticle deposition without silicone buildup. The shift is displacing established petroleum-derived conditioning bases and rewiring raw material procurement toward Amazonian cooperative networks.
ANVISA's 2024 cosmetic ingredient disclosure expansion requires full traceability for all cationic surfactants and fatty alcohols used in commercial conditioners. Brazilian manufacturers must now submit complete supply chain documentation for every conditioning agent batch. Professional salon brands face the steepest compliance timelines, while mass-market players consolidate formulations to reduce registration complexity.
Subscription-based replenishment models now capture growing conditioner volume in Brazil's southeastern metropolitan corridor, bypassing traditional retail shelf competition. Direct-to-consumer platforms leverage humidity-matched algorithmic recommendations to convert trial users into recurring buyers. This channel rotation is most pronounced among millennial consumers in Rio de Janeiro's Zona Sul district, where delivery infrastructure supports same-day fulfillment.
South America Hair Conditioner Market Segmentation
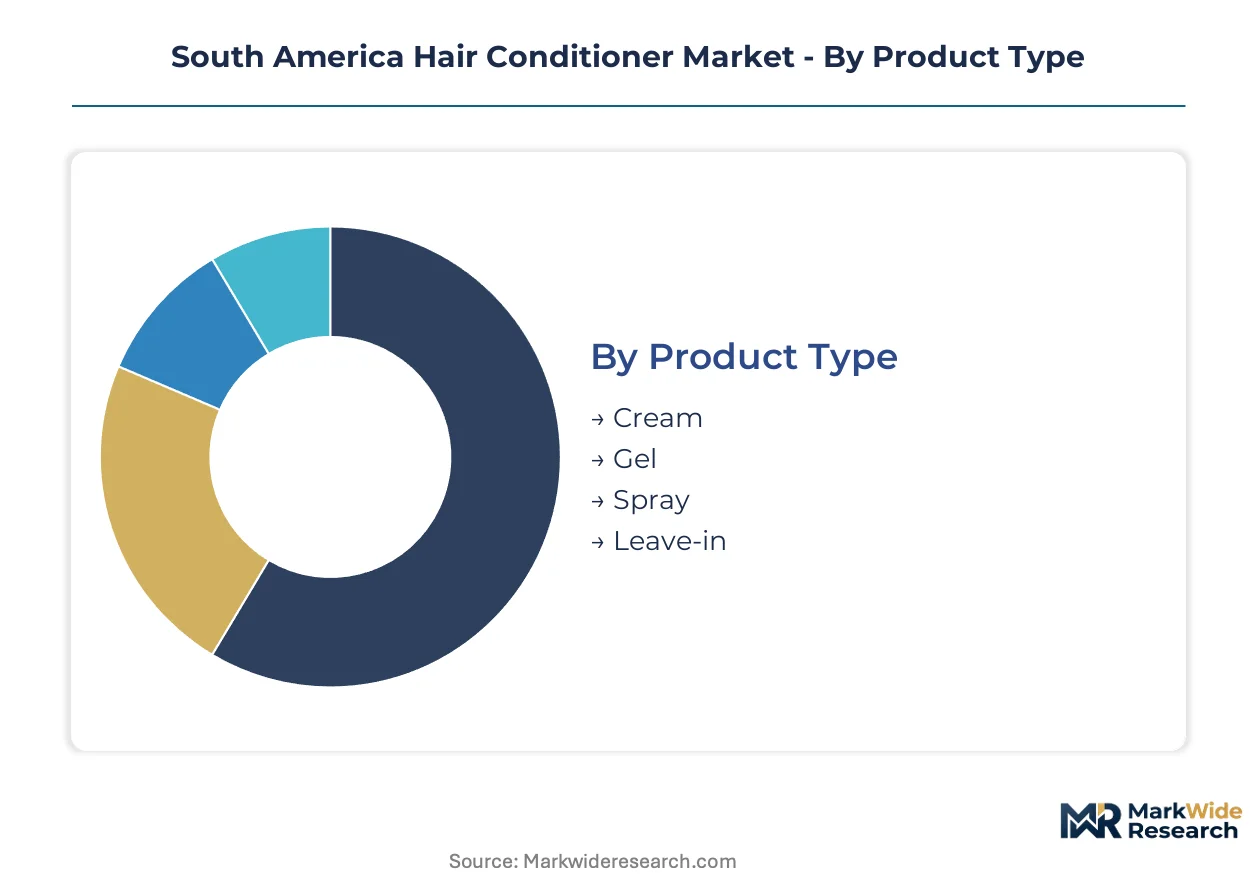
Segmentation in the South America Hair Conditioner Market reveals how formulation chemistry, channel economics, and packaging logistics create distinct competitive arenas. Each dimension carries unique substitution pressures from adjacent personal care categories and professional service alternatives.
Product Type:
Substitution pressure runs strongest against cream formats from all-in-one cleansing conditioners and salon treatment masks that bypass daily conditioning rituals entirely.
- Cream:Emulsion-based formulations with cationic surfactants and fatty alcohols at 3-5% active concentration deposit conditioning films on damaged cuticles. Demand concentrates in São Paulo's professional salon corridor where stylists apply post-color treatments to restore porosity. ANVISA's tightened preservative limits are forcing reformulation of legacy cream bases.
- Leave-in:Lightweight polymer-silicone suspensions designed for humid-climate frizz control without rinse cycles. Adoption concentrates in Rio de Janeiro's Zona Sul district among consumers seeking styling flexibility between washes. E-commerce algorithmic recommendations accelerate trial-to-recruitment conversion for this format.
- Gel:Hydroxyethylcellulose-thickened preparations targeting oil-prone scalps with minimal residue.
- Spray:Aerosol or pump-dispersed fine mists for detangling and thermal protection pre-styling.
Cream anchors the volume base while leave-in gains share at the steepest rate.
Formulation:
Cost tier stratification separates premium-positioned chemistry from commodity surfactant systems competing on per-liter pricing.
- Sulfate-free:Amphoteric and non-ionic surfactant systems replacing sodium lauryl sulfate with coco-glucoside or sodium cocoyl isethionate. Demand concentrates in Brazil's southeastern metropolitan corridor where ingredient-conscious consumers migrate from conventional cationic systems. ANVISA's expanded disclosure mandates accelerate clean-label migration.
- Natural:Plant-derived conditioning bases incorporating Brazilian babassu and murumuru oils as quaternary ammonium replacements. Procurement concentrates through Amazonian cooperative networks with captive sourcing agreements. Humidity-matched formulations from Rio de Janeiro innovation hubs validate performance claims.
- Organic:Certified ingredient systems meeting third-party agricultural standards with full supply chain traceability.
- Moisturizing:Glycerin and panthenol-enriched variants targeting chemically treated hair recovery.
Moisturizing formulations hold the largest installed base while sulfate-free climbs the fastest.
Customer Type:
Volume concentration in legacy retail channels faces structural rotation toward direct fulfillment models with superior customer data capture.
- Salons:Professional-only distribution through technical training partnerships and exclusive bulk formats. Brazil's urban salon sector drives premium formulation adoption with stylists recommending humidity-specific products. Dense secondary city penetration requires sustained trade investment from manufacturers.
- E-commerce:Direct-to-consumer platforms leveraging subscription replenishment and algorithmic matching. Same-day fulfillment infrastructure in Rio de Janeiro and São Paulo supports recurring revenue models. Channel rotation is most pronounced among millennial demographics.
- Individual Consumers:Mass-market retail purchasers selecting from shelf-available assortments.
- Retail Chains:Hypermarket and drugstore distribution with promotional calendar dependency.
Retail chains maintain absolute revenue leadership while e-commerce expands most quickly.
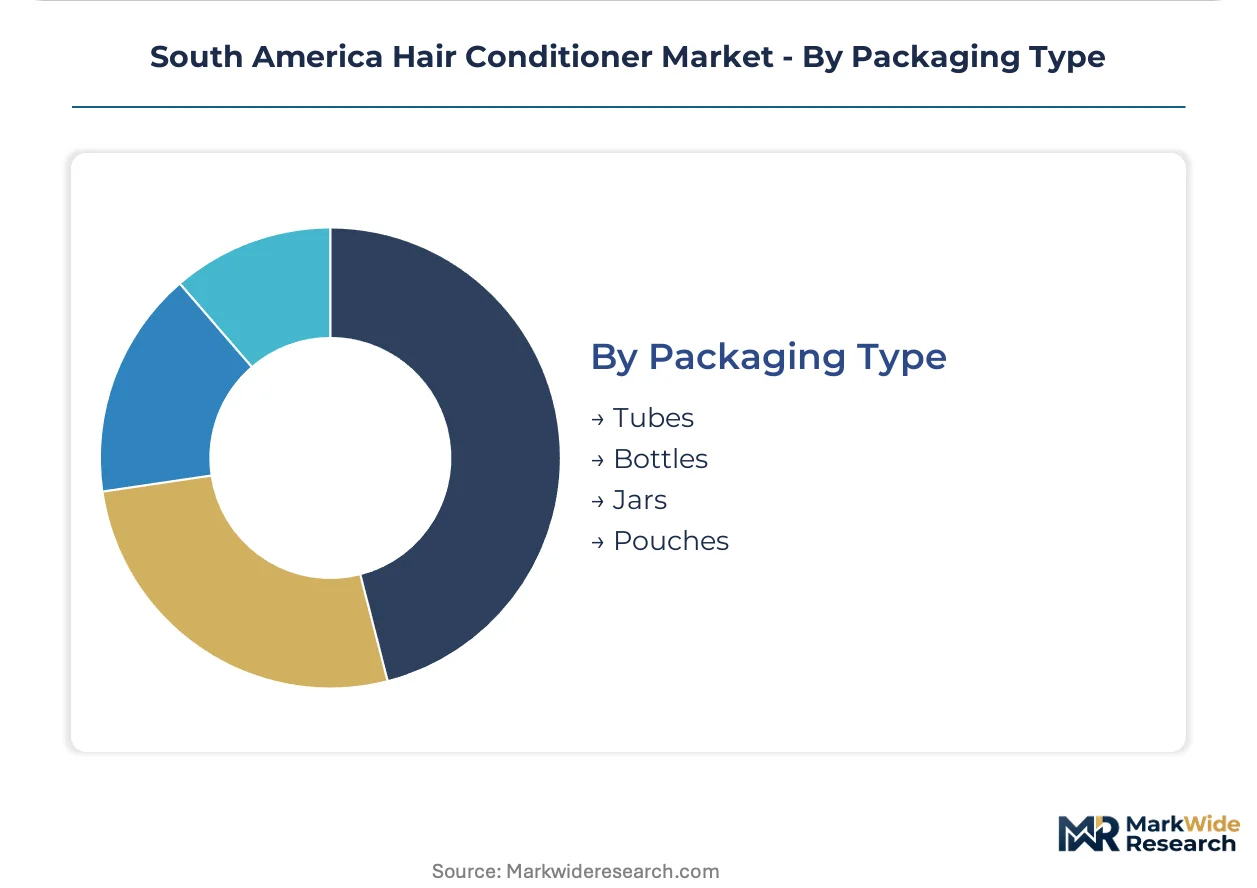
Packaging Type:
Supply concentration in plastic converter networks shapes regional sourcing strategies with sustainability mandates driving material substitution.
- Bottles:HDPE and PET containers with flip-top or pump closures dominating family-size and professional formats. Manufacturing concentrates in Brazil's southeastern industrial corridor with MERCOSUR tariff advantages. Post-consumer recycled content mandates are accelerating material qualification cycles.
- Tubes:Laminated aluminum-plastic or all-plastic squeeze formats for travel and trial sizes. Demand concentrates in airport retail and subscription box inserts where portability determines selection. Argentine cross-border registration creates first-mover positioning for compliant exporters.
- Jars:Wide-mouth containers for intensive treatment masks requiring finger-scoop application.
- Pouches:Flexible film sachets for single-use samples and emerging market price-tier entry.
Bottles carry the volume base while tubes gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Conditioner consumption patterns diverge sharply across South America, with Brazilian salons driving professional-grade volume while Argentine households favor mass-market retail formats and Chilean consumers prioritize clean-label imports.
Brazil
São Paulo's professional salon corridor anchors premium formulation demand through technical training partnerships and exclusive bulk distribution. ANVISA's 2024 cosmetic ingredient disclosure expansion mandates complete supply chain documentation for cationic surfactants. Rio de Janeiro's Zona Sul district concentrates leave-in conditioner adoption among humidity-conscious millennial consumers.
Argentina
Buenos Aires households sustain mass-market cream conditioner volume through hypermarket promotional calendars and price-tier sensitivity. The national pharmaceutical regulator enforces parallel cosmetic standards for cross-border Brazilian imports. Córdoba's secondary retail networks create first-mover positioning for compliant exporters from neighboring Mercosur states.
Chile
Santiago's ingredient-conscious consumers migrate toward sulfate-free formulations with expanded clean-label claims. REACH-aligned frameworks impose incremental registration burdens on imported silicone and fatty alcohol formulations. Valparaíso's port logistics cluster handles bulk raw material entry for regional formulation platforms.
Colombia
Bogotá's emerging salon sector adopts humidity-matched conditioning systems through professional distributor networks. National cosmetic safety standards require alignment with Andean Community technical regulations. Medellín's manufacturing corridor hosts contract packaging operations for multinational brand localization.
Peru
Lima's coastal climate drives lightweight leave-in conditioner preference among consumers managing frizz without heavy residue. Import registration protocols follow Chilean REACH-aligned compliance templates. Callao's port infrastructure supports e-commerce fulfillment for direct-to-consumer subscription models.
South America Hair Conditioner Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational laboratories commanding formulation R&D and regional players anchoring Amazonian bioactive sourcing. The structure rewards captive supply agreements and climate-adaptive product development. Three archetypes dominate: multinational innovators with dedicated humid-climate hubs, vertically integrated regional specialists with cooperative networks, and mass-market distributors with dense secondary-city penetration. Competitive moves concentrate on exclusive salon distribution partnerships and regulatory pre-registration for cross-border expansion.
Within the multinational tier, L'Oréal S.A. and The Procter & Gamble Company exemplify scale-driven formulation leadership, while Natura & Co represents the vertically integrated regional specialist archetype through its captive Amazonian sourcing position.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Procter & Gamble Company |
| Unilever PLC |
| Colgate-Palmolive Company |
| The Estée Lauder Companies Inc. |
| Kao Corporation |
| Natura & Co |
| Grupo Boticário |
| Henkel AG & Company, KGaA |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for Amazonian bioactives concentrate supply power among vertically integrated Brazilian manufacturers, directly amplifying pricing leverage for holders of captive babassu and murumuru oil contracts while compressing margin flexibility for spot-market dependent formulators.
Pricing Analysis
Long-term offtake agreements dominate procurement for premium salon-grade conditioners, locking in fatty alcohol volumes at fixed rates while spot-market exposure concentrates among mid-tier mass-market players. Price differentiation separates ANVISA-registered professional formulations from unregistered gray-market imports, with certification tier and geographic delivery cost driving tier spreads. Pricing pressure stems from palm oil commodity volatility feeding into cationic surfactant input costs. Individual consumers in Argentina's secondary cities exhibit highest price sensitivity; São Paulo salon professionals show lowest sensitivity due to technical performance requirements.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for silicone and fatty alcohol shipments arriving from Asian manufacturing hubs, compressing landed cost advantages for non-integrated formulators. Raw material procurement draws from Brazil's Amazonian cooperative networks for plant-derived lipids, Malaysia and Indonesia for palm oil derivatives, and China for specialty quaternary ammonium compounds. Single-source vulnerability concentrates in Amazonian bioactive harvest cooperatives with limited alternative qualification. Distribution runs through Brazil's southeastern industrial corridor manufacturing clusters, with MERCOSUR tariff advantages shaping cross-border flows to Argentina and Chile.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated e-commerce platforms and professional salon chains, fragmenting traditional retail channel leverage that once anchored manufacturer pricing authority.
For Market Incumbents: Secure exclusive distribution partnerships with São Paulo's technical training academies to lock in professional channel loyalty against emerging clean-label entrants. Deepen captive sourcing agreements with Amazonian harvest cooperatives before regulatory traceability mandates tighten supplier qualification windows. ANVISA's expanded disclosure requirements threaten margin structures for legacy formulations lacking supply chain documentation.
For New Entrants and Emerging Players: Anchor in Rio de Janeiro's Zona Sul millennial demographic through subscription-based replenishment models with humidity-matched algorithmic recommendations. Target Argentina's Córdoba secondary retail networks where compliant Brazilian exporters face limited clean-label competition. Deploy direct-to-consumer sampling via tube-format trial sizes to bypass shelf-space barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical-integration play because Amazonian bioactive sourcing constraints will concentrate supply power among holders of cooperative network equity. Acquisition candidates include mid-tier Brazilian manufacturers with ANVISA pre-registration assets for cross-border expansion. Monitor MERCOSUR harmonization negotiation progress as inflection signal for consolidated formulation platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Amazonian Sourcing Agreement | Locks in babassu and murumuru oil supply ahead of ANVISA traceability mandates. |
| Professional Salon Channel Expansion | Builds technical training partnerships that create switching costs for stylists. |
| Sulfate-Free Formulation Migration | Captures ingredient-conscious consumers migrating from conventional cationic systems. |
| E-Commerce Subscription Launch | Converts trial users through algorithmic humidity-matching in southeastern Brazil. |
| MERCOSUR Registration Pre-Positioning | Enables consolidated formulation platforms across Brazil, Argentina, and Uruguay. |
Research Methodology
A standing panel of formulation chemists, professional salon owners, ANVISA regulatory consultants, and e-commerce platform category managers provided ongoing calibration across the research cycle. Primary interviews with brand managers at multinational laboratories and procurement leads at Amazonian cooperative networks combined with secondary validation from ANVISA registration databases, customs import records, and Nielsen retail audit data. Bottom-up volume triangulation across product type and formulation segments was cross-checked against top-down market sizing from macroeconomic consumption indicators.
Consistency checks validated volume and value outputs against external benchmarks from regional trade associations and competitor financial disclosures. The analytical framework modeled segmentation across product type, formulation chemistry, customer channel, and packaging format throughout the projection horizon. CAGRs were derived from regression analysis of historical consumption patterns adjusted for regulatory inflection points and channel mix shifts. Industry-specific inputs included salon service frequency data and e-commerce penetration curves for beauty categories.
Decision-makers should treat outputs as directional under assumptions of sustained MERCOSUR trade integration and stable Amazonian harvest yields; material deviation would warrant model refresh. Specific risk factors include ANVISA regulatory acceleration, palm oil commodity spikes, and logistics disruptions at Santos port. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Italy Beauty and Personal Care Products Market
Beauty & Personal Care
At Home Hair Dye Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
North America Beauty Devices Market