
 Household Electric Steamer Cooker Market | 2026-2036
Household Electric Steamer Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Household Electric Steamer Cooker Market Insights
Buyer fragmentation across health-conscious millennials and aging populations is repositioning demand toward programmable, multi-functional appliances. Philips leverages its R&D intensity in precision temperature control systems to anchor premium positioning. Panasonic competes through geographic dominance across East Asian retail channels. Hamilton Beach specializes in value-tier stackable designs for North American mass-market distribution.
Household electric steamer cookers are countertop or portable electromechanical appliances that generate pressurized or atmospheric steam between 100°C and 120°C to prepare food while preserving water-soluble nutrients. Their primary commercial purpose centers on enabling oil-free meal preparation for dietary management and time-compressed domestic cooking routines. Multi-functional cooker configurations command the widest margin pools as they displace discrete appliances in space-constrained kitchens. Digital control interfaces represent the fastest-expanding segment as touch-panel and app-connected models displace manual dial mechanisms. Stainless steel construction leads in perceived durability and food-contact safety, though BPA-free plastic variants occupy the entry-price tier.
EU Ecodesign regulations and REACH substance restrictions shape material selection and standby-power thresholds for products entering European markets. FDA food-contact substance notifications and UL 1026 safety standards govern market access in the United States. China's GB standards for household electrical appliances and India's BIS certification requirements create layered compliance obligations for multinational suppliers. Stakeholders must monitor evolving interoperability standards between smart kitchen platforms and appliance firmware as connectivity becomes a baseline purchase criterion rather than a premium differentiator.
Market Dynamics
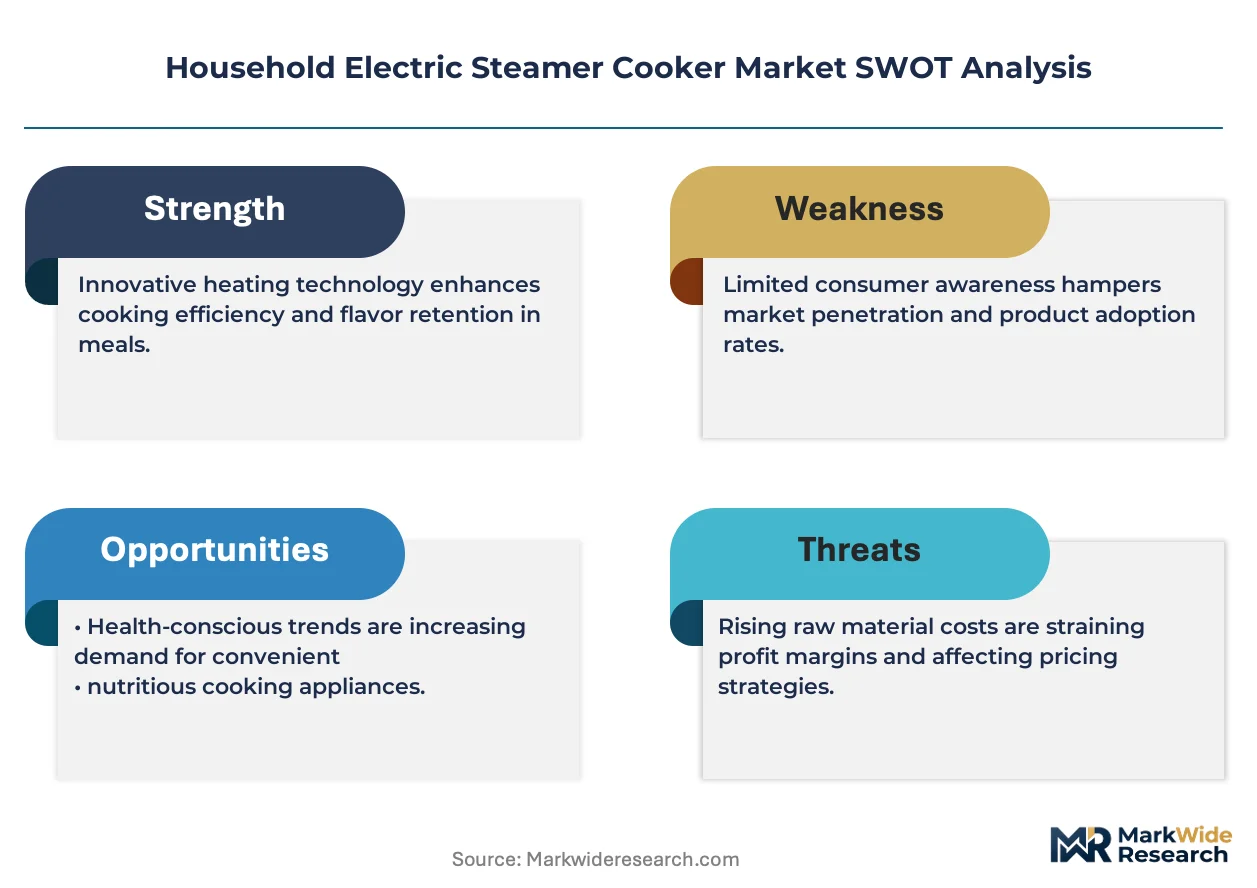
EU Ecodesign regulations on standby power consumption and material restrictions under REACH are forcing manufacturers to redesign heating elements and housing materials, compressing margins for non-compliant suppliers while rewarding early adopters of energy-efficient architectures.
Growth Catalysts
- REACH substance restrictions:Bans on certain phthalates and heavy metals in food-contact plastics accelerate migration toward stainless steel and ceramic steam chambers, opening premium positioning for compliant suppliers.
- Health-conscious urban households:Oil-free cooking protocols in China's tier-one cities and India's metropolitan corridors expand addressable demand for multi-functional steamers with programmable nutrient-preservation settings.
- Smart kitchen platform interoperability:Firmware integration with voice assistants and recipe apps transforms connected steamers from isolated appliances into nodes within integrated meal-planning ecosystems.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost fluctuations compress margins for mid-tier manufacturers lacking long-term supply contracts or backward integration into metal sourcing.
- Heating element supplier concentration:Precision temperature control modules rely on a concentrated base of East Asian component specialists, creating vulnerability to regional supply disruptions.
- Induction cooking substitution:Multi-functional induction hobs with steam-assisted modes capture overlapping use cases in space-constrained kitchens, limiting steamer cooker expansion in premium segments.
Strategic Opportunities
- India's BIS certification pipeline:Formalized safety standards for small domestic appliances create first-mover advantage for suppliers establishing local testing partnerships and distribution infrastructure ahead of enforcement deadlines.
- Aging population meal-prep services:Programmable steamers with texture-modification settings for dysphagia-friendly diets address underpenetrated senior care channels in Japan and South Korea.
- Appliance-as-a-service models:Subscription-based hardware provisioning with bundled recipe content and consumable replenishment shifts revenue from unit sales to recurring streams in North American urban markets.
Industry Challenges
- Firmware security certification:Smart steamer cookers require UL 2900 cybersecurity validation for connected devices, extending product development timelines by 4-6 months for engineering teams without embedded security expertise.
- Cross-platform integration complexity:Fragmented smart home protocols force manufacturers to maintain multiple firmware branches, inflating QA overhead and complicating over-the-air update deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Electric Steamer Cooker Market |
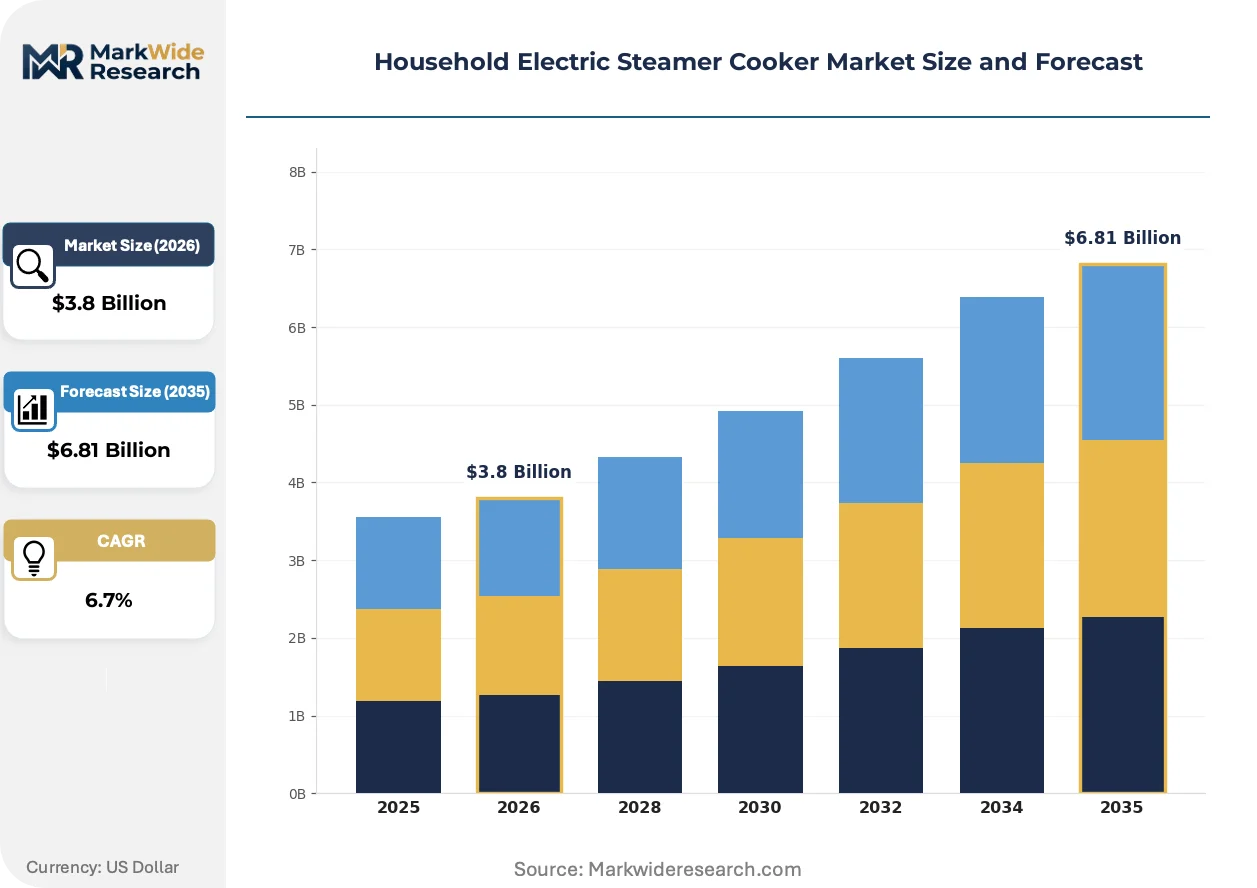
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Steamer, Multi-Functional Cooker, Stackable Steamer, Portable Steamer Capacity: 1-3 Liters, 3-5 Liters, 5-7 Liters, Above 7 Liters Control Type: Digital Control, Manual Control, Touch Control, Remote Control Material: Stainless Steel, BPA-Free Plastic, Silicone, Aluminum |
| Companies Covered | Philips, Panasonic, Breville, Hamilton Beach, Cuisinart, Braun GmbH, Morphy Richards, German Pool Group, Russell Hobbs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Electric Steamer Cooker Market Trends and Innovations
Digital control interfaces and connectivity modules are displacing mechanical dial mechanisms across all price tiers, while material science advances and energy-efficiency mandates reshape product architecture and supply chain sourcing priorities.
Precision temperature sensors with PID control algorithms are converging with cloud-based recipe databases to enable automated cooking programs that adjust steam intensity and duration based on food weight and type. Health-focused millennials in China's tier-one cities adopt these systems fastest, compressing the replacement cycle for manual steamers from seven years to four.
EU Ecodesign Directive 2019/2023 imposes maximum standby power thresholds of 0.5 watts for household cooking appliances, compelling redesigns of control boards and display modules. Manufacturers serving European markets accelerate migration to e-ink displays and capacitive touch surfaces that draw minimal idle current, with stainless steel construction variants gaining share over plastic-housed alternatives.
Direct-to-consumer channel expansion disrupts traditional appliance retail in North America, with subscription-box bundling and influencer-driven launches displacing big-box showroom dependence. Kitchenware startups leverage TikTok-native content to demonstrate multi-functional steamer capabilities, capturing younger household formations that bypass conventional purchase research patterns.
Household Electric Steamer Cooker Market Segmentation
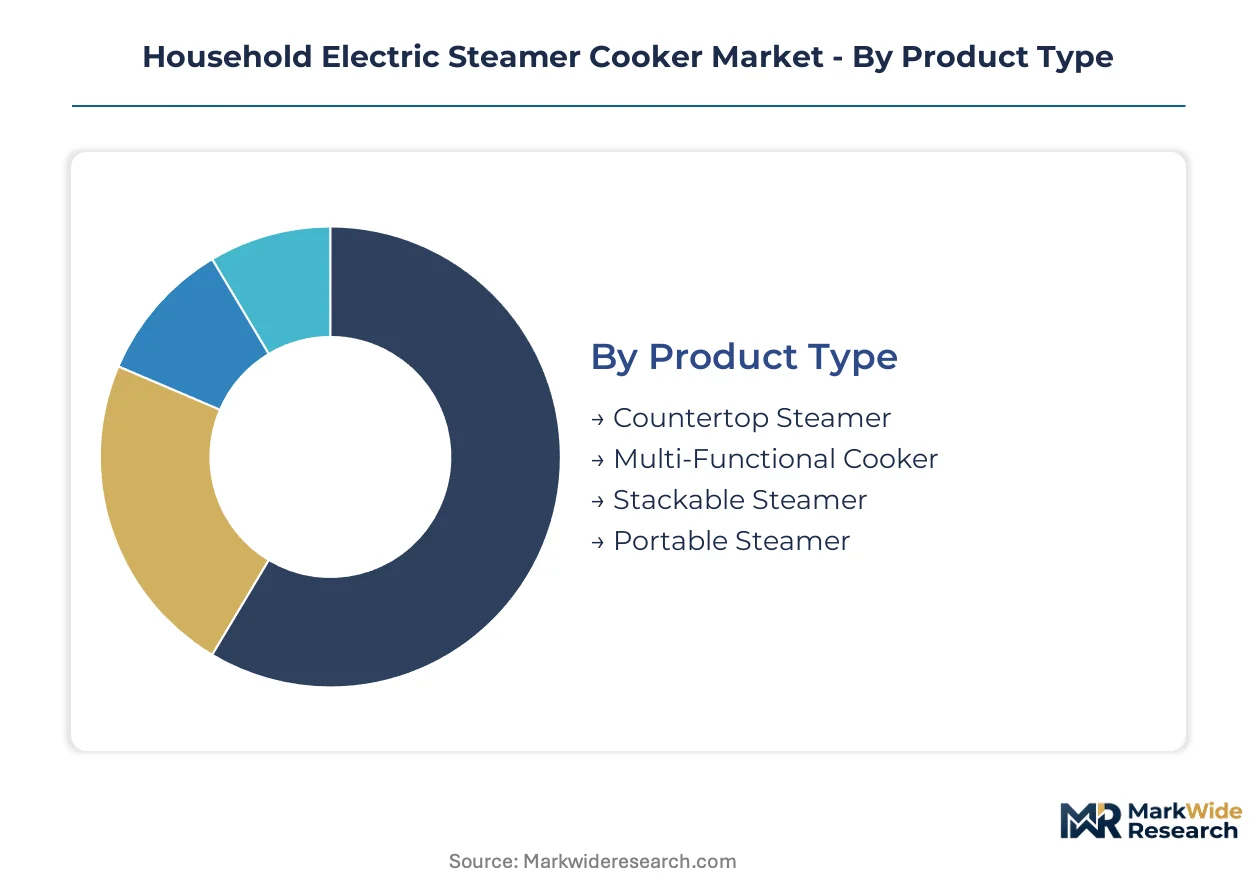
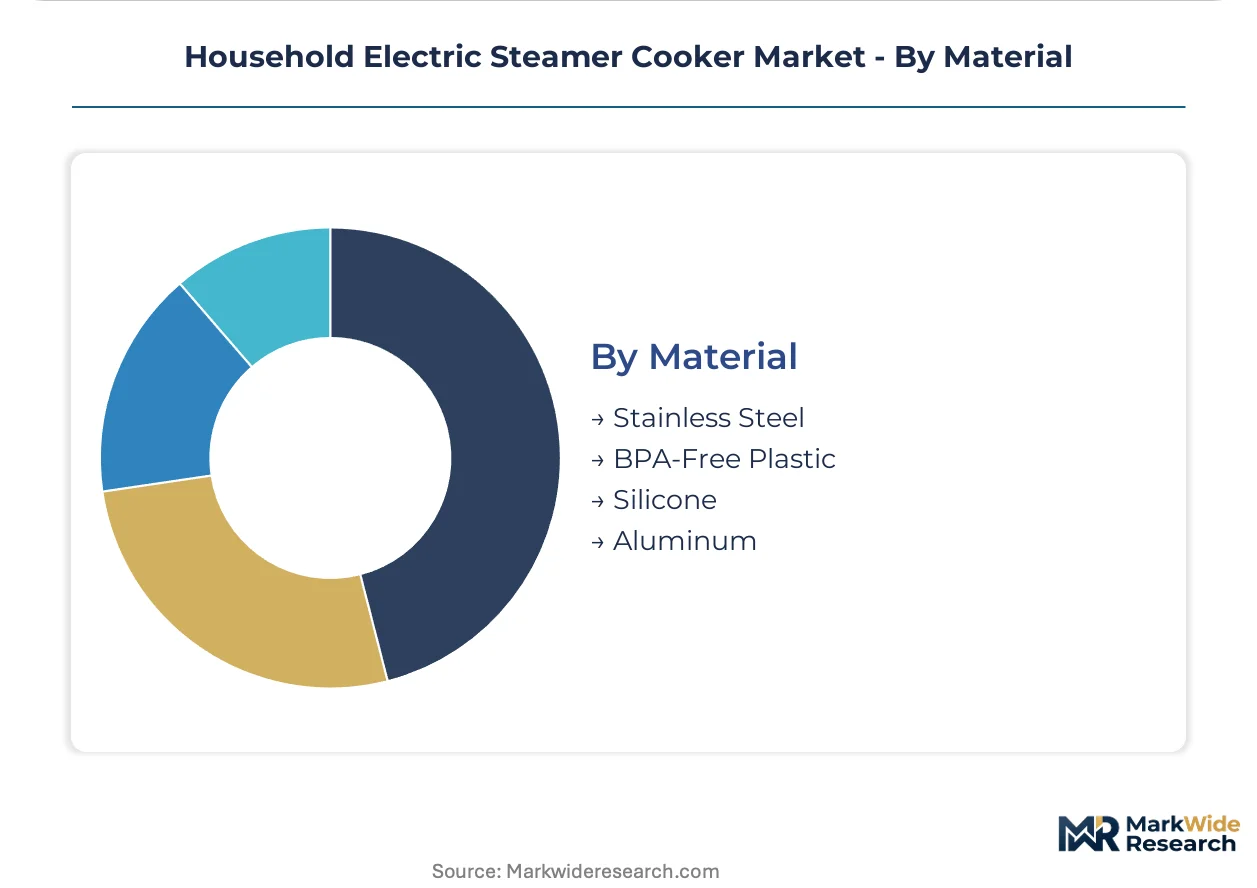
Segmentation in the Household Electric Steamer Cooker Market reveals how manufacturers balance customization depth against production standardization. Product architecture, capacity scaling, interface complexity, and material selection each create distinct margin profiles and compliance obligations across regional markets.
Product Type:
Customization intensity varies sharply across this category, from single-purpose appliances to modular systems displacing multiple kitchen devices.
- Multi-Functional Cooker:Integrated pressure-steam combinations and rice-steam hybrid chambers command premium shelf positioning. Demand concentrates in China's tier-one cities where apartment kitchens under 8 square meters reward space consolidation. Philips and Panasonic anchor this tier through precision temperature modules.
- Countertop Steamer:Fixed-base atmospheric steam generators between 100°C and 120°C serve as category entry points. North American mass-market retailers in the United States prioritize these units for seasonal promotional cycles, though replacement intervals stretch to seven years.
- Stackable Steamer:Modular tray systems allow capacity adjustment through vertical layering. Hamilton Beach dominates this configuration through value-tier positioning in big-box channels.
- Portable Steamer:Compact units under 2 liters target single-person households and travel use cases. India's metropolitan corridors show emerging traction among young professionals in shared housing.
Leading the category by volume: Countertop Steamer. Growing fastest: Multi-Functional Cooker.
Capacity:
Volume scaling in this category maps directly to household composition and meal-prep batch economics rather than premium positioning.
- 3-5 Liters:The dominant configuration for three-to-four-person households balancing daily cooking against storage constraints. China's urban districts favor this segment for dinner-plus-lunch batch preparation. EU Ecodesign standby power thresholds apply uniformly regardless of capacity tier.
- 5-7 Liters:Extended-family and meal-prep service applications drive specification requirements here. South Korea's senior care channels specify these units for texture-modified diet programs serving dysphagia patients.
- 1-3 Liters:Single-occupancy and dormitory settings in Japan's dense urban cores sustain this tier despite limited absolute volume.
- Above 7 Liters:Commercial-adjacent specifications for home-based catering operations in India's tier-two cities. BIS certification complexity deters informal suppliers.
Highest shipment volumes: 3-5 Liters. Steepest expansion trajectory: 5-7 Liters.
Control Type:
Interface sophistication in this category is accelerating replacement cycles as digital modules displace mechanical durability advantages.
- Digital Control:Microprocessor-driven PID temperature algorithms enable programmable nutrient-preservation protocols. Health-conscious millennials in China's tier-one cities compress replacement from seven years to four through connected feature adoption.
- Touch Control:Capacitive surfaces with e-ink or OLED feedback satisfy EU Ecodesign standby power thresholds below 0.5 watts. European market entry requires this architecture for regulatory compliance.
- Manual Control:Mechanical dial mechanisms persist in price-sensitive Indian rural markets and as backup specifications for elderly users.
- Remote Control:Smartphone-app and voice-assistant integration remains concentrated in North American direct-to-consumer channels. Firmware security certification under UL 2900 extends development timelines.
Dominant installed base: Manual Control. Gaining share fastest: Digital Control.
Material:
Supply-side input cost volatility and regulatory substance restrictions dominate material selection trade-offs in this category.
- Stainless Steel:304-grade and 316-grade variants command durability and food-contact safety premiums. REACH substance restrictions on phthalates accelerate migration from plastics toward these specifications in European markets. Nickel and chromium price volatility compresses margins for mid-tier manufacturers lacking long-term supply contracts.
- BPA-Free Plastic:Polypropylene and Tritan copolyester variants occupy entry-price tiers despite thermal degradation concerns above 110°C. India's BIS certification pipeline is formalizing migration testing requirements for these materials.
- Silicone:Foldable and collapsible steamer inserts target travel and storage-constrained applications. FDA food-contact substance notifications govern United States market access.
- Aluminum:Anodized variants offer thermal conductivity advantages for rapid steam generation. Japan's METI energy efficiency labeling favors these specifications for reduced heating element duty cycles.
Leading by revenue contribution: Stainless Steel. Expanding most quickly: BPA-Free Plastic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for household electric steamer cookers concentrates in urban clusters across China, India, Japan, South Korea, and the United States, where space-constrained kitchens and health-conscious meal preparation intersect. China's tier-one cities and India's metropolitan corridors anchor volume expansion, while regulatory mandates in Japan and South Korea reshape product specifications. North American direct-to-consumer channels disrupt traditional retail patterns.
China
Urban households in Shanghai, Beijing, and Shenzhen compress replacement cycles for manual steamers to four years through connected feature adoption. GB standards for household electrical appliances govern safety certification and energy efficiency labeling. The Yangtze River Delta manufacturing corridor supplies precision temperature control modules to domestic and export markets.
India
Young professionals in Mumbai, Delhi-NCR, and Bengaluru drive portable steamer adoption in shared housing and compact apartments. BIS certification requirements for small domestic appliances are formalizing safety standards and testing protocols. The Maharashtra-Gujarat industrial belt hosts assembly operations for entry-price tier models targeting mass-market distribution.
Japan
Senior care channels specify programmable steamers with texture-modification settings for dysphagia-friendly diets. METI energy efficiency labeling favors anodized aluminum specifications for reduced heating element duty cycles. The Kansai region around Osaka anchors precision component sourcing for temperature control systems.
South Korea
Meal-prep services and extended-family households demand 5-7 liter capacity units for batch cooking applications. MFDS food-contact substance regulations shape material selection for steam chambers and tray inserts. The Seoul Capital Area concentrates smart kitchen platform development and firmware integration capabilities.
United States
Health-focused millennials in coastal metros adopt app-connected models through subscription-box bundling and influencer-driven launches. FDA food-contact substance notifications and UL 1026 safety standards govern market access and retail distribution. The Pacific Northwest and Northeast Corridor host direct-to-consumer kitchenware startups bypassing big-box showroom dependence.
Household Electric Steamer Cooker Market Competitive Landscape
East Asian producers anchor the premium tier through precision engineering and component integration; North American and European specialists hold value-tier and design-focused positions through brand recognition and retail channel access. The vendor base fragments across three strategic archetypes: diversified appliance conglomerates with R&D intensity, single-category specialists with manufacturing scale, and direct-to-consumer entrants with platform-native marketing. Competitive moves concentrate on smart kitchen ecosystem partnerships and energy-efficient architecture redesigns to satisfy tightening regulatory thresholds.
Within the diversified conglomerate tier, Philips and Panasonic exemplify integrated players leveraging precision temperature control systems and geographic channel dominance. Hamilton Beach occupies a position among North American mass-market specialists with stackable, value-tier configurations. Braun GmbH represents European engineering-focused positioning through durable construction and regulatory compliance architecture. These three anchors illustrate how competitive positioning stratifies across R&D intensity, manufacturing scale, and regional channel access rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Philips |
| Panasonic |
| Breville |
| Hamilton Beach |
| Cuisinart |
| Braun GmbH |
| Morphy Richards |
| German Pool Group |
| Russell Hobbs |
| Others |
Pricing and Supply Chain Analysis
Nickel and chromium alloy costs cascade from Yangtze River Delta smelters through three pricing tiers, with 304-grade stainless steel premiums widening against BPA-free plastic alternatives as REACH substance restrictions tighten material specifications in European markets. Buyers in China's tier-one cities absorb connected-feature premiums while Indian mass-market channels resist price escalation beyond entry-tier thresholds.
Pricing Analysis
Volume concentrates in manual-control countertop steamers sold through North American big-box retailers, while margins pool in multi-functional cookers with PID temperature modules targeting health-conscious millennials in Shanghai and Shenzhen. Price differentiation hinges on certification grade—UL 1026 and UL 2900 cybersecurity validation command 15-20% premiums—and brand equity anchored by precision engineering heritage. Pricing pressure stems from nickel price volatility compressing mid-tier stainless steel variants, with Hamilton Beach and value-tier specialists most exposed to buyer price sensitivity in Indian rural markets and North American promotional cycles.
Supply Chain Analysis
Workforce availability in Guangdong province and the Maharashtra-Gujarat corridor shapes assembly capacity scaling, with precision temperature control module production concentrating in South Korea's Seoul Capital Area and Japan's Kansai region. Raw material dependencies center on nickel-chromium alloys from Indonesian smelters, polypropylene resin from Saudi petrochemical complexes, and ceramic heating elements from Taiwanese specialists. Supply chain risk manifests in single-source vulnerability for PID control firmware from East Asian component houses. Distribution runs through big-box retail partnerships in North America, appliance specialty chains in Europe, and direct-to-consumer platforms bypassing traditional showroom dependence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable suppliers as EU Ecodesign standby power mandates and UL 2900 cybersecurity certification timelines eliminate margin-poor competitors unable to fund 4-6 month development extensions.
For Market Incumbents: Deepen backward integration into precision temperature sensor sourcing to offset East Asian component concentration risk, while accelerating e-ink display adoption to secure European market access ahead of REACH enforcement deadlines. Philips and Panasonic should leverage existing R&D infrastructure to capture senior care channel specifications in Japan and South Korea before specialized dysphagia-friendly competitors emerge. For New Entrants and Emerging Players: Enter via India's BIS certification pipeline before formalized testing protocols close the window for informal suppliers, targeting young professionals in Mumbai and Bengaluru with portable steamer configurations under 2 liters. Direct-to-consumer launches through TikTok-native content demonstrate multi-functional capabilities to bypass established retail gatekeepers, mirroring successful North American kitchenware startup trajectories. For Investors and Strategic Acquirers: First-mover BIS certification completion is the leading indicator that a supplier has secured viable Indian distribution infrastructure worth premium valuation multiples. Acquisition targets should display captive supply relationships with Yangtze River Delta heating element manufacturers and firmware engineering teams with embedded security expertise. Long-term viability hinges on smart kitchen platform interoperability rather than isolated appliance sales, making connected-feature development capacity the critical diligence focus.| Strategic Initiative | Industry Significance |
|---|---|
| Energy-Efficient Architecture Redesign | EU Ecodesign compliance secures European market access and eliminates non-compliant competitors. |
| Smart Kitchen Platform Integration | Firmware partnerships with voice assistants transform steamers into ecosystem nodes driving replacement cycles. |
| Senior Care Channel Specification | Texture-modification settings for dysphagia diets open underpenetrated Japan and South Korea segments. |
| Direct-to-Consumer Channel Launch | TikTok-native content bypasses big-box retail dependence among younger household formations. |
| Backward Integration into Component Sourcing | Captive supply of precision temperature modules mitigates East Asian supplier concentration risk. |
Research Methodology
Document review covered customs records, appliance retail audit data, and regulatory filing databases including FDA food-contact substance notifications and EU Ecodesign directive implementations, complemented by interviews with product development executives at diversified appliance conglomerates, procurement managers at North American big-box retailers, regulatory affairs specialists navigating BIS certification pipelines, and channel partners in India's Maharashtra-Gujarat industrial belt. Secondary validation drew from SEC filings of publicly traded kitchen appliance manufacturers, GB standards documentation from China's Standardization Administration, and METI energy efficiency labeling guidelines. Bottom-up shipment data triangulated against top-down consumer expenditure estimates across the analysis window.
Cross-referencing historical replacement cycle compression patterns with expert panel input on smart kitchen adoption trajectories anchored the analytical framework across product type, capacity tier, control interface sophistication, and material specification segments. CAGRs were derived from regression analysis of urban household formation rates, health-conscious cooking protocol adoption curves, and regulatory enforcement timeline modeling. Industry-specific forecast inputs incorporated nickel price volatility scenarios and firmware security certification completion rates.
Revisions become necessary when EU Ecodesign standby power thresholds tighten beyond 0.5 watts, BIS certification enforcement accelerates ahead of published timelines, or induction cooking substitution rates exceed modeled expectations in premium kitchen segments. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Undercounter Refrigerators Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market