
 Russia Laundry Appliances Market | 2026-2036
Russia Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Laundry Appliances Market Analytics
Stainless steel drum assemblies is restructuring cost structures across mid-tier washing machine lines as manufacturers substitute traditional enamel-coated carbon steel to reduce corrosion warranty claims. Haier Group leverages captive motor production facilities in Russia to shield margin pools from currency volatility. BSH Hausgeräte sustains premium positioning through extended-cycle heat pump dryer engineering. Atlant Inc. anchors its competitive stance with localized assembly in Minsk that feeds duty-advantaged distribution into the Russian Federation.
Laundry appliances encompass electrically powered equipment designed for fabric cleaning, drying, and finishing operations, with drum capacities typically spanning five to twelve kilograms and spin speeds reaching fourteen hundred revolutions per minute for residential units. Front load technology commands the dominant revenue position due to superior water efficiency metrics and stackable installation profiles that suit compact urban dwellings. Smart appliance connectivity is expanding fastest among technology segments as Wi-Fi-enabled cycle management and energy monitoring integrate with multi-unit housing management systems. Commercial laundries represent a concentrated margin pool within end user segmentation, where equipment durability specifications and service contract structures generate recurring revenue streams distinct from household replacement cycles.
BIS-aligned EAC certification requirements and Russia's national GOST R standards govern electromagnetic compatibility and energy consumption labeling for imported and domestically produced laundry equipment. The Federal Tariff Service shapes demand patterns through time-of-use electricity pricing that incentivizes delayed-cycle operation in connected appliances. Stakeholders must monitor regulatory alignment between Eurasian Economic Union technical regulations and evolving EU ecodesign directives that could redirect supply chain certification costs for manufacturers serving both markets.
Market Dynamics
Inverter motor platforms are restructuring competitive cost structures across Russia's laundry appliance sector as manufacturers retool assembly lines to meet Eurasian Economic Commission energy efficiency mandates. This technology migration compresses margin pools for importers while rewarding localized motor production.
Growth Catalysts
- Urban Renewal Programs:Moscow's municipal housing stock modernization is absorbing premium front-load washing machines through developer procurement contracts tied to multi-apartment residential complexes.
- EAC Technical Regulations:The Eurasian Economic Commission's harmonized energy efficiency standards are accelerating inverter motor adoption by removing non-compliant imports from duty-advantaged channels.
- Heat Pump Engineering:Extended-cycle heat pump dryer technology is penetrating premium residential segments as water-scarce regions prioritize condensation-free drying solutions.
Market Restraints
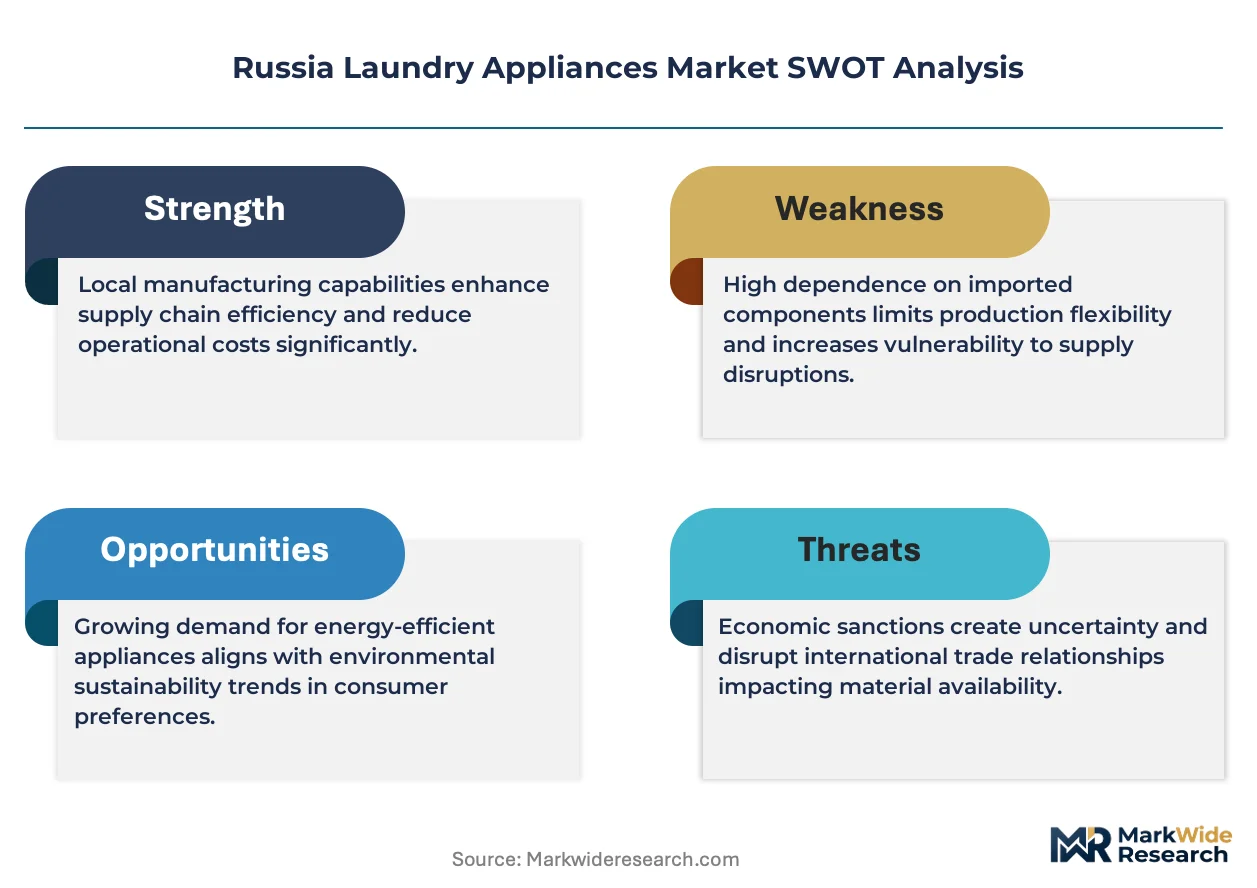
- Currency Volatility:Ruble-denominated input costs for imported electronic control modules create margin instability for distributors without captive hedging arrangements.
- Carbon Steel Substitution Limits:Stainless steel drum assemblies carry 15-20% material cost premiums that resist full penetration in economy-tier product lines.
- GOST R Certification Friction:Electromagnetic compatibility testing timelines for Wi-Fi-enabled appliances extend market entry windows by 8-12 weeks versus conventional models.
Strategic Opportunities
- Smart Connectivity Integration:Wi-Fi-enabled cycle management systems are converging with multi-unit housing management platforms in St. Petersburg's new-build residential developments.
- Commercial Laundry Services:Equipment-as-a-service contracts with durability specifications are opening recurring revenue streams distinct from household replacement cycles.
- Time-of-Use Pricing Arbitrage:The Federal Tariff Service's delayed-cycle electricity incentives are creating demand for programmable load-shifting appliances.
Industry Challenges
- Regulatory Alignment Complexity:Divergence between Eurasian Economic Union technical regulations and evolving EU ecodesign directives is forcing dual certification investments for manufacturers serving both markets.
- Stackable Installation Engineering:Compact urban dwelling specifications demand vertical integration of washer-dryer combinations that strain domestic service network capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Laundry Appliances Market |
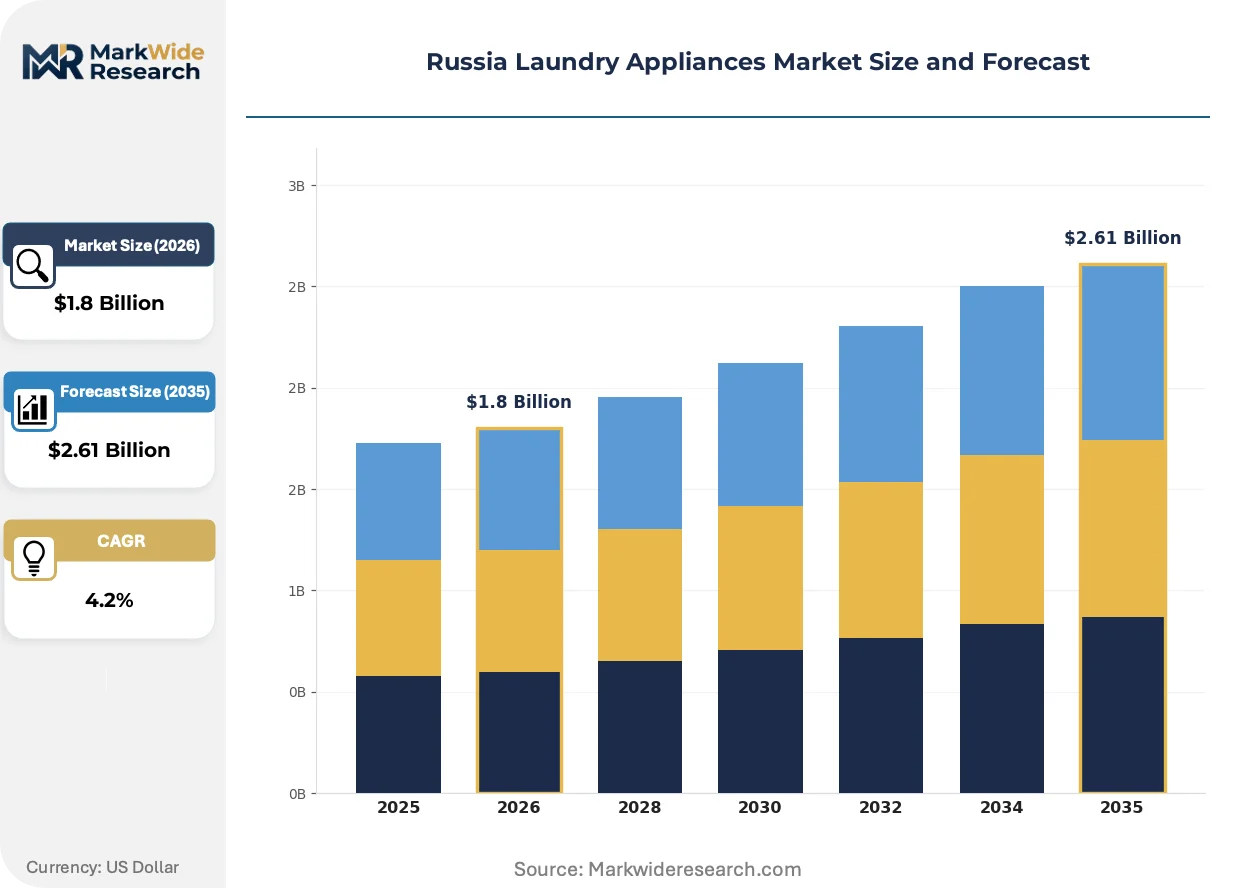
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
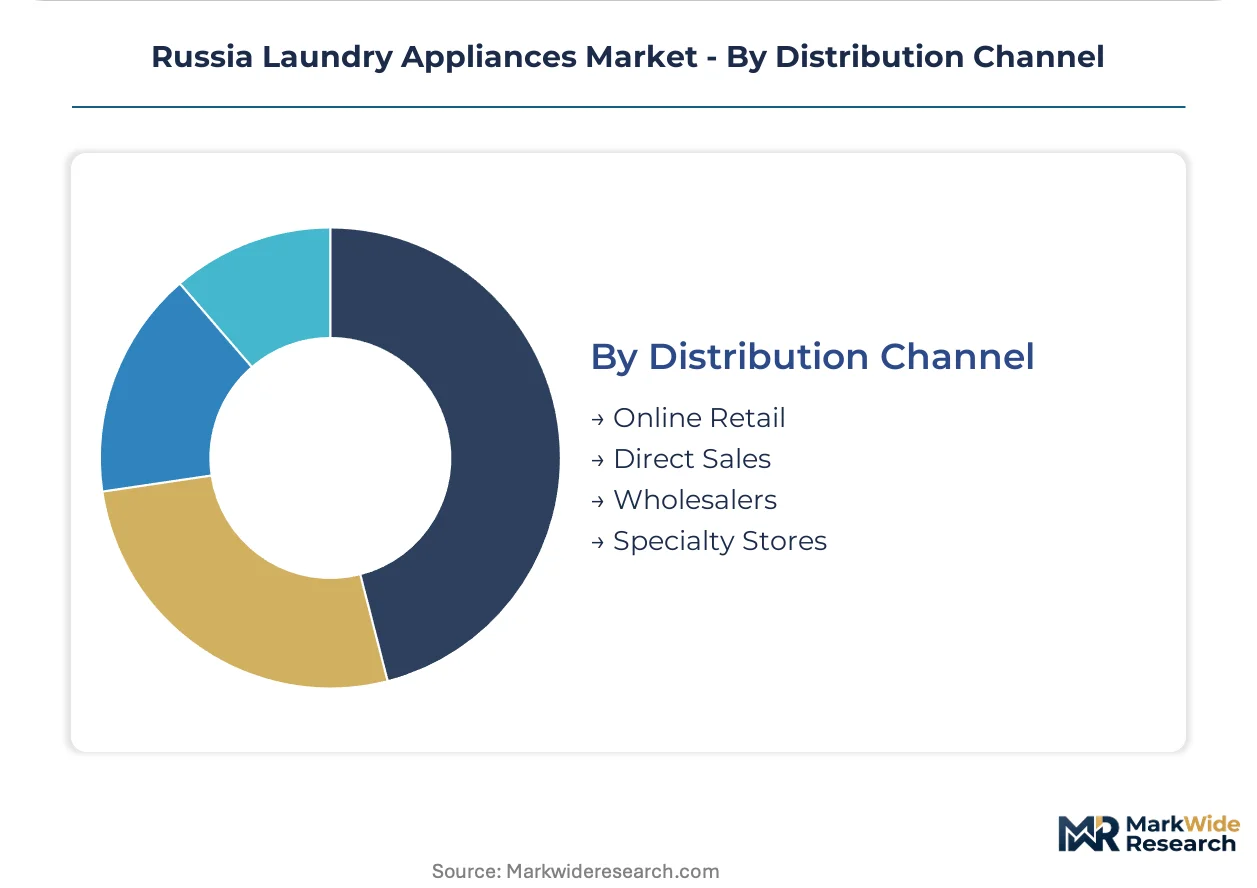
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Ironing Machines End User: Households, Commercial Laundries, Hotels, Fitness Centers Technology: Front Load, Top Load, Smart Appliances, Heat Pump Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Whirlpool Corp. / Indesit, Haier Group, BSH Hausgeräte (Bosch & Siemens), Midea Group, Atlant Inc., LG Electronics, Electrolux AB, BEKO (Arçelik), Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Laundry Appliances Market Evolving Landscape
Connected appliance architectures are redefining value capture in Russia's laundry equipment sector. Manufacturers are embedding telemetry systems that transform one-time hardware sales into ongoing service relationships.
Inverter motor technology is unifying variable-speed drum control with energy consumption optimization across residential product tiers. Developers in Moscow's premium residential complexes are specifying these platforms at accelerated procurement schedules. This unification is compressing price premiums between mid-tier and premium efficiency categories.
Eurasian Economic Commission technical regulations on electromagnetic compatibility are mandating redesigned control board shielding for all imported laundry equipment. Domestic assemblers in the Central Federal District are capturing volume by pre-certifying platforms to GOST R standards. Wi-Fi-enabled appliances face the steepest compliance cost escalation due to dual radio-frequency testing requirements.
Delayed-cycle operation preferences are spreading among multi-apartment residents responding to Federal Tariff Service time-of-use electricity pricing. Property management platforms in St. Petersburg are aggregating appliance control across housing units to optimize building-level demand profiles. This behavioral shift is most visible in new-build stock where smart infrastructure was pre-installed during construction phases.
Russia Laundry Appliances Market Segmentation
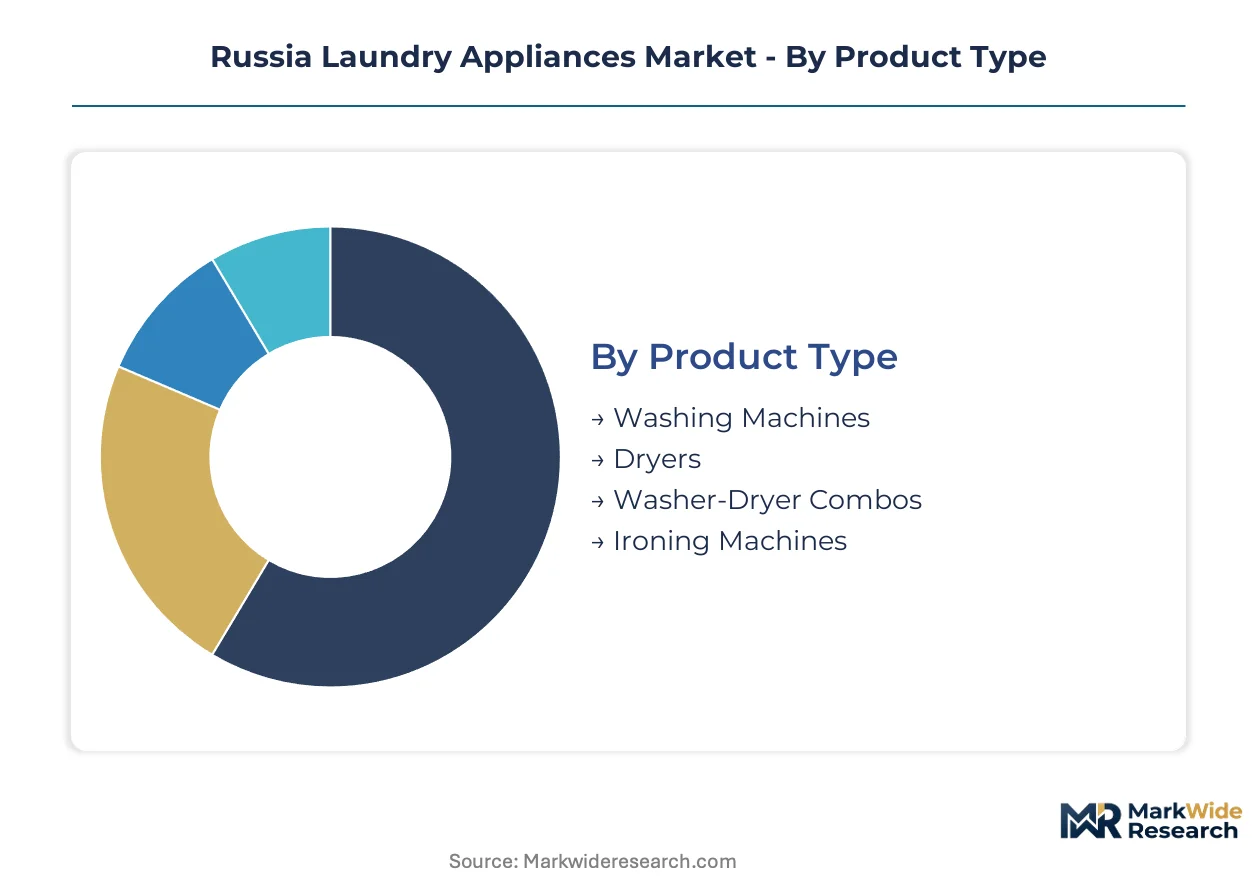
Segmentation in Russia's laundry appliance market exposes divergent certification burdens and margin structures across product tiers. EAC technical regulations and GOST R electromagnetic compatibility standards create asymmetric compliance costs that reshape competitive positioning in each category.
Product Type:
EAC certification intensity varies sharply by product type, with heat pump-bearing appliances facing dual energy efficiency and refrigerant safety testing protocols.
- Washing Machines:Drum capacities spanning five to twelve kilograms dominate procurement specifications for Moscow's multi-apartment residential complexes. Front-load configurations absorb the majority of developer contracts tied to urban renewal programs, with stainless steel drum assemblies displacing enamel-coated carbon steel in mid-tier lines to reduce warranty exposure.
- Dryers:Heat pump engineering commands extended-cycle certification timelines under Eurasian Economic Commission technical regulations, compressing import windows for non-localized manufacturers. Condensation-free drying solutions concentrate demand in water-scarce regions of the Central Federal District where municipal supply constraints shape appliance specifications.
- Washer-Dryer Combos:Stackable installation profiles suit compact urban dwellings in St. Petersburg's new-build developments, though combined mechanical complexity strains domestic service network capabilities.
- Ironing Machines:Lower certification friction under GOST R standards relative to motor-driven appliances enables faster market entry for specialized distributors.
Leading the category by volume: Washing Machines. Growing fastest: Dryers with heat pump engineering.
End User:
Customer type determines service contract structures and replacement cycle predictability, with commercial accounts generating recurring revenue distinct from household discretionary purchases.
- Households:Individual purchasers respond to Federal Tariff Service time-of-use electricity pricing, creating demand for programmable load-shifting appliances with Wi-Fi-enabled delayed-cycle operation. Replacement cycles average seven to ten years, with demand concentrating in the Central Federal District's urban renewal zones.
- Commercial Laundries:Equipment-as-a-service contracts with durability specifications above residential standards generate recurring revenue streams. Service-level agreements mandate inverter motor platforms to minimize downtime exposure in high-throughput operations.
- Hotels:Procurement runs through hospitality management groups specifying stackable configurations for space-constrained back-of-house installations in Moscow and St. Petersburg properties.
- Fitness Centers:towel-processing volume requirements favor compact commercial units with accelerated cycle times, though segment scale remains limited relative to hospitality verticals.
Households dominate absolute unit demand. Commercial Laundries deliver the steepest expansion trajectory through service contract penetration.
Technology:
Technology choice dictates motor platform requirements and electromagnetic compatibility testing scope under harmonized EAC standards.
- Front Load:Superior water efficiency metrics and stackable installation profiles command dominant revenue position in premium urban segments. EAC energy efficiency mandates accelerate inverter motor adoption, removing non-compliant imports from duty-advantaged channels.
- Top Load:Economy-tier positioning resists full stainless steel drum penetration due to material cost premiums, preserving enamel-coated carbon steel in price-sensitive configurations.
- Smart Appliances:Wi-Fi-enabled cycle management integrates with multi-unit housing management systems in St. Petersburg's new-build residential developments. Dual radio-frequency testing requirements extend GOST R certification timelines by 8-12 weeks versus conventional models.
- Heat Pump:Extended-cycle engineering penetrates premium residential segments as water-scarce regions prioritize condensation-free drying, though control board shielding redesigns escalate compliance costs for imported equipment.
Front Load technology holds the largest revenue share. Smart Appliances are climbing the fastest as property management platforms aggregate building-level demand optimization.
Distribution Channel:
Channel selection determines inventory risk allocation and margin capture, with direct sales relationships insulating manufacturers from ruble volatility.
- Online Retail:E-commerce platforms absorb growing share of replacement-cycle purchases, particularly for Wi-Fi-enabled appliances where specification transparency reduces pre-purchase consultation needs. Logistics networks concentrate in Moscow and St. Petersburg metropolitan zones.
- Direct Sales:Developer procurement contracts for multi-apartment residential complexes bypass wholesale intermediaries, enabling captive hedging arrangements against currency volatility for manufacturers with localized assembly.
- Wholesalers:Inventory risk concentrates in distributor networks serving secondary cities, with margin compression from inverter motor platform cost migration.
- Specialty Stores:Consultative sales environments retain relevance for heat pump and smart appliance categories where installation complexity demands technical guidance.
Online Retail is expanding most quickly in unit terms. Direct Sales captures the highest revenue concentration through developer contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Russia's Central Federal District, where Moscow's urban renewal programs and new-build residential stock absorb premium front-load washing machines at scale. Developer procurement contracts tied to multi-apartment complexes are reshaping distribution patterns across the federation.
Central Federal District
Moscow anchors absolute volume demand through municipal housing stock modernization and premium residential development. The Eurasian Economic Commission's technical regulations on energy efficiency are accelerating inverter motor adoption across developer specifications. Industrial clusters in the Moscow metropolitan zone concentrate assembly operations for duty-advantaged distribution into surrounding oblasts.
Northwestern Federal District
St. Petersburg's new-build residential developments are integrating Wi-Fi-enabled appliances with multi-unit housing management platforms. The Federal Tariff Service's time-of-use electricity pricing is incentivizing delayed-cycle operation preferences among apartment residents. Logistics networks in the Baltic port corridor facilitate component import for localized assembly operations serving this demand cluster.
Volga Federal District
Kazan and Nizhny Novgorod are absorbing mid-tier washing machine volume through replacement cycles in Soviet-era housing stock. GOST R certification requirements for electromagnetic compatibility are extending market entry timelines for imported electronic control modules. Regional distributors are consolidating inventory positions to manage ruble-denominated input cost volatility.
Southern Federal District
Rostov-on-Don and Krasnodar are experiencing demand expansion from residential construction in water-scarce regions where condensation-free drying solutions command specification priority. The Eurasian Economic Union's harmonized standards are removing non-compliant imports from duty-advantaged channels. Local retail networks are prioritizing heat pump engineering in premium segment positioning.
Ural Federal District
Yekaterinburg's industrial base supports component fabrication for captive motor production facilities shielding margin pools from currency volatility. Secondary city distributors face inventory risk concentration without hedging arrangements against ruble fluctuation. Regional procurement patterns favor economy-tier configurations resisting full stainless steel drum penetration due to material cost premiums.
Russia Laundry Appliances Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among European-origin portfolios and volume production gravitating toward Asia-Pacific fabrication networks. The vendor base organizes around three strategic archetypes: diversified appliance conglomerates with captive component production, regional specialists leveraging localized assembly for duty advantages, and scale-driven OEMs supplying private-label channels. Consolidation pressure is mounting through inverter motor platform standardization and EAC certification cost escalation. Strategic moves center on backward integration into motor production and pre-certification of platforms to GOST R standards.
Within the diversified conglomerate tier, Whirlpool Corp. and Haier Group exemplify contrasting geographic origins and structural approaches to the Russian market. BSH Hausgeräte GmbH anchors premium-tier positioning through European engineering heritage. These three entities occupy distinct competitive spaces—American portfolio breadth, Chinese scale integration, and German precision positioning—without overlapping segment focus.
| Leading Market Players |
|---|
| Whirlpool Corp. / Indesit |
| Haier Group |
| BSH Hausgeräte (Bosch & Siemens) |
| Midea Group |
| Atlant Inc. |
| LG Electronics |
| Electrolux AB |
| BEKO (Arçelik) |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
Steel price indices cascading from Black Sea commodity benchmarks compress margin pools across Russia's laundry appliance tiers, with stainless steel drum assemblies transmitting 15-20% material premiums into mid-tier product positioning while inverter motor platforms concentrate cost migration in premium segments.
Pricing Analysis
Volume concentration in economy-tier washing machines absorbs ruble-denominated input volatility, while margin capture clusters in heat pump dryer segments where extended-cycle engineering sustains premium positioning. Price differentiation hinges on EAC energy efficiency certification tiers and localized motor production depth, with pricing pressure intensifying in import-dependent electronic control modules as currency hedging costs escalate. Developer procurement contracts for Moscow multi-apartment complexes exhibit lowest price sensitivity, whereas secondary city distributors face acute margin compression without captive hedging arrangements.
Supply Chain Analysis
Eurasian Economic Union domestic-content requirements are redirecting component sourcing toward Belarus-based assembly operations and captive motor production facilities in the Moscow metropolitan zone. Supply concentration draws from China for electronic control modules, Germany for precision engineering components, and domestic Russian fabrication for steel drum assemblies. Single-source vulnerability concentrates in Wi-Fi-enabled control board imports subject to GOST R electromagnetic compatibility testing delays. Distribution runs through developer direct contracts in primary cities, with wholesale networks absorbing inventory risk in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EAC technical regulations on energy efficiency have erected a compliance moat around Russia's laundry appliance market, with inverter motor platform certification costs filtering out undercapitalized competitors and consolidating share among pre-certified domestic assemblers.
For Market Incumbents: Acquire captive motor production facilities to insulate margin pools from ruble volatility and currency-hedging cost escalation. BSH Hausgeräte's extended-cycle heat pump engineering demonstrates how technical differentiation defends positioning against Chinese scale players, while Haier Group's localized assembly in Russia illustrates backward integration into component fabrication as a barrier against import substitution pressures. For New Entrants and Emerging Players: EAC technical regulations on electromagnetic compatibility in the Eurasian Economic Union open a window for domestic pre-certified platform offerings that bypass 8-12 week certification delays facing Wi-Fi-enabled imports. White-space targets concentrate in St. Petersburg's new-build residential developments where smart appliance integration with multi-unit housing management systems remains underpenetrated, and in commercial laundry service contracts where equipment-as-a-service recurring revenue models are displacing transactional sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with localized assembly in Minsk or the Moscow zone that feed duty-advantaged distribution into the Russian Federation. Long-term viability rests on regulatory alignment capacity between Eurasian Economic Union technical regulations and potential EU ecodesign directive convergence, with the inflection signal to monitor being Federal Tariff Service acceleration of time-of-use electricity pricing adoption across multi-apartment housing stock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive inverter motor fabrication shields margin pools from ruble-denominated import cost volatility. |
| Pre-Certification to GOST R Standards | Domestic electromagnetic compatibility testing accelerates market entry windows versus import competitors. |
| Smart Appliance Platform Development | Wi-Fi-enabled cycle management integrates with St. Petersburg multi-unit housing management systems. |
| Commercial Laundry Service Contracts | Equipment-as-a-service recurring revenue displaces transactional household replacement cycles in high-throughput operations. |
| Developer Direct Procurement Relationships | Moscow urban renewal contracts bypass wholesale intermediaries and enable currency-hedging arrangements. |
Research Methodology
Multi-period observation of EAC certification timelines, GOST R electromagnetic compatibility testing windows, and Federal Tariff Service electricity pricing trajectories anchored the trend analysis, supplemented by interviews with appliance manufacturing plant managers, procurement leads at Moscow developer firms, Eurasian Economic Commission regulatory affairs specialists, and aftermarket service network heads. Secondary validation drew from Eurasian Economic Commission technical regulation filings, Russian customs import data, GOST R certification registry records, and municipal housing modernization procurement disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches distributed volume and value estimates across product type, end user, technology, and distribution channel dimensions, with additional granularity applied to regional Federal District clustering. CAGRs were derived from regression analysis of historical procurement patterns and projected replacement cycle timing, incorporating inverter motor adoption curves, smart appliance penetration rates in new-build residential stock, and commercial laundry service contract expansion as industry-specific forecast inputs throughout the modeling period.
The model assumes a particular technology adoption path; alternative pathways for heat pump dryer engineering or Wi-Fi-enabled smart appliance integration would alter the outlook. Forecasts reflect assumptions regarding EAC regulatory stability, ruble exchange rate bands, and Federal Tariff Service pricing policy continuity, with revision triggers including divergence between Eurasian Economic Union and EU ecodesign directives, or acceleration of domestic-content requirement enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Range Hood Market
Home Appliances
Germany Washing Machine Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Canada Home Appliances Market
Home Appliances
European Built-In Refrigerator Market
Home Appliances
Electric Fireplace Market
Home Appliances
Household Appliance Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
Germany Small Home Appliance Market