
 Refrigerator Market | 2026-2036
Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerator Market Analysis
Software-defined temperature management is repositioning refrigerator value chains toward recurring revenue models. Samsung Electronics leverages its IoT platform to sustain consumer engagement beyond the point of sale. Haier anchors its growth through connected kitchen ecosystems that integrate with meal-planning services. Whirlpool differentiates via predictive maintenance algorithms that reduce service costs for commercial clients.
A refrigerator is a thermally insulated cabinet employing vapor-compression refrigeration to maintain temperatures between 0°C and 4°C for fresh compartments and below −18°C for freezer sections, using refrigerants such as R-600a or R-134a circulated through evaporator and condenser coils. French Door configurations command premium positioning in residential markets due to ergonomic access and flexible storage zones. Energy-Efficient technology segments face tightening margin pressure as regulatory baselines rise, while Smart Refrigerators concentrate software value and data monetization potential. Food Service end users prioritize rapid-recovery compressors and stainless-steel construction for compliance with health codes.
The US Department of Energy sets minimum efficiency standards under ENERGY STAR certification, while the EPA regulates refrigerant phase-downs through its SNAP program to limit high-GWP substances. The EU F-Gas Regulation and Ecodesign requirements compel manufacturers to redesign cooling systems for lower environmental impact. Stakeholders must monitor refrigerant transition timelines and efficiency standard trajectories to align R&D pipelines with compliance deadlines.
Market Dynamics
Compressor electrification and refrigerant chemistry transitions are forcing simultaneous retooling of manufacturing lines and service infrastructure across the refrigerator value chain. The EPA's SNAP program and EU F-Gas Regulation are accelerating capital deployment into alternative cooling systems before amortization cycles complete.
Growth Catalysts
- Food Service Cold-Chain Expansion:Commercial kitchens in the United States are retrofitting under-counter and reach-in units to comply with FDA Food Code temperature logging mandates. Rapid-recovery compressor demand from restaurant chains is pulling premium equipment through distribution.
- ENERGY STAR 7.0 Baseline Elevation:The US Department of Energy's tightened efficiency thresholds are compelling residential replacement cycles. Manufacturers are engineering variable-speed compressors and vacuum-insulated panels to clear certification hurdles.
- Urban Household Upgrades in China:Tier-1 and Tier-2 cities are shifting from single-door to multi-door configurations. SAMR energy-labeling requirements and living-space constraints are steering demand toward French Door and Side-by-Side formats with embedded icemakers.
Market Restraints
- Copper and Aluminum Price Volatility:Condenser coil and compressor motor materials constitute 18-22% of bill-of-materials exposure. Spot-market swings in Shanghai and London Metal Exchange pricing compress assembler margins during contract negotiation windows.
- Refrigerant Supply Concentration:R-600a (isobutane) and R-1234yf production clusters in Chinese and Middle Eastern chemical complexes. Geopolitical friction or export-license restrictions threaten just-in-sequence delivery for European and North American assembly plants.
- Low-GWP Alternative Technical Limits:Hydrocarbon refrigerants face charge-size caps under IEC 60335-2-89 safety standards. System redesign for larger commercial cabinets requires costly secondary-loop architectures that extend development timelines.
Strategic Opportunities
- India PLI Scheme for White Goods:The government's production-linked incentive scheme offers 4-6% cashback on incremental sales. Greenfield manufacturing in Tamil Nadu and Andhra Pradesh can serve domestic demand and Middle East export corridors with tariff advantages.
- Predictive Maintenance Subscriptions:Vibration-sensor and current-signature monitoring bundled with commercial service contracts. Food Service operators in Germany and Japan are piloting per-cubic-meter uptime guarantees that shift revenue from hardware to performance.
- Refrigerant-as-a-Service Models:Chemical leasing arrangements where suppliers retain ownership of working fluid and handle recovery. The EU F-Gas Regulation's phase-down quotas are creating compliance-driven demand for closed-loop refrigerant management in supermarket chains.
Industry Challenges
- Field Technician Certification Gaps:Hydrocarbon and mildly flammable HFO handling requires specialized training that outpaces vocational pipeline output. The EPA's Section 608 technician program and EU F-Gas company certification are creating bottlenecks for service-network scaling.
- Legacy Control System Integration:Smart refrigerator IoT platforms must interface with existing Building Management Systems in commercial installations. BACnet and Modbus protocol fragmentation across aged HVAC infrastructure complicates unified fleet monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerator Market |
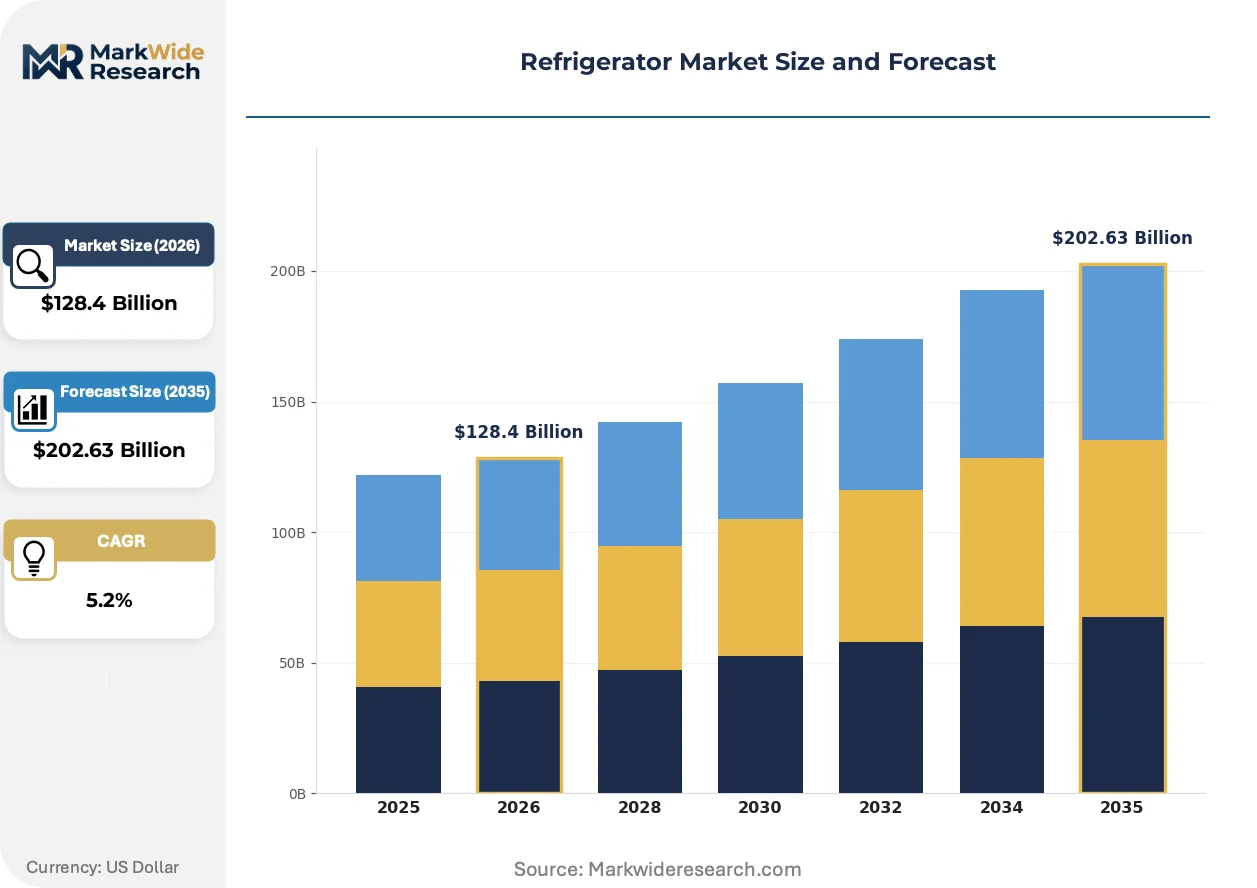
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $202.63 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: French Door, Side-by-Side, Top-Freezer, Bottom-Freezer End User: Residential, Commercial, Hospitality, Food Service Technology: Smart Refrigerators, Energy-Efficient, Two-Door, Multi-Door Size: Compact, Standard, Large Capacity, Built-In |
| Companies Covered | Samsung Electronics, Electrolux, Whirlpool, Haier, Frigidaire, GE Appliances, Bosch, Carrier, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerator Market Emerging Trajectories
Software-defined functionality is migrating from consumer electronics into thermal appliances, rewiring how value is captured and how products age in the field. This shift is compressing traditional hardware-only margins while opening recurring-revenue architectures.
Vacuum-insulated panel (VIP) technology is unifying slim-wall construction with superior thermal resistance in premium residential segments. German and Japanese manufacturers are embedding VIP cores into French Door cabinets to reclaim interior volume without exterior footprint expansion. This materials convergence is compressing polyurethane foam dependence and enabling compliance with tightening envelope-efficiency codes.
The EU F-Gas Regulation's 2024 step-down in HFC quota allocations is forcing refrigerant-transition roadmaps across European production lines. System engineers are redesigning evaporator circuits for R-290 (propane) and R-600a to maintain capacity within charge-size limits. Commercial cold-room and supermarket rack systems face the steepest retrofit obligations, with operators consolidating fleets to extend amortization against compliance deadlines.
Food Service procurement is fragmenting across direct-manufacturer, foodservice-equipment-dealer, and group-purchasing-organization channels. Large restaurant chains in the United States are consolidating specifications into national contracts with white-label provisions, while independent operators retain local-dealer relationships for service responsiveness. This bifurcation is visible in distributor consolidation patterns across Texas, California, and Florida metro corridors.
Refrigerator Market Segmentation
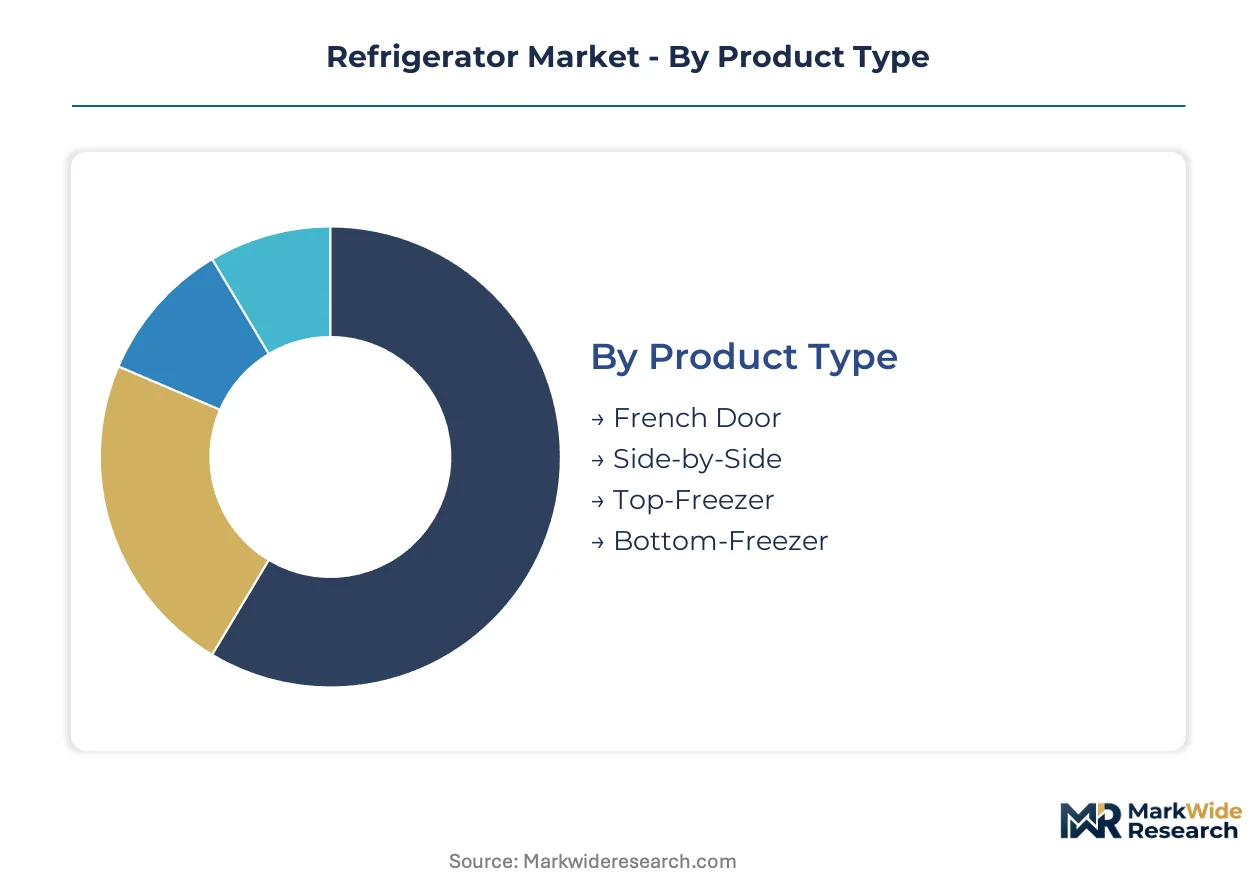
Refrigerator manufacturers engineer distinct product architectures to match thermal load profiles across residential kitchens, commercial food operations, and institutional hospitality settings. Segment boundaries increasingly blur as smart connectivity and variable-speed compressors migrate across form factors.
Product Type:
Supply concentration in compressor and panel sourcing favors configurations that maximize production line flexibility across regional assembly plants.
- French Door:Twin refrigerator doors above a pull-out freezer drawer optimize aisle clearance in narrow galley kitchens. Demand concentrates in US suburban renovations where SAMR energy-labeling requirements and living-space constraints steer purchases toward premium formats with embedded icemakers.
- Side-by-Side:Vertical freezer-refrigerator split delivers frozen access without bending, suited for mobility-limited households. Urban households in China Tier-1 cities are shifting from single-door to multi-door configurations, pulling Side-by-Side units through retail channels.
- Top-Freezer:Classic configuration with lowest bill-of-materials exposure targets replacement cycles in rental housing and budget-conscious segments.
- Bottom-Freezer:Refrigerator-at-eye-level design appeals to fresh-food-priority households in European markets with smaller average kitchen footprints.
Today's leader: French Door. Tomorrow's challenger: Side-by-Side.
End User:
Cost tier stratification separates specification-grade commercial equipment from mass-market residential units.
- Residential:Volume anchor consuming 70%+ of compressor output globally, with replacement cycles triggered by ENERGY STAR baseline elevations.
- Commercial:Rapid-recovery compressor demand from US restaurant chains pulls premium equipment through distribution to comply with FDA Food Code temperature logging mandates.
- Hospitality:Minibar and suite refrigeration specifications prioritize acoustic dampening and lockable storage for hotel operators.
- Food Service:Stainless-steel construction and health-code compliance dominate procurement, with German and Japanese operators piloting per-cubic-meter uptime guarantees.
Residential volumes anchor production planning. Food Service margins fund R&D recovery.
Technology:
Application-driven feature bundling concentrates software value in premium tiers while efficiency compliance reshapes base configurations.
- Smart Refrigerators:IoT-enabled inventory tracking and meal-planning integration command recurring-revenue potential. Samsung Electronics and Haier anchor growth through connected kitchen ecosystems that sustain consumer engagement beyond point of sale.
- Energy-Efficient:Variable-speed compressors and vacuum-insulated panels clear ENERGY STAR 7.0 certification hurdles, though tightening regulatory baselines compress margins.
- Two-Door:Simplified control architecture suits emerging market price sensitivity and grid-stability constraints.
- Multi-Door:Flexible temperature zones address diverse storage protocols for specialty diets and pharmaceutical cold chain extension.
Smart connectivity captures software value. Energy efficiency faces margin compression from rising baselines.
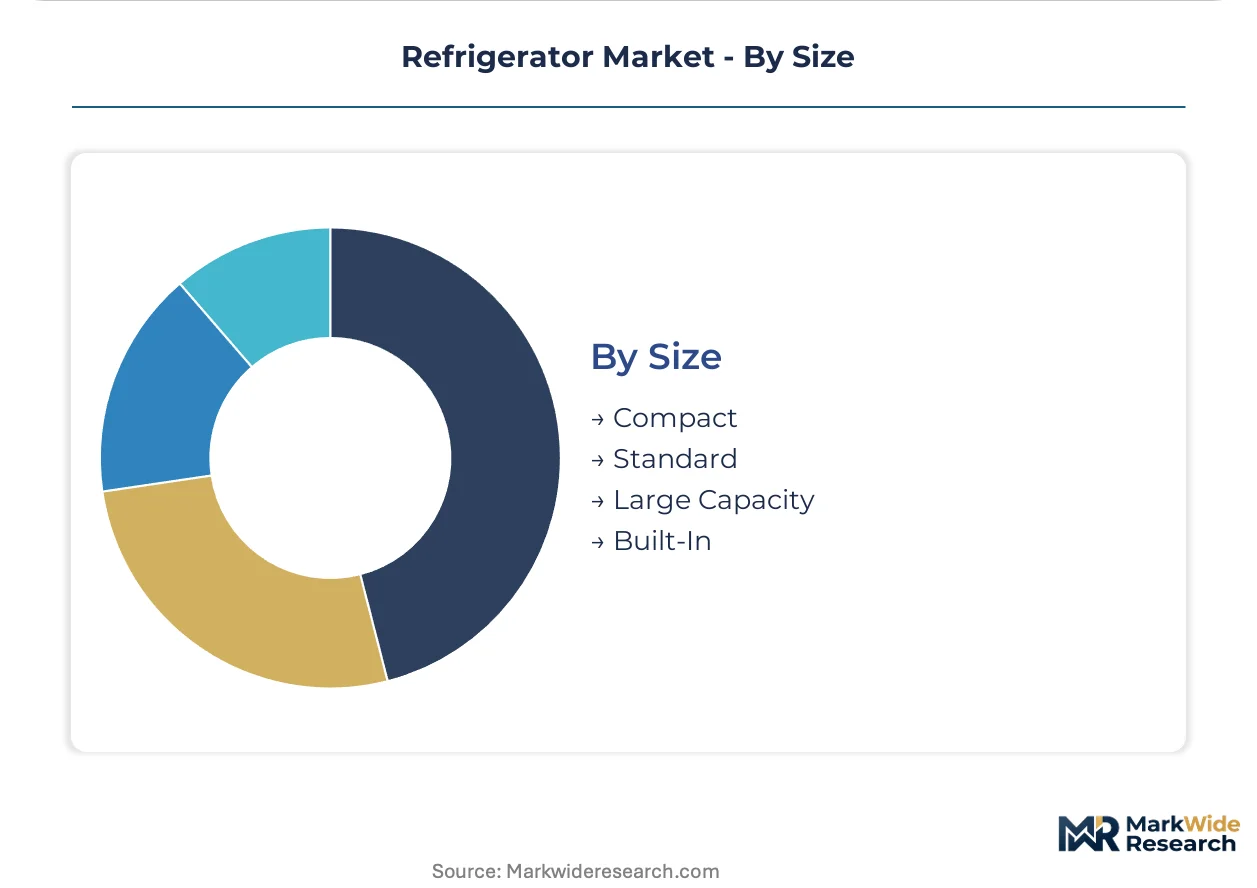
Size:
Customer type segmentation separates specification-driven built-in projects from standard-capacity replacement cycles.
- Compact:Under-counter and countertop units serve dormitory, office, and secondary kitchen applications with minimal footprint.
- Standard:18-22 cubic foot configurations dominate North American replacement demand and European apartment stock.
- Large Capacity:25+ cubic foot cabinets target US suburban households with bulk purchasing patterns and extended-family storage needs.
- Built-In:Panel-ready integration with custom cabinetry commands 3-4x price multiples in luxury residential and commercial kitchen design.
Standard capacity drives volume economics. Built-in specifications capture margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refrigerator production migrates toward jurisdictions where energy-efficiency compliance costs and refrigerant-phase-down obligations create arbitrage windows for capital deployment. Manufacturers reposition assembly capacity to exploit gaps between EPA SNAP timelines and EU F-Gas Regulation enforcement.
United States
Restaurant chains retrofit under-counter and reach-in units to satisfy FDA Food Code temperature-logging mandates. The EPA's SNAP program accelerates R-600a adoption timelines for domestic assembly plants. Texas and California metro corridors concentrate foodservice-equipment distribution networks serving independent operators.
China
Tier-1 and Tier-2 urban households upgrade from single-door to multi-door configurations including French Door and Side-by-Side formats. SAMR energy-labeling requirements steer demand toward premium formats with embedded icemakers. Yangtze River Delta manufacturing clusters supply compressor and panel components for domestic and export assembly.
Germany
Commercial operators pilot per-cubic-meter uptime guarantees that shift revenue from hardware to performance contracts. The EU F-Gas Regulation's 2024 quota step-down forces refrigerant-transition roadmaps across European production lines. Bavaria hosts vacuum-insulated panel R&D facilities serving premium residential segments.
India
The PLI scheme for white goods offers 4-6% cashback on incremental sales, attracting greenfield manufacturing investment. BIS certification requirements and FSSAI cold-chain protocols shape product specifications for domestic market entry. Tamil Nadu and Andhra Pradesh assembly plants target Middle East export corridors with tariff advantages.
Japan
Food Service operators demand predictive maintenance subscriptions bundled with commercial service contracts. METI efficiency standards and JIS certification protocols constrain import competition. Kansai manufacturing clusters specialize in compact and built-in configurations for space-constrained urban kitchens.
Refrigerator Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with residential markets consolidating around household-name recognition while commercial procurement fragments across specification-grade fabricators. The vendor base organizes into three tiers: full-line multinationals with connected-kitchen platforms, regional assemblers serving price-sensitive emerging markets, and niche specialists in built-in or medical-grade refrigeration. M&A activity concentrates on IoT software assets and compressor technology licensing. Geographic expansion through joint ventures dominates entry strategies into India and Southeast Asia.
Within the connected-appliance tier, Samsung Electronics and Haier exemplify platform-centric strategies that sustain consumer engagement beyond point of sale. LG Electronics occupies a position bridging residential premium positioning with commercial compressor supply. These three Korean and Chinese entities anchor the software-defined migration reshaping how thermal appliances capture recurring revenue.
| Leading Market Players |
|---|
| Samsung Electronics |
| Electrolux |
| Whirlpool |
| Haier |
| Frigidaire |
| GE Appliances |
| Bosch |
| Carrier |
| LG Electronics |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compressor specialists in Germany and Japan anchor premium pricing through captive R-600a technology and long-term service contracts with European supermarket chains. Their ownership structure insulates margin discipline from quarterly earnings pressure while funding vertical integration into vacuum-insulated panel production.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard-efficiency residential units. Three-tier pricing structure across premium smart-connected, standard inverter, and economy fixed-speed levels stratifies the market. Price differentiation rests on ENERGY STAR certification tier and after-sales service bundling. Pricing pressure stems from aluminum and copper spot volatility compressing assembler margins. Budget-conscious rental housing segments exhibit highest price sensitivity, while commercial food service operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Chinese white-goods assemblers, while foodservice-equipment dealers serve fragmented US restaurant operators. Manufacturing concentrates in China, Thailand, and Mexico. Raw material dependencies include copper condenser coils, aluminum compressor housings, and hydrocarbon refrigerant feedstocks. Supply chain risk centers on R-600a production concentration in Middle Eastern chemical complexes. Distribution runs through manufacturer-direct, specialized dealers, and group-purchasing-organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refrigerator market functions as a stable compounder anchored by regulatory-driven replacement cycles. Efficiency standard escalations and refrigerant phase-down mandates create predictable equipment refresh demand.
For Market Incumbents: Extend predictive maintenance subscription coverage to capture recurring revenue from commercial installed bases. Deepen backward integration into variable-speed compressor manufacturing to defend margins against copper price volatility. Secure EPA Section 608 and EU F-Gas certification pipelines ahead of technician shortage bottlenecks.
For New Entrants and Emerging Players: IoT-enabled temperature analytics platforms offer a technology-first wedge into underserved independent restaurant segments in India and Southeast Asia. Target commercial cold-chain monitoring services where incumbent hardware margins obscure software value. Pursue white-label partnerships with regional foodservice distributors lacking in-house connectivity capabilities.
For Investors and Strategic Acquirers: Valuations sit cheapest among second-tier Chinese assemblers lacking smart-platform assets. Long-term viability favors targets with refrigerant-transition engineering capabilities and established service networks. Monitor EPA SNAP program acceleration and EU F-Gas quota step-downs as inflection signals for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-as-a-Service Model | EU F-Gas Regulation compliance obligations drive closed-loop chemical leasing adoption in supermarket chains. |
| Predictive Maintenance Platform | German and Japanese food service operators pilot per-cubic-meter uptime guarantees shifting revenue to performance. |
| Vacuum-Insulated Panel Integration | Bavaria R&D facilities enable slim-wall construction meeting tightening envelope-efficiency codes. |
| India PLI Manufacturing Footprint | Tamil Nadu and Andhra Pradesh plants capture 4-6% cashback while serving Middle East export corridors. |
| Smart Kitchen Ecosystem Expansion | Samsung and Haier sustain consumer engagement beyond point of sale through meal-planning service integration. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included plant engineers at compressor manufacturers, procurement leads at US restaurant chains, channel partners in foodservice-equipment distribution, and regulatory affairs directors navigating EPA SNAP and EU F-Gas timelines. Secondary validation drew from ENERGY STAR certification databases, SAMR energy-labeling records, US customs import data, and SEC filings of listed appliance manufacturers. Bottom-up unit shipment modeling and top-down value chain triangulation anchored market sizing.
Historical reference periods spanning the pre-pandemic baseline through efficiency standard transitions established the forecast anchor. The analytical framework modeled product type, end-user segment, technology tier, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segmented growth rate blending weighted by compressor output allocation. Forecast inputs included ENERGY STAR 7.0 adoption curves and refrigerant-transition capital expenditure timelines.
The model holds under steady regulatory enforcement and intact copper-aluminum supply channels; deviation in geopolitical export restrictions or abrupt efficiency standard acceleration would shift replacement cycle assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Canada Home Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market