
 Home Laundry Appliances Market | 2026-2036
Home Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Home Laundry Appliances Market Foresight
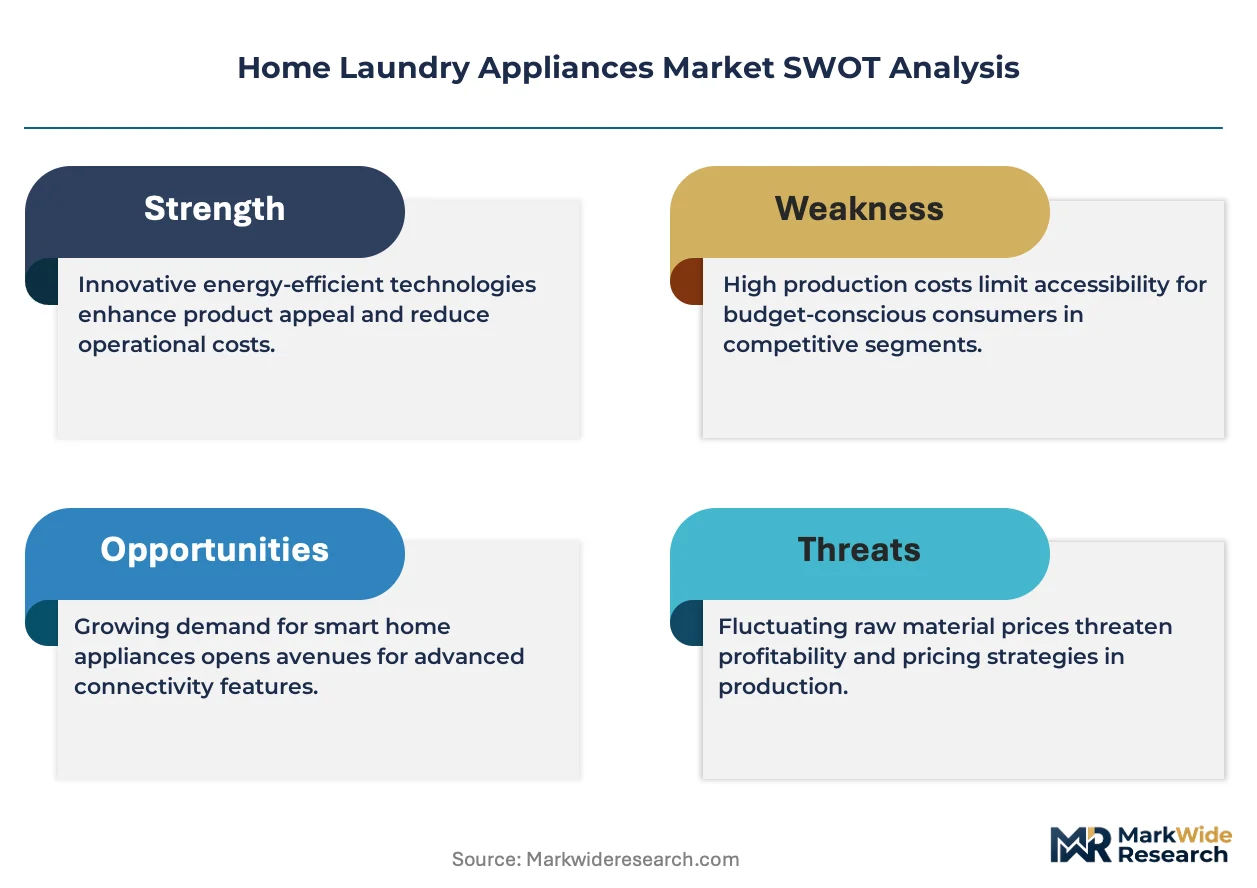
EPA WaterSense certification is repositioning the baseline efficiency requirements for manufacturers seeking access to the US market. Whirlpool Corporation leverages its vertically integrated North American manufacturing footprint to sustain cost competitiveness against import-dependent rivals. LG Electronics anchors its position through deep R&D investment in AI-driven wash-cycle optimization. Samsung differentiates via smart-home ecosystem integration that extends consumer lock-in beyond the appliance itself.
Home laundry appliances encompass electrically powered machines designed for fabric cleaning and drying, typically operating at 120-240V with drum capacities ranging from compact 2.3 cu. ft. units to extra-large 6.0 cu. ft. systems, employing either vented heat-exchange or condensation-based moisture removal processes. These devices serve the fundamental purpose of automating textile sanitation and moisture extraction for residential and light-commercial environments. Front-loading technology dominates margin pools due to superior water and energy efficiency ratings, while smart appliances represent the fastest-expanding technology segment as Wi-Fi-enabled diagnostics and app-based cycle control reshape replacement cycles. The household end-user segment remains structurally mature, whereas laundromat operators are consolidating procurement toward higher-capacity, coinless payment-integrated machines.
The US Department of Energy enforces minimum efficiency standards through federally mandated test procedures that directly constrain which product configurations achieve market access. EPA WaterSense labeling and California's Title 20 appliance regulations together create a compliance stacking effect that elevates engineering costs for national distribution. Ecodesign requirements in Europe and China's GB standards for water consumption impose parallel technical barriers that fragment global platform strategies. Stakeholders must monitor whether pending refrigerant-phaseout rules under the US AIM Act will accelerate heat-pump dryer adoption as manufacturers face compressed development timelines for next-generation drying architectures.
Market Dynamics
Heat-pump drying architectures are forcing a platform redesign cycle across major manufacturers as refrigerant-phaseout rules compress development timelines and elevate engineering costs for moisture-removal systems.
Growth Catalysts
- EU Ecodesign Directive:Tightening water-efficiency thresholds for washing machines sold across member states are pulling forward replacement demand and rewarding engineering investment in low-consumption drum systems.
- Urban housing densification:Multi-unit residential developers in Germany and France are expanding procurement of compact, ventless laundry systems optimized for space-constrained rental units.
- AI-driven wash-cycle optimization:Deep R&D investment in sensor-based load detection and adaptive water dosing is shortening replacement cycles among tech-forward household segments.
Market Restraints
- Copper and steel input volatility:Drum assemblies and motor windings remain exposed to commodity price swings that compress margin predictability for volume manufacturers.
- Platform fragmentation:Parallel technical barriers from EPA WaterSense, California Title 20, EU Ecodesign, and China's GB standards prevent global product architecture standardization.
- Technical limitation in ventless heat exchange:Condensation-based drying cycles extend runtimes versus vented alternatives, creating performance perception gaps in time-sensitive consumer segments.
Strategic Opportunities
- Coinless payment integration:Laundromat operators are consolidating procurement toward higher-capacity machines with app-based transaction systems, opening retrofit and replacement revenue streams.
- Smart-home ecosystem convergence:Wi-Fi-enabled diagnostics paired with voice-assistant integration create consumer lock-in beyond the appliance hardware itself.
- Refrigerant-phaseout tailwinds:Pending AIM Act rules are accelerating heat-pump dryer adoption as manufacturers face compressed timelines for next-generation architectures.
Industry Challenges
- Cross-border certification complexity:Stacking compliance requirements across EPA, DOE, and state-level regulations elongate product launch timelines and strain regulatory affairs staffing.
- Legacy system integration friction:Smart appliance connectivity protocols face interoperability gaps with existing residential electrical infrastructure and home automation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Laundry Appliances Market |
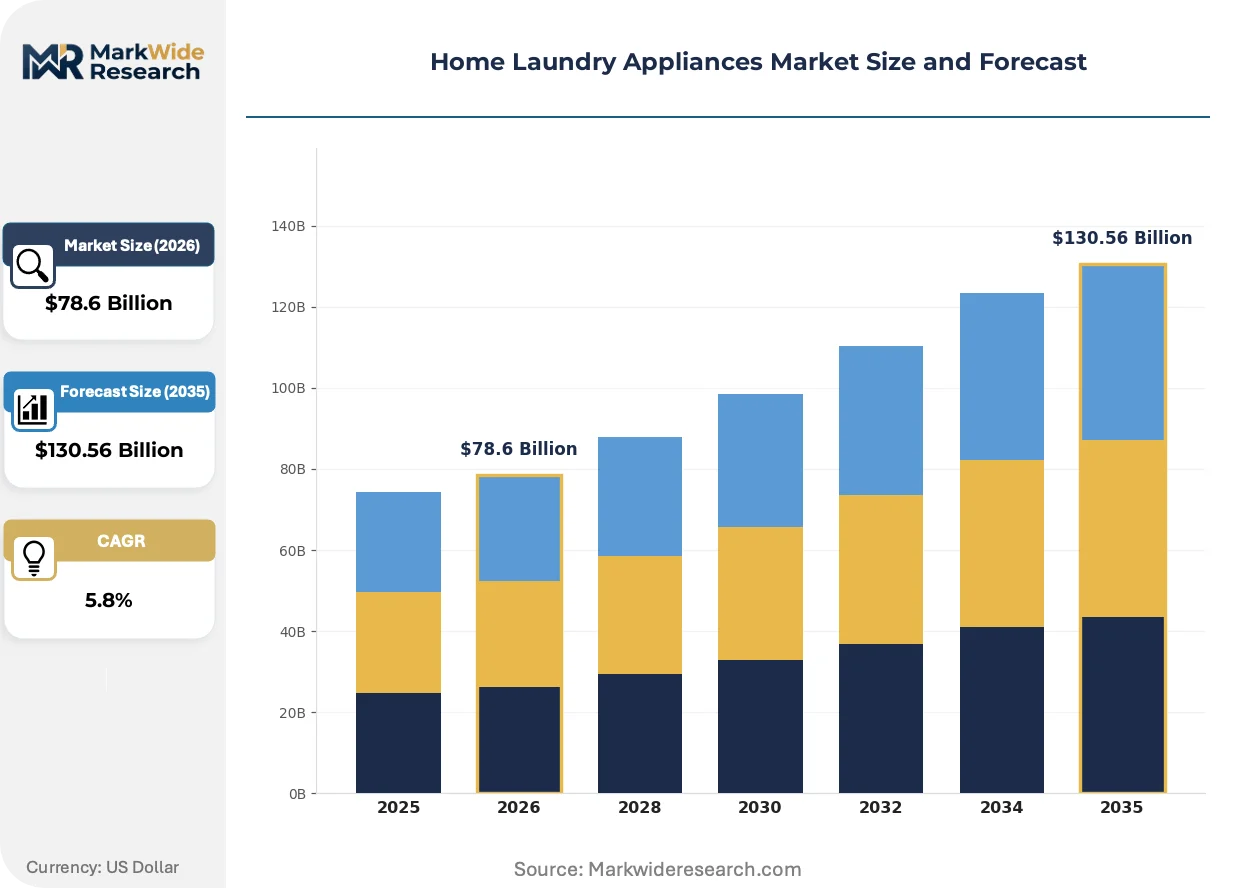
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $130.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Wash-Dry Combination, Portable Washers Technology: Top Loading, Front Loading, Smart Appliances, Energy Efficient End User: Households, Apartments, Laundromats, Commercial Facilities Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Whirlpool Corporation, LG Electronics, Samsung, GE Appliances, BSH Home Appliances Group, Electrolux, Haier Group, Midea Group, IFB Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Laundry Appliances Market Shifts & Advancements
Connected appliance architectures and efficiency mandates are compressing traditional replacement cycles while redistributing value capture toward software-enabled service layers and ecosystem providers.
Heat-pump drying technology is decentralizing moisture-removal engineering away from traditional vented heat-exchange architectures. German and Japanese manufacturers are accelerating adoption in premium compact segments, displacing condenser-based systems in urban multi-unit installations. This thermal-mechanical shift is decentralizing supply chain concentration from sheet-metal venting suppliers toward refrigeration-component specialists and compressor OEMs.
EPA WaterSense certification is repositioning baseline efficiency requirements for manufacturers seeking US market access. The industrial consequence elevates engineering costs for national distribution as California Title 20 regulations create compliance stacking effects. Front-loading platform developers face the tightest certification timelines, responding with accelerated test-procedure optimization and third-party verification partnerships.
Rental-unit operators are unbundling after-sales service from equipment procurement, compressing traditional dealer-margin structures. Property management platforms and multi-family REITs are consolidating vendor relationships toward direct manufacturer contracts with embedded maintenance terms. This purchasing model shift is most visible in German urban centers where housing densification concentrates procurement volume among institutional buyers.
Home Laundry Appliances Market Segmentation
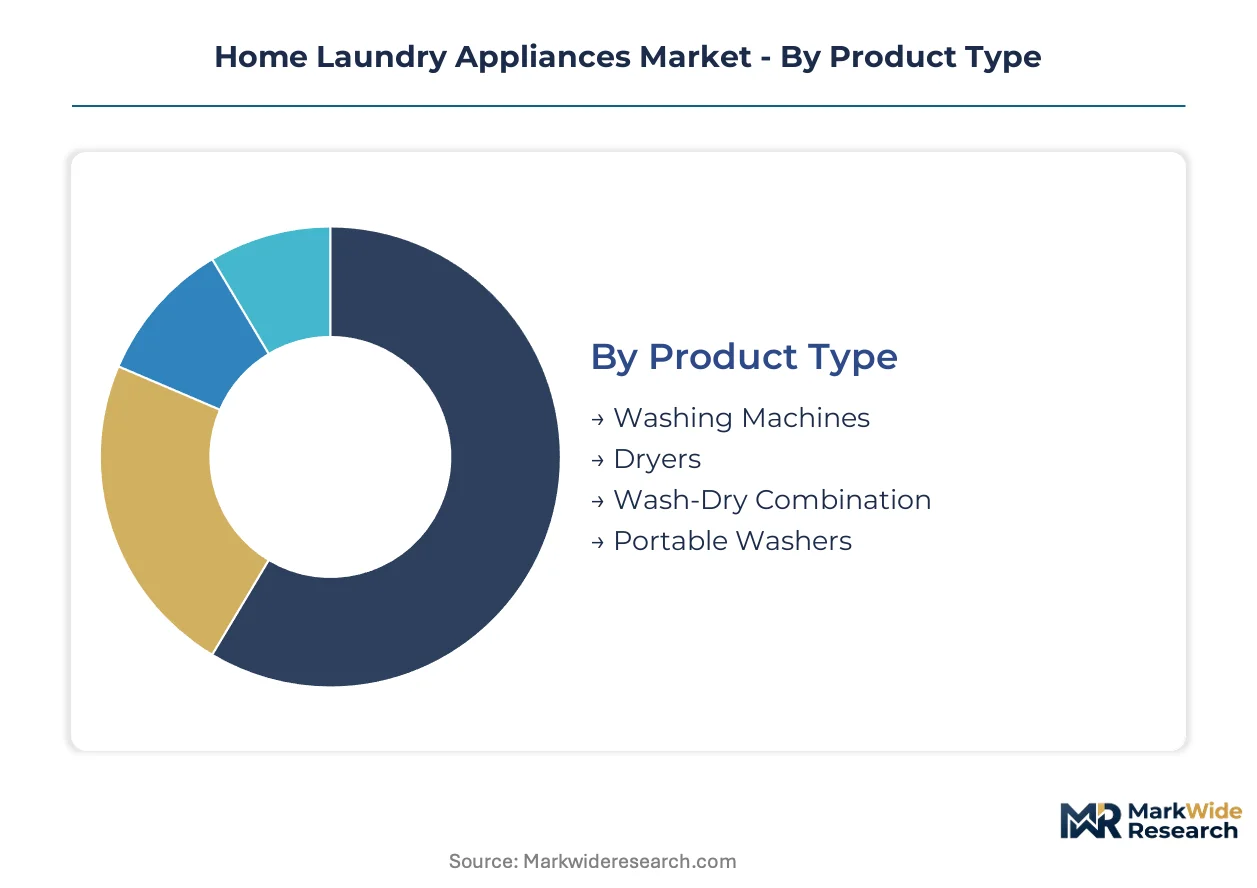
Segmentation in home laundry appliances reveals how capital intensity, regulatory exposure, and channel economics concentrate value capture across distinct product configurations. Understanding these divides clarifies where engineering investment and compliance costs fall heaviest.
Product Type:
Capital intensity varies sharply across product categories, with drum assemblies and motor systems demanding the heaviest upfront tooling investment.
- Washing Machines:Front-loading drum systems require precision-machined stainless steel drums and direct-drive motor architectures that elevate manufacturing capex. Demand concentrates in Germany and France where rental-unit densification favors compact, water-efficient configurations under EU Ecodesign thresholds.
- Dryers:Heat-pump and condenser architectures force platform redesigns as refrigerant-phaseout rules compress development timelines. German multi-unit developers are expanding procurement of ventless systems optimized for space-constrained urban installations.
- Wash-Dry Combination:Integrated thermal-mechanical systems merge washing and drying cycles into single-footprint units popular in Japanese and Korean compact housing.
- Portable Washers:Lightweight polymer drum systems with reduced motor specifications serve transient populations and recreational vehicle owners.
Washing machines absorb the bulk of installed capacity; dryers are expanding most quickly as heat-pump adoption accelerates.
Technology:
Margin pools distribute unevenly across engineering tiers, with premium configurations commanding pricing power through certification stacking.
- Front Loading:Horizontal-axis drum orientation enables superior water extraction and reduced cycle temperatures, satisfying EPA WaterSense and California Title 20 efficiency mandates. German and French institutional buyers specify these configurations for rental-unit portfolios.
- Smart Appliances:Wi-Fi-enabled diagnostics and app-based cycle control reshape replacement cycles among tech-forward household segments.
- Top Loading:Vertical-axis systems retain cost advantages in price-sensitive North American markets with legacy infrastructure preferences.
- Energy Efficient:Certification-labeled products carry compliance premiums across stacked regulatory regimes.
Front loading dominates margin capture; smart appliances are gaining share fastest as connectivity protocols standardize.
End User:
Procurement concentration determines contract structure, with institutional buyers unbundling after-sales service from equipment acquisition.
- Households:Replacement-driven demand cycles correlate with housing turnover and appliance-age thresholds in owner-occupied single-family residences.
- Apartments:Multi-unit residential developers in German urban centers specify compact ventless systems with embedded maintenance terms.
- Laundromats:Coinless payment-integrated machines with higher drum capacities consolidate procurement among consolidating operators.
- Commercial Facilities:Hospitality and healthcare laundries demand industrial-scale throughput with sanitation certification compliance.
Households absorb the bulk of installed capacity; laundromats are climbing the fastest as payment digitization accelerates.
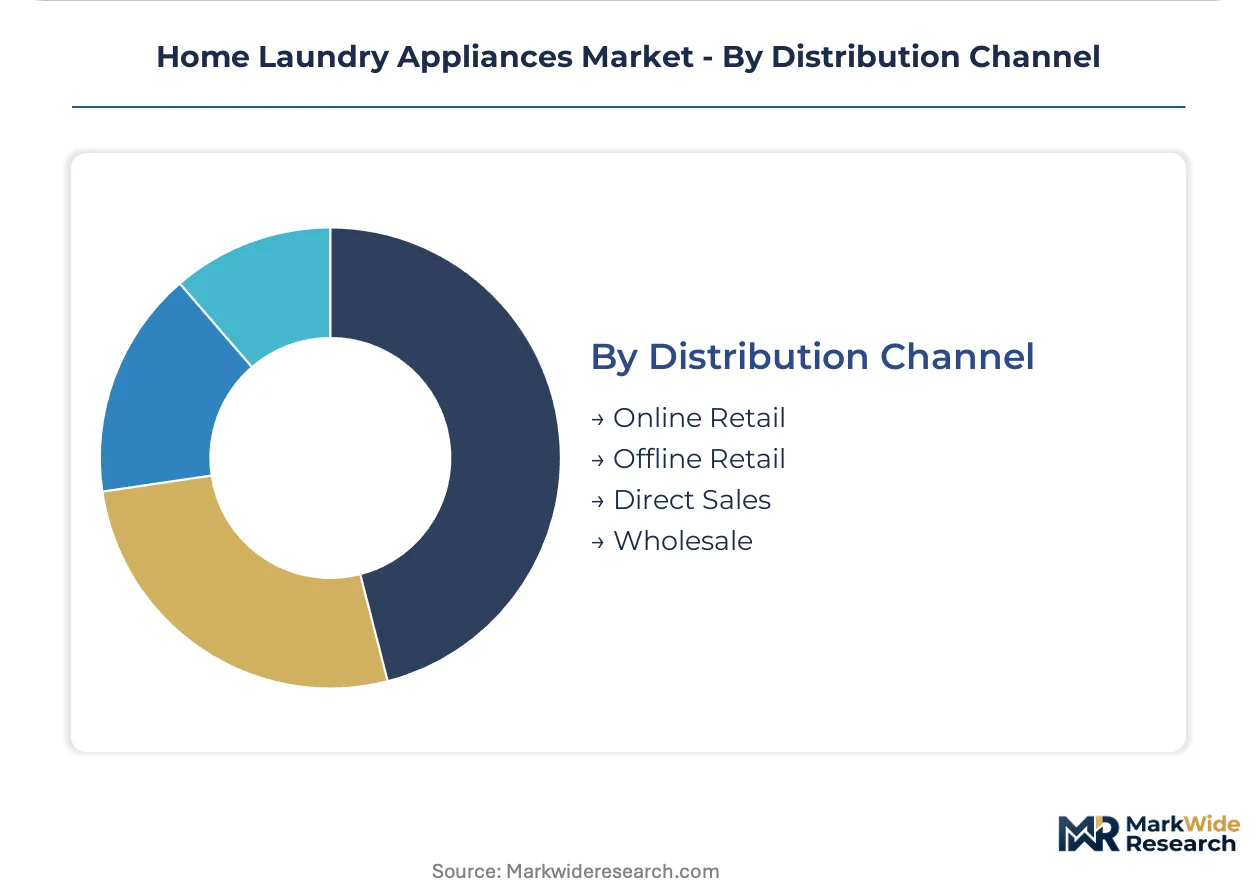
Distribution Channel:
Channel economics fragment along service-intensity lines, with direct relationships capturing institutional volume at compressed margins.
- Offline Retail:Big-box and specialty dealers retain installation and warranty service bundling that sustains margin structures in replacement markets.
- Online Retail:Platform-based transactions disintermediate traditional dealer networks, compressing fulfillment costs while expanding geographic reach.
- Direct Sales:Manufacturer contracts with property management platforms and multi-family REITs embed maintenance terms and consolidate vendor relationships.
- Wholesale:Volume distributors serve contractor and builder segments with project-based pricing and bulk logistics optimization.
Offline retail absorbs the bulk of installed capacity; direct sales are expanding most quickly as institutional procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam's northern provinces are concentrating electronics assembly capacity, pulling component sourcing away from traditional manufacturing basins as tariff engineering reshapes procurement geography.
United States
Multi-family housing construction in Texas and Florida is absorbing compact ventless dryer shipments as developers optimize for rental-unit density. EPA WaterSense and California Title 20 regulations create compliance stacking that elevates engineering costs for national distribution. Appliance manufacturing clusters in Ohio and Tennessee are retooling for heat-pump platform transitions under AIM Act refrigerant phaseout timelines.
Germany
Rental-unit densification in Berlin and Munich is driving specification of front-loading, water-efficient configurations under EU Ecodesign Directive thresholds. The country's national energy regulator enforces stringent efficiency test procedures that constrain market access for non-compliant imports. Industrial concentration in North Rhine-Westphalia hosts R&D facilities optimizing heat-pump drying architectures for European multi-unit installations.
China
Urban residential upgrading in Shanghai and Shenzhen is replacing legacy top-loading units with smart-enabled front-loading systems. GB standards for water consumption impose technical barriers that fragment global platform strategies for multinational manufacturers. Manufacturing agglomeration in the Yangtze River Delta supplies drum assemblies and motor systems to both domestic brands and export markets.
Japan
Compact housing configurations in Tokyo and Osaka sustain demand for integrated wash-dry combination units with reduced footprint requirements. METI efficiency labeling programs accelerate replacement cycles among tech-forward household segments. Industrial clusters in the Chubu region specialize in precision-machined stainless steel drums and direct-drive motor architectures.
India
Rising electrification in Maharashtra and Karnataka is expanding addressable markets for semi-automatic washing machines in first-time buyer segments. BIS certification requirements for electrical safety and energy consumption create compliance barriers for import-dependent brands. Manufacturing investment in Gujarat is localizing component supply for drum assemblies and polymer injection-molded parts.
Home Laundry Appliances Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with scale-driven manufacturers leveraging captive supply chains against nimble regional fabricators. The vendor base organizes around three strategic archetypes: vertically integrated appliance conglomerates with in-house component production, electronics specialists extending from consumer technology into white goods, and regional champions serving price-sensitive emerging markets. Competitive intensity manifests through capacity expansion in Southeast Asian assembly zones and strategic partnerships between component suppliers and finished-goods brands.
Among North American-based manufacturers, Whirlpool Corporation anchors the diversified conglomerate tier, while GE Appliances occupies a position within institutional procurement channels. LG Electronics and Samsung exemplify the electronics-specialist archetype, extending ecosystem integration capabilities from adjacent consumer technology segments. Haier Group and Midea Group represent scale-driven regional champions with manufacturing concentration in Chinese industrial zones. Electrolux and BSH Home Appliances Group sit within the European premium-tier vector, serving specification-driven multi-unit residential developers.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| LG Electronics |
| Samsung |
| GE Appliances |
| BSH Home Appliances Group |
| Electrolux |
| Haier Group |
| Midea Group |
| IFB Industries Limited |
| Others |
Supply & Pricing Matrix
Captive in-house production of direct-drive motor systems and precision-machined stainless steel drums anchors Whirlpool Corporation's cost position against import-dependent rivals while compressing margin vulnerability to copper and steel commodity swings. This backward integration into core electromechanical components simultaneously insulates pricing power during raw material volatility and constrains competitor ability to undercut on landed cost.
Pricing Analysis
Short lead-time premiums for heat-pump dryer platforms command pricing advantages as refrigerant-phaseout rules compress development timelines and OEMs scramble for compliant inventory. Three-tier pricing structure across premium smart-enabled, standard front-loading, and economy top-loading levels stratifies by certification stacking intensity. Pricing pressure stems from platform fragmentation across EPA WaterSense, California Title 20, and EU Ecodesign compliance costs. Institutional buyers in German multi-unit residential show lowest price sensitivity due to embedded maintenance contracts, while first-time buyers in Indian semi-automatic segments exhibit highest elasticity.
Supply Chain Analysis
Workforce availability in China's Yangtze River Delta, Vietnam's northern special economic zones, and India's Gujarat industrial corridors shapes component assembly capacity for drum systems and motor windings. Raw material dependencies center on copper for motor windings, cold-rolled steel for drum assemblies, and refrigerants for heat-pump architectures. Supply chain risk concentrates in single-source vulnerability for precision-machined stainless steel drums from Japanese Chubu region specialists. Distribution runs through big-box retail networks for replacement markets, direct manufacturer contracts for institutional procurement, and platform-based e-commerce for geographic expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where compliance stacking across EPA, DOE, and EU Ecodesign regulations is forcing sub-scale manufacturers toward exit or acquisition.
For Market Incumbents: Lock in captive supply of refrigeration-grade compressors and heat-exchanger components ahead of AIM Act phaseout deadlines. Secure direct-contract relationships with German and French multi-unit residential developers before institutional procurement consolidates further. Vertical integration into smart-home ecosystem protocols defends against electronics specialists extending from adjacent consumer technology segments. For New Entrants and Emerging Players: Capture the coinless payment-integrated laundromat retrofit opportunity as operators consolidate toward higher-capacity machines. Target Indian semi-automatic segments where BIS certification barriers filter out import-dependent rivals. Pursue OEM partnerships with Southeast Asian electronics assemblers for cost-competitive platform development. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified appliance conglomerates seeking heat-pump engineering capabilities and EU Ecodesign compliance infrastructure. Long-term viability favors vertically integrated manufacturers with in-house motor and drum production over assembly-dependent brands. Watch refrigerant-phaseout implementation velocity as the critical inflection signal for heat-pump adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Platform Transition | AIM Act compliance deadlines force accelerated R&D investment in next-generation drying architectures. |
| Smart-Home Ecosystem Integration | Wi-Fi-enabled diagnostics paired with voice-assistant protocols extend consumer lock-in beyond hardware replacement cycles. |
| Direct Institutional Procurement | Manufacturer contracts with German multi-family REITs embed maintenance terms and compress traditional dealer margins. |
| Coinless Payment Integration | App-based transaction systems in laundromat machines open retrofit revenue streams among consolidating operators. |
| Southeast Asian Assembly Expansion | Vietnam's northern special economic zones concentrate electronics capacity for tariff-engineered procurement geography. |
Research Methodology
Multi-period observation of heat-pump adoption rates, certification timeline compliance, and refrigerant-phaseout implementation anchored the trend analysis, supplemented by interviews with appliance R&D directors, regulatory affairs leads at multinational manufacturers, procurement managers at German multi-unit residential developers, and aftermarket service heads at laundromat operators. Secondary validation drew from EPA WaterSense certification databases, EU Ecodesign implementing measure texts, DOE appliance standards rulemakings, and customs trade data for drum assembly and motor component flows. Bottom-up shipment modeling triangulated against top-down market sizing across product type, technology tier, and end-user segmentation dimensions.
Input-output matrices mapped unit economics across front-loading, top-loading, heat-pump dryer, and condenser dryer platforms, with value capture distributed across hardware, software-enabled service layers, and ecosystem integration fees. Segmentation dimensions modeled include product configuration, technology tier, end-user archetype, and distribution channel structure. CAGRs derived from regression analysis of replacement cycle compression, housing formation rates, and regulatory pull-forward effects. Industry-specific forecast inputs incorporated refrigerant-phaseout implementation schedules and smart-appliance connectivity protocol standardization trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant-substitute technology maturation, copper and steel commodity volatility, and cross-border tariff regime shifts. Assumptions reflect current regulatory implementation timelines and technology cost curves. A small set of triggers warrants ongoing watch: AIM Act enforcement velocity, EU Ecodesign threshold tightening schedules, and smart-home ecosystem interoperability standard emergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Latin America Home Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Germany Washing Machine Market