
 Global Wet Vacuum Cleaner Market | 2026-2036
Global Wet Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wet Vacuum Cleaner Market Outlook
Multi-source component procurement is pivoting toward captive motor and pump production as supply chain reliability dominates vendor strategy. Alfred Kärcher SE & Co. KG leverages its German manufacturing footprint to sustain premium positioning in industrial-grade systems. Nilfisk Group anchors its competitiveness through specialized offerings for food service and medical facility applications. Tennant Company differentiates via autonomous wet-dry platforms that integrate with facility management software.
A wet vacuum cleaner is a suction device engineered to recover liquids, semi-liquids, and wet debris through sealed corrosion-resistant tanks, typically constructed from polypropylene or stainless steel with airflow rates exceeding 100 cubic feet per minute. Its primary commercial purpose centers on maintaining slip-resistant floors in manufacturing facilities, food service operations, and medical environments where standing liquids create contamination or safety hazards. Industrial-grade units dominate revenue contribution due to extended duty cycles and replacement part ecosystems, while portable configurations represent the fastest structural expansion as contractors demand site-to-site mobility. HEPA filtration integration captures margin pools in medical and pharmaceutical cleanroom applications where airborne pathogen control accompanies liquid recovery.
OSHA workplace safety standards in the United States and EU machinery directives under CE marking compel manufacturers to certify electrical ingress protection and wet-environment operational safety, directly shaping product development roadmaps. China's GB standards and NMPA-equivalent quality frameworks for commercial cleaning equipment add compliance layers for export-oriented suppliers. Stakeholders must monitor how tightening energy efficiency regulations across multiple geographies will redefine motor technology choices and service model economics.
Market Dynamics
Automated wet vacuum deployments in manufacturing facilities are compressing replacement cycles and forcing vendors to reconfigure service revenue models around predictive maintenance rather than parts replacement.
Growth Catalysts
- OSHA workplace safety mandates:Stricter enforcement of slip-resistant floor standards in US manufacturing plants compels facility managers to upgrade from manual mopping to sealed-tank recovery systems.
- Electronics assembly spill protocols:East Asian semiconductor fabs now require dedicated liquid containment stations with corrosion-resistant polypropylene tanks to protect cleanroom integrity.
- HEPA filtration convergence:Medical and pharmaceutical environments integrate airborne pathogen control with liquid recovery, expanding addressable applications beyond traditional industrial cleaning.
Market Restraints
- Stainless steel input volatility:Tank fabrication costs fluctuate with nickel and chromium commodity markets, squeezing margin on industrial-grade units with extended duty cycles.
- Motor and pump supply concentration:Captive production strategies by dominant vendors limit component availability for mid-tier assemblers dependent on third-party sourcing.
- EU machinery directive friction:CE marking requirements for electrical ingress protection add certification timelines that delay product launches in European markets.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO cleanroom standards and PLI scheme incentives create demand for medical-grade wet recovery systems in bulk drug production clusters.
- Autonomous platform integration:Convergence of wet-dry vacuum hardware with facility management software enables recurring SaaS revenue streams from industrial clients.
- Food service HEPA adoption:FSMA-aligned kitchens in the United States seek combined liquid recovery and airborne contamination control for open-food preparation zones.
Industry Challenges
- Automation engineering talent scarcity:Vendors struggle to hire embedded systems specialists capable of integrating sensor arrays with sealed corrosion-resistant tank architectures.
- Multi-jurisdiction certification complexity:Simultaneous OSHA, CE marking, and GB standards compliance extends product development timelines by 8-14 months for global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wet Vacuum Cleaner Market |
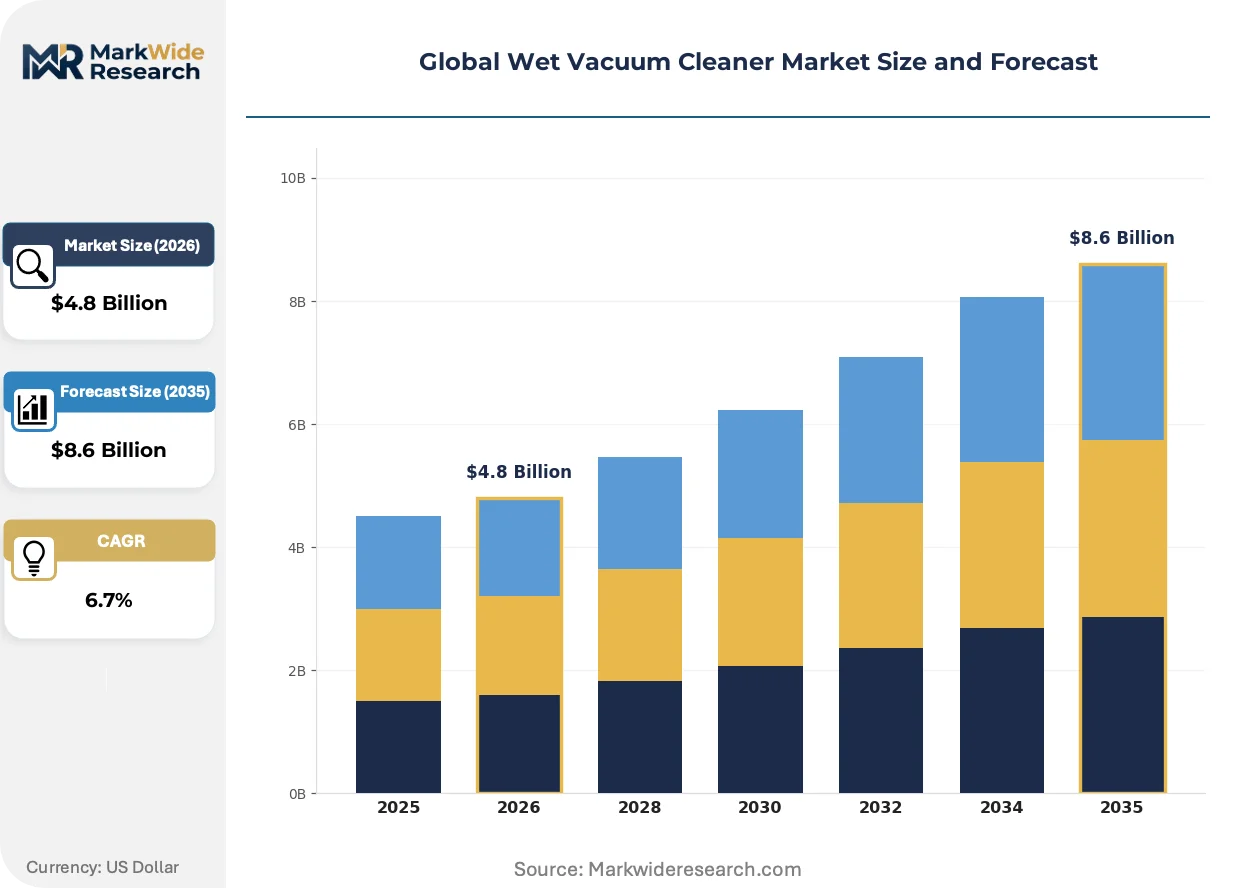
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial, Commercial, Residential, Portable End User: Households, Offices, Retail Stores, Manufacturing Facilities Feature: Multi-Surface, HEPA Filtration, Automatic, Eco-Friendly Application: Construction Sites, Automotive, Food Service, Medical Facilities |
| Companies Covered | Alfred Kärcher SE & Co. KG, Nilfisk Group, Tennant Company, Electrolux, Haier Inc., Koninklijke Philips N.V., Panasonic Corporation, Samsung, BISSELL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wet Vacuum Cleaner Market Strategic Shifts
Equipment intelligence and energy efficiency mandates are rewriting how wet vacuum systems are specified, procured, and monetized across industrial, medical, and commercial end-uses.
Brushless DC motor architectures paired with variable-frequency drives are rewriting energy consumption benchmarks for continuous-duty industrial units. Automotive battery plants in Germany and South Korea specify these systems to meet dual carbon goals while maintaining airflow rates above 100 cubic feet per minute. The technology is compressing total cost of ownership calculations and shifting procurement criteria from upfront price to kilowatt-hour recovery metrics.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of gasket and seal materials in sealed tank assemblies. European manufacturers now specify fluorine-free elastomers that maintain chemical resistance against industrial solvents. Medical device cleaning applications face the steepest compliance burden, with ANSM and BfArM-aligned facilities requiring material traceability documentation that adds 15-20% to component sourcing costs.
Contractors in construction and disaster restoration are consolidating purchases through rental channel partners rather than owning equipment fleets. United Rentals and Sunbelt are expanding wet-dry vacuum categories with telematics-equipped units that report utilization and maintenance status. This shift is most pronounced in North American metropolitan markets where labor mobility and project-based demand favor operational expenditure models over capital deployment.
Global Wet Vacuum Cleaner Market Segmentation
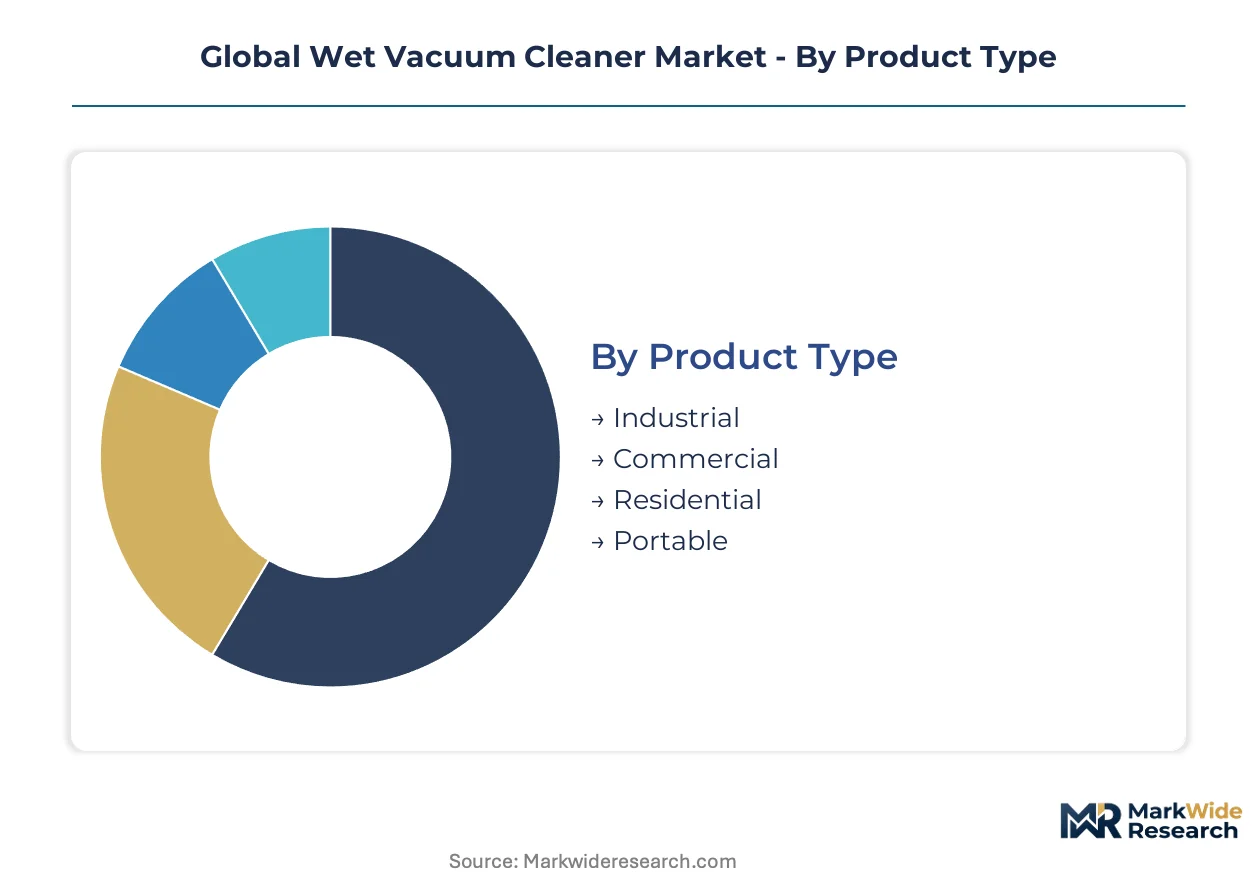
Wet vacuum cleaner procurement decisions diverge sharply across use cases, with industrial buyers prioritizing duty-cycle endurance while contractors optimize for site mobility. Segmentation reveals how specification requirements fragment vendor strategies across corrosion resistance, filtration grade, and automation integration.
Product Type:
Replacement cycles compress fastest where sealed-tank durability intersects with high-utilization environments, pushing buyers toward premium configurations with predictive maintenance compatibility.
- Industrial:Extended-duty systems with stainless steel or polypropylene tanks rated for continuous operation dominate revenue pools. German automotive battery plants and US semiconductor fabs specify these units under OSHA electrical safety mandates and corrosion-resistant requirements for solvent recovery.
- Commercial:Mid-tier configurations balance airflow performance with footprint constraints for retail and hospitality settings. Food service operators in France and Japan specify these for FSMA-aligned and ANSM-regulated open-kitchen liquid containment protocols.
- Residential:Compact units with reduced tank capacity target homeowner spill recovery and garage maintenance routines.
- Portable:Contractor-grade mobility features dominate disaster restoration and construction site deployments. North American rental channel expansion through United Rentals and Sunbelt accelerates operational expenditure adoption over fleet ownership.
Volume placements concentrate in Industrial; the faster expansion belongs to Portable.
End User:
Facility management software integration is reshaping procurement authority, with corporate real estate teams overriding traditional maintenance department specifications.
- Manufacturing Facilities:Cleanroom-grade units with HEPA filtration and sealed corrosion-resistant tanks protect semiconductor wafer integrity. South Korean and Taiwanese electronics assembly hubs mandate dedicated liquid containment stations under tightened spill protocols.
- Households:Entry-level wet-dry recovery for residential garages, basements, and workshop environments.
- Offices:Low-noise configurations with compact storage profiles serve commercial building services contractors.
- Retail Stores:Rapid-response units for customer-facing spill containment with minimal operational disruption.
Procurement volume tilts toward Manufacturing Facilities; steepest expansion trajectory surfaces in Retail Stores integrating autonomous cleaning platforms.
Feature:
Energy efficiency regulations across multiple geographies are redefining motor technology roadmaps and service model economics for feature-differentiated product lines.
- HEPA Filtration:Medical-grade airborne pathogen control combined with liquid recovery captures margin pools in pharmaceutical cleanrooms. CDSCO-aligned Indian bulk drug production clusters and BfArM-regulated German facilities require material traceability documentation that elevates component sourcing costs.
- Automatic:Sensor-integrated units with facility management software connectivity enable recurring SaaS revenue streams. Tennant Company and Nilfisk Group compete through autonomous platform deployment in US and European industrial campuses.
- Multi-Surface:Adaptable suction configurations transition between carpet extraction and hard-floor liquid recovery.
- Eco-Friendly:REACH-compliant fluorine-free elastomer seals replace per- and polyfluoroalkyl substances in gasket assemblies for European market access.
Revenue concentration clusters in HEPA Filtration; Eco-Friendly specifications gain share fastest under tightening chemical restriction frameworks.
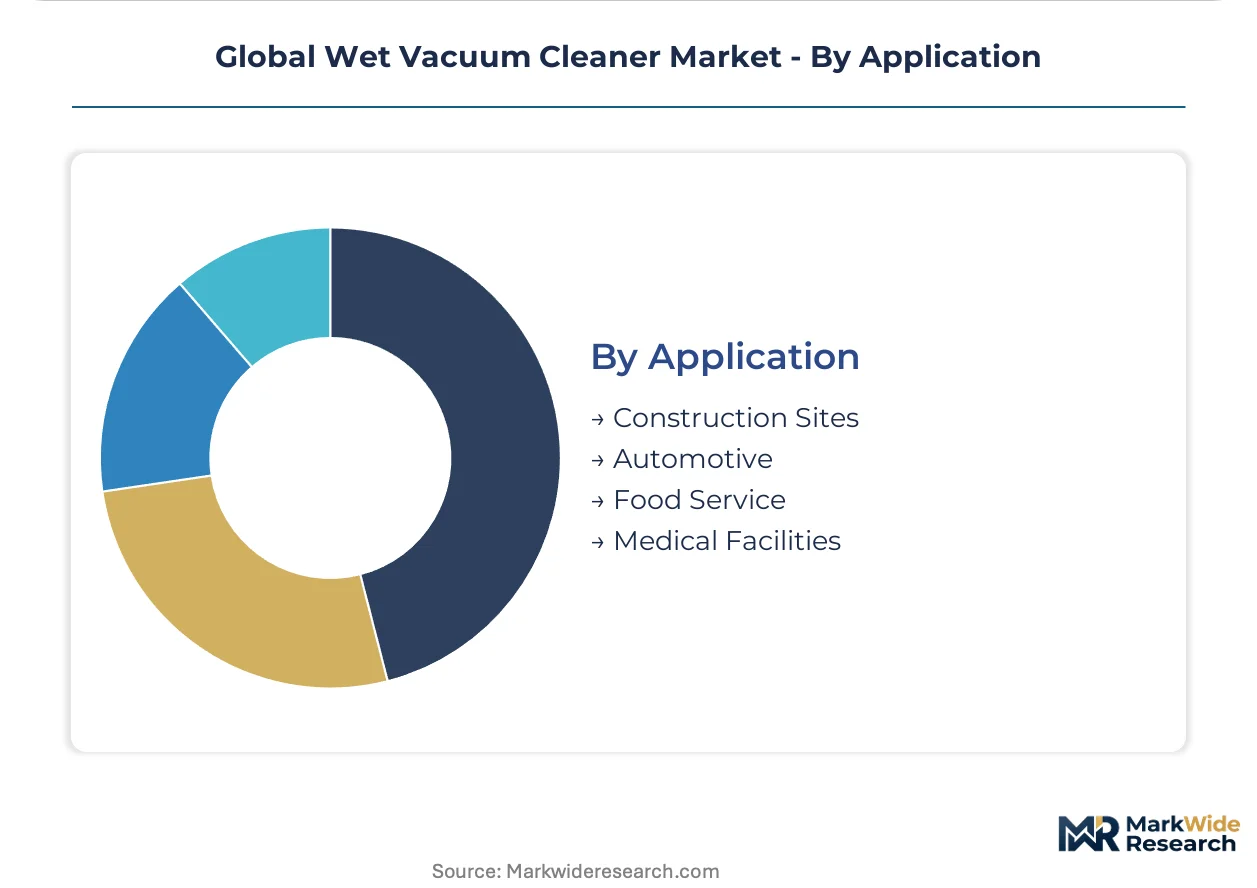
Application:
Application-specific certification requirements extend product development timelines, with multi-jurisdiction compliance adding 8-14 months for global platform launches.
- Medical Facilities:Combined liquid recovery and airborne contamination control serves ANSM, BfArM, and Health Canada-regulated environments. Open-food preparation zones in US hospitals and long-term care facilities drive FSMA-aligned HEPA adoption.
- Food Service:Stainless steel tank configurations resist sanitizing chemical exposure in commercial kitchens. NSF certification requirements govern US market access for equipment contacting food preparation surfaces.
- Construction Sites:Ruggedized portable units with debris filtration handle wet concrete slurry and flood restoration.
- Automotive:Battery plant installations in Germany and South Korea specify brushless DC motor architectures to meet dual carbon goals while maintaining airflow thresholds.
Medical Facilities anchor premium pricing; Automotive applications climb fastest as electrification manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock from Jamshedpur and nickel processing corridors in Odisha anchor Indian manufacturing cost structures for corrosion-resistant tank fabrication.
United States
OSHA workplace safety mandates compel automotive battery plants in Michigan and Tennessee to deploy sealed-tank recovery systems for electrolyte spill containment. The Inflation Reduction Act production tax credits accelerate electrification manufacturing scale-up. Cleanroom-grade HEPA configurations serve pharmaceutical clusters in New Jersey and North Carolina under FDA-regulated protocols.
Germany
REACH restrictions on per- and polyfluoroalkyl substances force gasket material reformulation for EU machinery directive compliance. The KBA oversees workplace safety certifications for industrial-grade deployments. Automotive battery facilities in Stuttgart and Wolfsburg specify brushless DC motor architectures to meet dual carbon goals while maintaining airflow thresholds.
China
GB standards and NMPA-equivalent quality frameworks add compliance layers for export-oriented wet vacuum suppliers. MIIT energy efficiency regulations reshape motor technology roadmaps. Semiconductor fabs in Shanghai and Shenzhen mandate dedicated liquid containment stations under tightened spill protocols for wafer integrity protection.
India
CDSCO cleanroom standards and PLI scheme incentives create demand for medical-grade wet recovery systems in bulk drug production. BIS certification requirements govern domestic market access for commercial cleaning equipment. Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad drive specification upgrades for combined liquid and airborne contamination control.
South Korea
MFDS-regulated medical device cleaning applications face material traceability documentation requirements that elevate component sourcing costs. METI-aligned energy efficiency benchmarks influence procurement criteria toward kilowatt-hour recovery metrics. Electronics assembly hubs in Gyeonggi Province deploy corrosion-resistant polypropylene tank systems under tightened semiconductor spill containment mandates.
Global Wet Vacuum Cleaner Market Competitive Environment
Global majors compete with regional champions across certification breadth and captive supply chain depth. Market structure tilts toward consolidated premium tiers where extended duty cycles and replacement part ecosystems defend positioning, while portable configurations fragment among contractor-focused assemblers. Three archetypes dominate: German-engineered industrial specialists, Asia-Pacific diversified conglomerates, and North American autonomous platform integrators. Competitive moves concentrate on backward integration into motor and pump production and predictive maintenance service model conversion.
Within the German-engineered tier, Alfred Kärcher SE & Co. KG exemplifies premium industrial positioning through its domestic manufacturing footprint. Nilfisk Group occupies a specialized position serving food service and medical facility applications with regulatory-aligned configurations. Tennant Company anchors the autonomous platform vector, representing convergence of wet-dry hardware with facility management software integration.
| Leading Market Players |
|---|
| Alfred Kärcher SE & Co. KG |
| Nilfisk Group |
| Tennant Company |
| Electrolux |
| Haier Inc. |
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Samsung |
| BISSELL |
| Others |
Value Chain & Pricing Dynamics
Nickel and chromium feedstock volatility cascades through stainless steel tank fabrication costs, compressing margins on industrial-grade units while polypropylene alternatives gain cost advantage in corrosion-resistant configurations. German and Chinese motor manufacturers wield pricing power through captive production strategies that limit component availability for mid-tier assemblers dependent on third-party sourcing.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium industrial configurations from unbundled commercial tiers where service contracts remain optional. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and duty-cycle endurance specifications. Cost compression in mid-tier commercial segments intensifies because rental channel expansion favors operational expenditure models over capital deployment. Contractor buyers through United Rentals and Sunbelt exhibit highest price sensitivity, while pharmaceutical cleanroom operators prioritize HEPA filtration compliance over unit economics.
Supply Chain Analysis
CE marking and OSHA electrical safety certifications gate supplier eligibility for German and US manufacturing facility deployments, extending qualification timelines. Motor and pump production concentrates in Germany, China, and South Korea, with brushless DC architectures sourcing rare earth magnets from Chinese processing corridors. Supply chain risk rests on single-source vulnerability for specialized corrosion-resistant tank alloys. Distribution runs through industrial equipment distributors, rental channel partners, and direct OEM relationships with automotive battery plants and semiconductor fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wet vacuum cleaner market sits in a technology-transition phase where brushless DC motor architectures displace legacy induction motor platforms across industrial duty-cycle applications. Facility management software integration and predictive maintenance telemetry are rewriting procurement criteria and vendor monetization models.
For Market Incumbents: Deepen backward integration into motor and pump production to defend margin position against captive supply strategies by dominant vendors. Invest in embedded systems engineering talent to accelerate autonomous platform development, as automation engineering scarcity threatens product roadmap execution. Prioritize predictive maintenance service model conversion to offset compressed replacement cycles from automated deployments.
For New Entrants and Emerging Players: Rental channel partners represent the most penetrable entry vector for contractor-grade portable configurations in North American metropolitan markets. Target Indian pharmaceutical manufacturing clusters where CDSCO cleanroom standards and PLI scheme incentives create specification upgrade demand for medical-grade wet recovery systems. Pursue white-label arrangements with facility management software platforms to bypass direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Consolidation of United Rentals and Sunbelt wet-dry vacuum categories with telematics-equipped units is the leading indicator that operational expenditure models are displacing capital ownership in contractor segments. Long-term viability favors vendors with captive motor production and certification breadth across OSHA, CE marking, and GB standards. Acquisition targets should demonstrate embedded systems capability for sensor-integrated autonomous platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive supply of brushless DC architectures insulates against component scarcity and secures energy efficiency compliance. |
| Predictive Maintenance Service Launch | Telemetry-enabled units generate recurring revenue streams as automated deployments compress hardware replacement cycles. |
| Autonomous Platform Certification | Facility management software integration positions vendors for corporate real estate procurement authority shifts. |
| Fluorine-Free Elastomer Reformulation | REACH-compliant gasket materials maintain EU market access as per- and polyfluoroalkyl substance restrictions tighten. |
| Indian Pharmaceutical Market Entry | CDSCO-aligned cleanroom configurations capture PLI scheme-driven demand in bulk drug production clusters. |
Study Parameters
Independent corroboration across maintenance directors at automotive battery plants, procurement leads at semiconductor fabs, aftermarket service heads at industrial equipment distributors, and facility management software integration specialists underwrites the qualitative findings. Primary interviews combined with secondary validation from OSHA enforcement databases, EU machinery directive filings, SEC 10-K disclosures by listed equipment manufacturers, and customs/trade data on stainless steel and polypropylene tank imports. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, feature, and application dimensions.
Comparable-period anchoring to historical replacement cycle data and rental channel penetration rates calibrated the forecast window across the projection horizon. Segmentation modeling incorporated product type, end user category, feature integration level, and application environment with regional regulatory cluster overlays. CAGRs derived from elasticity-adjusted demand curves incorporating energy efficiency mandate compliance costs and automation adoption curves. Industry-specific inputs included semiconductor fab spill protocol tightening timelines and automotive electrification manufacturing scale-up trajectories.
Caveats apply where nickel and chromium commodity volatility, multi-jurisdiction certification timeline extensions, or embedded systems talent scarcity could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and rental channel expansion velocity. A model refresh is warranted upon material change in OSHA workplace safety mandate implementation or REACH substance restriction scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Knife Set Market
Household Items
Deodorizer Bag Market
Household Items
Can Opener Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Commercial Lawnmower Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
US Soap Dispenser Market
Household Items
Leaf Blower Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Washing Capsules Market
Household Items
South Korea Cookware Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Coffin and Cremation Urn Market
Household Items
Flushable Wipes Market
Household Items
Electric Clothes Drying Hanger Market