
 Australia Home Appliances Market | 2026-2036
Australia Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Home Appliances Market Outlook
AS/NZS 4474 energy performance certification is reorganizing competitive access for refrigerator and washing machine suppliers in Australia. Fisher & Paykel Appliances leverages its New Zealand-Australian manufacturing heritage to dominate premium laundry and refrigeration segments. Haier Group anchors its position through backward integration into compressor and motor production, sustaining cost advantages across the mid-market. Samsung Electronics differentiates through connected kitchen ecosystems that integrate with its broader consumer electronics platform.
Australia home appliances comprise electrically powered machines designed for domestic tasks including food preservation, garment cleaning, and thermal cooking, typically operating at 230-240V/50Hz with MEPS-mandated minimum energy performance coefficients. Refrigerators and washing machines occupy the largest installed base and generate recurring replacement cycles tied to housing turnover and efficiency upgrades. Smart appliances and IoT-enabled units represent the fastest-expanding technology tier as households adopt app-controlled scheduling and energy monitoring, while conventional models retain volume leadership in price-sensitive segments and regional markets.
TGA does not regulate home appliances directly, but the Greenhouse and Energy Minimum Standards Act administered by the Department of Climate Change, Energy, the Environment and Water shapes product eligibility through MEPS registration and Energy Rating Label requirements. The Electrical Equipment Safety System under state-based electrical safety offices mandates compliance with AS/NZS 3820 and relevant product standards before market entry. Stakeholders must monitor proposed MEPS tier upgrades and state-level gas appliance transition policies that will determine which product configurations remain viable across Australian jurisdictions.
Market Dynamics
Queensland's coastal construction surge and Sydney-Melbourne smart kitchen upgrades are pulling demand toward connected, high-efficiency units while MEPS tier tightening compresses margins on legacy product lines.
Growth Catalysts
- MEPS Tier Upgrades:The Department of Climate Change, Energy, the Environment and Water is tightening minimum energy performance standards for refrigerators and washing machines, forcing replacement cycles and premium product adoption.
- Urban Apartment Modernization:Sydney and Melbourne high-density residential towers are specifying smart kitchen suites as standard fit-out, creating bundled procurement channels for connected appliance ecosystems.
- Queensland Coastal Expansion:Gold Coast and Sunshine Coast residential construction is outpacing national averages, generating concentrated demand for full-suite appliance installations in new housing stock.
Market Restraints
- Compressor Supply Concentration:Backward-integrated Asian manufacturers control motor and compressor supply, limiting Australian assemblers' bargaining power on critical components.
- Copper and Rare Earth Volatility:Input costs for wiring, motors, and permanent magnets fluctuate with commodity cycles, compressing margins on mid-market price-locked contracts.
- Gas Appliance Transition Friction:State-level policies phasing out natural gas connections in new builds create inventory risk for dual-fuel cooking product lines.
Strategic Opportunities
- Regional Queensland Penetration:Cairns and Townsville appliance replacement rates lag southeastern capitals, offering volume expansion for efficient entry-level SKUs.
- IoT-Enabled Predictive Maintenance:Convergence of appliance sensors and cloud analytics is creating subscription service revenue streams beyond hardware sales.
- Energy Rating Label Differentiation:AS/NZS 4474 certification tiers are enabling price premiums for 5-star and above units in environmentally conscious household segments.
Industry Challenges
- Electrical Safety Certification Timelines:AS/NZS 3820 compliance testing through state-based Electrical Equipment Safety System offices creates six-to-twelve month product launch delays.
- Smart-Retrofit Integration Complexity:Legacy 230-240V infrastructure in pre-2000 housing stock requires electrical upgrades to support connected appliance full functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Home Appliances Market |
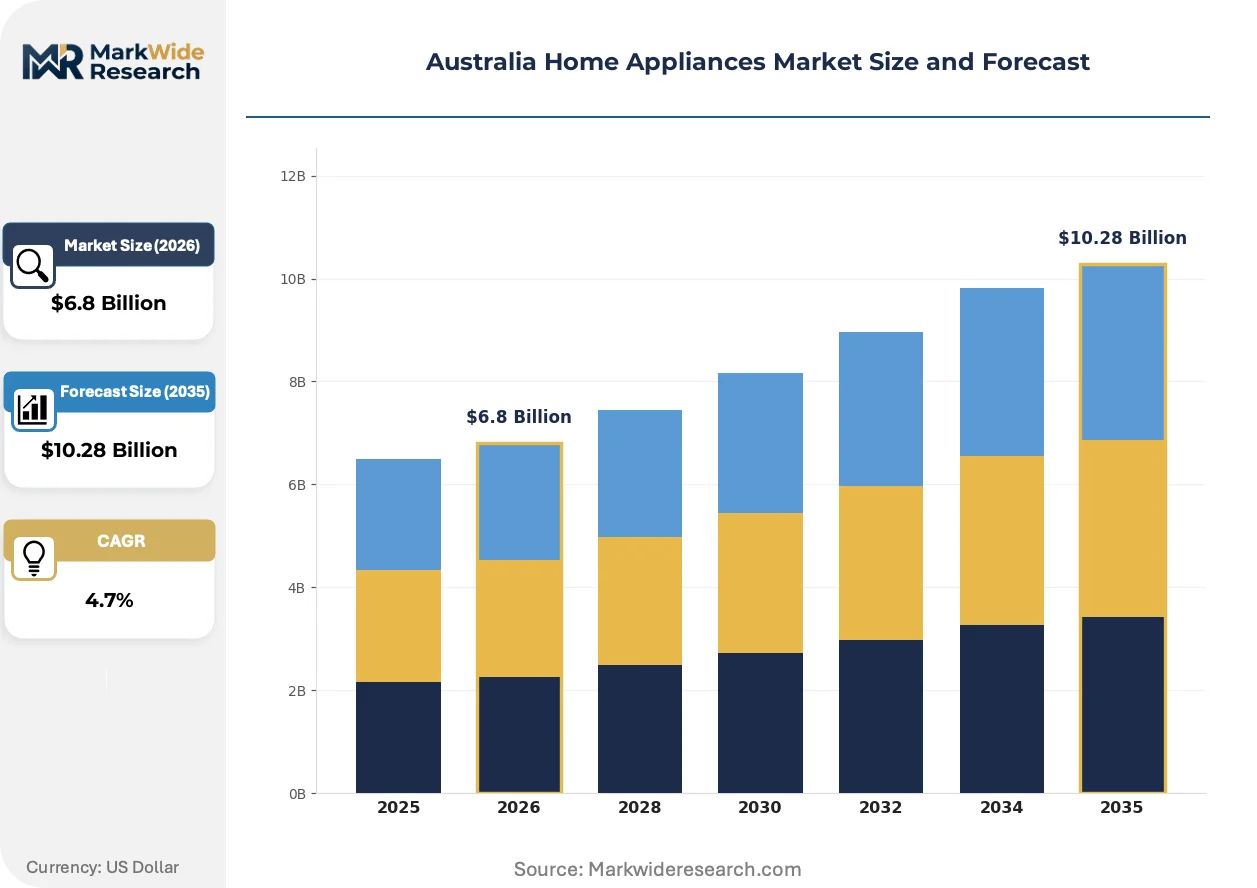
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Microwaves End User: Households, Businesses, Hotels, Institutions Technology: Smart Appliances, Energy-Efficient, Conventional, IoT-Enabled Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Fisher & Paykel Appliances, Haier Group, Samsung Electronics, Panasonic Corporation, Breville Group, Electrolux AB, BSH Home Appliances, Midea Group, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Home Appliances Market Strategic Shifts
Connected kitchen ecosystems and energy performance certification are restructuring how Australian households evaluate and purchase domestic appliances, compressing replacement cycles for conventional units.
Smart appliance operating systems is fragmenting the control layer across competing platforms. Samsung's SmartThings, Google Home, and Amazon Alexa are each capturing distinct buyer segments based on existing device ecosystems. Melbourne and Sydney early adopters are accepting platform lock-in for seamless scheduling and energy monitoring. This fragmentation is preventing interoperability standards from consolidating, forcing manufacturers to support multiple protocols and raising software development costs.
The Greenhouse and Energy Minimum Standards Act administered by the Department of Climate Change, Energy, the Environment and Water is tightening refrigerator and washing machine efficiency thresholds. Suppliers must redesign compressor systems and insulation packages to maintain market access. Premium refrigeration segments are absorbing compliance costs through price positioning, while mid-market suppliers face margin compression from AS/NZS 4474 re-testing requirements.
Appliance-as-a-service pilots are emerging in Queensland's build-to-rent developments. Property managers are bundling connected whitegoods into tenancy agreements with maintenance included, displacing traditional retail purchase for transient coastal populations. This shift is most visible in Gold Coast apartment towers targeting young professional tenants with twelve-month lease terms and fully fitted kitchens.
Australia Home Appliances Market Segmentation
Australian households exhibit distinct purchasing patterns across product categories, with MEPS compliance tiers and connectivity features now driving channel selection and price positioning. Understanding these segment boundaries reveals where replacement cycles concentrate and which technology tiers command procurement priority.
Product Type:
Channel mix varies sharply by product category, with refrigerators and washing machines flowing through builder-specified contracts while cooking appliances retain stronger retail showroom dependency.
- Refrigerators:Compression systems and insulation packages determine AS/NZS 4474 certification tiers. Queensland coastal new builds and Sydney-Melbourne apartment renovations are pulling demand toward French-door configurations with inverter compressors.
- Washing Machines:Front-load drum systems with heat-pump drying integration dominate premium replacement cycles. Melbourne and Sydney strata managers are specifying stacked laundry pairs for space-constrained apartments.
- Ovens:Electric convection and pyrolytic self-cleaning variants face inventory risk from state-level gas transition policies.
- Microwaves:Countertop and built-in grill combinations retain volume leadership through hypermarket promotional cycles.
By volume, washing machines lead. By growth pace, connected refrigerators are expanding most quickly.
End User:
Cost tier stratification separates household discretionary purchases from commercial procurement governed by total-cost-of-ownership calculations.
- Households:Owner-occupiers in Queensland's coastal expansion zones are driving full-suite installations. Energy Rating Label awareness is concentrating upgrade decisions in 5-star and above tiers.
- Businesses:Corporate housing providers and serviced apartment operators are standardizing on connected appliances with remote diagnostics for maintenance cost control.
- Hotels:Minibar refrigeration and in-room beverage systems follow procurement cycles tied to refurbishment timelines.
- Institutions:Aged care facilities and university residences prioritize durability certifications over smart features.
Households dominate absolute unit demand. Commercial end users are gaining share fastest through build-to-rent channel expansion.
Technology:
Application requirements dictate technology tier selection, with food preservation and thermal cooking demanding different connectivity integration levels.
- Smart Appliances:Operating system fragmentation across Samsung SmartThings, Google Home, and Amazon Alexa is forcing multi-protocol development costs onto manufacturers.
- Energy-Efficient:MEPS tier upgrades are compressing legacy product viability. Premium positioning absorbs compliance costs while mid-market suppliers face margin pressure from re-testing requirements.
- Conventional:Non-connected units retain price-sensitive volume in regional Queensland and pre-2000 housing stock lacking smart infrastructure.
- IoT-Enabled:Sensor convergence with cloud analytics is enabling subscription maintenance services in Gold Coast build-to-rent developments.
Conventional technology holds volume leadership. IoT-enabled units are climbing the fastest as property managers adopt appliance-as-a-service models.
Distribution Channel:
Customer type and geography determine channel effectiveness, with urban apartment dwellers diverging from regional household purchasing patterns.
- Online Retail:Platform comparison tools are accelerating replacement cycle decisions for standardized products with clear Energy Rating Label differentiation.
- Specialty Stores:Kitchen design studios in Sydney and Melbourne are capturing bundled smart suite specifications through architect and developer relationships.
- Hypermarkets:Promotional cycles and immediate availability retain strength for emergency replacements and entry-tier microwaves.
- Direct Sales:Builder and developer contracts bypass retail markup for new construction volumes in Queensland coastal markets.
Hypermarkets lead by transaction volume. Specialty stores are gaining share fastest through high-value kitchen suite bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greenhouse and Energy Minimum Standards Act administered by the Department of Climate Change, Energy, the Environment and Water shapes demand patterns across Australian states through MEPS tier upgrades and Energy Rating Label mandates.
New South Wales
Sydney apartment towers are specifying smart kitchen suites as standard fit-out, creating bundled procurement channels for connected appliance ecosystems. The state's electrical safety offices enforce AS/NZS 3820 compliance through the Electrical Equipment Safety System. Parramatta and inner-west renovation corridors are driving French-door refrigerator adoption with inverter compressors.
Victoria
Melbourne's high-density residential market is pulling demand toward stacked laundry pairs and space-constrained cooking solutions. State-level gas appliance transition policies are creating inventory risk for dual-fuel cooking product lines. The city's kitchen design studios are capturing bundled smart suite specifications through architect relationships.
Queensland
Gold Coast and Sunshine Coast residential construction is outpacing national averages, generating concentrated demand for full-suite appliance installations. MEPS registration requirements under federal administration determine product eligibility for coastal new builds. Cairns and Townsville replacement rates lag southeastern capitals, offering volume expansion for efficient entry-level SKUs.
Western Australia
Perth's build-to-rent developments are piloting appliance-as-a-service models with maintenance-included tenancy agreements. The state's distance from eastern manufacturing centers elevates logistics costs for mid-market suppliers. Mining corridor housing stock maintains conventional appliance demand due to pre-2000 electrical infrastructure limitations.
South Australia
Adelaide's aged care facility expansions prioritize durability certifications over smart features in institutional procurement. The state's renewable energy integration policies are accelerating interest in energy-efficient refrigeration with high AS/NZS 4474 certification tiers. Regional housing stock retains price-sensitive volume for conventional non-connected units.
Australia Home Appliances Market Competitive Environment
Player mix skews toward Asia-Pacific conglomerates with captive component supply and Australasian heritage specialists with premium positioning. The market exhibits tiered concentration with three distinct strategic archetypes dominating: backward-integrated manufacturers controlling compressor and motor production, ecosystem platform operators leveraging consumer electronics integration, and regional heritage brands exploiting trans-Tasman manufacturing proximity. Competitive moves center on MEPS compliance redesign and smart kitchen suite bundling through developer contracts.
Among Asia-Pacific conglomerates with captive supply chains, Haier Group exemplifies backward integration into compressor production, while Samsung Electronics anchors the ecosystem-platform archetype through SmartThings connectivity integration. Fisher & Paykel Appliances occupies a heritage-specialist position leveraging its New Zealand-Australian manufacturing proximity for premium laundry and refrigeration segments.
| Leading Market Players |
|---|
| Fisher & Paykel Appliances |
| Haier Group |
| Samsung Electronics |
| Panasonic Corporation |
| Breville Group |
| Electrolux AB |
| BSH Home Appliances |
| Midea Group |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
AS/NZS 4474 energy performance certification gates both supplier qualification and price differentiation simultaneously, compressing legacy product margins while enabling premium tiers for compliant manufacturers. The regime forces mid-market assemblers to absorb re-testing costs or exit, concentrating pricing power among backward-integrated players with captive compressor production.
Pricing Analysis
Cost-plus contracts with copper and rare earth indexation dominate procurement between Australian retailers and Asian manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates 5-star AS/NZS 4474 certified units from 3-star compliance-grade and non-certified legacy inventory. Pricing pressure stems from MEPS tier upgrades forcing compressor redesign cycles. Owner-occupiers in Queensland coastal zones exhibit lowest price sensitivity, while regional Queensland households and pre-2000 housing stock buyers drive volume in entry tiers.
Supply Chain Analysis
China, Thailand, and South Korea anchor compressor and motor production for Australian-bound appliances. Wiring harnesses, permanent magnets, and inverter control modules draw from concentrated Asian component ecosystems. Single-source vulnerability in compressor supply elevates risk for non-integrated Australian assemblers. Distribution runs through direct builder contracts for Queensland new builds, specialty kitchen studios for Sydney-Melbourne renovations, and hypermarket promotional cycles for emergency replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Appliance-as-a-service subscription layers in Queensland build-to-rent developments are expanding faster than hardware unit growth, repositioning the market as a service-attach opportunity with recurring maintenance revenue streams.
For Market Incumbents: Secure developer relationships in Gold Coast and Sunshine Coast residential towers to lock in bundled smart suite specifications before channel consolidation. Defend margin position by accelerating backward integration into compressor sourcing or captive motor production, countering the pricing leverage of integrated Asian competitors. For New Entrants and Emerging Players: Anchor in Cairns and Townsville replacement corridors where AS/NZS 4474 awareness lags southeastern capitals, offering efficient entry-tier SKUs with simplified feature sets. Target property management aggregators servicing Queensland's transient coastal workforce with white-label appliance-as-a-service bundles. For Investors and Strategic Acquirers: MEPS tier tightening reshapes the acquisition landscape toward targets with established Energy Rating Label testing infrastructure and existing 5-star certification portfolios. Viable acquisition archetypes include regional heritage brands with trans-Tasman manufacturing proximity and distressed mid-market assemblers facing compliance-driven margin compression. Monitor state-level gas appliance transition policy announcements as inflection signals for cooking product line inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Appliance-as-a-Service Launch | Subscription maintenance models capture recurring revenue from Gold Coast build-to-rent tenants. |
| MEPS Compliance Redesign | Compressor and insulation upgrades preserve market access under tightening AS/NZS 4474 thresholds. |
| Developer Contract Expansion | Direct procurement channels in Queensland coastal construction bypass retail margin erosion. |
| IoT Platform Integration | Multi-protocol support for Samsung SmartThings, Google Home, and Alexa prevents ecosystem lock-out. |
| Regional Distribution Partnership | Cairns and Townsville logistics alliances reduce lead times for entry-tier SKU penetration. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with appliance category managers, electrical safety compliance officers, property development procurement leads, and retail channel buyers; and secondary validation through Australian Bureau of Statistics construction data, Department of Climate Change MEPS registration databases, AS/NZS standards documentation, and customs import records. Bottom-up unit shipment estimates triangulated against top-down housing completion and replacement cycle models.
Across the projection horizon, the analytical framework modeled demand by product type, end user segment, technology tier, and distribution channel, with state-level regulatory clusters as a cross-cutting dimension. CAGRs derived from housing stock turnover rates, MEPS implementation schedules, and smart appliance adoption curves. Forecast inputs incorporated Queensland coastal construction permits and Sydney-Melbourne apartment renovation pipeline data.
Material uncertainties — commodity price volatility in copper and rare earths, state-level gas transition policy divergence, and Electrical Equipment Safety System certification delays — sit outside the modeled envelope. Forecasts reflect assumptions about MEPS tier implementation timing and smart infrastructure penetration in pre-2000 housing stock. Recalibration cycles align with material shifts in regulatory enforcement intensity and coastal construction permit volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
North America Home Appliances Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Washing Machine Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Range Hood Market
Home Appliances
India Small Home Appliances Market