
 US Induction Cookware Market | 2026-2036
US Induction Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
US Induction Cookware Market Insights
Department of Energy efficiency mandates are expanding the baseline for induction-compatible cookware certification. All-Clad leverages its domestic manufacturing footprint to sustain premium positioning across stainless steel collections. T-fal competes aggressively on non-stick induction lines through mass retail channel control. Meyer Corporation anchors mid-market volume with broad SKU coverage across material tiers.
US induction cookware comprises ferromagnetic metal vessels engineered with specific alloy compositions—typically 18/10 stainless steel or enameled cast iron—designed to generate resistive heat through electromagnetic field interaction rather than thermal conduction. The technology demands flat-bottom precision within tolerance ranges and base-layer ferrous content above threshold levels to ensure energy transfer efficiency. Stainless steel frying pans dominate unit sales through household penetration, while professional chef demand for copper-core stock pots commands the strongest margin pool. Non-stick griddles represent the fastest-expanding material-technology intersection as residential consumers prioritize convenience without sacrificing induction compatibility.
Federal Trade Commission advertising standards and California Air Resources Board building electrification rules jointly shape product labeling requirements and market access pathways for cookware manufacturers. The National Sanitation Foundation certification framework governs commercial kitchen equipment safety, creating tiered compliance obligations across household and professional end-user segments. Stakeholders must monitor state-level building code amendments to anticipate demand inflection points before inventory commitments lock in.
Market Dynamics
California's electric-only building codes are forcing cookware manufacturers to retool production lines for ferromagnetic compatibility, creating a supply-side bottleneck as residential kitchen electrification accelerates across the Western states.
Growth Catalysts
- Department of Energy appliance efficiency standards:Tightening compliance thresholds are mandating induction-compatible cookware in new residential construction, expanding the addressable household base.
- California Air Resources Board electrification mandates:Building code amendments in major metropolitan areas are prohibiting natural gas hookups, creating captive demand for electric cooking infrastructure.
- Stainless steel alloy innovation:Advanced 18/10 formulations with optimized ferrous base layers are improving energy transfer efficiency, reducing consumer switching friction from gas ranges.
Market Restraints
- Nickel price volatility:Stainless steel production depends on nickel input costs, which fluctuate with Indonesian export restrictions and Philippine mining disruptions.
- Flat-bottom precision manufacturing:Tolerance requirements within 0.5 millimeters demand specialized stamping equipment, constraining supplier base expansion.
- Cast iron weight limitations:Enameled cast iron vessels exceed ergonomic thresholds for aging demographics, limiting penetration in senior housing developments.
Strategic Opportunities
- New York State gas ban replication:Proposed legislation in Albany mirrors California's trajectory, opening Northeast corridor demand before inventory commitments solidify.
- Copper-core hybrid technology:Bonded five-ply constructions combining ferromagnetic exteriors with copper interiors are capturing professional chef segments previously loyal to gas.
- Mass retail private label expansion:Costco and Target are developing exclusive induction-compatible lines, creating volume channels outside traditional cookware distribution.
Industry Challenges
- Federal Trade Commission greenwashing enforcement:Advertising claims regarding "induction-ready" labeling face heightened scrutiny, extending compliance review timelines.
- Legacy aluminum inventory stranding:Non-ferromagnetic stockpiles require discount liquidation or export diversion, compressing margin recovery during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Induction Cookware Market |
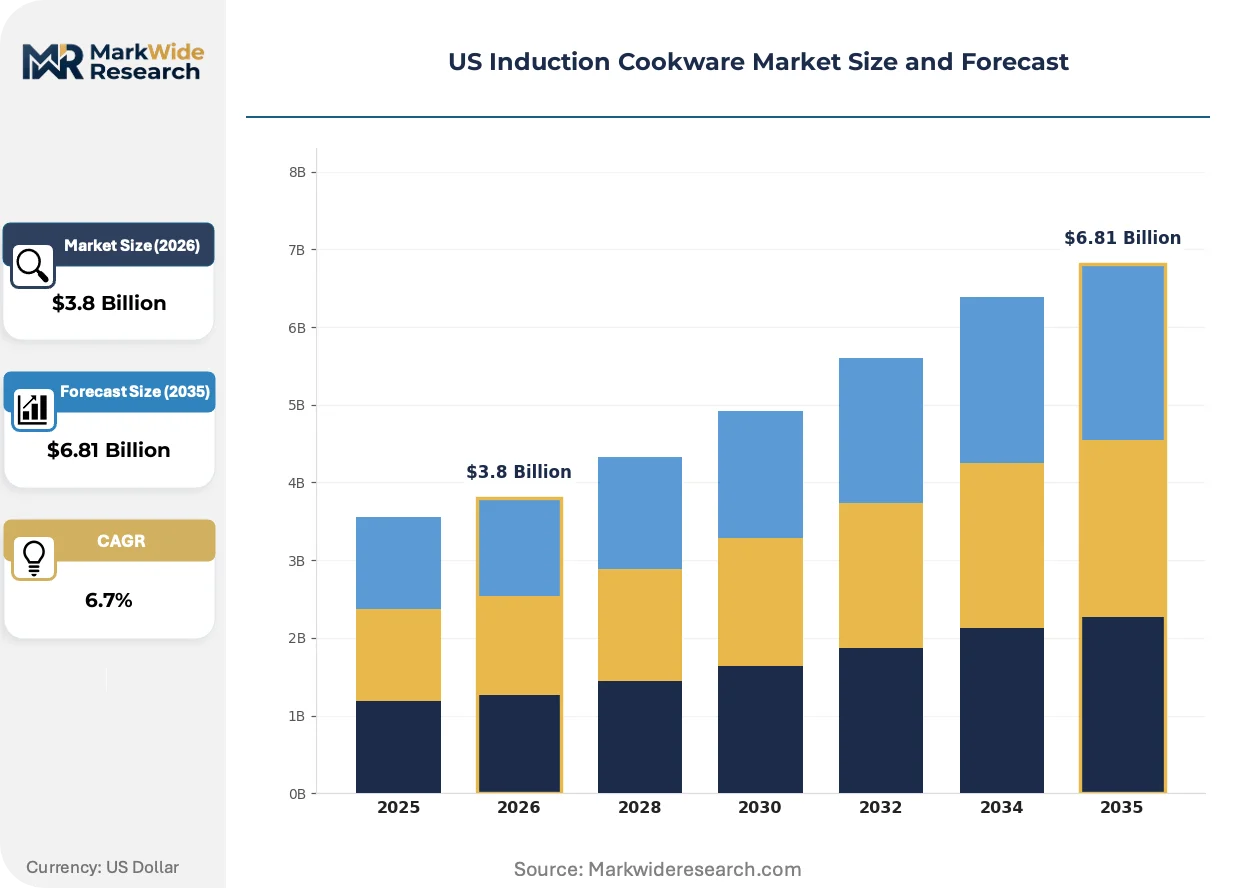
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frying Pans, Saucepans, Stock Pots, Griddles Material: Stainless Steel, Cast Iron, Non-Stick, Copper End User: Households, Professional Chefs, Restaurants, Culinary Schools Technology: Magnetic Induction, Electric, Hybrid, Traditional |
| Companies Covered | All-Clad, Le Creuset, T-fal, Scanpan, Cuisinart, Calphalon, Groupe SEB, Meyer Corporation, Fissler, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Induction Cookware Market Trends and Innovations
Material science advances and regulatory electrification mandates are converging to redefine cookware performance benchmarks, with ferromagnetic compatibility now a baseline rather than premium feature.
Multi-ply stainless steel construction is absorbing electromagnetic energy more efficiently than single-layer alternatives, enabling faster boil times and precise temperature control. Residential consumers in California and Washington are adopting these vessels at replacement-cycle acceleration, compressing the traditional ten-year cookware renewal timeline. The technology is absorbing market share from aluminum-clad alternatives by eliminating hot spots that damage non-stick coatings.
The Department of Energy's amended appliance standards are tightening test protocols for cookware energy transfer coefficients, effective for products manufactured after compliance deadlines. Manufacturers must submit third-party verification of ferrous content percentages and base flatness specifications. Small-batch artisan producers in Portland and Austin are struggling to absorb certification costs, ceding shelf space to scaled domestic manufacturers.
Builder-installed appliance packages are bundling induction ranges with certified cookware sets, shifting consumer acquisition from retail replacement to new construction specification. Multifamily developers in Seattle and Denver are specifying these packages to meet local electrification ordinances, bypassing traditional kitchenware retail channels. The Pacific Northwest multifamily segment exhibits the strongest bundling penetration, with appliance-coordinated cookware becoming standard in Class A rental inventory.
US Induction Cookware Market Segmentation
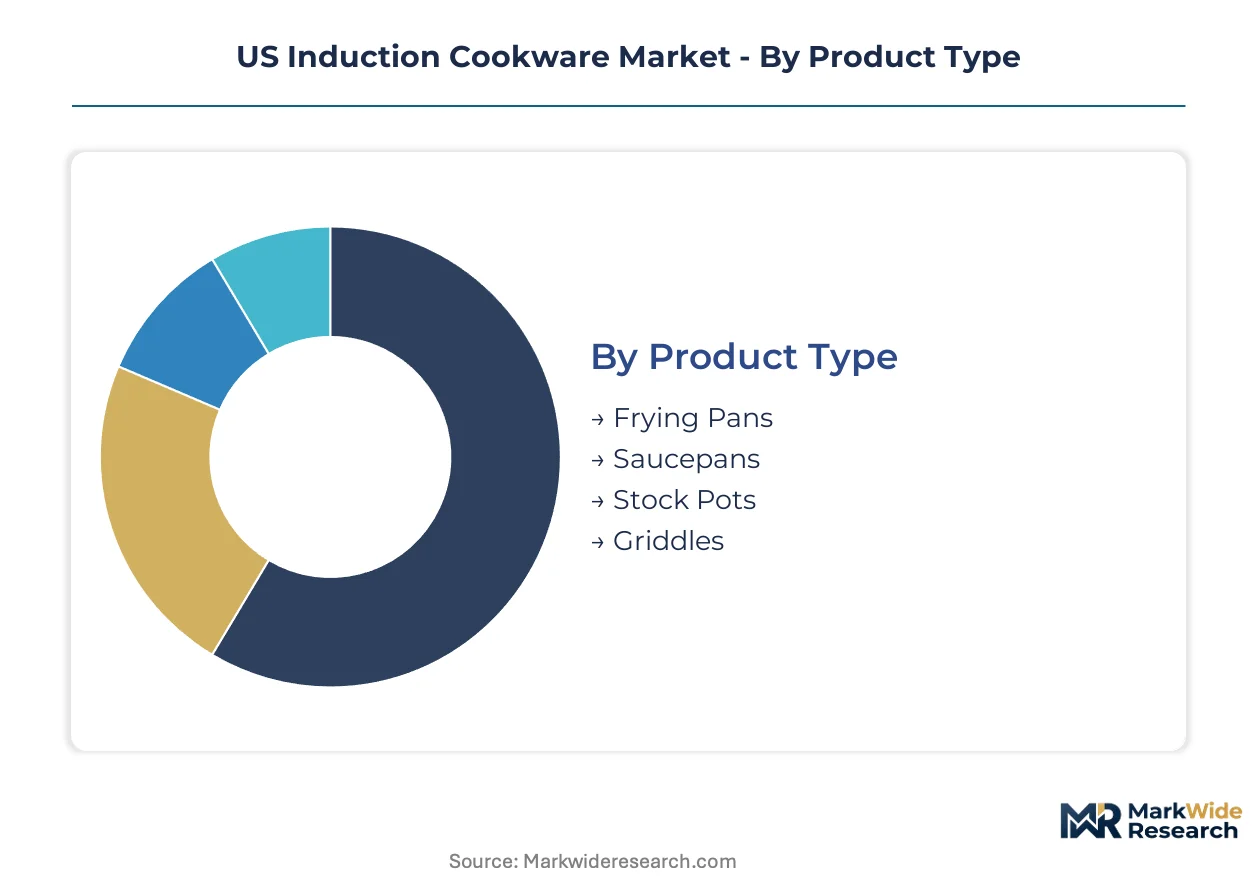
Induction cookware segmentation reveals how capital deployment, material science, and end-user requirements fragment manufacturing priorities. Each dimension carries distinct tooling costs and certification burdens that reshape competitive positioning across the value chain.
Product Type:
Frying pans and stock pots demand the heaviest upfront capital—multi-ply bonding presses and flat-bottom stamping equipment run into seven figures per production line.
- Frying Pans:Dominated by 18/10 stainless steel constructions with ferromagnetic base layers precision-bonded to aluminum cores. California residential retrofits are absorbing volume as electric-only building codes force gas-to-induction conversions in single-family homes.
- Stock Pots:Copper-core five-ply configurations command the highest unit economics, with professional kitchens in Manhattan and San Francisco driving specification. The weight and material cost restrict household penetration despite superior thermal response.
- Saucepans:Mid-volume category with standardized 2-4 quart capacities serving household meal preparation.
- Griddles:Rectangular surface designs for breakfast preparation; non-stick variants are climbing fastest among convenience-focused consumers.
Frying pans absorb the bulk of installed capacity; griddles are expanding most quickly.
Material:
Material selection determines electromagnetic efficiency thresholds and directly shapes Department of Energy compliance pathways.
- Stainless Steel:18/10 formulations with optimized ferrous content between 16-18% chromium and 10% nickel deliver the strongest energy transfer coefficients. The alloy's corrosion resistance sustains replacement cycles exceeding fifteen years in household use.
- Cast Iron:Enameled variants from Lodge and Le Creuset dominate heritage positioning, though ergonomic weight limits penetration in senior housing developments across Arizona and Florida.
- Non-Stick:Ceramic-reinforced PTFE coatings applied to ferromagnetic substrates serve convenience-seeking segments; California Air Resources Board emissions rules are tightening coating chemistry standards.
- Copper:Bonded exterior layers with stainless steel cooking surfaces capture professional chef loyalty previously anchored to gas ranges.
Stainless steel commands the majority of production throughput; non-stick formulations are gaining share fastest.
End User:
End-user segmentation splits procurement authority between retail replacement cycles and institutional specification channels.
- Households:Replacement-driven demand concentrated in coastal states with electrification mandates; consumers prioritize flat-bottom compatibility verification over premium material claims.
- Professional Chefs:Independent restaurant operators and culinary consultants specify copper-core and carbon steel variants; their purchasing power concentrates in New York, Chicago, and Los Angeles metro corridors.
- Restaurants:Chain operators bundle induction cookware with range purchases through foodservice distributors; NSF certification is mandatory for commercial kitchen deployment.
- Culinary Schools:Institutional procurement through state education budgets; Le Cordon Bleu and CIA campuses standardize on durable stainless steel sets for student training.
Households absorb the bulk of unit volume; restaurant chains are expanding procurement fastest as electrification mandates hit commercial kitchen construction.
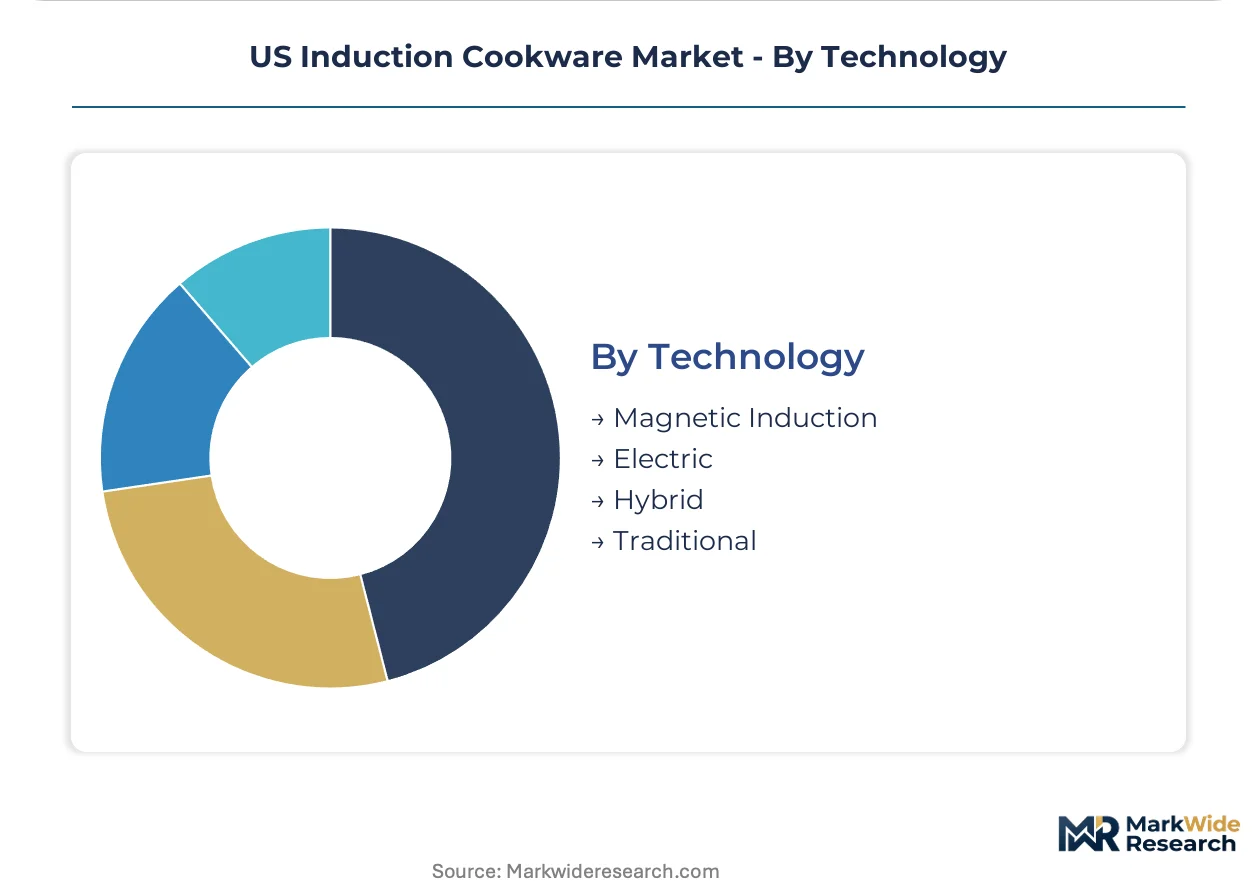
Technology:
Technology segmentation tracks how heat generation mechanisms align with regulatory efficiency standards and infrastructure access.
- Magnetic Induction:Electromagnetic field interaction with ferromagnetic vessels delivers 90% energy transfer efficiency, the highest of any cooking technology. Department of Energy test protocols now mandate this compatibility for federal procurement eligibility.
- Electric:Resistive coil systems in traditional electric ranges; cookware compatibility is universal but efficiency lags induction by thirty percentage points.
- Hybrid:Dual-fuel and induction-gas combinations serve transitional kitchens during electrification retrofits.
- Traditional:Gas flame and conventional electric coil systems; cookware demand is contracting in states with building code prohibitions on new gas hookups.
Magnetic induction captures the bulk of new product development; hybrid systems are climbing fastest as retrofit markets bridge infrastructure gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in California's Central Valley and Texas's Gulf Coast are concentrating induction cookware distribution infrastructure, drawing logistics investment away from legacy Midwest distribution corridors.
California
Electric-only building codes in Los Angeles and San Francisco are forcing residential kitchen retrofits at scale. The California Air Resources Board's 2023 emissions regulations mandate induction compatibility for all new appliance packages. Sacramento's distribution clusters are expanding cold storage and last-mile capacity to serve electrified multifamily developments.
Texas
Houston's petrochemical corridor is repurposing polymer expertise toward ceramic non-stick coating chemistry for induction substrates. ERCOT grid stability investments are accelerating commercial kitchen electrification in Dallas-Fort Worth restaurant clusters. Austin's builder-installed appliance packages are bundling induction ranges with certified cookware sets in new construction.
New York
The New York State gas ban legislation is replicating California's trajectory, opening Northeast corridor demand before inventory commitments solidify. NYC's Local Law 97 carbon caps are pressuring commercial kitchen operators toward induction retrofits. Buffalo's manufacturing heritage is attracting stainless steel stamping equipment for ferromagnetic base-layer production.
Washington
Seattle's multifamily Class A rental inventory is standardizing appliance-coordinated cookware packages to meet municipal electrification ordinances. The state's clean building performance standards are tightening compliance thresholds for residential construction. Spokane's inland logistics position is emerging as a regional distribution node for Pacific Northwest electrification retrofits.
Florida
Senior housing developments across Tampa and Orlando are resisting enameled cast iron due to ergonomic weight limitations, creating demand for lightweight stainless steel alternatives. The state's building code amendments are lagging coastal electrification mandates, preserving gas range compatibility in suburban construction. Miami's import channels are handling Latin American-sourced aluminum inventory diversion as ferromagnetic requirements tighten.
US Induction Cookware Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material tiers and distribution channels. The market structure fragments into three distinct competitive layers: scaled domestic manufacturers with captive stamping capacity, European heritage brands commanding premium positioning, and mass-market specialists controlling retail shelf space. Strategic moves concentrate on backward integration into ferromagnetic substrate supply and exclusive retail partnerships with electrification-focused appliance bundlers.
Among heritage European manufacturers, Le Creuset and Fissler exemplify the premium-tier archetype through enameled cast iron and multi-ply stainless steel positioning. All-Clad anchors the domestic manufacturing tier with its Pennsylvania-based bonding press operations. These three represent divergent responses to Department of Energy compliance pressures: European players leverage brand equity to absorb certification costs, while All-Clad exploits geographic proximity to California and Northeast electrification corridors for logistics advantage.
| Leading Market Players |
|---|
| All-Clad |
| Le Creuset |
| T-fal |
| Scanpan |
| Cuisinart |
| Calphalon |
| Groupe SEB |
| Meyer Corporation |
| Fissler |
| Others |
Pricing and Supply Chain Analysis
Specialized ferromagnetic stamping technicians in Pennsylvania's Monongahela Valley command wage premiums that compress margin spreads between premium multi-ply lines and entry-level induction-compatible alternatives. Labor-cost differentials between captive domestic bonding operations and outsourced Asian substrate finishing widen pricing-tier spreads as Department of Energy certification burdens escalate.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent attach to domestic multi-ply inventory available within two-week windows, while spot-market liquidation of non-ferromagnetic legacy stock trades at steep discounts. Pricing stratifies across premium, standard, and economy tiers based on NSF certification grade and bonded-layer complexity. Cost compression in the economy tier is intensifying because Indonesian nickel export restrictions are elevating stainless steel input costs. Restaurant chains exhibit the least price sensitivity due to bundled appliance procurement, while senior housing developers prioritize lightweight alternatives regardless of material grade.
Supply Chain Analysis
Domestic-content mandates in federal procurement specifications are reshaping sourcing patterns toward Pennsylvania, Ohio, and Wisconsin stamping facilities. Nickel draws from Indonesian smelters, Philippine mining operations, and Russian refined stockpiles; ferromagnetic substrate fabrication rests on German bonding press technology and Chinese cold-rolled steel inputs. Single-source vulnerability concentrates in Indonesian nickel processing after export license consolidation. Distribution runs through builder-installed appliance packages in electrification-mandate states and traditional kitchenware retail in lagging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as Department of Energy certification costs strand artisan producers without captive testing infrastructure. Weaker players face exit triggers from compliance timeline compression.
For Market Incumbents: To counter private-label encroachment from mass retail bundlers, All-Clad and domestic bonded-ply specialists should deepen backward integration into ferromagnetic substrate supply and lock exclusive appliance-coordination contracts with electrification-focused builders in California and Washington. Certification investment in accelerated NSF pathways preserves shelf space against European heritage brands. For New Entrants and Emerging Players: Launch via direct-to-builder specification channels targeting Class A multifamily developers in Seattle and Denver before inventory commitments solidify around incumbent appliance bundles. Lightweight stainless steel alternatives for Florida senior housing represent the most penetrable white-space segment. Ceramic non-stick coating partnerships with Houston petrochemical repurposing facilities offer material-differentiation entry. For Investors and Strategic Acquirers: The window for entry favors mid-cap stamping specialists with captive bonding press capacity and existing Department of Energy compliance documentation. Acquisition targets should demonstrate established relationships with California and Northeast appliance bundlers. The signal to watch is state-level building code amendment velocity beyond the current coastal concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferromagnetic Substrate Supply | Captive nickel-alloy sourcing insulates margin compression from Indonesian export volatility. |
| Exclusive Appliance-Coordination Contracts | Builder-installed packages in California multifamily developments bypass traditional retail channel fragmentation. |
| NSF Certification Acceleration | Commercial kitchen eligibility unlocks restaurant chain procurement concentrated in Manhattan and San Francisco corridors. |
| Lightweight Stainless Steel Product Line Extension | Florida senior housing penetration displaces enameled cast iron limited by ergonomic weight thresholds. |
| Ceramic Non-Stick Coating Partnership | Houston petrochemical repurposing aligns with California Air Resources Board tightening coating chemistry standards. |
Research Methodology
Independent corroboration across cookware manufacturing executives, appliance bundling procurement officers, and California building code administrators underwrites the qualitative findings. Primary interviews with NSF certification specialists, ferromagnetic substrate metallurgists, and multifamily development project managers combined with secondary validation from Department of Energy appliance standard filings, California Air Resources Board regulatory dockets, and SEC 10-K disclosures from listed conglomerates. Bottom-up production capacity assessments and top-down household electrification penetration models were triangulated.
Comparable historical reference periods spanning pre-electrification mandate baselines through current code-amendment implementation anchored the forecast window. The analytical framework segmented volume and value across product type, material formulation, end-user procurement authority, and technology compatibility dimensions throughout the projection horizon. CAGRs were derived from replacement-cycle compression rates in electrification-mandate states and professional chef specification shifts from gas to induction. Nickel price volatility bands and builder-installed package penetration curves served as industry-specific forecast inputs.
Regulatory timeline slippage, nickel supply disruption severity, and multifamily construction financing contraction are the dominant revision risks to the projection envelope. Forecasts reflect documented assumptions regarding state-level building code replication velocity and federal procurement mandate expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Pressure Cooker Market