
 Global Residential Water Heaters Market | 2026-2036
Global Residential Water Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Residential Water Heaters Market Foresight
The gap between premium tankless systems and commodity storage-tank units is expanding as efficiency mandates and energy-cost volatility split buyer budgets. Rheem Manufacturing Company leverages its captive distribution network to dominate the North American replacement channel. A. O. Smith Corporation anchors its position through backward integration into coated-tank manufacturing, insulating margin pools from steel-price swings. Bradford White Corporation specializes in professional-grade gas-fired units that sustain contractor loyalty and resist big-box commoditization.
Residential water heaters are pressurized vessels designed to store or instantaneously heat potable water to temperatures between 120°F and 140°F, employing combustion, electric resistance, or thermodynamic heat transfer to maintain delivery capacity across variable draw profiles. Heat pump water heaters capture the fastest growth trajectory within the product-type taxonomy, as coefficient-of-performance advantages above three-to-one displace electric-resistance units in electrification programs. Tankless configurations command premium positioning in single-family homes, while multi-family apartments sustain centralized storage-tank demand due to simultaneous-use load requirements and retrofit-space constraints.
The EU F-Gas Regulation and EPA ENERGY STAR certification frameworks collectively restrict refrigerant choices and minimum efficiency thresholds, forcing manufacturers to redesign heat-exchanger architectures and burner assemblies for compliance access. BIS efficiency labeling in India and China's GB standards for household appliances extend this regulatory density into emerging volume markets. Stakeholders must monitor refrigerant-transition timelines and regional subsidy qualification criteria to align product-portfolio investments with jurisdictional compliance windows.
Market Dynamics
Heat pump water heater technology is compressing replacement cycles and redrawing competitive moats as electrification mandates and refrigerant-phaseout deadlines converge on manufacturer R&D pipelines.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants forces fuel-switching from gas-fired tanks to electric heat pumps in European retrofits, opening subsidy-eligible upgrade pathways for single-family homeowners.
- China's tier-one urbanization:Building code enforcement in Beijing, Shanghai, and Shenzhen sustains volume demand for high-efficiency storage systems in new residential construction and existing stock replacement.
- Heat pump coefficient-of-performance gains:Three-to-one efficiency ratios versus electric resistance units are accelerating adoption in US electrification programs and Japanese all-electric home initiatives.
Market Restraints
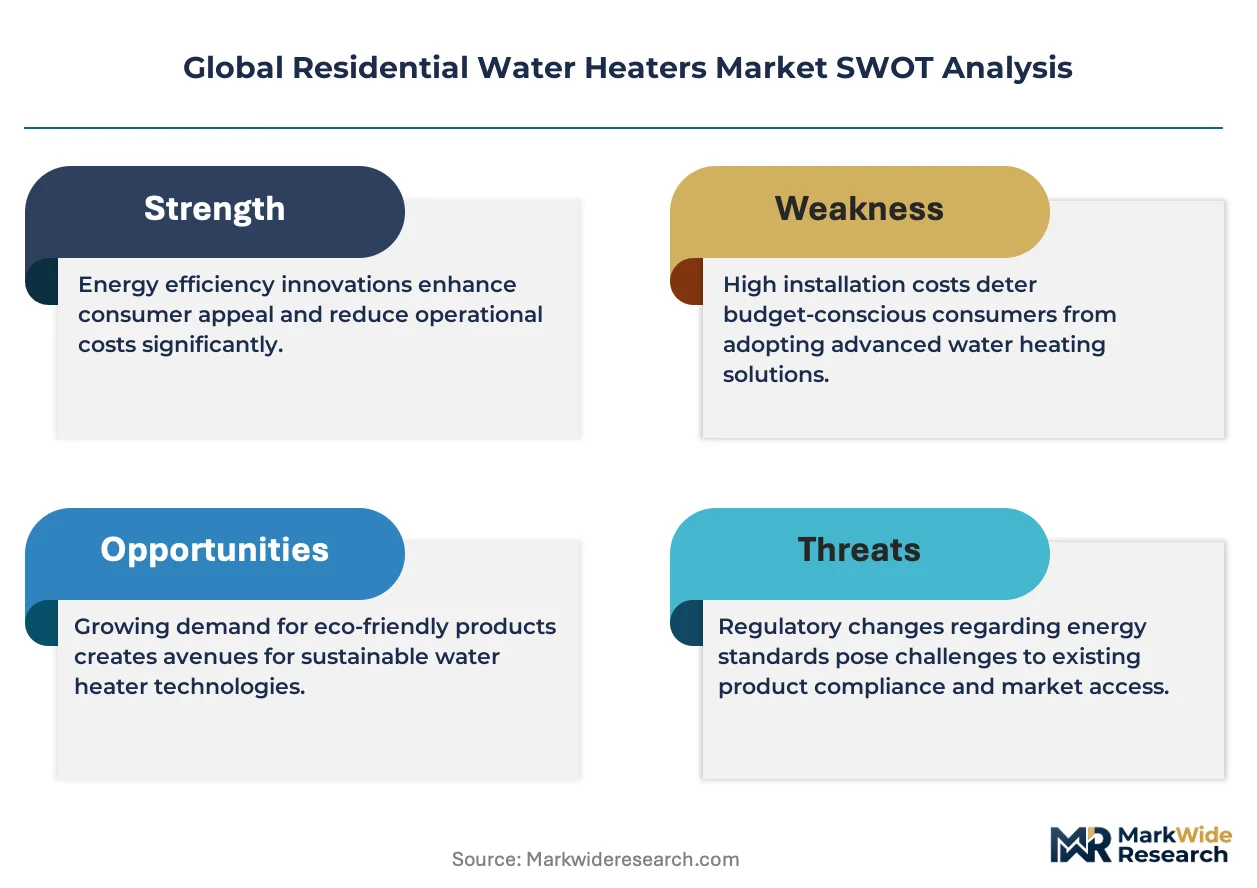
- Copper and steel input volatility:Tank and heat-exchanger manufacturing faces margin compression from commodity price swings that captive sourcing cannot fully neutralize.
- Refrigerant supply concentration:R-454B and R-290 alternatives depend on limited chemical plant capacity in China and the US Gulf Coast, creating bottleneck risk for heat pump production ramps.
- Cold-climate performance degradation:Air-source heat pumps lose efficiency below 40°F, restricting addressable market penetration in northern US states and Nordic geographies without hybrid backup configurations.
Strategic Opportunities
- India BIS efficiency labeling expansion:Tier-2 and tier-3 city enforcement of mandatory star ratings creates first-mover positioning for heat pump and solar-thermal hybrid entrants ahead of full market development.
- US Inflation Reduction Act rebates:Point-of-sale tax credits up to $2,000 for heat pump water heaters compress payback periods and unlock contractor channel partnerships for premium product lines.
- IoT-enabled predictive maintenance:Sensor-integrated tankless systems allow manufacturers to capture recurring service revenue and displace independent plumbers in warranty and extended-care contracts.
Industry Challenges
- EPA refrigerant-handling certification:Installer licensing requirements for A2L mildly flammable refrigerants extend sales-to-commissioning timelines and constrain available contractor capacity in rural markets.
- Legacy electrical panel upgrades:Heat pump installations frequently require 240V circuit additions or service upgrades, adding $1,500-$3,000 in non-product costs that stall consumer conversion at point of sale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Residential Water Heaters Market |
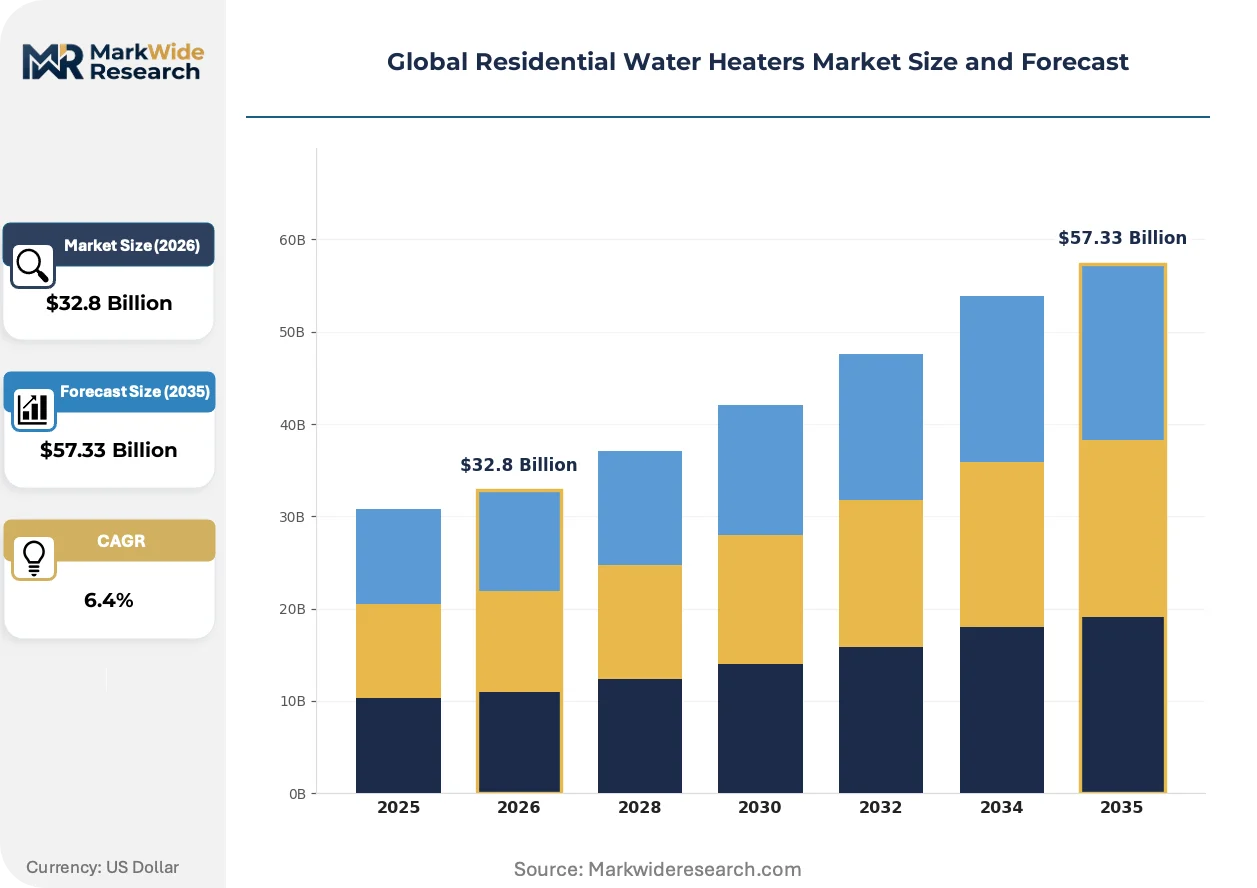
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless, Storage Tank, Heat Pump, Solar, Electric, Gas Fuel Type: Electricity, Natural Gas, Propane, Kerosene, Solar Energy Installation Type: Point-of-Use, Centralized, Wall-Mounted, Floor-Mounted, Outdoor End User: Single-Family Homes, Multi-Family Apartments, Vacation Homes, Condominiums |
| Companies Covered | Rheem Manufacturing Company, A. O. Smith Corporation, Bradford White Corporation, Ariston Holding N.V., Rinnai America Corporation, Bosch Thermotechnology Corp., Noritz America Corporation, Whirlpool Corporation, Haier Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Residential Water Heaters Market Shifts & Advancements
Product architecture and channel economics are diverging as efficiency mandates split the market between premium electrified systems and cost-optimized gas replacements, with software and service layers emerging as new margin pools.
Heat pump water heater technology is decentralizing thermal energy production in residential buildings by extracting ambient heat rather than generating it through combustion or resistance. Single-family homeowners in suburban US developments and EU retrofit programs are adopting these systems at accelerating rates as utility rebates stack with federal incentives. This distributed heat capture model is decentralizing the traditional central-boiler infrastructure in multi-family housing and compressing the addressable market for gas-fired tankless units in new construction.
REACH and RoHS substance restrictions in Europe, paralleled by EPA SNAP program rulings in the United States, are eliminating legacy refrigerant chemistries from heat pump water heater supply chains. Manufacturers must redesign compressor architectures and safety systems to accommodate A2L flammability classifications, extending product development cycles by 18-24 months. The professional-install channel bears the brunt of this transition, as big-box retailers lack the certified technician networks to handle refrigerant-bearing equipment.
Homeowner preference is migrating from emergency-replacement urgency toward planned-upgrade deliberation, with energy-cost volatility and electrification messaging extending research phases. Digital-native buyers in US coastal markets and German metropolitan areas are bypassing traditional contractor relationships to source equipment through direct-to-manufacturer platforms and utility marketplace aggregators. This disintermediation compresses distributor margins and forces incumbent manufacturers to build captive digital sales infrastructure or cede customer data to intermediaries.
Global Residential Water Heaters Market Segmentation
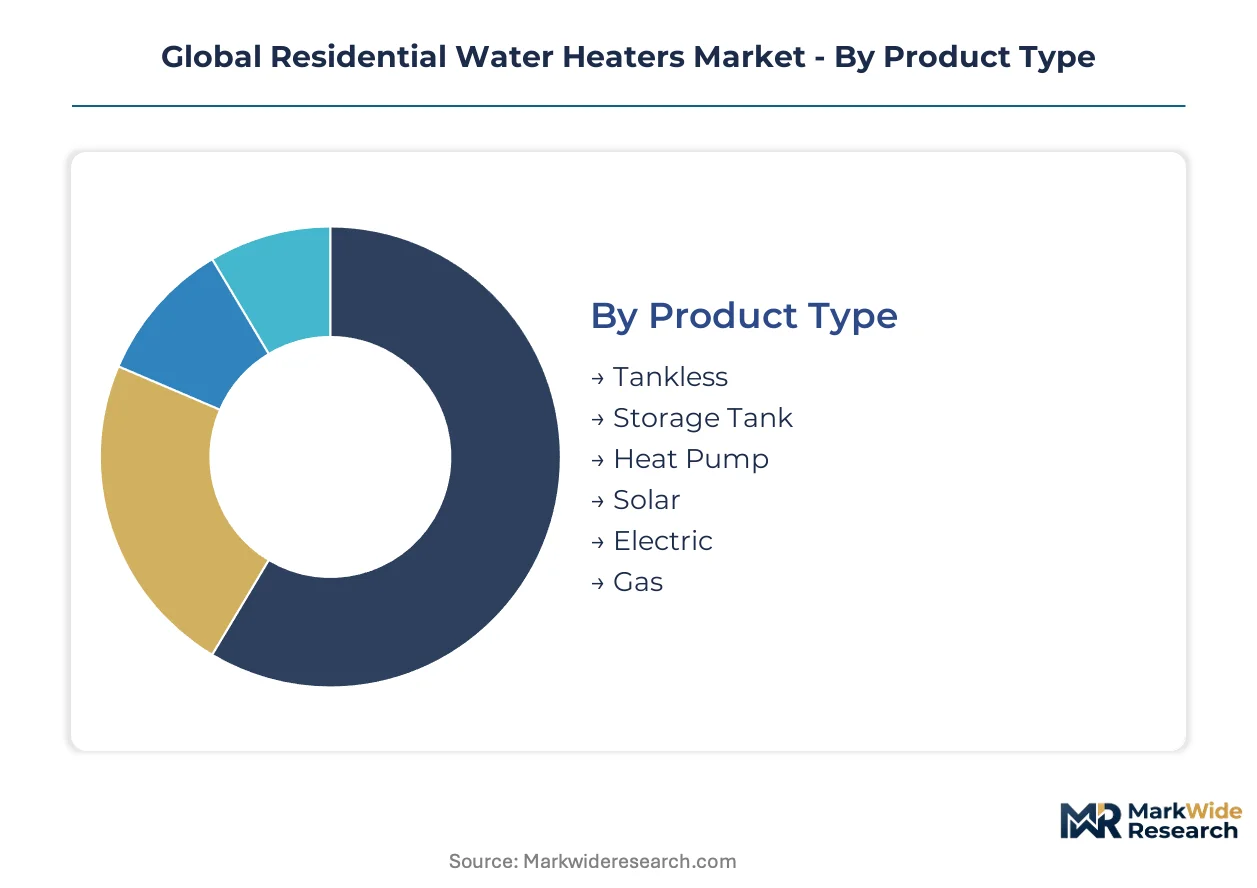
Residential water heater segmentation reveals divergent margin pools across product architectures and fuel sources, with electrification mandates and building code enforcement redrawing volume concentration. Manufacturers align portfolio investments against installation constraints and end-use load profiles rather than pursuing undifferentiated coverage.
Product Type:
Volume concentrates in mature storage architectures while premium growth clusters around thermodynamic efficiency gains and instantaneous delivery systems.
- Heat Pump:Thermodynamic systems extract ambient thermal energy through vapor-compression cycles, achieving coefficient-of-performance ratios exceeding three-to-one versus resistance heating. Demand clusters in US coastal electrification programs and EU F-Gas Regulation retrofit corridors where utility rebates compress payback periods.
- Tankless:On-demand gas or electric configurations eliminate standby thermal losses through compact heat-exchanger architectures. Single-family suburban developments in Germany and Japan drive specification for space-constrained renovations and all-electric home mandates.
- Storage Tank:Pressurized vessels maintain 40-80 gallon reserves at 120-140°F through submerged heating elements or burner assemblies. Commodity replacement cycles dominate volume in aging US housing stock.
- Solar:Evacuated-tube or flat-plate collectors supplement conventional heating through thermosiphon or active circulation systems. Mediterranean and Australian markets sustain niche demand through solar irradiance advantages.
- Electric:Resistance-element configurations persist in rental housing and regions with low electricity tariffs. Regulatory phaseout pressures mount in efficiency-mandate jurisdictions.
- Gas:Atmospheric and power-vented combustion systems retain cost advantages in natural-gas infrastructure corridors. Cold-climate performance sustains specification in northern US states and Canadian provinces.
Today's leader: Storage Tank. Tomorrow's challenger: Heat Pump.
Fuel Type:
Electrification policy vectors are compressing hydrocarbon demand curves while refrigerant-transition timelines constrain near-term heat pump supply elasticity.
- Electricity:Grid-sourced power drives resistance and heat pump configurations, with load-profile management emerging as utility priority. US Inflation Reduction Act rebates accelerate conversion from gas-fired tanks.
- Natural Gas:Pipeline-delivered methane retains installed-base dominance in North American single-family housing. EPA efficiency standards and local building electrification ordinances erode new-construction specification.
- Propane:Bottled fuel sustains rural and off-grid installations beyond natural-gas infrastructure reach. Tankless configurations dominate due to storage-space constraints.
- Kerosene:Liquid petroleum distillates persist in Japanese rural housing and emergency backup applications. Declining specification in new construction.
- Solar Energy:Direct thermal collection bypasses conversion losses inherent in photovoltaic-to-resistance pathways. Hybrid systems with electric backup gain traction in high-insolation zones.
Natural Gas holds the installed base. Electricity commands the policy momentum.
Installation Type:
Retrofit-space constraints and simultaneous-use load requirements partition demand between distributed point-of-use and centralized mechanical-room architectures.
- Centralized:Single-unit systems serve entire dwelling through insulated distribution plumbing. Multi-family apartments in China and India sustain specification for cost-optimized volume heating.
- Point-of-Use:Compact electric units install beneath sinks or adjacent to appliances for isolated demand nodes. Kitchen and bathroom renovations in European apartments drive specification.
- Wall-Mounted:Vertical tankless configurations reclaim floor space in Japanese compact housing and European retrofit projects. Condensing gas and electric models dominate.
- Floor-Mounted:Traditional tank architectures require structural support for 300-500 pound loaded weight. Basements and utility rooms in North American single-family homes standardize placement.
- Outdoor:Weatherized enclosures withstand freeze-risk climates through sealed combustion and insulated jackets. Southern US and Australian markets minimize indoor space allocation.
Centralized systems anchor multi-family economics. Point-of-Use gains from renovation intensity.
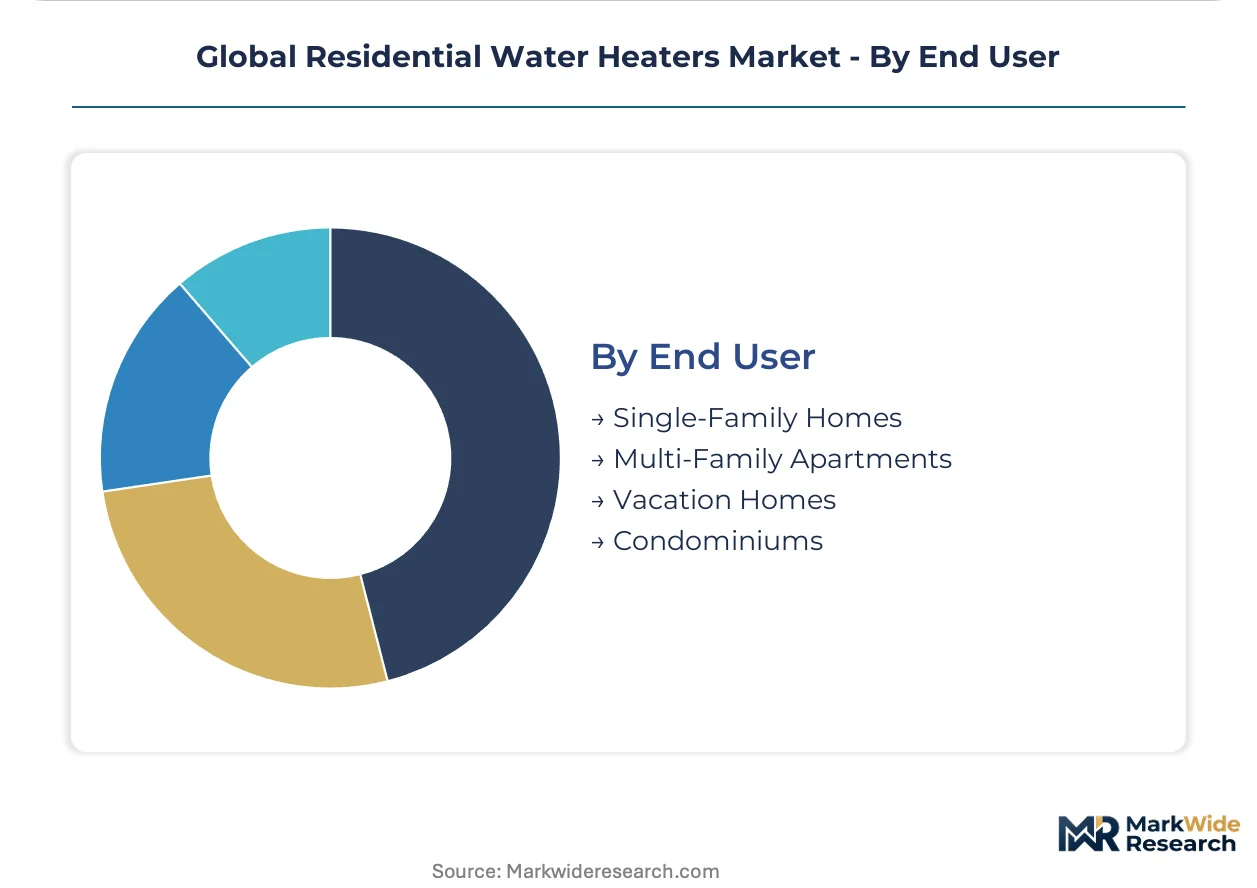
End User:
Ownership structure and occupancy patterns determine replacement-cycle urgency, energy-cost sensitivity, and technology-upgrade authorization pathways.
- Single-Family Homes:Owner-occupied detached dwellings generate 10-15 year replacement cycles and permit discretionary efficiency upgrades. Suburban US developments and EU retrofit programs concentrate heat pump adoption.
- Multi-Family Apartments:Centralized systems serve tenant populations with landlord-controlled capital decisions. China's tier-one cities enforce efficiency standards in new construction.
- Vacation Homes:Intermittent occupancy patterns favor tankless configurations for standby-loss elimination. Seasonal markets in Florida, Arizona, and Mediterranean coastal zones sustain demand.
- Condominiums:Homeowner association governance constrains individual unit modifications while permitting building-level system upgrades. Urban infill projects in Toronto and Vancouver standardize heat pump specification.
Single-Family Homes drive premium technology adoption. Multi-Family Apartments dictate volume manufacturing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands volume leadership through tier-one urbanization, while the United States drives premium electrification through federal subsidy programs. Divergent regulatory timelines and infrastructure maturity create distinct competitive arenas across major economies.
China
Beijing, Shanghai, and Shenzhen enforce GB standards for household appliances in new residential construction, sustaining replacement demand for high-efficiency storage systems. The Ministry of Ecology and Environment accelerates dual carbon goals through building code mandates. Manufacturing clusters in Guangdong and Shandong provinces supply domestic volume and export markets.
United States
The Inflation Reduction Act delivers point-of-sale tax credits up to $2,000 for heat pump water heaters, compressing payback periods in suburban single-family developments. EPA ENERGY STAR certification frameworks establish minimum efficiency thresholds for market access. Installation intensity concentrates in California, Texas, and Florida where electrification programs stack with utility rebates.
Germany
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing fuel-switching from gas-fired tanks to electric heat pumps in retrofit corridors. REACH and RoHS substance restrictions eliminate legacy chemistries from supply chains. Industrial concentration in Bavaria and North Rhine-Westphalia anchors heat-exchanger manufacturing for continental distribution.
Japan
METI all-electric home initiatives accelerate adoption of heat pump and tankless configurations in residential new builds. JIS standards govern safety and efficiency benchmarks for domestic manufacturers. The Kansai region around Osaka maintains production infrastructure for compact wall-mounted systems serving space-constrained urban housing.
India
BIS efficiency labeling expansion into tier-2 and tier-3 cities creates positioning opportunities for heat pump entrants ahead of full market development. The Bureau of Indian Standards mandates star ratings for electrical appliances in residential applications. Manufacturing activity clusters in Maharashtra and Gujarat where domestic assembly serves price-sensitive volume segments.
Global Residential Water Heaters Market Competitive Landscape
Top-tier vendors anchor premium electrification portfolios, while mid-scale specialists defend replacement-channel positions through contractor relationships. The vendor base stratifies across three archetypes: integrated manufacturers with captive distribution, component specialists with backward integration into coated-tank production, and regional assemblers serving price-elastic segments. Dominant competitive moves include capacity expansion in heat pump compressor architectures and strategic partnerships with utility marketplace aggregators.
Among North American manufacturers, Rheem Manufacturing Company and A. O. Smith Corporation exemplify integrated archetypes with established contractor-channel presence, while Bradford White Corporation occupies a position within professional-grade specialization. Ariston Holding N.V. and Bosch Thermotechnology Corp. represent European-based vendors navigating refrigerant-transition compliance. Haier Inc. anchors Chinese volume manufacturing for domestic and export markets. These entities collectively illustrate the geographic and strategic diversity structuring competitive positioning across electrification and conventional product lines.
| Leading Market Players |
|---|
| Rheem Manufacturing Company |
| A. O. Smith Corporation |
| Bradford White Corporation |
| Ariston Holding N.V. |
| Rinnai America Corporation |
| Bosch Thermotechnology Corp. |
| Noritz America Corporation |
| Whirlpool Corporation |
| Haier Inc. |
| Others |
Supply & Pricing Matrix
Single-family homeowners in suburban US developments and EU retrofit corridors anchor demand concentration, locking in a project-based pricing model where equipment cost separates from installation labor and electrical panel upgrade services. This unbundled structure lets manufacturers defend premium heat pump positioning while contractors capture variable retrofit margins.
Pricing Analysis
Unbundled equipment and installation pricing dominates residential water heater transactions, with three-tier pricing structure across premium, standard, and economy levels separating heat pump systems from gas-fired tankless and commodity storage tanks. Price differentiation rests on ENERGY STAR certification tier and after-sales warranty bundling. Cost compression in electric resistance segments is intensifying because of regulatory phaseout pressures. Multi-family landlords exhibit highest price sensitivity due to capital constraint cycles, while single-family electrification adopters show lowest sensitivity under stacked subsidy programs.
Supply Chain Analysis
Regional distribution centers in the US Midwest and Germany's North Rhine-Westphalia anchor hub-and-spoke patterns serving contractor channels and big-box retail networks. Manufacturing concentrates in China, Mexico, and the United States for tank fabrication and final assembly. Raw material inputs draw from coated steel sheet, copper tubing, and compressor refrigerant chemistries. Single-source vulnerability in R-454B and R-290 refrigerant supply creates bottleneck exposure for heat pump production ramps. Distribution runs through captive dealer networks for premium brands and open distribution for commodity replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between the United States, where Inflation Reduction Act rebates compress heat pump payback periods, and India, where BIS efficiency enforcement in tier-2 cities precedes subsidy infrastructure and creates early-mover positioning at lower customer acquisition cost.
For Market Incumbents: Cement contractor channel loyalty through certified installer training programs for A2L refrigerant handling, insulating against big-box disintermediation. Deepen upstream control over coated-tank manufacturing to neutralize steel price volatility. Prioritize heat pump compressor capacity expansion in US Southeast manufacturing clusters ahead of electrification mandate deadlines.
For New Entrants and Emerging Players: Begin with India's tier-2 and tier-3 city enforcement gaps for BIS star ratings, where heat pump penetration remains underdeveloped and first-mover brand recognition can be established before full market development. Target multi-family apartment centralized systems in China's tier-one cities through cost-optimized volume manufacturing partnerships with domestic assembly specialists.
For Investors and Strategic Acquirers: HVAC equipment conglomerates pursuing electrification portfolio completion are the most active acquirer in this space, seeking heat pump technology assets and captive distribution networks. Long-term viability hinges on refrigerant-transition compliance capability and utility marketplace aggregator partnerships. Acquisition target archetype: mid-scale manufacturers with backward integration into tank production and established regional contractor relationships. Monitor EPA refrigerant-handling certification rollout timelines as inflection indicator for installer capacity constraints and consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Compressor Capacity Expansion | Secures supply elasticity ahead of EU F-Gas Regulation phaseout deadlines and US IRA demand surges. |
| A2L Refrigerant Safety System Redesign | Unlocks market access under EPA SNAP program rulings and REACH substance restrictions. |
| Utility Marketplace Aggregator Partnership | Captures digital-native buyer segments bypassing traditional contractor channels in coastal US markets. |
| Certified Installer Network Development | Defends professional-install channel positioning against big-box retail commoditization. |
| Coated-Tank Manufacturing Backward Integration | Insulates margin pools from steel price volatility and supply disruption. |
Research Methodology
Direct dialogue with water heater product managers, HVAC contractor business owners, utility program administrators, and building code enforcement officials grounded qualitative assessment, cross-referenced with customs trade data, EPA ENERGY STAR certification databases, SEC 10-K filings from listed manufacturers, and GB standards documentation from China's Ministry of Ecology and Environment. Bottom-up unit shipment modeling and top-down value estimation triangulated market sizing across product architectures and fuel types.
Bottom-up demand modeling tracked replacement-cycle timing by housing vintage, electrification program enrollment, and building code enforcement intensity, while top-down analysis validated aggregate value against manufacturer revenue disclosures and distributor channel flow data. Segmentation dimensions included product type, fuel source, installation configuration, and end-user ownership structure across the projection horizon. CAGRs derived from fitted adoption curves incorporating regulatory mandate timelines and subsidy program sunsets.
Several conditions sit outside the modeled scope, including geopolitical trade disruption affecting steel and copper input flows, refrigerant supply chain nationalization policies, and extreme weather events accelerating emergency replacement cycles beyond historical patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
US Household Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
France Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market