
 Switzerland Home Appliances Market | 2026-2036
Switzerland Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Home Appliances Market Analytics
Subscription-based maintenance and software-defined feature upgrades is repositioning how manufacturers capture lifetime value from Swiss households. BSH Hausgeräte GmbH leverages its integrated service network to lock in recurring revenue across refrigeration and cooking portfolios. Miele sustains premium positioning through exceptional R&D intensity and Zurich-centric brand equity. Electrolux AB competes on manufacturing scale and channel breadth across French-speaking western cantons.
Switzerland Home Appliances encompass electrically powered domestic equipment designed for food preservation, textile care, meal preparation, and ambient comfort, typically operating at 230V/50Hz with energy efficiency ratings scaled from A to G under revised EU-harmonized frameworks. Refrigerators and washing machines anchor volume demand while smart appliances and IoT-enabled platforms command expanding margin pools in affluent urban households. The residential end-user segment dominates absolute consumption, though hospitality procurement in Alpine tourism corridors generates disproportionate premium-unit pull.
Swiss Federal Energy Ordinance, CE marking alignment, and cantonal building codes collectively mandate escalating efficiency thresholds and connected-home compatibility for new installations. These frameworks compress replacement cycles for legacy equipment while elevating compliance costs for non-integrated importers. Stakeholders must monitor Geneva and Basel regulatory harmonization with evolving EU Ecodesign requirements to anticipate product-line obsolescence risks.
Market Dynamics
The Swiss Federal Energy Ordinance is compressing replacement cycles by mandating escalating efficiency thresholds for new installations, forcing manufacturers to accelerate R&D pipelines while cantonal building codes in Zurich and Geneva demand connected-home compatibility.
Growth Catalysts
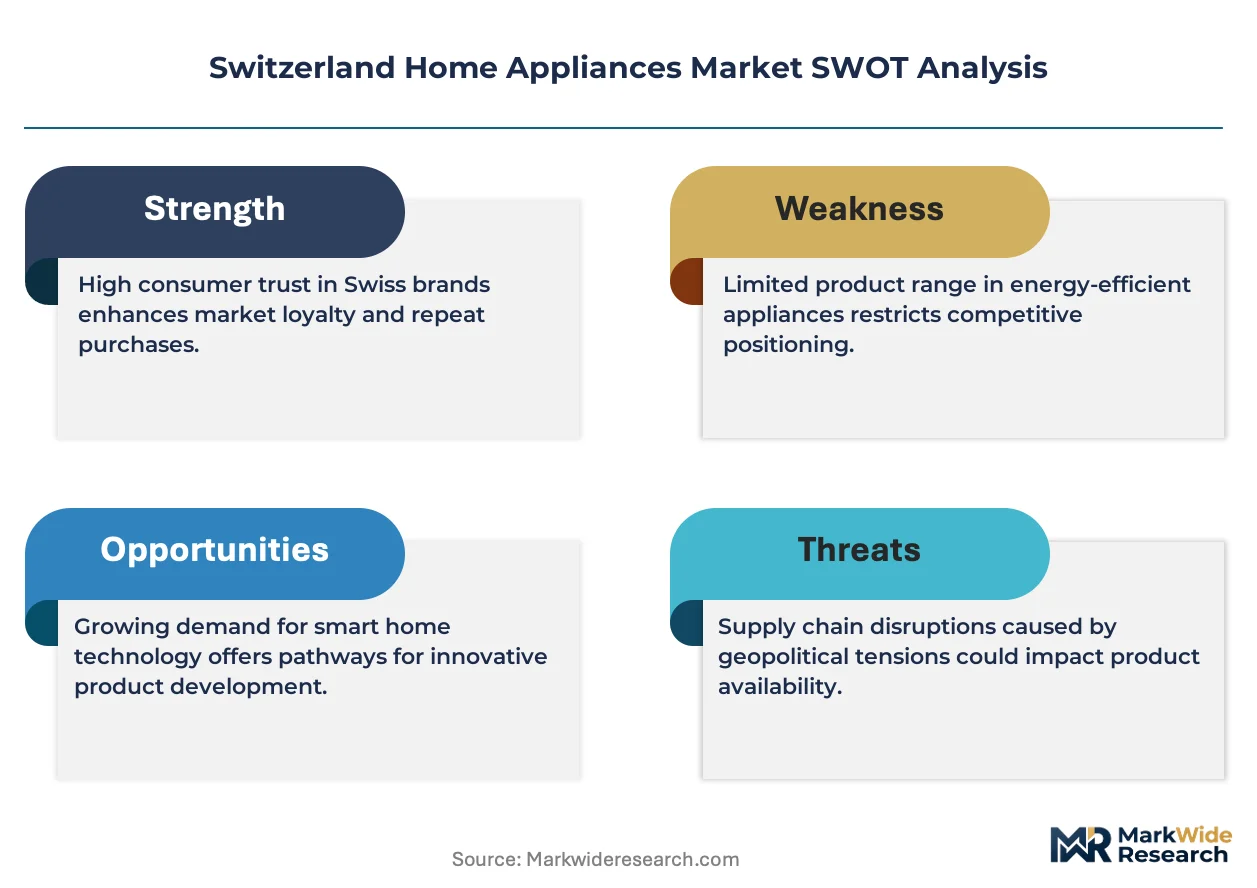
- Swiss Federal Energy Ordinance:Tightening efficiency thresholds for refrigeration and washing equipment are accelerating replacement demand among legacy appliance owners in German-speaking cantons.
- Alpine tourism corridor procurement:Hospitality operators in St. Moritz, Zermatt, and Davos are driving disproportionate premium-unit pull for connected kitchen ecosystems and smart climate systems.
- IoT platform convergence:Integration of energy management software with appliance hardware is enabling subscription-based maintenance revenue streams from affluent urban households.
Market Restraints
- Copper and rare earth input volatility:Motor and compressor manufacturing faces margin pressure from concentrated supply origins outside European trading zones.
- CE marking alignment costs:Non-integrated importers bear disproportionate compliance burdens as Swiss regulations harmonize with evolving EU Ecodesign requirements.
- Technical limitation in grid integration:Legacy electrical infrastructure in rural Ticino and Valais cantons constrains smart appliance penetration despite consumer willingness.
Strategic Opportunities
- Underpenetrated French-speaking western cantons:Vaud and Neuchâtel exhibit lower smart appliance density than Zurich, presenting channel expansion potential for ecosystem providers.
- Cantonal building code mandates:Basel-Stadt and Geneva are requiring connected-home compatibility for new residential construction, creating regulatory tailwind for compliant product lines.
- Direct-to-installer distribution:Bypassing traditional retail through certified technician networks reduces margin leakage and captures renovation-driven demand.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for appliance IoT stacks competes with fintech and medtech sectors for limited Swiss technical labor pools.
- Dual certification timeline friction:Swissmedic alignment with EU notified body procedures creates lag between product readiness and market authorization.
- Legacy system integration complexity:Retrofitting connected capabilities into installed base equipment requires backward-compatible communication protocols that extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Home Appliances Market |
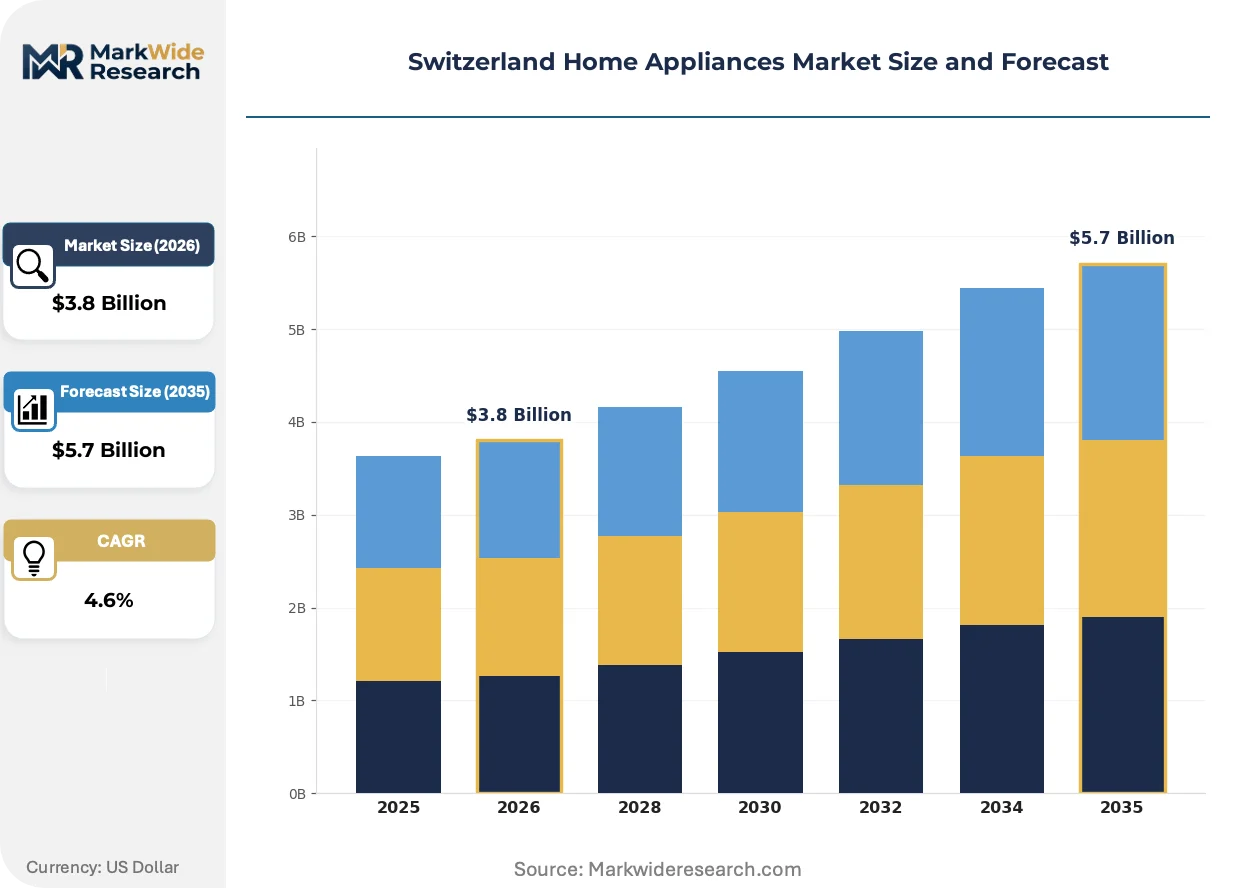
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Microwaves End User: Residential, Commercial, Institutions, Hospitality Technology: Smart Appliances, Energy Efficient, Traditional Technology, IoT Enabled Distribution Channel: Online Retail, Offline Stores, Direct Sales, Wholesalers |
| Companies Covered | BSH Hausgeräte GmbH, Siemens, Whirlpool Corporation, Miele, Bosch, Electrolux AB, Gorenje Group, Philips, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Home Appliances Market Evolving Landscape
Swiss home appliance architecture is pivoting from standalone hardware to software-defined platforms where feature upgrades and predictive maintenance reshape manufacturer-customer relationships. Three convergent developments are reconfiguring competitive positioning.
Refrigeration compressor technology is modularizing into swappable sub-assemblies that enable field replacement rather than full-unit disposal. Premium residential buyers in Zurich's Seefeld district and Geneva's Eaux-Vives are adopting these systems at twice the rate of standard configurations. This modularity is compressing service revenue timelines while extending nominal product lifespans beyond traditional depreciation schedules.
The Swiss Federal Energy Ordinance's 2024 efficiency recalibration is forcing manufacturers to redesign thermal insulation assemblies and motor control algorithms. Industrial consequence includes accelerated obsolescence of A-rated legacy inventory and elevated R&D allocation toward heat pump integration. The cooking appliance segment faces the steepest compliance gradient, with Geneva-based distributors already clearing non-compliant stock from warehouse positions.
Subscription-based ownership is displacing outright purchase among renovation-active households in Basel and Lausanne. Traditional electronics retailers are losing appliance attachment rates to manufacturer-direct service contracts bundled with installation and preventive maintenance. This behavioral pivot is most pronounced in multi-unit residential developments where property managers aggregate fleet-level agreements for common-area laundry and kitchen equipment.
Switzerland Home Appliances Market Segmentation
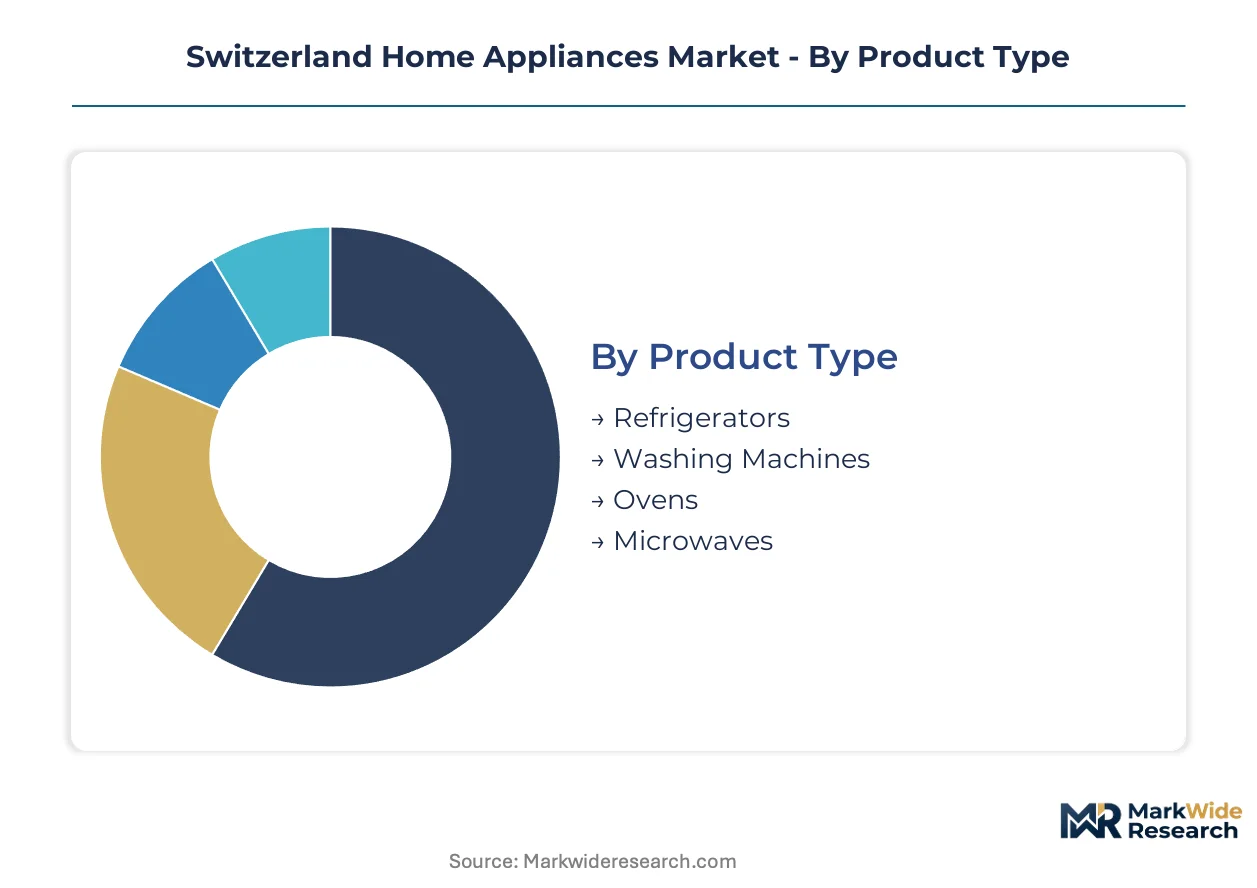
Swiss home appliance purchasing patterns diverge sharply between renovation-driven replacement cycles in German-speaking cantons and hospitality procurement in Alpine tourism corridors. Understanding these segment boundaries clarifies where manufacturers must configure distinct product-service bundles versus standardized offerings.
Product Type:
Replacement urgency varies by appliance category based on regulatory pressure and failure modes.
- Refrigerators:Compressor-driven cold chain equipment with modular sub-assembly designs enabling field replacement rather than full-unit disposal. Swiss Federal Energy Ordinance efficiency recalibrations are accelerating obsolescence of A-rated legacy inventory in Zurich and Geneva residential renovations.
- Washing Machines:Motor and drum assemblies operating at 230V/50Hz with heat pump integration emerging as compliance pathway. Demand concentrates in multi-unit residential developments across Basel-Stadt where property managers aggregate fleet-level maintenance agreements.
- Ovens:Thermal insulation assemblies facing steepest compliance gradient under cooking appliance efficiency mandates.
- Microwaves:Magnetron-based heating equipment with shorter replacement cycles than built-in alternatives.
Volume sits with Refrigerators; growth tilts toward Washing Machines.
End User:
Contracting structures determine whether procurement favors upfront purchase or subscription-based ownership models.
- Residential:Individual households in renovation-active segments across German-speaking cantons. Premium buyers in Zurich's Seefeld district adopt connected kitchen ecosystems at twice standard configuration rates.
- Commercial:Property managers and facility operators aggregating fleet-level agreements for common-area equipment in multi-unit developments.
- Institutions:Public sector and educational facilities with extended procurement timelines and connected-home compatibility mandates.
- Hospitality:Alpine tourism operators in St. Moritz, Zermatt, and Davos driving disproportionate premium-unit pull for smart climate systems and connected kitchen platforms.
Residential commands absolute volume; Hospitality generates steepest margin expansion.
Technology:
Software-defined capabilities are repositioning hardware margins toward recurring service revenue streams.
- Smart Appliances:Connected platforms with firmware-upgradable feature sets and predictive maintenance integration. Affluent urban households in Geneva's Eaux-Vives are displacing outright purchase with manufacturer-direct service contracts.
- Energy Efficient:Heat pump-integrated and advanced insulation assemblies meeting tightened Swiss Federal Energy Ordinance thresholds. Cantonal building codes in Basel and Geneva mandate compatibility for new residential construction.
- Traditional Technology:Non-connected electromechanical systems with declining installed base share in urban centers.
- IoT Enabled:Energy management software convergence with appliance hardware enabling subscription-based maintenance revenue from renovation-active households in Lausanne.
Traditional Technology retains installed base dominance; IoT Enabled climbs the fastest on new installation share.
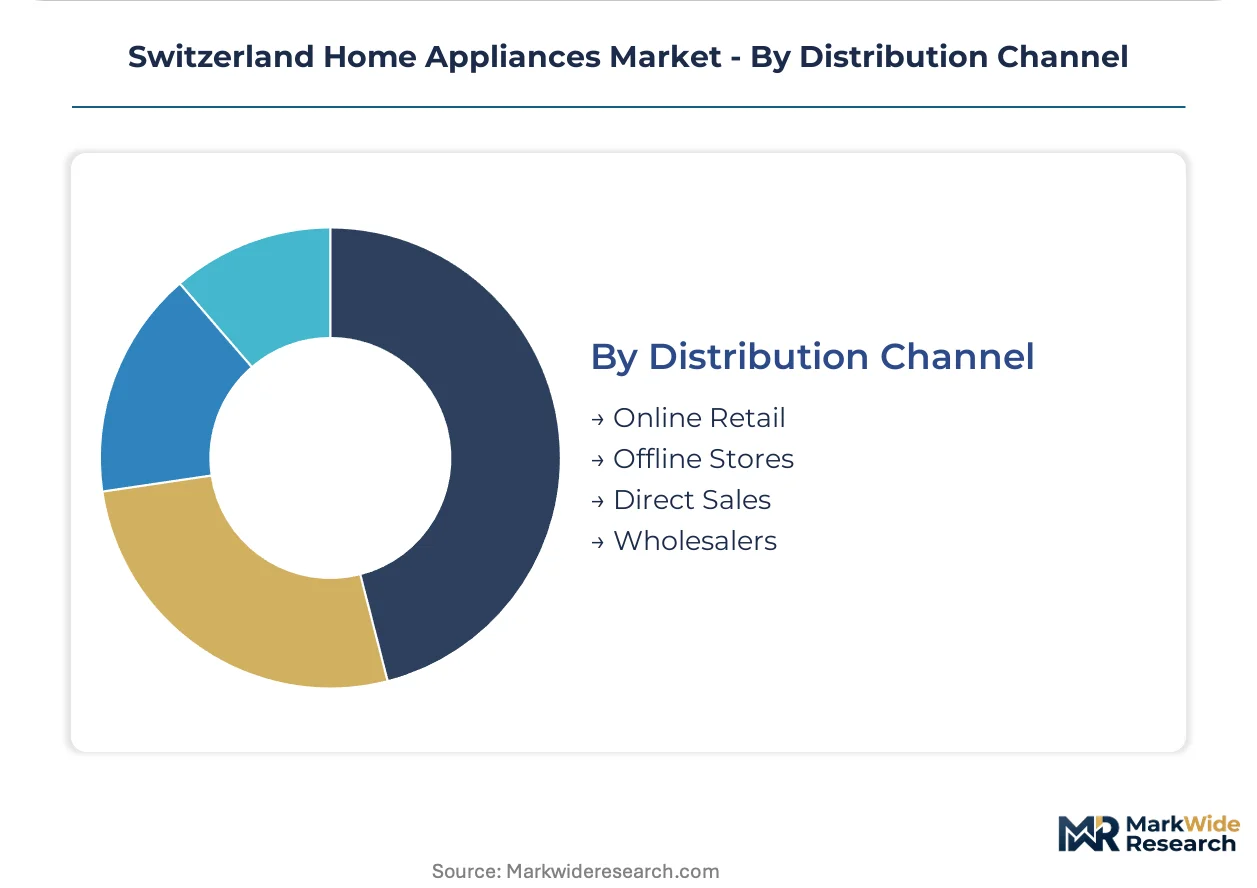
Distribution Channel:
Channel selection determines margin retention and installer relationship depth.
- Online Retail:Digital platforms capturing standard appliance replacement demand with limited service attachment. Electronics retailers are losing appliance attachment rates to manufacturer-direct models.
- Offline Stores:Traditional retail networks with demonstration capabilities for premium product tiers in French-speaking western cantons.
- Direct Sales:Manufacturer-certified technician networks bypassing retail margin leakage to capture renovation-driven demand in Vaud and Neuchâtel.
- Wholesalers:Bulk procurement channels serving hospitality and institutional segments with fleet-level contracting.
Offline Stores maintain volume throughput; Direct Sales gains share fastest on margin retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zurich anchors Switzerland's home appliance demand, with renovation-active households in the Seefeld district adopting connected kitchen ecosystems at twice standard configuration rates. German-speaking cantons concentrate replacement volume while Alpine tourism corridors generate premium-unit pull. Cantonal building codes in Basel and Geneva mandate connected-home compatibility for new residential construction.
German-Speaking Cantons
Zurich and Basel-Stadt drive replacement demand through household renovation rates outpacing national averages. The Swiss Federal Energy Ordinance compresses replacement cycles by mandating escalating efficiency thresholds for refrigeration and washing equipment. BSH Hausgeräte GmbH leverages its integrated service network to capture recurring revenue across these urban centers.
French-Speaking Western Cantons
Vaud and Neuchâtel exhibit lower smart appliance density than Zurich, presenting channel expansion potential for ecosystem providers. Electrolux AB competes on manufacturing scale and channel breadth across this underpenetrated region. Property managers in Lausanne aggregate fleet-level agreements for multi-unit residential developments.
Alpine Tourism Corridors
Hospitality operators in St. Moritz, Zermatt, and Davos drive disproportionate premium-unit pull for smart climate systems and connected kitchen platforms. Subscription-based maintenance contracts displace outright purchase among renovation-active households. Miele sustains premium positioning through Zurich-centric brand equity in these high-margin segments.
Ticino and Valais
Legacy electrical infrastructure in rural Ticino and Valais cantons constrains smart appliance penetration despite consumer willingness. Technical limitation in grid integration limits IoT-enabled platform deployment. Direct-to-installer distribution networks bypass traditional retail to capture scattered renovation demand.
Geneva
Geneva's Eaux-Vives district leads adoption of manufacturer-direct service contracts bundled with installation and preventive maintenance. Cantonal building codes require connected-home compatibility for new residential construction. Geneva-based distributors are clearing non-compliant cooking appliance stock from warehouse positions ahead of efficiency recalibrations.
Switzerland Home Appliances Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Switzerland's home appliance market. The vendor base concentrates around integrated manufacturers with captive service networks and premium-positioned specialists with R&D intensity advantages. Three archetypes dominate: full-ecosystem providers with subscription revenue models, scale-driven broadliners with channel breadth, and premium specialists with exceptional brand equity. Competitive moves center on direct-to-installer distribution bypasses and software-defined feature upgrade platforms.
Within the full-ecosystem tier, BSH Hausgeräte GmbH and Bosch exemplify integrated service network operators capturing recurring revenue across refrigeration and cooking portfolios. Miele occupies a premium specialist position anchored by Zurich-centric brand equity and exceptional R&D intensity. Electrolux AB represents the scale-driven archetype competing on manufacturing scale and channel breadth across French-speaking western cantons.
| Leading Market Players |
|---|
| BSH Hausgeräte GmbH |
| Siemens |
| Whirlpool Corporation |
| Miele |
| Bosch |
| Electrolux AB |
| Gorenje Group |
| Philips |
| LG Electronics |
| Others |
Value Network & Pricing Analysis
Copper price volatility on the London Metal Exchange cascades through Swiss appliance manufacturing into three distinct pricing tiers, with motor and compressor assemblies absorbing upstream commodity swings while subscription-based service bundles insulate premium positioning from spot-market turbulence.
Pricing Analysis
Margin tightening in standard-tier refrigeration traces to Swiss Federal Energy Ordinance compliance costs and rare earth magnet price exposure. Three-tier pricing structure across premium, standard, and economy levels separates Zurich-connected ecosystem buyers from Valais price-sensitive replacement purchasers. Cost-down pressure on entry-level washing machines accelerates because CE marking alignment burdens fall disproportionately on non-integrated importers. Hospitality procurement in Alpine corridors shows least price sensitivity due to fleet-level contracting power.
Supply Chain Analysis
Regional distribution centers in Stuttgart and Milan anchor hub-and-spoke patterns serving German-speaking cantons and Ticino respectively. Motor and compressor manufacturing draws from concentrated supply origins in China, Germany, and Poland. Copper winding and rare earth magnet dependencies expose assemblers to single-source vulnerability for neodymium processing. Distribution runs through manufacturer-certified technician networks bypassing traditional retail for renovation-driven demand capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swiss home appliance competition has become a vertical-integration race where captive service networks and firmware development capabilities determine margin retention against subscription-native challengers.
For Market Incumbents: Anchor recurring revenue through direct-to-installer distribution expansion in underpenetrated Vaud and Neuchâtel cantons. Deepen backward integration into predictive maintenance software stacks to defend against IoT-native entrants. The Swiss Federal Energy Ordinance's efficiency recalibration timeline compresses R&D windows for non-integrated assemblers. For New Entrants and Emerging Players: Property managers in Lausanne multi-unit residential developments represent an underserved buyer archetype with aggregated fleet-level procurement power. French-speaking western cantons offer channel whitespace with lower smart appliance density than Zurich. A certified technician network partnership bypasses retail margin leakage while capturing renovation-driven replacement cycles. For Investors and Strategic Acquirers: The window for entry favors firmware-development specialists with appliance IoT stack capabilities over hardware-only assemblers. Long-term viability centers on software-defined feature upgrade platforms that extend customer lifetime value beyond traditional depreciation schedules. Watch Swissmedic-EU notified body harmonization progress as regulatory lag inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Installer Distribution Expansion | Bypasses retail margin leakage in Vaud and Neuchâtel renovation corridors. |
| Predictive Maintenance Platform Development | Captures subscription revenue from Geneva Eaux-Vives affluent households. |
| Heat Pump Integration R&D Investment | Secures Swiss Federal Energy Ordinance compliance for refrigeration portfolios. |
| Firmware-Defined Feature Upgrade Architecture | Extends product lifespans beyond traditional depreciation schedules in Zurich. |
| Cantonal Building Code Compliance Certification | Unlocks Basel-Stadt and Geneva new construction mandates for connected-home compatibility. |
Research Methodology
Document review covered Swiss Federal Energy Ordinance amendments, cantonal building code filings, and EU Ecodesign harmonization protocols, complemented by interviews with appliance R&D directors, certified installation network operators, property management procurement leads, and hospitality facility managers across Zurich, Geneva, and Lausanne. Secondary validation drew from SEC filings of listed manufacturers, Swiss customs trade data, and renovation permit databases. Bottom-up unit shipment estimates triangulated against top-down household penetration models.
Segment-level value outputs across product type, end user, technology tier, and distribution channel dimensions were derived through structured projection frameworks. CAGRs were computed from replacement cycle compression rates under regulatory efficiency mandates and smart appliance adoption curves in affluent urban districts. Forecast inputs incorporated copper price volatility scenarios and cantonal construction permit trends.
Revisions become necessary when Swiss-EU regulatory harmonization timelines shift, rare earth supply disruptions materialize, or grid infrastructure investment in rural Ticino and Valais accelerates smart appliance penetration beyond baseline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
India Home Appliances Market
Home Appliances
Oman Major Home Appliances Market
Home Appliances
Europe Home Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Household Refrigerator Market
Home Appliances
Household Induction Cooktops Market