
 Europe Portable Washing Machine Market | 2026-2036
Europe Portable Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Portable Washing Machine Market Insights
Energy-efficiency tier upgrades is unwinding across the Europe Portable Washing Machine Market as manufacturers chase A+++ ratings and heat-pump integration. Bosch leverages its German engineering heritage to sustain premium positioning in compact laundry systems. Electrolux anchors its Nordic design philosophy to differentiate through water-recirculation technology and Scandinavian aesthetic appeal.
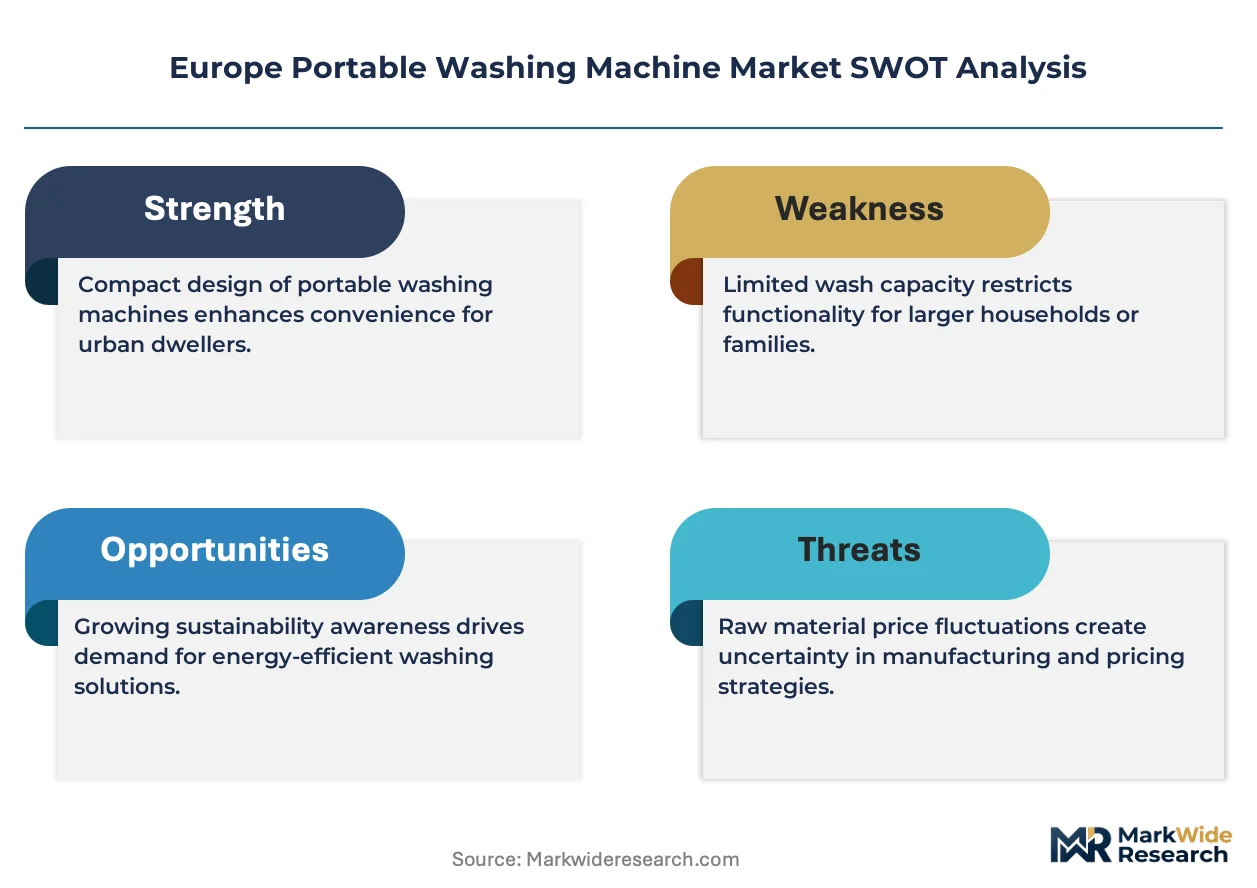
A portable washing machine denotes a compact, self-contained laundry appliance typically weighing under 35 kilograms, designed for installation without permanent plumbing connections, operating on standard 220-240V European electrical supply with drum capacities ranging from 3 to 8 kilograms. Its primary purpose serves households, recreational vehicles, and marine vessels where space constraints or mobility requirements preclude conventional full-size appliance deployment. Fully automatic configurations capture the dominant margin pool as consumers prioritize one-touch operation over manual intervention, while the RV and yacht end-user segment registers the fastest structural expansion driven by Europe's leisure travel recovery and marina infrastructure investment. Twin tub variants retain residual share in Eastern European price-sensitive markets where dual-chamber washing and spin-dry separation remains valued.
The EU Ecodesign Directive and Energy Labeling Framework mandate minimum efficiency thresholds and standardized consumption disclosure, compelling manufacturers to redesign motor systems and thermal management. CE marking and the EU F-Gas Regulation govern refrigerant-based heat-pump variants entering the European Economic Area, adding compliance layers to product development cycles. Stakeholders must monitor impending Ecodesign tier escalations and assess whether in-house testing capacity or third-party certification partnerships offer faster route-to-market advantage.
Market Dynamics
Heat-pump technology is compressing energy consumption benchmarks across the Europe Portable Washing Machine Market as manufacturers race to meet escalating EU Ecodesign tiers. This thermal efficiency pivot is restructuring R&D allocation and supplier relationships simultaneously.
Growth Catalysts
- EU Ecodesign Directive escalation:The 2024 tier upgrade mandates 20% efficiency gains over prior baselines, forcing motor redesigns that favor compact heat-pump architectures over traditional resistive heating.
- Urban rental density:Berlin and Paris housing stock under 50 square meters is generating installed-base expansion where permanent plumbing is unavailable or prohibited under lease terms.
- Marina infrastructure investment:Mediterranean port modernization in Spain, Italy, and Greece is creating dedicated shore-power hookups that enable 220-240V appliance deployment aboard leisure vessels.
Market Restraints
- Copper and rare-earth magnet cost volatility:Permanent-magnet motor supply chains concentrate in Chinese processing facilities, exposing European assemblers to input price swings that compress margin on sub-500 euro units.
- CE marking timeline friction:The EU F-Gas Regulation adds 8-14 weeks to heat-pump variant certification, delaying seasonal product launches and freezing working capital in pre-approved inventory.
- Full-size appliance substitution:Shared laundry facilities in Dutch and Belgian co-housing developments offer cost-per-wash economics that undercut individual portable unit ownership.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania rental markets show sub-15% portable washing machine penetration versus 40%+ in Germany, presenting volume expansion potential as distributor networks mature.
- Refrigerant innovation convergence:R290 propane and R600a isobutane heat-pump systems are crossing over from commercial refrigeration, enabling manufacturers to leverage existing compressor supplier relationships.
- Direct-to-consumer channel emergence:Specialized marine and RV e-commerce platforms are bypassing traditional appliance retail, capturing margin and capturing behavioral data from leisure-vehicle owners.
Industry Challenges
- Thermodynamics engineering talent scarcity:Heat-pump system design requires cross-disciplinary expertise spanning refrigeration cycles and textile mechanics, with European technical universities producing insufficient graduates.
- Water-recirculation certification complexity:Electrolux-style closed-loop systems face divergent national plumbing codes across Germany, France, and Italy, fragmenting product architecture and testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Portable Washing Machine Market |
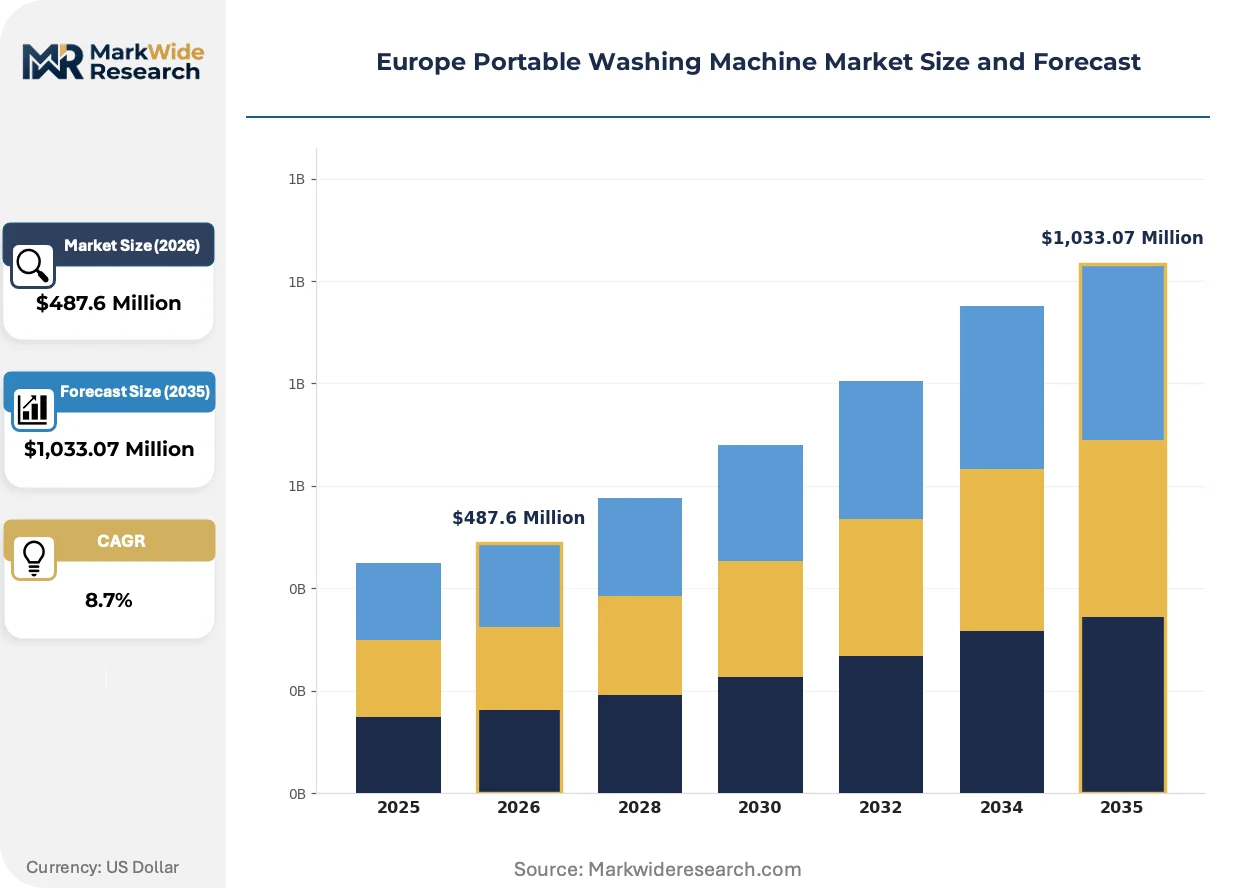
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Twin Tub, Mini End User: Residential, Commercial, RVs, Yachts Capacity: 3-4 Kg, 5-6 Kg, 7-8 Kg, Above 8 Kg Power Rating: 500-800 W, 801-1000 W, 1001-1200 W, Above 1200 W |
| Companies Covered | Whirlpool, Bosch, Electrolux, LG Electronics, Samsung Electronics, Haier Group, Miele, Panasonic Corporation, Midea Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Portable Washing Machine Market Trends and Innovations
Connected functionality and thermal efficiency are converging to redefine portable washing machine value propositions. Manufacturers are embedding sensors and heat-pump architectures that transform compact units from basic appliances into data-generating, grid-responsive assets.
Inverter-driven brushless DC motors are supplanting universal AC motor architectures across mid-tier and premium portable washing machines. German and French urban renters are specifying these variants at accelerating rates despite 30-40% price premiums. The technology is compressing energy consumption curves and enabling variable-speed drum control that reduces fabric wear.
The EU F-Gas Regulation is tightening refrigerant containment standards for heat-pump washing machines entering the European Economic Area. Manufacturers must now certify leak-detection systems and service accessibility that add component cost but prevent atmospheric release. Scandinavian markets are responding fastest, with Norwegian and Swedish distributors prioritizing R290-based units ahead of southern European adoption curves.
Subscription-based appliance access is displacing outright ownership among Amsterdam and Copenhagen housing cooperatives. Property managers are bundling portable washing machines into service contracts that include maintenance and efficiency upgrades. This model concentrates procurement authority with facility operators and compressing brand loyalty at the individual household level.
Europe Portable Washing Machine Market Segmentation
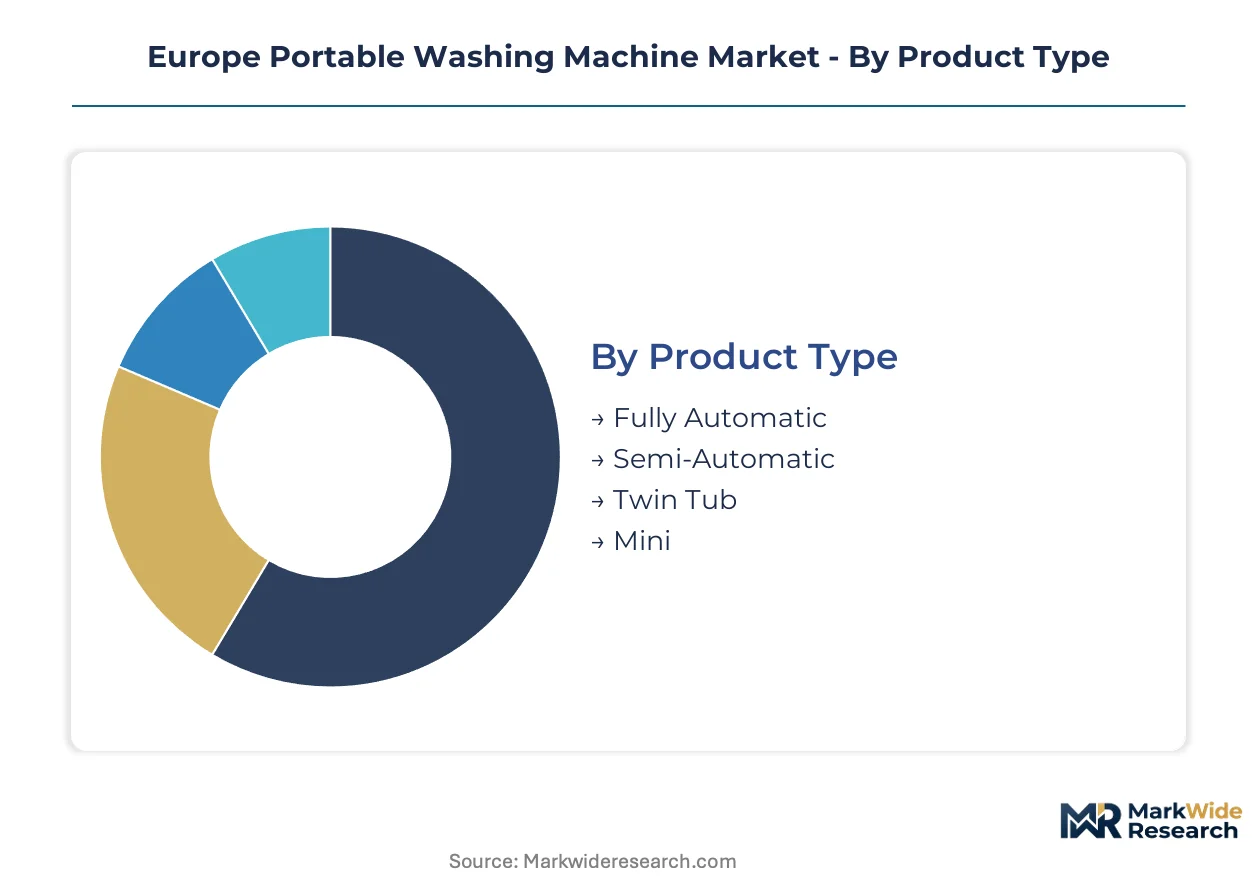
Portable washing machine manufacturers route distinct configurations through divergent channel strategies. Product type and capacity tiers determine whether units flow through marine distributors, appliance retailers, or direct-to-consumer platforms targeting urban renters.
Product Type:
Fully automatic and semi-automatic variants dominate traditional appliance retail channels, while twin tub and mini formats concentrate in specialized marine and RV distributors serving Mediterranean marinas and Central European caravan parks.
- Fully Automatic:Single-drum units integrate wash, rinse, and spin cycles with programmable controls and load-sensing water adjustment. German and French urban renters prioritize these for studio apartments where space constraints eliminate full-size alternatives. Electrolux and Bosch anchor premium positioning through inverter motor technology and heat-pump thermal management.
- Twin Tub:Dual-chamber designs separate washing and spin-drying functions, enabling water reuse and manual cycle control. Eastern European price-sensitive markets in Poland and Romania sustain demand where dual-chamber washing and spin-dry separation remains valued over automation convenience.
- Semi-Automatic:Intermediate automation requiring manual water filling and drainage intervention. Budget retail chains in Portugal and Greece stock these for seasonal coastal rentals and secondary residences.
- Mini:Sub-3 kg capacity units designed for single garments or small loads. Direct-to-consumer marine platforms and Amsterdam housing cooperatives procure these for subscription-based appliance access models.
By volume, fully automatic leads. By growth pace, mini formats are expanding most quickly through leisure-vehicle channels.
End User:
Residential demand concentrates in metropolitan rental markets, while commercial procurement concentrates with facility operators bundling units into service contracts.
- Residential:Individual households in space-constrained urban housing stock across Berlin, Paris, and Barcelona. Lease restrictions on permanent plumbing installations drive specification of 220-240V plug-and-play units with gravity drainage options.
- RVs:Recreational vehicle owners require vibration-dampened 12V/220V convertible units. Italian and German caravan manufacturers specify these for factory installation, while aftermarket sales concentrate in Alpine region camping retailers.
- Commercial:Boutique hotels, hostels, and co-living operators in Copenhagen and Amsterdam. Procurement authority concentrates with facility managers negotiating maintenance-inclusive service contracts rather than individual ownership.
- Yachts:Marine-grade stainless steel enclosures with securing gimbals for seakeeping. Mediterranean marina infrastructure investment in Spain, Italy, and Greece enables shore-power hookups that support standard European voltage deployment.
Residential captures the dominant revenue share. Yacht applications gain share fastest through marina modernization programs.
Capacity:
Capacity selection correlates with housing unit size and installation permanence, with smaller drums dominating transient living arrangements.
- 3-4 Kg:Compact drums for single-person households and marine applications. French and Italian yacht brokers specify these for cabin installations where space constraints preclude larger alternatives.
- 5-6 Kg:Standard urban rental specification balancing load flexibility against footprint constraints. German distributor networks move volume through electronics retail chains serving Berlin and Munich apartment markets.
- 7-8 Kg:Family-sized portable units for multi-person households in semi-permanent installations. Dutch co-housing developments specify these for shared laundry facilities where individual unit ownership is discouraged.
- Above 8 Kg:Commercial-grade drums for hospitality and institutional procurement. Scandinavian facility operators prioritize these for throughput efficiency in bundled service contracts.
Five-to-six kilogram units dominate unit economics. Three-to-four kilogram drums climb fastest through marine and RV penetration.
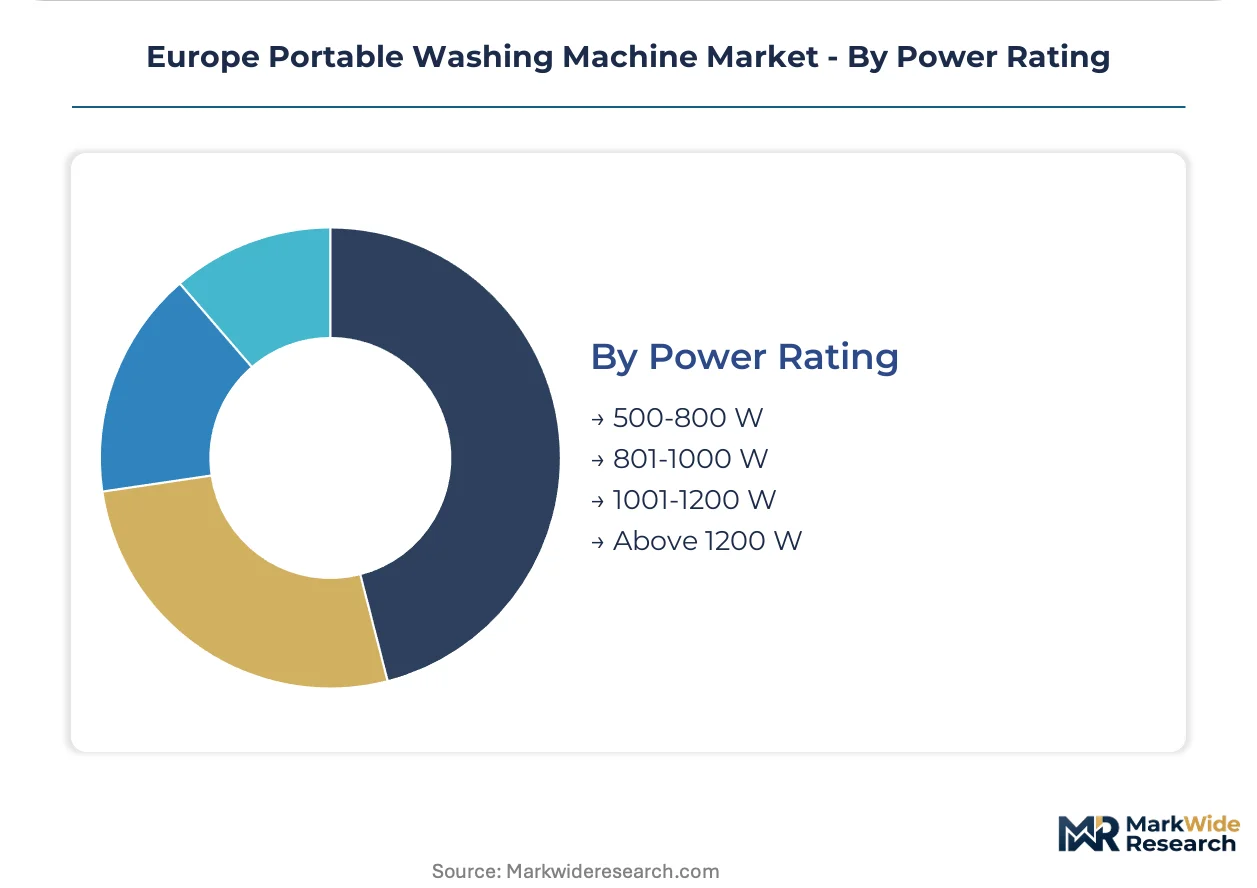
Power Rating:
Power tier selection determines heat-pump viability and EU Ecodesign tier compliance, with higher-wattage variants requiring advanced thermal management.
- 500-800 W:Entry-level universal motor architectures without heat-pump integration. Polish and Romanian retail channels stock these for price-sensitive consumers prioritizing acquisition cost over operating efficiency.
- 801-1000 W:Mid-tier inverter motor specifications achieving A++ energy ratings. French and German urban renters specify these for balance of performance and EU Ecodesign compliance.
- 1001-1200 W:Premium heat-pump enabled units approaching A+++ efficiency thresholds. Electrolux and Bosch compete through R290 refrigerant systems and water-recirculation technology.
- Above 1200 W:Commercial-grade thermal output for high-capacity drums and rapid cycle completion. Institutional procurement in Nordic markets specifies these for throughput requirements in shared facilities.
Eight-hundred-one-to-one-thousand-watt configurations anchor volume. One-thousand-one-to-one-thousand-two-hundred-watt heat-pump variants represent the steepest expansion trajectory as Ecodesign tiers escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters in Germany and Italy, with component sourcing stretching into Poland and Romania. Distribution networks radiate from these hubs to serve distinct national regulatory environments and housing market conditions across the continent.
Germany
Berlin and Munich rental markets under 50 square meters drive specification of 5-6 kg fully automatic units. The EU Ecodesign Directive mandates efficiency upgrades that favor heat-pump architectures in domestic manufacturing. Bosch anchors premium positioning through inverter motor technology developed at its Stuttgart engineering centers.
France
Paris studio apartments generate installed-base expansion where lease restrictions prohibit permanent plumbing installations. ANSM and DGCCRF oversee product safety compliance alongside CE marking requirements. Marseille and Lyon distributor networks move volume through electronics retail chains serving urban renters prioritizing plug-and-play deployment.
Italy
Mediterranean marina infrastructure investment in Genoa and Naples enables shore-power hookups for marine-grade portable units. The F-Gas Regulation adds certification timelines for heat-pump variants entering the Italian market. Lombardy-based fabricators supply stainless steel enclosures for yacht applications.
Spain
Barcelona and Madrid housing cooperatives are piloting subscription-based appliance access models. The EU Energy Labeling Framework mandates standardized consumption disclosure at point of sale. Valencia port modernization creates dedicated electrical infrastructure for leisure vessel deployments.
Poland
Warsaw and Krakow rental markets show sub-15% portable washing machine penetration versus Western European benchmarks. Polish retail channels stock entry-level 500-800 W universal motor architectures for price-sensitive consumers. Distributor network maturation is bridging the penetration gap with German market development curves.
Europe Portable Washing Machine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe Portable Washing Machine Market. The vendor base organizes into three tiers: premium European engineering houses, mid-tier Asian electronics conglomerates, and specialized compact appliance fabricators. German and Swedish manufacturers anchor the premium tier through heat-pump integration and water-recirculation systems. Korean and Chinese electronics groups compete on scale and connected functionality. Strategic moves concentrate on refrigerant innovation partnerships and direct-to-consumer channel development for marine and RV segments.
Among European-based engineering houses, Bosch and Electrolux occupy positions defined by thermal efficiency leadership and Nordic design differentiation respectively. Miele represents the ultra-premium archetype with extended durability positioning. LG Electronics and Samsung Electronics exemplify the scale-driven Asian electronics model, leveraging component ecosystem advantages across home appliance portfolios. Haier Group and Midea Group anchor the cost-optimized tier, supplying entry-level configurations through Polish and Romanian retail channels.
| Leading Market Players |
|---|
| Whirlpool |
| Bosch |
| Electrolux |
| LG Electronics |
| Samsung Electronics |
| Haier Group |
| Miele |
| Panasonic Corporation |
| Midea Group |
| Others |
Pricing and Supply Chain Analysis
CE marking and the EU F-Gas Regulation gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb certification costs that stratify offerings across premium heat-pump and entry-level resistive-heating tiers while compressing margins on sub-500 euro units.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure across the Europe Portable Washing Machine Market. Three-tier pricing structure across premium, standard, and economy levels separates A+++ heat-pump units with R290 refrigerant from A++ inverter-motor configurations and entry-level universal-motor alternatives. Price differentiation hinges on energy certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because copper and rare-earth magnet supply chains concentrate in Chinese processing facilities. Polish and Romanian retail channels show the highest buyer price sensitivity, while Scandinavian facility operators purchasing through subscription-based appliance access models demonstrate the least.
Supply Chain Analysis
Inventory cycles stretch 8-14 weeks for heat-pump variants awaiting F-Gas Regulation certification, freezing working capital in pre-approved stock. Assembly capacity clusters in Germany and Italy, with component sourcing stretching into Poland and Romania. Permanent-magnet motor architectures draw from Chinese rare-earth processing, while R290 propane and R600a isobutane heat-pump compressors rest on commercial refrigeration supplier relationships. Single-source vulnerability concentrates in permanent-magnet supply chains. Distribution runs through marine and RV e-commerce platforms bypassing traditional appliance retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Portable Washing Machine Market sustains defensive moats through regulatory entrenchment, where CE marking and escalating Ecodesign tiers create certification barriers that favor incumbents with established testing infrastructure and third-party laboratory partnerships.
For Market Incumbents: Consolidate heat-pump engineering talent through targeted acquisition of thermodynamics specialists from European technical universities, addressing capability scarcity that constrains R&D velocity. Deepen backward integration into inverter motor production to reduce exposure to Chinese rare-earth magnet price volatility. Prioritize certification investment in water-recirculation systems to defend against Electrolux-style Nordic design differentiation.
For New Entrants and Emerging Players: Lead with direct-to-consumer channel development targeting Mediterranean marina infrastructure and Central European caravan parks, where specialized marine and RV e-commerce platforms capture margin and behavioral data. Target Poland and Romania rental markets showing sub-15% portable washing machine penetration versus Western European benchmarks. Emphasize twin tub configurations for price-sensitive Eastern European consumers valuing manual cycle control over automation convenience.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heat-pump-enabled portable washing machine manufacturing, driven by refrigerant containment system investments and in-house testing capacity requirements. Long-term viability favors vertically integrated engineering houses with captive compressor supplier relationships and established CE marking pathways. Watch for Ecodesign tier escalation announcements as the inflection indicator signaling accelerated R&D allocation requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Innovation Partnership | R290 propane crossover from commercial refrigeration leverages existing compressor supplier relationships at Electrolux and Bosch. |
| Direct-to-Consumer Channel Launch | Specialized marine and RV e-commerce platforms bypass traditional appliance retail, capturing margin from leisure-vehicle owners. |
| Heat-Pump Engineering Talent Acquisition | Thermodynamics expertise scarcity at European technical universities constrains R&D velocity for compact thermal management systems. |
| Water-Recirculation Certification Investment | Electrolux-style closed-loop systems face divergent national plumbing codes across Germany, France, and Italy, fragmenting testing budgets. |
| Eastern European Distributor Network Expansion | Poland and Romania rental markets show sub-15% penetration versus 40%+ in Germany, presenting volume expansion potential. |
Research Methodology
Desk research of EU regulatory filings, customs and trade data, and energy labeling databases preceded structured interviews with appliance engineering directors, marine distributor procurement managers, and co-housing facility operators across Berlin, Paris, and Amsterdam. Primary fieldwork with heat-pump system designers and textile mechanics professors at European technical universities validated thermal efficiency claims and R&D allocation patterns. Secondary sources included CE marking documentation, F-Gas Regulation compliance records, and marina infrastructure investment disclosures. Bottom-up unit shipment modeling triangulated against top-down market value estimates derived from distributor pricing surveys.
Variance decomposition across product type, capacity tier, power rating, and end-user segmentation anchored the analytical framework throughout the forecast period. CAGRs were synthesized from installation base expansion curves in urban rental markets and leisure-vehicle registration data. Heat-pump adoption rates and Ecodesign tier compliance timelines served as primary forecast inputs, with marina infrastructure investment pipelines and co-housing development permits providing secondary validation.
Forecasts assume regulatory continuity in EU Ecodesign Directive tier escalations and F-Gas refrigerant containment standards; material policy shifts would require re-modeling of manufacturer R&D allocation and certification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
India Home Appliances Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Australia Home Appliances Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Chile Home Appliances Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
North America Luxury Appliance Market