
 North America Electric Fireplace Market | 2026-2036
North America Electric Fireplace Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Fireplace Market Insights
UL 127 certification for fixed and portable electric heaters is bifurcating the competitive landscape between qualified OEMs and peripheral suppliers. Glen Dimplex Group leverages its captive testing laboratories to fast-track certification renewals across its insert and wall-mounted portfolios. Twin Star Home anchors its position through exclusive retail partnerships with big-box distributors in the United States. Napoleon competes on heating capacity breadth, spanning low-output decorative units through extra-high models rated for commercial zoning.
North America electric fireplaces are electrically powered heating appliances designed to simulate flame effects through LED projection or holographic display while delivering resistive or infrared thermal output, typically rated between 4,000 and 9,000 BTU depending on heating capacity tier. Their primary purpose is to provide zone heating and ambient visual focal points in residential, hospitality, and retail environments without requiring venting, chimneys, or combustion air supply. Wall-mounted and insert product types command the majority of current volume, with insert units capturing disproportionate margin pools from retrofit replacement cycles in existing housing stock. Smart and app-based control types are expanding fastest, though manual and remote configurations still dominate unit economics in builder-grade channels.
UL certification requirements, the U.S. EPA's voluntary indoor air quality partnerships, and CSA Group standards in Canada collectively shape product safety thresholds and cross-border market access for electric fireplace manufacturers. The U.S. Department of Energy periodically revises test procedures for electric resistance heating equipment, pressuring R&D budgets toward efficiency optimization. Stakeholders must monitor evolving building electrification mandates at the state and provincial level, as jurisdictions like California and British Columbia advance code amendments that restrict new gas hookups and elevate electric alternatives in commercial and residential construction.
Market Dynamics
Municipal electrification mandates across California, British Columbia, and New York are forcing residential builders to substitute electric inserts for gas hearths in new multifamily construction, compressing specification windows and privileging UL 127-certified suppliers.
Growth Catalysts
- Building Electrification Codes:California's Title 24 and British Columbia's zero-carbon building standards mandate electric heating in new residential units, eliminating gas hookup alternatives.
- Hospitality Retrofit Cycles:Hotels across Texas, Florida, and Arizona are replacing gas hearths with zero-clearance electric units to eliminate venting infrastructure and reduce maintenance overhead.
- Smart Control Integration:Wi-Fi and app-based fireplace controls are capturing specification share in high-end residential and commercial installations, commanding margin premiums over manual configurations.
Market Restraints
- Copper and Semiconductor Input Volatility:Resistive heating elements and LED flame-projection systems depend on copper windings and driver chips, exposing manufacturers to commodity price swings and allocation constraints.
- Testing Laboratory Bottlenecks:UL 127 certification capacity concentrates in a limited number of North American testing facilities, creating queue delays that gate market entry for peripheral suppliers.
- Heat Pump Substitution:Cold-climate heat pumps with aesthetic casing options are displacing electric fireplaces in whole-home heating specifications, particularly in northern US states and Canadian provinces.
Strategic Opportunities
- Mexico Manufacturing Expansion:OEMs establishing final assembly in Baja California and Chihuahua can access USMCA tariff preferences while serving California and southwestern US demand clusters.
- Outdoor Electric Hearth Segments:Weather-rated electric units for patio and hospitality outdoor spaces remain underpenetrated, with IP-rated enclosures and infrared heating arrays opening new application verticals.
- Utility Rebate Alignment:Alignment with US Department of Energy appliance efficiency programs and provincial utility incentives in Ontario and Quebec can reduce end-user acquisition costs and accelerate replacement cycles.
Industry Challenges
- Electrical Contractor Certification Gaps:Installation of 240V hardwired units requires licensed electricians with low-voltage control integration skills, creating labor bottlenecks in high-growth metropolitan markets.
- Cross-Border Standards Harmonization:Divergent testing protocols between UL 127 in the United States and CSA C22.2 No. 46 in Canada force dual certification investments that compress margins on border-state sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Fireplace Market |
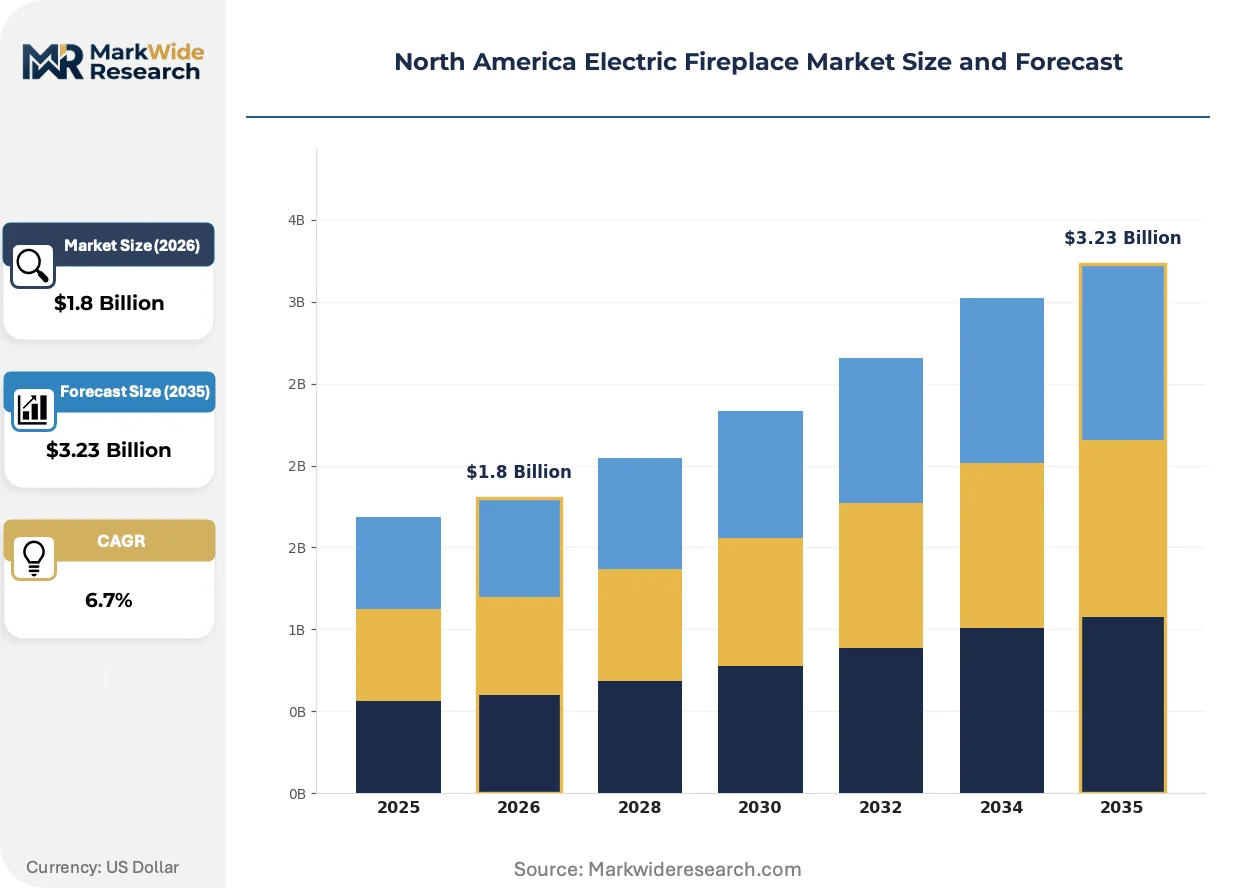
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Insert, Freestanding, Outdoor End User: Residential, Commercial, Hospitality, Retail Heating Capacity: Low, Medium, High, Extra High Control Type: Remote, Manual, Smart, App-Based |
| Companies Covered | Glen Dimplex Group, Twin Star Home, Napoleon, Hearth & Home Technologies, Inc., Empire Comfort Systems, Inc., Touchstone Home Products, Inc., Amantii Electric Fireplaces, Modern Flames, GHP Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Fireplace Market Trends and Innovations
Holographic flame projection and infrared heating arrays are restructuring product tiering in electric fireplaces, while regulatory pressure on combustion heating accelerates specification shifts across residential and hospitality channels.
LED-based flame simulation is bifurcating the product hierarchy between basic projection systems and advanced holographic displays. Hospitality designers in Miami and Los Angeles are specifying premium holographic units at triple the rate of conventional inserts. This technology is bifurcating margin pools, compressing returns on legacy projection hardware while enabling premium pricing for immersive visual systems.
California's building electrification mandates and British Columbia's zero-carbon building code are prohibiting new gas hookups in residential construction. These regulations are forcing developers to standardize electric fireplace specifications in multifamily projects. The impact concentrates in entry-level and mid-market housing segments, where builders are negotiating volume supply agreements with certified OEMs to secure specification lock-in.
Specification authority is migrating from mechanical contractors to interior designers and hospitality procurement teams. Boutique hotel chains and luxury residential developers now source electric hearths through design-specification channels rather than traditional HVAC distributors. This shift is most visible in Texas and Florida, where design-build firms control procurement for large-scale hospitality retrofits and amenity-focused residential towers.
North America Electric Fireplace Market Segmentation
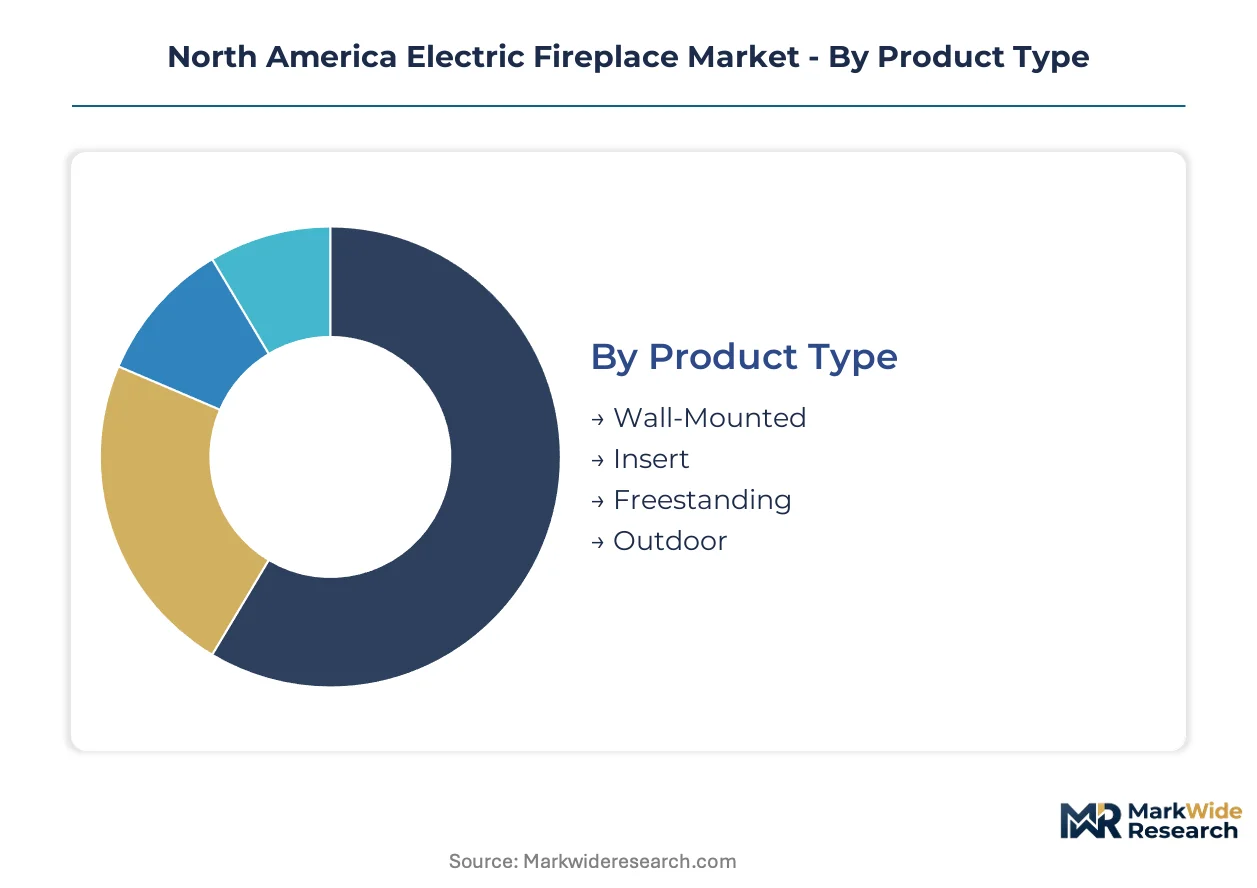
Electric fireplace manufacturers configure product portfolios across four distinct segmentation axes, each governing different margin structures and specification channels. Product type and heating capacity determine manufacturing complexity and certification requirements, while control type and end-user orientation shape distribution pathways and pricing power.
Product Type:
Margin pools concentrate in insert units due to retrofit replacement cycles in existing housing stock, while wall-mounted products anchor volume through new construction specifications.
- Wall-Mounted:These units attach directly to vertical surfaces without floor footprint requirements, typically featuring slim-profile enclosures between 4 and 6 inches deep. Demand clusters in California multifamily developments where Title 24 electrification mandates eliminate gas alternatives, with builders negotiating volume supply agreements to secure specification lock-in. Wall-mounted products command builder-grade volume but face margin compression from commodity LED flame systems.
- Insert:Engineered to retrofit existing masonry or factory-built fireplace openings, these units require precise dimensional tolerances and zero-clearance safety ratings. The segment captures disproportionate margin pools from replacement cycles in Texas and Florida existing housing stock, where homeowners upgrade aging gas logs without structural modifications. UL 127 certification requirements gate which manufacturers can access major retail channels.
- Freestanding:Portable units with integrated enclosures serve rental properties and seasonal heating needs across the southern United States.
- Outdoor:Weather-rated enclosures with IP-rated protection target patio hospitality installations in Miami and Los Angeles, remaining underpenetrated relative to indoor categories.
Insert units hold installed capacity in legacy housing retrofits. Outdoor products are rotating up the share rankings through hospitality amenity specifications.
End User:
Volume distribution skews toward residential channels, though hospitality procurement teams are capturing specification authority from traditional HVAC distributors.
- Residential:Single-family and multifamily homeowners specify electric hearths for zone heating and ambient focal points, with California and British Columbia building codes mandating electric alternatives in new construction. The segment splits between builder-grade specifications in entry-level housing and premium design-specified units in luxury developments.
- Hospitality:Boutique hotel chains and amenity-focused properties across Texas, Florida, and Arizona are retrofitting gas hearths with zero-clearance electric units to eliminate venting infrastructure and reduce maintenance overhead. Procurement authority has migrated from mechanical contractors to interior designers and hospitality procurement teams.
- Commercial:Office lobbies and retail environments specify low-output decorative units where combustion restrictions apply.
- Retail:Showroom and customer-facing spaces deploy electric hearths for atmospheric merchandising in furniture and home goods sectors.
Residential channels dominate unit economics. Hospitality is climbing the fastest through design-specification migration.
Heating Capacity:
Product tiering aligns with thermal output ratings, with extra-high capacity units serving commercial zoning requirements and low-output models penetrating decorative-only applications.
- Extra High:Rated above 7,500 BTU, these units satisfy commercial heating loads and large residential open plans. Napoleon anchors position through breadth across this tier, serving hotel lobbies and residential great rooms where supplemental heating capacity determines specification.
- High:Between 5,500 and 7,500 BTU output, this segment addresses primary zone heating in cold-climate residential applications across northern US states and Canadian provinces.
- Medium:4,000 to 5,500 BTU ratings serve standard residential rooms and hospitality guest spaces.
- Low:Below 4,000 BTU decorative units prioritize flame visualization over thermal output, commanding premium pricing for holographic projection features.
Extra-high capacity holds specification authority in commercial zoning. Low-output decorative units are gaining share fastest through holographic flame technology premiums.
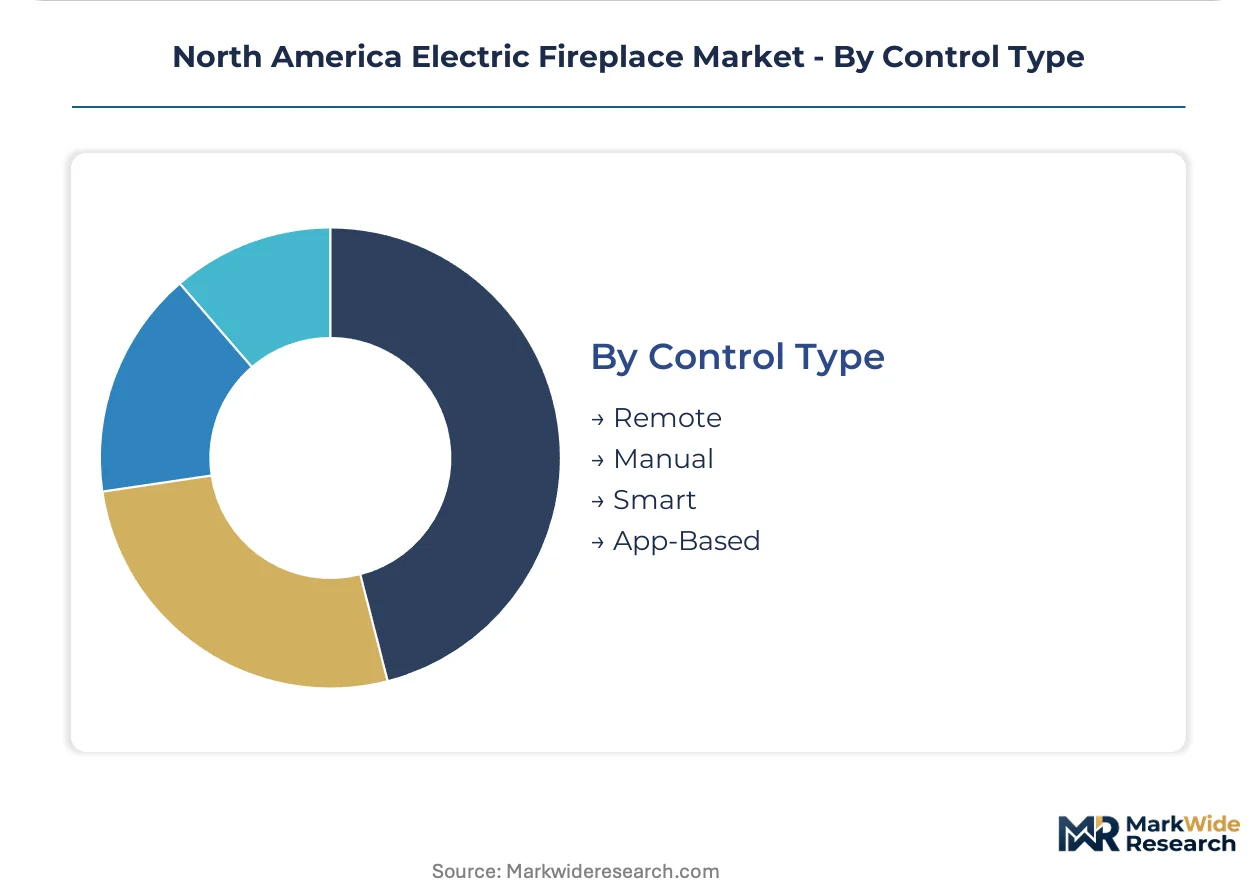
Control Type:
Smart and app-based configurations are expanding specification share in high-end residential and commercial installations, though manual and remote configurations still dominate builder-grade channels.
- App-Based:Wi-Fi enabled controls with smartphone integration and programmable scheduling capture margin premiums in luxury residential and hospitality specifications. Miami and Los Angeles designers specify these systems at elevated rates for seamless integration with whole-home automation platforms.
- Smart:Voice-control compatibility and occupancy-sensing features serve tech-forward residential segments and boutique hospitality properties.
- Remote:Handheld infrared or RF controllers remain standard in mid-market residential and builder-grade specifications.
- Manual:Hardwired switches and dial controls dominate entry-level pricing tiers and rental property installations where simplicity reduces maintenance exposure.
Remote configurations hold volume leadership in builder channels. App-based controls are rotating up the share rankings through smart home integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Building electrification mandates and utility rebate programs are redrawing demand geography across North America. California's Title 24 standards and British Columbia's zero-carbon building code are accelerating specification shifts, while Texas and Florida hospitality retrofits concentrate retrofit volume in Sun Belt corridors.
United States
California multifamily developers specify electric inserts under Title 24 electrification mandates, eliminating gas alternatives in new construction. The EPA's voluntary indoor air quality partnerships shape product safety thresholds for cross-state distribution. Dallas and Houston hotel operators retrofit gas hearths with zero-clearance electric units to eliminate venting infrastructure.
Canada
British Columbia's zero-carbon building standards mandate electric heating in residential units, compressing specification windows for certified suppliers. CSA C22.2 No. 46 certification requirements create dual-testing investments for manufacturers serving border markets. Toronto and Vancouver design-build firms control procurement for luxury residential towers and boutique hospitality properties.
Mexico
Baja California and Chihuahua assembly operations access USMCA tariff preferences while serving California and southwestern US demand clusters. The country's national standards body aligns product safety protocols with cross-border export requirements. Monterrey manufacturing clusters are expanding final assembly capacity for North American distribution.
North America Electric Fireplace Market Competitive Landscape
Listed leaders compete with private specialists across certification capacity and retail channel access. The vendor base splits between UL 127-certified incumbents with captive testing resources and peripheral suppliers facing laboratory queue delays. Three archetypes dominate: integrated OEMs with in-house certification laboratories, retail-anchored distributors with exclusive big-box partnerships, and capacity-focused manufacturers spanning decorative through commercial heating tiers. Competitive moves concentrate on Mexico manufacturing expansion and smart control portfolio diversification.
Among integrated OEMs with testing infrastructure, Glen Dimplex Group exemplifies the laboratory-captive archetype. Twin Star Home occupies a position within retail-anchored distribution. Napoleon represents the capacity-breadth specialist tier spanning low-output decorative through extra-high commercial models.
| Leading Market Players |
|---|
| Glen Dimplex Group |
| Twin Star Home |
| Napoleon |
| Hearth & Home Technologies, Inc. |
| Empire Comfort Systems, Inc. |
| Touchstone Home Products, Inc. |
| Amantii Electric Fireplaces |
| Modern Flames |
| GHP Group Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day UL 127 certification queues concentrate pricing power among laboratory-captive OEMs while compressing margins for peripheral suppliers awaiting testing slots. This lead-time bottleneck shapes tiered procurement negotiations across California multifamily developments and Texas hospitality retrofits, privileging certified incumbents with inventory buffers.
Pricing Analysis
Certification level (UL 127-grade) creates the primary spread between laboratory-captive OEMs and queue-dependent challengers. Three-tier pricing structure across premium holographic, standard LED, and economy manual configurations reflects control sophistication and heating capacity. Cost compression in economy tiers is intensifying because copper winding and semiconductor allocation constraints squeeze resistive element margins. Builder-grade channels exhibit highest price sensitivity, while hospitality procurement teams absorb premiums for app-based integration and zero-clearance safety ratings.
Supply Chain Analysis
China and Mexico anchor component manufacturing for LED driver chips and resistive heating elements, with final assembly rotating toward Baja California and Chihuahua to capture USMCA tariff preferences. Copper windings, semiconductor controllers, and holographic projection modules constitute critical input dependencies. Single-source vulnerability concentrates in UL 127 testing laboratory capacity, where queue delays gate market entry. Distribution runs through big-box retail partnerships and design-build specification channels, with hospitality procurement teams bypassing traditional HVAC distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
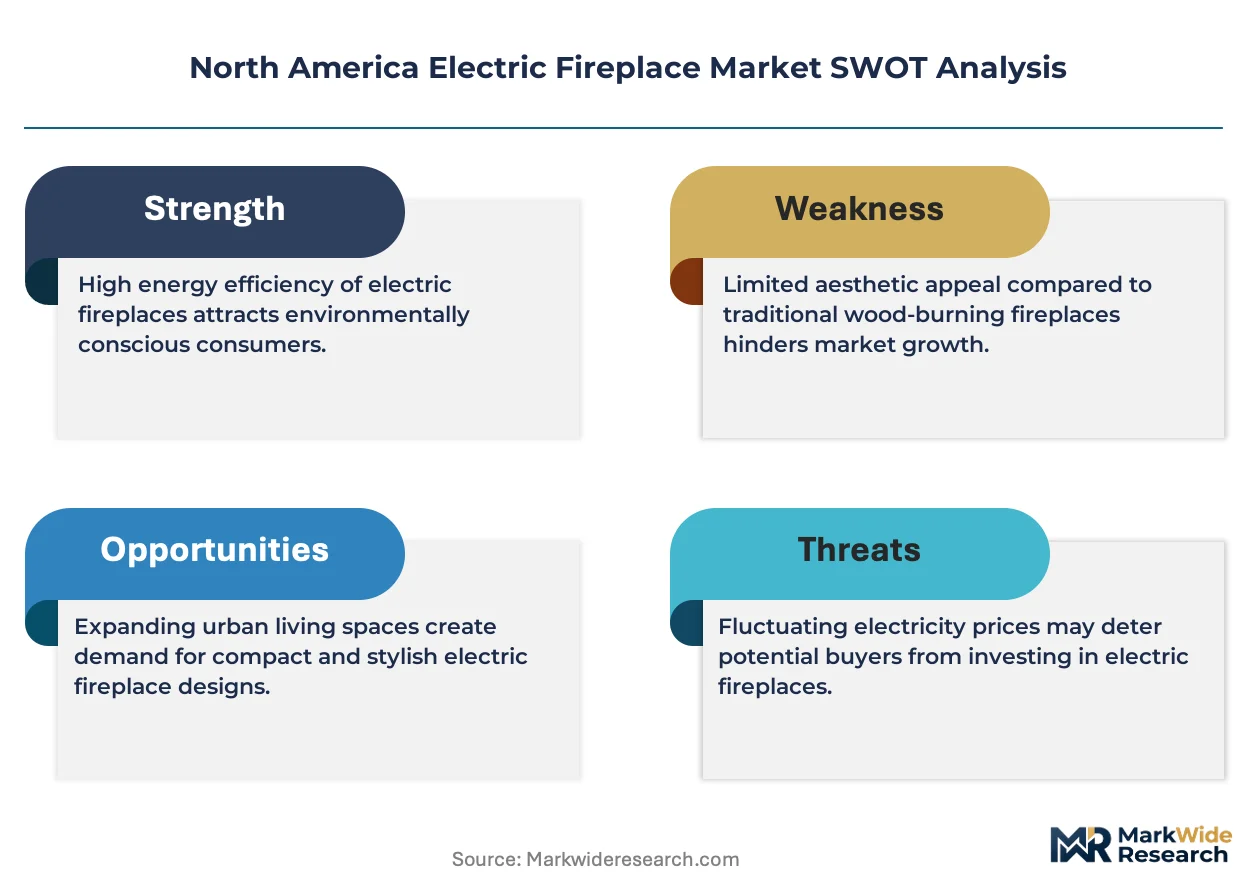
Cold-climate heat pumps with aesthetic casing options threaten substitution across northern US states and Canadian provinces, forcing incumbents to defend specification share through control integration and certification moats.
For Market Incumbents: Secure captive UL 127 testing capacity to compress certification renewal cycles and accelerate product pipeline velocity. Deepen backward integration into holographic projection module supply to differentiate premium tiers from commodity LED competitors. Defend against heat pump substitution by anchoring specification authority with interior design channels in Texas and Florida hospitality retrofits. For New Entrants and Emerging Players: UL 127 fast-track partnerships with third-party laboratories offer queue-jumping pathways into California multifamily builder-grade specifications. Target outdoor electric hearth segments in Miami and Los Angeles hospitality patio installations, where IP-rated enclosures remain underpenetrated. Pursue utility rebate alignment in Ontario and Quebec to reduce end-user acquisition costs and accelerate replacement cycles. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because electrification mandates in California and British Columbia structurally expand addressable demand while certification barriers constrain supply expansion. Acquisition targets should display laboratory-captive testing infrastructure or exclusive retail channel partnerships. The signal to watch is queue-length dynamics at North American UL testing facilities, which indicate competitive entry pressure and margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| UL 127 Certification Fast-Track | Laboratory-captive OEMs compress renewal cycles and outpace queue-dependent challengers in specification windows. |
| Mexico Manufacturing Expansion | Baja California assembly accesses USMCA preferences while serving California Title 24 demand clusters. |
| Smart Control Portfolio Diversification | Wi-Fi and app-based configurations capture margin premiums in Miami and Los Angeles design-specified installations. |
| Holographic Flame Technology Investment | Premium projection systems command triple specification rates over conventional LED in hospitality channels. |
| Utility Rebate Program Alignment | DOE efficiency partnerships and provincial incentives in Ontario reduce end-user acquisition costs. |
Research Methodology
A standing panel of electric fireplace product managers, UL certification engineers, hospitality procurement directors, and multifamily construction specifiers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA voluntary indoor air quality partnership filings, DOE electric resistance heating test procedure revisions, California Title 24 code amendment records, and CSA Group standard update notifications. Bottom-up unit shipment modeling and top-down construction permit analysis were triangulated against utility rebate program participation data.
Consistency checks validated volume and value outputs against cross-referenced regulatory filing trajectories and channel inventory observations across the projection horizon. Segmentation dimensions modeled include product type, heating capacity tier, control sophistication, and end-user orientation. CAGRs were derived from fitted growth curves anchored to electrification mandate implementation schedules and hospitality retrofit cycle timing. Industry-specific inputs incorporated copper commodity price bands and semiconductor allocation lead times.
Underlying assumptions cover sustained municipal electrification mandate enforcement, stable USMCA tariff treatment, and uninterrupted UL testing laboratory capacity expansion, with deviation risk concentrated in commodity price volatility and cross-border standards harmonization delays. Recalibration cycles align with material shifts in building code adoption timelines and testing queue dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
North America Major Home Appliances Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
South Korea Small Home Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
Household Appliance Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
European Built-In Refrigerator Market