
 United States Major Home Appliances Market | 2026-2036
United States Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United States Major Home Appliances Market Analytics
Market Context with Strategic Players
Capital-intensity divergence between in-house compressor manufacturing and outsourced assembly is redrawing competitive tiers among US appliance producers. Whirlpool Corporation leverages captive motor production in Ohio and Tennessee to sustain margin resilience against import volatility. Samsung Electronics anchors its position through vertical control over semiconductor-driven inverter modules. GE Appliances differentiates via proprietary water-filtration integration and dedicated US-based distribution infrastructure.
Technical Definition and Structural Segments
United States major home appliances comprise electrically powered domestic equipment with rated capacities exceeding compact or portable thresholds, typically incorporating sealed refrigeration systems, resistive or induction heating elements, and motorized drum mechanisms for thermal comfort and food preservation. These units serve residential and commercial installations requiring sustained operational reliability under cyclic load conditions. Refrigerators command the largest installed base renewal cycle, while smart appliances represent the fastest-expanding technology tier as Wi-Fi-enabled diagnostics and utility-integrated demand response reshape replacement timing. Energy efficient models capture premium positioning as utility rebate programs and state-level efficiency mandates widen the cost-performance gap against conventional units.
Regulatory Framework and Forward Outlook
EPA ENERGY STAR specifications and DOE minimum efficiency standards govern federal product certification thresholds, while California CEC Title 20 provisions impose supplemental state-level constraints that manufacturers must satisfy for coastal market access. NIST calibration protocols and UL safety listings further structure compliance burdens for imported and domestically assembled product lines. Stakeholders must monitor evolving federal appliance standards rulemakings and state-level building electrification mandates to align R&D allocation with forthcoming efficiency tier transitions.
Market Dynamics
Tightening EPA ENERGY STAR certification thresholds are compressing replacement cycles for suburban homeowners while forcing manufacturers to reallocate R&D toward inverter-driven compressor architectures and connected diagnostics platforms.
Growth Catalysts
- Building electrification mandates:State-level decarbonization frameworks in California, New York, and Washington are accelerating heat pump water heater and induction range adoption among residential retrofits.
- Utility demand response programs:Smart appliance enrollment for grid-balancing services is expanding rebate pools and shortening payback periods for Wi-Fi-enabled refrigeration and laundry equipment.
- Semiconductor-driven motor control:Variable-speed inverter modules are improving part-load efficiency and enabling predictive maintenance alerts that reduce warranty exposure.
Market Restraints
- Copper and rare-earth price volatility:Compressor winding materials and permanent-magnet motors face input cost swings that compress margin stability for mid-tier product lines.
- Asian component concentration:Power electronics and display module sourcing remains concentrated in South Korean and Chinese manufacturing clusters, exposing assemblers to shipping rate fluctuations.
- Refrigerant transition complexity:EPA phasedown schedules for hydrofluorocarbons under AIM Act provisions are forcing costly retooling of sealed-system production lines.
Strategic Opportunities
- Texas-Florida-California corridor density:Metropolitan clusters with high new construction permits and above-average electricity rates offer concentrated demand for premium smart refrigeration.
- IRA residential clean energy credits:Federal tax incentives for heat pump appliances are expanding addressable market for electrified cooking and water heating equipment.
- Voice-assistant and energy management convergence:Integration with utility time-of-use pricing APIs and smart home platforms is creating differentiated subscription revenue streams.
Industry Challenges
- Sealed-system technician scarcity:EPA Section 608 certification requirements and aging workforce demographics are constraining service network expansion for refrigerant-handling repairs.
- UL safety listing timelines:Extended validation cycles for novel heating element configurations and connected-device cybersecurity protocols are delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Major Home Appliances Market |
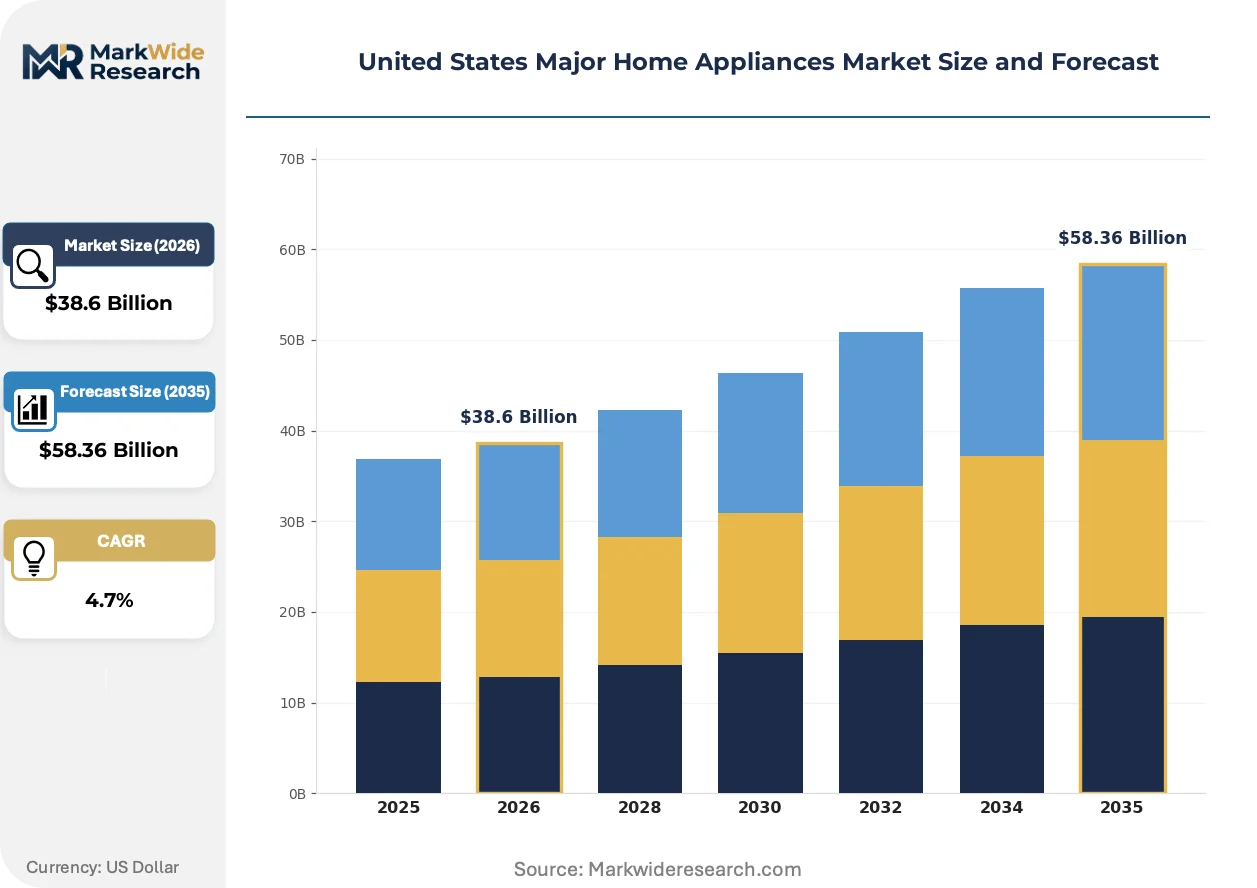
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
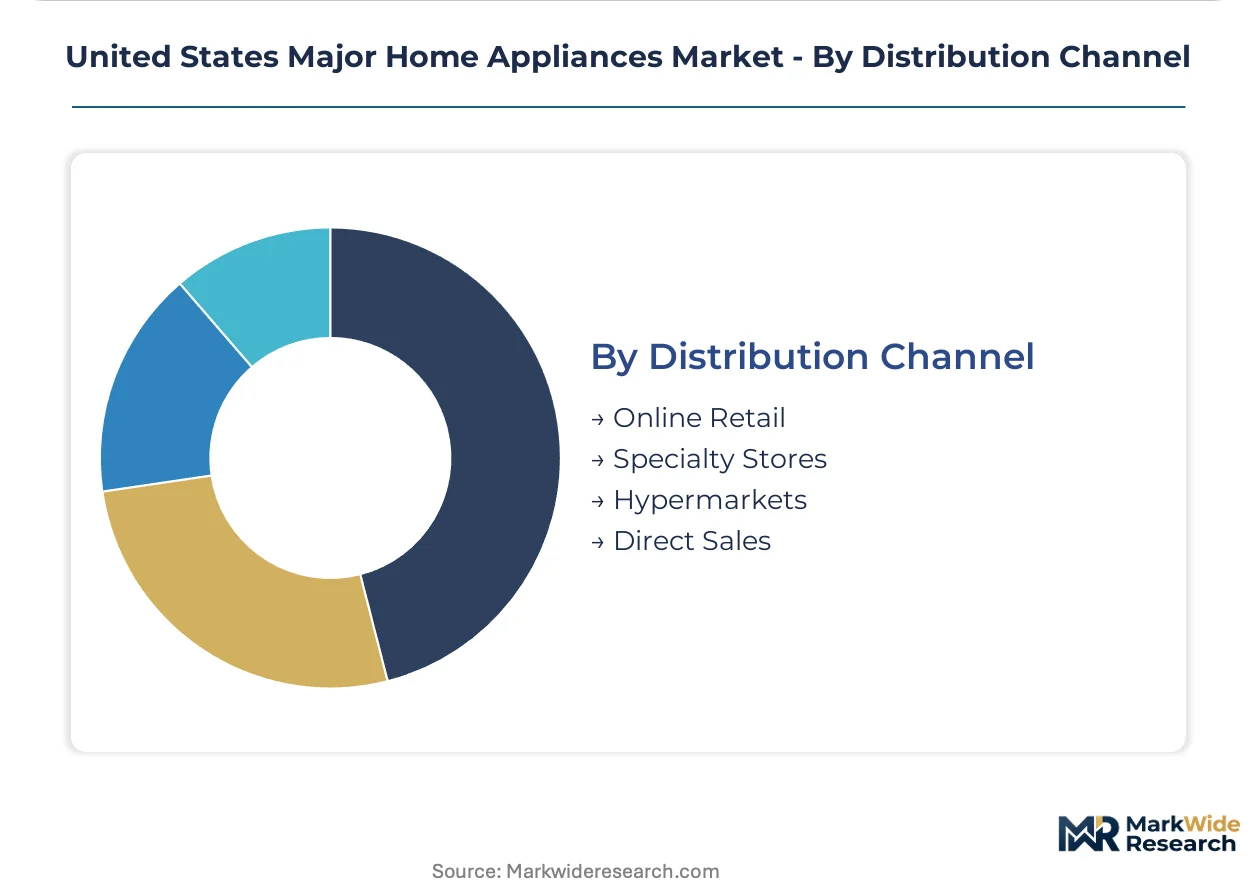
| Segmentation | Product Type: Refrigerators, Washers, Dryers, Ovens End User: Residential, Commercial, Rental, Hospitality Technology: Smart Appliances, Energy Efficient, Modular, Conventional Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Whirlpool Corporation, BSH Home Appliances Corporation, LG Electronics, Panasonic North America, Haier Smart Home Co. Ltd., GE Appliances, Electrolux Group, Miele, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Major Home Appliances Market Evolving Landscape
Connected diagnostics and utility-integrated demand response are rewriting replacement timing logic while fragmenting traditional channel structures between big-box retail, direct-to-consumer platforms, and utility-sponsored fulfillment models.
Inverter-driven compressor architectures are fragmenting the efficiency-performance landscape across the US market. Suburban homeowners in high-electricity-rate municipalities are adopting variable-speed refrigeration at accelerated replacement cycles. This technology is fragmenting competitive positioning by enabling granular efficiency tiering that separates premium smart models from conventional fixed-speed alternatives.
EPA ENERGY STAR Version 7.0 specifications are tightening refrigerator and freezer efficiency thresholds ahead of DOE federal minimum updates. Manufacturers must redesign insulation packages and control algorithms to maintain certification eligibility for coastal market access. California CEC Title 20 provisions are extending these constraints to online sales channels, forcing nationwide platform compliance.
Homeowner purchasing is migrating toward utility-integrated fulfillment models that bundle equipment, installation, and demand-response enrollment. Traditional appliance retail channels in Texas and Florida metropolitan corridors are ceding volume to electricity provider marketplaces offering instant rebate application. This behavioral pivot concentrates volume in regions where state regulators have authorized rate-basing for grid-edge assets.
United States Major Home Appliances Market Segmentation
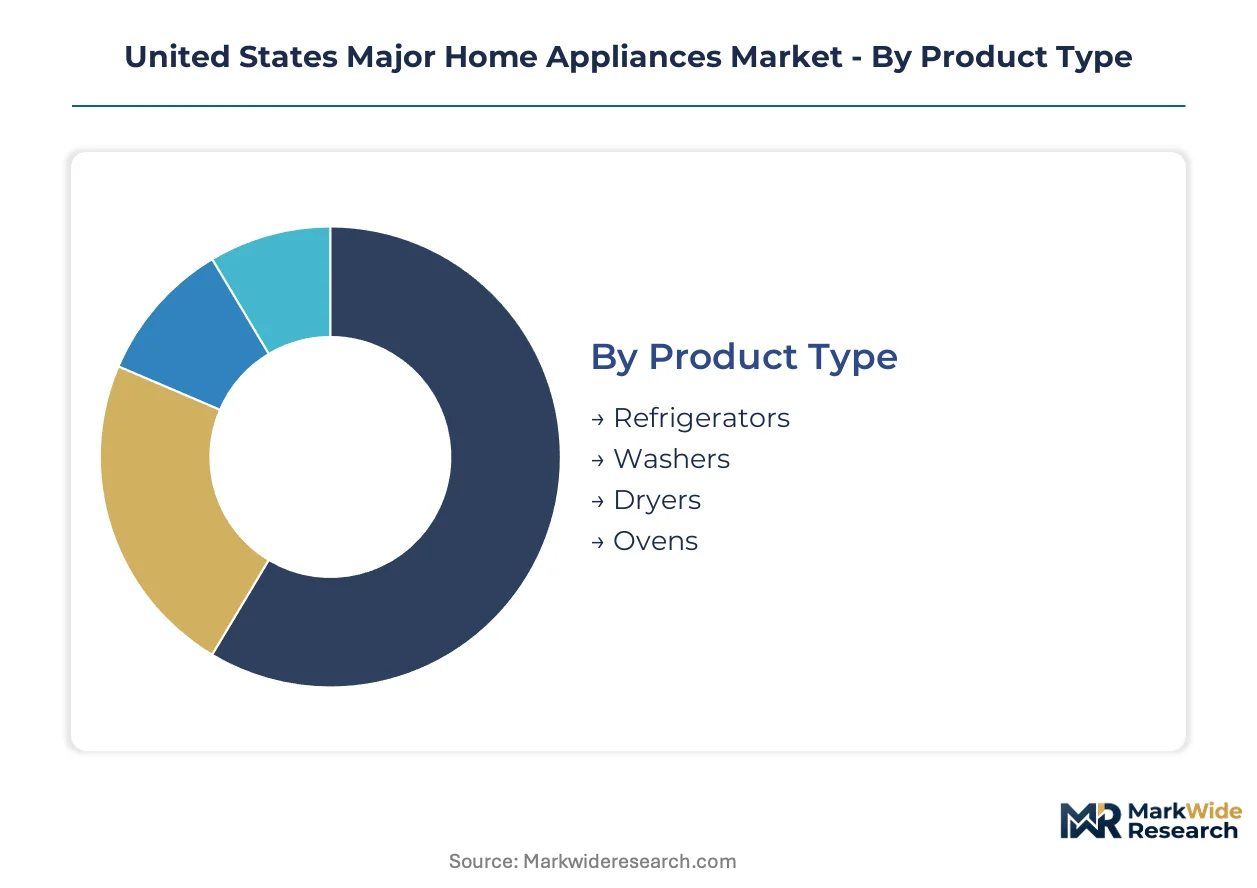
Segmentation in the United States major home appliances market reveals how replacement cycles, electrification mandates, and channel migration concentrate value across distinct product tiers and customer configurations. Understanding these splits enables manufacturers to align inverter-driven R&D and utility-partnership investments with the highest-velocity demand corridors.
Product Type:
Domestic assembly dominates refrigerators and laundry equipment, while oven sourcing retains heavier import exposure from Mexican and Asian manufacturing clusters.
- Refrigerators:Sealed-system units with variable-speed inverter compressors now dominate suburban replacement cycles. ENERGY STAR Version 7.0 compliance pressures are accelerating turnover in California, Texas, and Florida metropolitan markets where electricity rates amplify efficiency payback calculations.
- Washers:Front-load horizontal-axis drums with direct-drive motor systems command the premium residential tier. Water scarcity regulations in Western states and utility rebate programs for high-efficiency models are concentrating demand in Arizona, Nevada, and Colorado urban corridors.
- Dryers:Heat pump condensation drying is displacing conventional vented gas and electric resistance units in electrification-mandate jurisdictions. Heat pump dryers face installation complexity that slows penetration outside coastal retrofit markets.
- Ovens:Induction cooktops and convection ranges are gaining share in residential new construction. Induction requires electrical service upgrades that constrain retrofit adoption in older housing stock.
Refrigerators command the established base. The steepest expansion runs through heat pump dryers.
End User:
Cost tier stratification separates long-ownership residential purchasers from high-turnover commercial operators with distinct service and warranty expectations.
- Residential:Suburban homeowners drive replacement demand through ENERGY STAR-triggered upgrade cycles. IRA residential clean energy credits are expanding addressable market for electrified cooking and water heating equipment in owner-occupied single-family housing.
- Commercial:Multi-unit property managers prioritize total-cost-of-ownership metrics over first cost. Commercial operators demand expedited service response that favors national distribution networks over direct-to-consumer fulfillment models.
- Rental:Property owners select mid-tier durability-focused models with extended warranty terms. Rental channel volume concentrates with institutional landlords in Sun Belt metropolitan areas with above-average unit turnover.
- Hospitality:Hotels and extended-stay properties require compact configurations with unified aesthetic standards across property portfolios. Hospitality procurement runs through designated national account contracts with integrated installation and maintenance provisions.
Residential purchasers anchor volume. Hospitality is climbing the fastest on post-pandemic property renovation cycles.
Technology:
Application intensity varies across retrofit versus new construction, with smart and energy-efficient tiers demanding differentiated electrical infrastructure and installation expertise.
- Smart Appliances:Wi-Fi-enabled refrigeration and laundry equipment with utility-integrated demand response capabilities. Smart appliance enrollment for grid-balancing services is expanding rebate pools and shortening payback periods in Texas and California markets with time-of-use pricing structures.
- Energy Efficient:Units meeting or exceeding ENERGY STAR Version 7.0 thresholds with advanced insulation and control algorithms. EPA certification tightening is compressing replacement cycles for suburban homeowners in high-electricity-rate municipalities.
- Modular:Component-standardized designs enabling field service replacement of sub-assemblies. Modular architectures reduce technician dispatch costs but require inventory investment from service networks.
- Conventional:Fixed-speed compressor and resistive heating configurations without connectivity features. Conventional units retain price-positioning relevance in rental and budget residential segments.
Energy efficient models command the established base. Smart appliances are gaining share fastest on utility rebate expansion and voice-assistant integration.
Distribution Channel:
Customer type fragmentation is redrawing fulfillment economics, with direct sales and utility-sponsored channels capturing efficiency-motivated purchasers while specialty stores retain premium kitchen remodeling traffic.
- Online Retail:Platform-based fulfillment with third-party installation coordination. California CEC Title 20 provisions extending efficiency constraints to online sales channels are forcing nationwide platform compliance.
- Specialty Stores:Kitchen and bath showrooms with design consultation and project management services. Specialty channel retains high-margin built-in and premium freestanding volume.
- Hypermarkets:Big-box retail with high-volume promotional pricing and private-label offerings. Hypermarket channel faces margin compression from utility-sponsored fulfillment models.
- Direct Sales:Manufacturer-controlled e-commerce with integrated delivery and installation. Direct channels capture smart appliance purchasers seeking seamless demand-response enrollment.
Hypermarkets command the established base. Direct sales are expanding most quickly on manufacturer investments in utility-partnership fulfillment infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across US sub-regions. High-electricity-rate coastal metros drive premium efficiency demand, while Sun Belt growth markets prioritize first-cost accessibility in new construction.
California
California CEC Title 20 mandates compress replacement cycles for refrigerators and freezers. EPA ENERGY STAR Version 7.0 compliance costs fall hardest on fixed-speed inventory. Los Angeles and San Francisco Bay Area corridors concentrate smart appliance uptake through utility demand-response programs.
Texas
Deregulated electricity markets in Houston and Dallas-Fort Worth amplify time-of-use pricing incentives for grid-connected appliances. ERCOT grid instability events accelerate homeowner interest in load-shifting refrigeration. Austin and San Antonio municipal utilities bundle smart appliance rebates with installation services.
Florida
Hurricane-resilient construction codes and above-average cooling loads sustain premium refrigeration demand. Florida Public Service Commission-approved utility programs subsidize ENERGY STAR heat pump water heaters. Miami and Tampa metropolitan clusters lead smart appliance penetration among coastal suburban developments.
New York Metro
Local Law 97 carbon caps and state-level building electrification mandates accelerate induction range and heat pump dryer adoption. Con Edison demand-response pilots enroll smart appliances for peak-load reduction. Brooklyn and Queens retrofit markets face electrical service upgrade constraints that slow electrification timelines.
Pacific Northwest
Hydropower-abundant utilities offer aggressive rebate structures for high-efficiency electric appliances. Washington State Clean Buildings Performance Standards extend efficiency requirements to existing residential stock. Seattle and Portland urban cores concentrate heat pump water heater installations among aging housing renovations.
United States Major Home Appliances Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in US appliance manufacturing. Whirlpool Corporation and Samsung Electronics anchor the upper tier through captive component production and semiconductor-driven control systems. Mid-tier assemblers rely on outsourced compressor and inverter sourcing. Strategic moves concentrate on utility partnership fulfillment infrastructure and direct-to-consumer channel expansion.
Among integrated manufacturers, Whirlpool Corporation exemplifies the captive-production archetype through Midwest motor manufacturing. Samsung Electronics occupies a position defined by semiconductor and display vertical control. GE Appliances represents the US-based distribution and proprietary subsystem differentiation model. These three anchors illustrate how capital-intensity divergence separates margin-resilient leaders from import-exposed assemblers.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| BSH Home Appliances Corporation |
| LG Electronics |
| Panasonic North America |
| Haier Smart Home Co. Ltd. |
| GE Appliances |
| Electrolux Group |
| Miele |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
Variable-speed inverter modules displacing fixed-speed compressor architectures are redrawing component sourcing maps toward South Korean semiconductor clusters while compressing margin structures for mid-tier assemblers lacking captive motor production.
Pricing Analysis
After-sales service contracts and extended warranty programs now drive lifetime value capture across the installed base. Three-tier pricing structure across premium smart, ENERGY STAR-certified, and conventional economy levels segments suburban homeowners by electricity rate exposure and rebate eligibility. Cost compression in mid-tier fixed-speed inventory is intensifying because EPA ENERGY STAR Version 7.0 compliance costs fall disproportionately on legacy product lines. Rental property operators exhibit highest price sensitivity, while coastal metropolitan homeowners in high-rate utility territories show lowest sensitivity due to efficiency payback calculations.
Supply Chain Analysis
Inventory buffers for power electronics and display modules have shortened to 6-8 week horizons following pandemic-era destocking. Manufacturing concentration rests on South Korea for semiconductor-driven inverter modules, China for display and control board assemblies, and Mexico for finished oven and range metalwork. Copper winding materials, rare-earth permanent magnets, and hydrofluorocarbon refrigerants anchor raw material dependencies. Single-source vulnerability in semiconductor motor controllers exposes assemblers to foundry allocation constraints. Distribution runs through big-box retail, direct-to-consumer platforms, and utility-sponsored fulfillment models in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States major home appliances market constitutes a high-growth disruption as EPA ENERGY STAR Version 7.0 specifications and IRA residential clean energy credits simultaneously tighten efficiency thresholds and expand electrified equipment subsidies.
For Market Incumbents: Secure captive compressor and inverter module production through backward integration into Ohio and Tennessee manufacturing corridors to defend against import volatility. Prioritize UL safety listing pre-submission for connected-device cybersecurity protocols to compress validation timelines ahead of competitive launches. For New Entrants and Emerging Players: ENERGY STAR certification fast-track through EPA-recognized laboratories opens coastal market access before federal minimum efficiency updates take effect. Target Texas and Florida utility-sponsored fulfillment partnerships where municipal rate-basing authorizes grid-edge asset procurement. Pursue direct-to-consumer channel control with integrated demand-response enrollment to bypass hypermarket margin compression. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional distributors lacking smart appliance technical capabilities and utility partnership infrastructure. Long-term viability hinges on R&D allocation toward inverter architectures and sealed-system service network density. Monitor EPA appliance standards rulemaking dockets as the inflection signal for efficiency tier transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive motor production in Ohio and Tennessee insulates margins against copper and rare-earth price swings. |
| Utility Partnership Fulfillment Infrastructure | Direct collaboration with ERCOT and California IOU marketplaces captures rebate-integrated demand response enrollment volume. |
| ENERGY STAR Version 7.0 Pre-Certification | Early EPA validation secures coastal market access before California CEC Title 20 provisions extend to online channels. |
| Sealed-System Service Network Expansion | EPA Section 608 certified technician density addresses scarcity constraints in refrigerant-handling repair markets. |
| Voice-Assistant Platform Integration | Amazon Alexa and Google Home API connectivity enables subscription revenue from utility time-of-use pricing optimization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with appliance manufacturing executives, utility demand-response program managers, EPA regulatory affairs specialists, and HVAC contractor network heads; alongside secondary validation through DOE appliance standards rulemaking dockets, ENERGY STAR certification databases, FERC utility rate case filings, and UL safety listing records. Bottom-up unit shipment modeling triangulated against top-down market value reconstruction.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-user configuration, technology tier, and distribution channel structure. CAGRs were derived from replacement cycle compression rates, electrification mandate adoption curves, and smart appliance penetration trajectories. Forecast inputs incorporated electricity rate differentials across metropolitan statistical areas and utility rebate program enrollment caps.
Underlying assumptions cover ENERGY STAR specification adherence timelines and IRA credit extension continuity, with deviation risk concentrated in refrigerant phasedown schedule acceleration and semiconductor foundry allocation shocks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Washing Machine Market
Home Appliances
India Home Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
China Home Appliances Market
Home Appliances
European Built-In Refrigerator Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Japan Small Home Appliances Market