
 Australia Washing Machine Market | 2026-2036
Australia Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Washing Machine Market Outlook
Australia's Equipment Energy Efficiency (E3) Program is hardening minimum water and energy performance thresholds for residential appliances. Electrolux leverages its European engineering heritage to sustain premium positioning in front-load segments. Fisher & Paykel anchors its competitive stance through localized manufacturing and strong trade channel relationships. Haier competes aggressively on cost while extending its smart-connected product portfolio into mid-market Australian households.
A washing machine is an electromechanical appliance engineered to clean textiles through automated cycles of agitation, rinsing, and spin-drying, typically operating at drum speeds between 800 and 1600 revolutions per minute and water temperatures from cold to 90 degrees Celsius for residential and commercial sanitation. Front-load configurations dominate the premium tier due to superior water efficiency and stackability in urban apartments, while smart technology integration represents the fastest-expanding feature set as connectivity protocols enable remote cycle management and energy optimization. Energy-efficient inverter motor systems now occupy the core margin pool, displacing conventional brushed-motor platforms across replacement cycles.
The E3 Program and Water Efficiency Labelling and Standards (WELS) scheme jointly shape product design mandates, with non-compliant models barred from Australian market entry. The Australian Competition and Consumer Commission (ACCC) enforces durability and safety claims, pressuring brands to substantiate lifecycle performance. Stakeholders must monitor impending WELS rating revisions and state-level building efficiency codes that will determine which platform configurations qualify for new construction specifications and retrofit incentives.
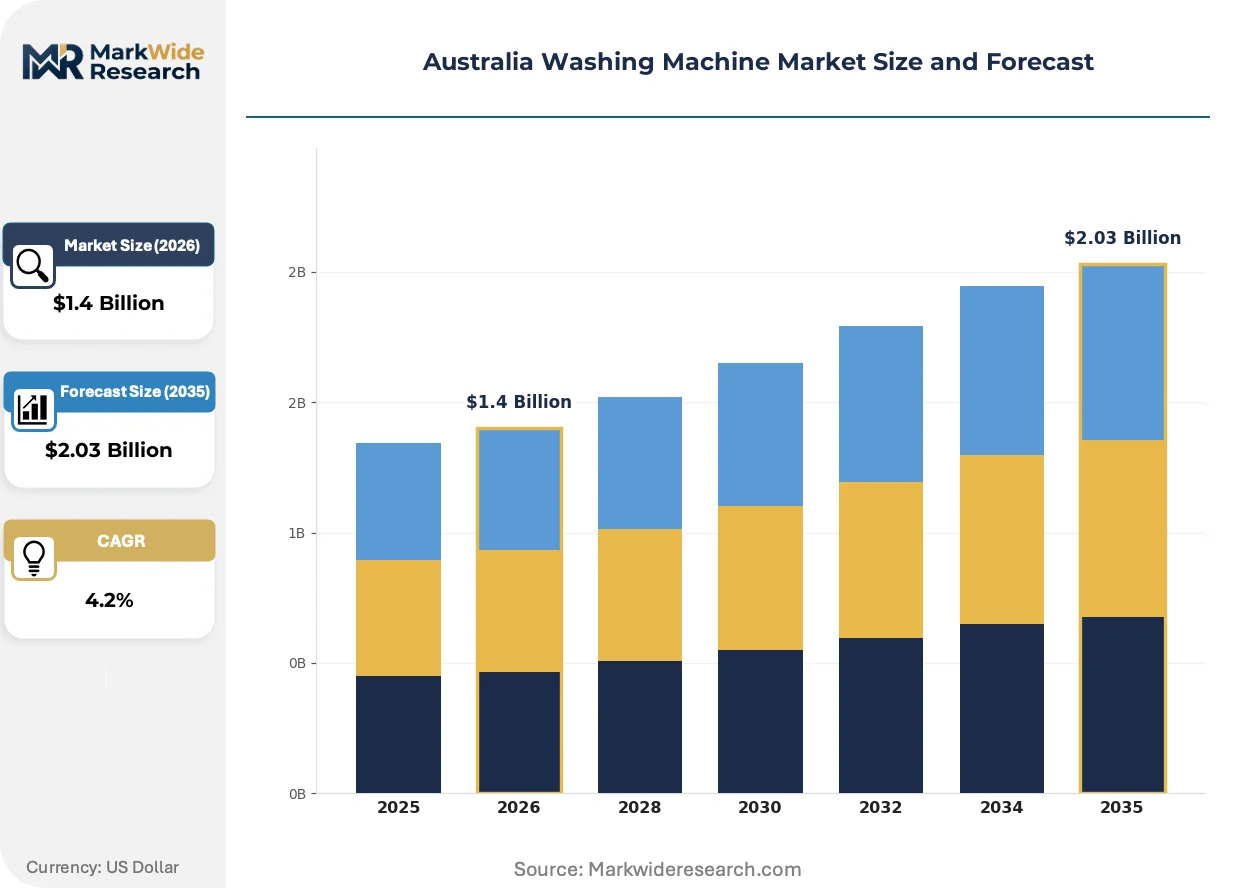
Market Dynamics
Australia's Equipment Energy Efficiency Program is compressing replacement cycles by mandating higher water and energy performance thresholds, forcing manufacturers to redesign motor systems and control architectures ahead of WELS rating revisions.
Growth Catalysts
- Build-to-rent housing expansion:Sydney and Melbourne rental operators are scaling appliance procurement as institutional investors deploy capital into multi-unit residential developments.
- WELS scheme compliance upgrades:Stricter water efficiency labelling requirements are compelling households to replace aging units with certified models.
- Inverter motor adoption:Brushless direct-drive technology is penetrating mid-market segments as energy costs pressure household budgets.
Market Restraints
- Copper and rare-earth input volatility:Motor winding materials and permanent magnet supply expose manufacturers to commodity price swings.
- Import dependency concentration:Finished goods and component sourcing clusters through Port Melbourne and Port Botany, creating single-point logistics vulnerability.
- Apartment spatial constraints:Compact laundry cavities in high-density developments limit drum capacity expansion and feature bundling.
Strategic Opportunities
- Queensland retrofit wave:Brisbane's aging housing stock and rising humidity-driven replacement rates create underpenetrated demand pockets.
- Smart-grid integration:Demand-response washing cycles that sync with rooftop solar generation are attracting early-adopter households.
- State-level efficiency rebates:Victoria's appliance upgrade incentives and New South Wales building sustainability programs subsidize premium-tier purchases.
Industry Challenges
- Certification timeline compression:E3 Program testing protocols and WELS re-rating schedules strain product development pipelines.
- Legacy electrical infrastructure:Pre-1990s apartment wiring in Melbourne's inner suburbs limits high-draw heat-pump dryer pairing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Washing Machine Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Load, Top Load, Washer-Dryer Combo, Portable Technology: Smart, Energy Efficient, Conventional, Inverter End User: Residential, Commercial, Industrial, Utility Capacity: Compact, Standard, Large, Extra Large |
| Companies Covered | Miele, Haier, Simpson, Samsung, Electrolux, LG, Panasonic, Fisher & Paykel, Hisense, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Washing Machine Market Strategic Shifts
Connected appliance ecosystems and predictive maintenance algorithms are redefining ownership economics. Manufacturers are bundling energy optimization software with hardware to capture recurring service value.
Heat-pump drying technology is decentralizing laundry energy consumption from centralized hot-water systems toward appliance-integrated thermal management. Build-to-rent operators in Sydney are specifying these units to reduce strata utility disputes. The shift is compressing traditional vented-dryer replacement demand while expanding premium front-load bundling.
The E3 Program's 2025 minimum energy performance standards are tightening allowable standby power and cycle efficiency thresholds. Manufacturers must redesign control boards and recalibrate motor mapping to maintain market access. Front-load platforms above 4-star ratings are capturing specification preference in Melbourne's new apartment approvals.
Rental housing procurement is consolidating decision authority toward property management platforms and institutional asset operators. Traditional retail channels are losing volume to direct-manufacturer contracts with build-to-rent developers. This concentration is most visible in Victoria, where Meriton and Lendlease pipelines specify white-goods packages at scale.
Australia Washing Machine Market Segmentation
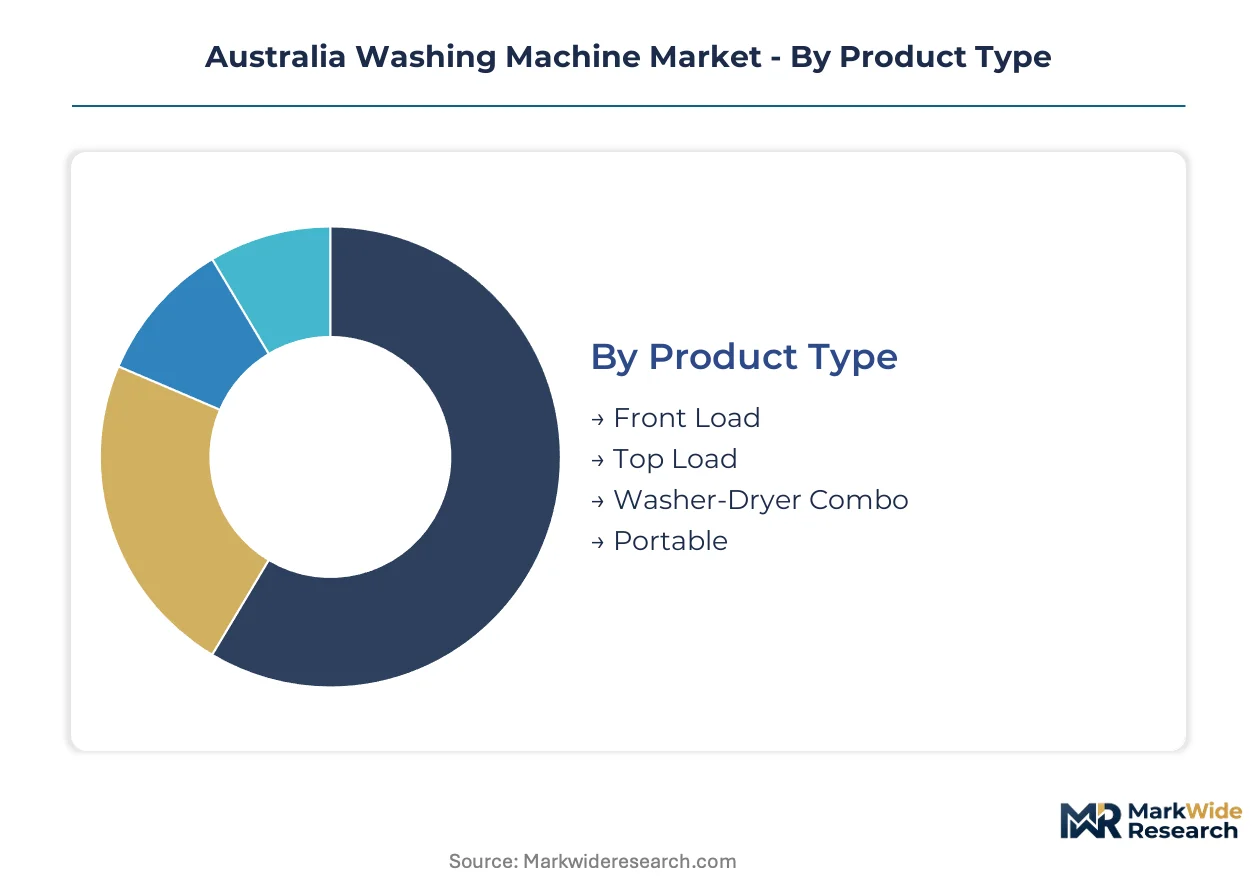
Segmentation in the Australian washing machine market reflects divergent replacement pressures across housing types and regulatory compliance tiers. Understanding these splits enables manufacturers to align motor platform investments with the specific efficiency mandates and spatial constraints governing each demand pocket.
Product Type:
Upgrade cycles accelerate where water efficiency regulations intersect with apartment stackability requirements.
- Front Load:Horizontal-axis drum orientation delivers superior water extraction and enables vertical dryer stacking. Victorian apartment approvals above 4-star WELS ratings specify these units exclusively, compressing replacement timelines for aging top-load stock in Melbourne's inner suburbs.
- Top Load:Vertical-axis agitation systems retain penetration in Queensland's detached housing stock where laundry footprint constraints are minimal. Brisbane's humidity-driven replacement wave favors these units for faster cycle completion and lower upfront procurement outlays.
- Washer-Dryer Combo:Integrated condensation drying suits Sydney's high-density build-to-rent developments with strata-managed utility allocations.
- Portable:Compact wheeled units address rental mobility and secondary dwelling applications across New South Wales granny flat conversions.
Volume placements concentrate in Front Load; the faster expansion belongs to Washer-Dryer Combo.
Technology:
Cost tier stratification separates premium inverter platforms from legacy motor architectures facing E3 Program obsolescence.
- Smart:Wi-Fi-enabled cycle management and predictive maintenance algorithms command specification preference among build-to-rent operators seeking remote diagnostics. Sydney's institutional landlords bundle these capabilities to reduce on-site service calls across multi-unit portfolios.
- Energy Efficient:Heat-pump integration and optimized thermal management satisfy Victoria's appliance upgrade rebate thresholds. Melbourne households leveraging state-level subsidies drive procurement concentration in this tier.
- Conventional:Brushed-motor platforms face accelerating displacement as E3 Program minimum standards tighten standby power allowances.
- Inverter:Brushless direct-drive systems penetrate mid-market segments as permanent-magnet motor costs moderate and energy price pressure intensifies.
Procurement volume clusters in Energy Efficient; smart connectivity is climbing the fastest.
End User:
Customer type determines channel structure and contract duration, with institutional procurement consolidating decision authority away from retail.
- Residential:Owner-occupier replacement cycles align with renovation activity and state-level rebate windows, particularly in New South Wales sustainability programs.
- Commercial:Laundromat and hospitality operators prioritize drum durability and rapid cycle throughput over efficiency ratings.
- Industrial:Continuous-batch systems serve healthcare and hospitality linen services with specialized sanitation protocols.
- Utility:Build-to-rent developers and property management platforms specify white-goods packages at scale, bypassing traditional retail channels entirely.
Residential maintains placement dominance; Utility procurement is gaining share fastest.
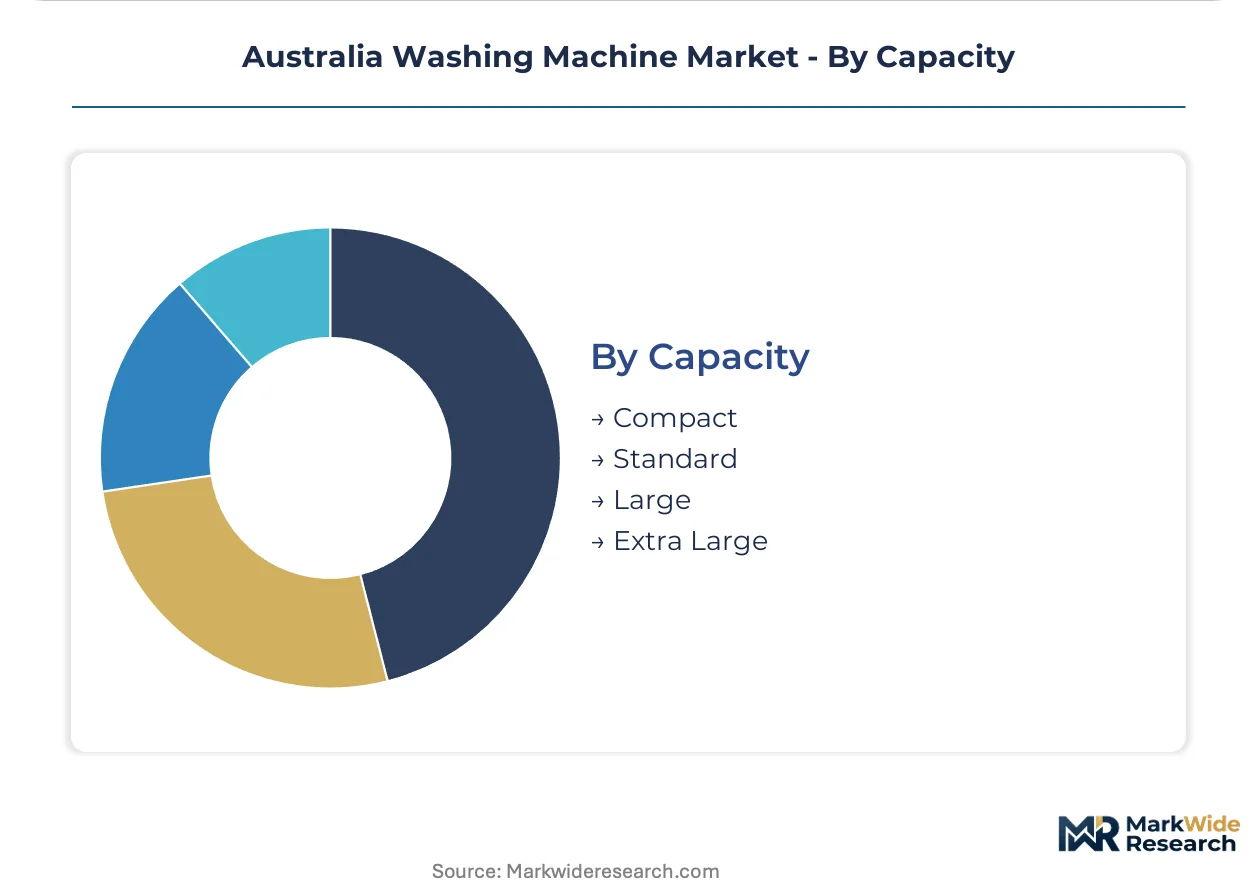
Capacity:
Margin pools concentrate where drum volume intersects with inverter motor bundling and smart feature integration.
- Standard:7-8.5kg drum capacity captures the core replacement market across Australian detached housing. These units balance load flexibility with cabinet dimensions compatible with pre-2000 laundry recesses.
- Large:9-10kg configurations attract family households in Queensland's outer suburbs where batch consolidation reduces cycle frequency. Brisbane's larger land parcels accommodate the physical footprint.
- Compact:Sub-7kg drums address apartment spatial constraints in Sydney and Melbourne high-density developments.
- Extra Large:10.5kg-plus drums serve commercial operators and multi-generational households with consolidated washing requirements.
Standard capacity drives unit volume; Large configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne command the bulk of Australian washing machine procurement, with build-to-rent developers and renovation contractors driving specification volumes across these metropolitan corridors.
New South Wales
Apartment construction in Sydney's inner-ring suburbs accelerates front-load washer specifications, with Meriton and Lendlease bundling white-goods packages into multi-unit developments. The state's building sustainability programs subsidize premium-tier purchases through appliance upgrade incentives. Port Botany handles the majority of finished goods importation, creating logistics concentration for national distribution.
Victoria
Melbourne's renovation activity and apartment density outpace other states, compressing replacement timelines for aging top-load stock in inner suburbs. Victoria's appliance upgrade rebates and efficiency programs direct procurement toward 4-star WELS-rated units. The Fisher & Paykel manufacturing presence in Auckland supports localized supply chain responsiveness across the Tasman corridor.
Queensland
Brisbane's humidity-driven replacement wave favors faster-cycle top-load configurations in detached housing stock across outer suburbs. The state's aging housing inventory creates underpenetrated demand pockets for retrofit activity. Gold Coast and Sunshine Coast rental markets show rising procurement from property management platforms consolidating decision authority.
Western Australia
Perth's mining-dependent household formation rates create cyclical demand volatility for standard-capacity units in suburban developments. The state's water efficiency regulations align with national WELS standards, directing procurement toward certified models. Fremantle port infrastructure supports direct importation from Asian manufacturing centers, bypassing eastern seaboard congestion.
South Australia
Adelaide's slower housing turnover extends replacement cycles compared to eastern capitals, with owner-occupier renovation timing driving procurement windows. The state's building efficiency codes incorporate federal E3 Program minimums for new construction specifications. Limited local distribution infrastructure concentrates retail channel presence in metropolitan Adelaide.
Australia Washing Machine Market Competitive Environment
The competitive structure tilts toward diversified appliance conglomerates with multi-brand portfolios spanning premium and mass-market tiers. European engineering heritage and Asian manufacturing scale represent the dominant strategic archetypes, with localized assembly operations providing regulatory compliance advantages. Capacity expansion through build-to-rent direct contracts and portfolio diversification into smart-connected ecosystems constitute the primary competitive moves reshaping channel relationships.
Within the premium-tier vector, Miele exemplifies European engineering positioning through its German GmbH structure, while Electrolux anchors Swedish-heritage consolidation across mid-market and premium segments. Fisher & Paykel represents Australasian localized manufacturing archetypes, with its corporate form signaling regional supply chain integration. Haier occupies the scale-driven Chinese conglomerate position, competing through cost architecture and connected-product portfolio extension.
| Leading Market Players |
|---|
| Miele |
| Haier |
| Simpson |
| Samsung |
| Electrolux |
| LG |
| Panasonic |
| Fisher & Paykel |
| Hisense |
| Others |
Value Chain & Pricing Dynamics
Australia's Equipment Energy Efficiency (E3) Program gates qualified supply and premium-tier pricing access by mandating minimum water and energy performance thresholds that only inverter motor platforms and heat-pump configurations satisfy. This regulatory filter concentrates margin capture among manufacturers with certified 4-star WELS-rated portfolios while compressing pricing power for legacy brushed-motor suppliers facing market exit.
Pricing Analysis
Energy throughput per cycle anchors value-based pricing, with heat-pump integrated units commanding premium positioning against conventional vented-dryer pairings. Three-tier pricing structure across premium, standard, and economy levels separates Fisher & Paykel's localized assembly from Haier's cost-optimized imports and Miele's German-engineered positioning. Cost compression in economy tiers is intensifying because Chinese manufacturers are flooding mid-market channels with inverter-equipped models. Build-to-rent developers exhibit lowest price sensitivity due to bulk procurement scales and strata utility allocation pass-through, while Queensland's detached housing owner-occupiers remain most price-responsive.
Supply Chain Analysis
Direct-to-developer channels handle build-to-rent hyperscale demand, bypassing traditional retail distribution entirely. Finished goods concentration rests on China, Thailand, and Vietnam for component assembly and motor manufacturing, with Fisher & Paykel's Auckland facility providing Tasman corridor responsiveness. Permanent magnet rare-earth inputs and copper winding materials draw from Chinese and Australian mining operations. Single-source vulnerability concentrates through Port Melbourne and Port Botany, where customs clearance bottlenecks disrupt national distribution. Distribution runs through institutional procurement platforms and property management aggregators consolidating multi-unit specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's washing machine market operates as a supply-constrained story where E3 Program certification capacity bottlenecks prop pricing by limiting qualified supplier pools to manufacturers with compliant motor platforms and testing infrastructure.
For Market Incumbents: To counter Haier's cost-optimized smart-connected portfolio expansion, Electrolux and Fisher & Paykel should deepen backward integration into inverter motor production and secure exclusive build-to-rent developer contracts through white-goods package bundling. Certification investment in 5-star WELS-rated heat-pump configurations will defend margin position against regulatory ratcheting.
For New Entrants and Emerging Players: Capture Queensland's humidity-driven replacement wave in Brisbane's aging detached housing stock, where top-load configurations retain penetration and incumbent coverage remains thin. Target property management platforms consolidating Gold Coast and Sunshine Coast rental procurement as the most penetrable channel archetype, leveraging direct-manufacturer contracting to bypass established retail gatekeepers.
For Investors and Strategic Acquirers: Victoria's appliance upgrade rebate program expansion is the leading indicator that state-level efficiency incentives will sustain premium-tier demand across the analysis window. Acquisition targets should prioritize localized assembly operations with E3 Program testing infrastructure and existing trade channel relationships. The signal to monitor is WELS rating revision announcements that would trigger compliance-driven replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Integration | Meets Victoria's rebate thresholds and reduces strata utility disputes in Sydney build-to-rent developments. |
| Direct-to-Developer Contracting | Bypasses retail margin compression by securing Meriton and Lendlease pipeline specifications at scale. |
| Inverter Motor Platform Expansion | Displaces brushed-motor inventory ahead of E3 Program standby power threshold tightening. |
| Smart-Grid Cycle Optimization | Captures early-adopter households with rooftop solar synchronization and demand-response capabilities. |
| Queensland Distribution Buildout | Addresses underpenetrated Brisbane retrofit demand and humidity-driven replacement frequency. |
Study Parameters
Independent corroboration across appliance manufacturer executives, property management platform procurement directors, and retail channel category managers underwrites the qualitative findings in this study. Primary interviews with Fisher & Paykel supply chain leads, Electrolux regulatory affairs specialists, and Haier connected-product engineers combined with secondary validation from Australian Bureau of Statistics building approval data, WELS registry certifications, and ACCC enforcement disclosures. Bottom-up unit shipment analysis and top-down market value estimation triangulate across the modeling period.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, technology tier, capacity segment, and end-user category dimensions. CAGRs derive from regression analysis against housing formation rates, renovation expenditure cycles, and regulatory compliance deadlines. Forecast inputs incorporate Port Melbourne and Port Botany import volume trends, copper and rare-earth price indices, and state-level rebate program budget allocations.
The model holds under stable E3 Program implementation timelines and WELS rating continuity; deviation in regulatory acceleration or commodity price spikes would shift replacement cycle assumptions. Forecasts reflect documented base-case assumptions regarding build-to-rent pipeline completion and inverter motor cost curves. Periodic stress-testing of base assumptions is recommended against ACCC enforcement intensity and Queensland humidity-driven failure rate variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
UK Household Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Built-In Appliance Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Chile Home Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
Europe Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
Built-In Hobs Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Qatar Home Appliances Market