
 US Household Appliances Market | 2026-2036
US Household Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
US Household Appliances Market Intelligence
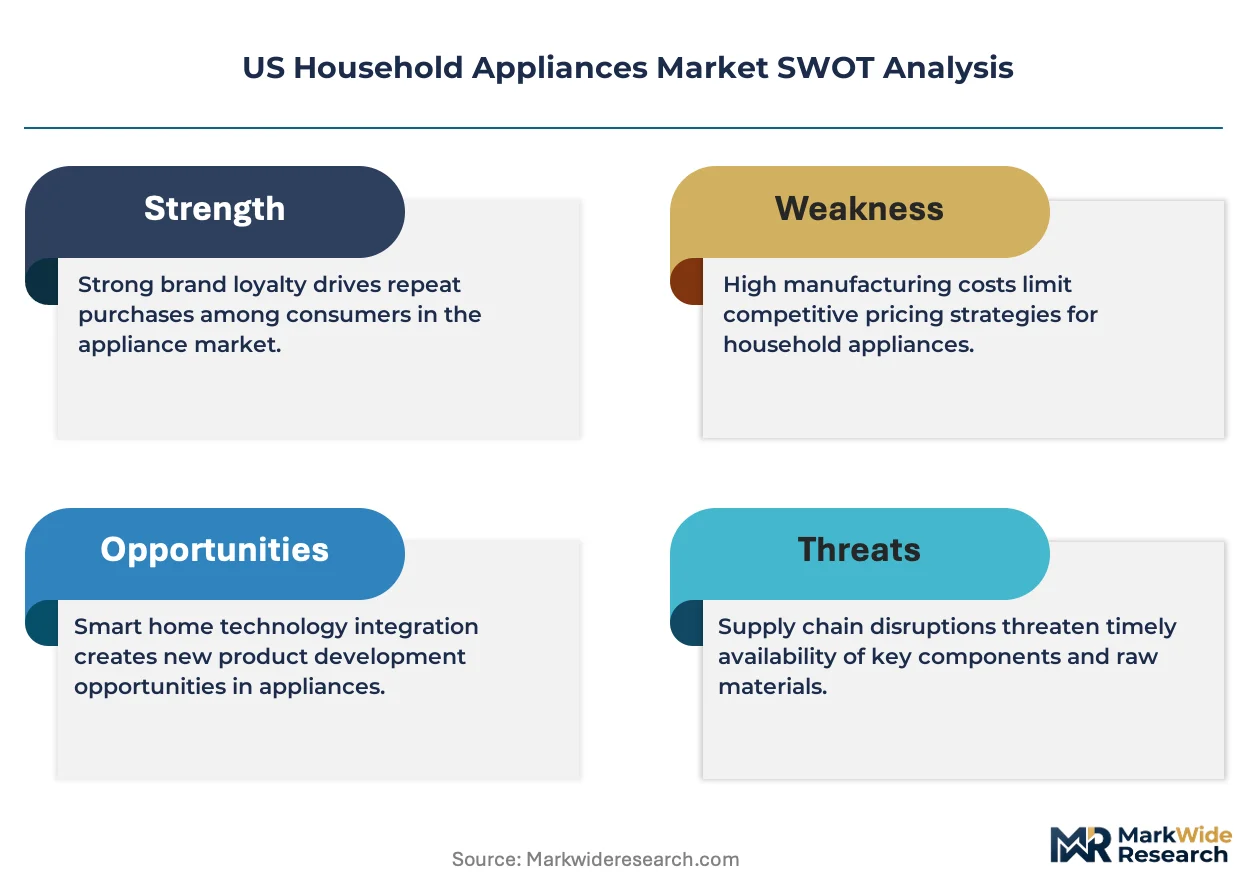
New manufacturing investment in Southeastern states like Tennessee and South Carolina is tilting the domestic production landscape. Whirlpool leverages its extensive US manufacturing footprint to control supply chain logistics and reduce import dependency. In contrast, Samsung Electronics competes on technology integration and smart home features. GE Appliances sustains a strong brand presence through its deep relationships with US home builders.
US household appliances encompass a range of electrically or mechanically powered devices designed for domestic tasks like food preservation, cooking, and cleaning. These products are engineered for specific energy consumption targets, often measured in kWh per year, and operational noise levels. The market for smart appliances represents the fastest-growing technology segment, driven by connectivity and remote management. In terms of distribution, home improvement stores and online retail channels are gaining share from traditional specialty shops.
The EPA's Energy Star program sets voluntary standards for energy efficiency that heavily influence consumer choice and product development. Concurrently, the FTC's Appliance Labeling Rule mandates clear disclosure of energy consumption, enabling direct product comparisons. Navigating the transition to lower-GWP refrigerants while managing cost and performance will be a critical decision point for manufacturers.
Market Dynamics
The US household appliance market is shaped by the central tension between long-term product replacement cycles and the rapid pace of technological innovation. Regulatory pressure from the EPA for greater energy efficiency intersects with consumer demand for smart, connected home ecosystems.
Growth Catalysts
- Federal Efficiency Incentives:The EPA's Energy Star standards, often coupled with federal tax credits under policies like the Inflation Reduction Act, encourage consumers to replace older units with more energy-efficient models, accelerating the replacement cycle.
- Housing Market Dynamics:Sustained new home construction, particularly in Sun Belt states, and a robust home renovation market create consistent demand for full suites of new kitchen and laundry appliances.
- Smart Home Integration:The proliferation of IoT connectivity allows appliances to integrate into broader smart home platforms, creating new value propositions around convenience, remote management, and predictive maintenance for consumers.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of essential inputs such as steel, copper, and resins create significant margin pressure for manufacturers and can lead to price instability for consumers.
- Semiconductor Dependency:A high reliance on imported microcontrollers and sensors for smart appliance features exposes the domestic supply chain to geopolitical risks and global component shortages, potentially delaying production.
- Long Replacement Cycles:The inherent durability and high cost of major appliances mean consumers replace them infrequently, slowing the market-wide adoption of the latest energy-saving and smart technologies.
Strategic Opportunities
- Build-to-Rent Sector:Developing specialized appliance lines for the growing build-to-rent housing market, emphasizing durability, energy efficiency, and centralized management capabilities for property managers, opens a new B2B channel.
- Low-GWP Refrigerants:The mandated phase-down of high-GWP refrigerants under the EPA's AIM Act creates a significant opportunity for manufacturers to lead with next-generation cooling systems that offer superior environmental performance.
- Subscription-Based Services:Launching subscription models for consumables like water filters and detergents, or for premium software features and extended warranties, can create valuable recurring revenue streams beyond the initial hardware sale.
Industry Challenges
- Skilled Technician Shortage:A deficit of qualified repair technicians trained to service modern, electronically complex appliances strains after-sales support networks and can negatively impact brand perception and customer loyalty.
- Regulatory Fragmentation:Navigating a complex web of differing state-level energy and water consumption standards, such as those set by the California Energy Commission, complicates product design and national distribution.
- Consumer Data Privacy:Managing the vast amounts of data collected by smart appliances while ensuring compliance with privacy regulations like the CCPA presents a significant technical and legal challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Household Appliances Market |
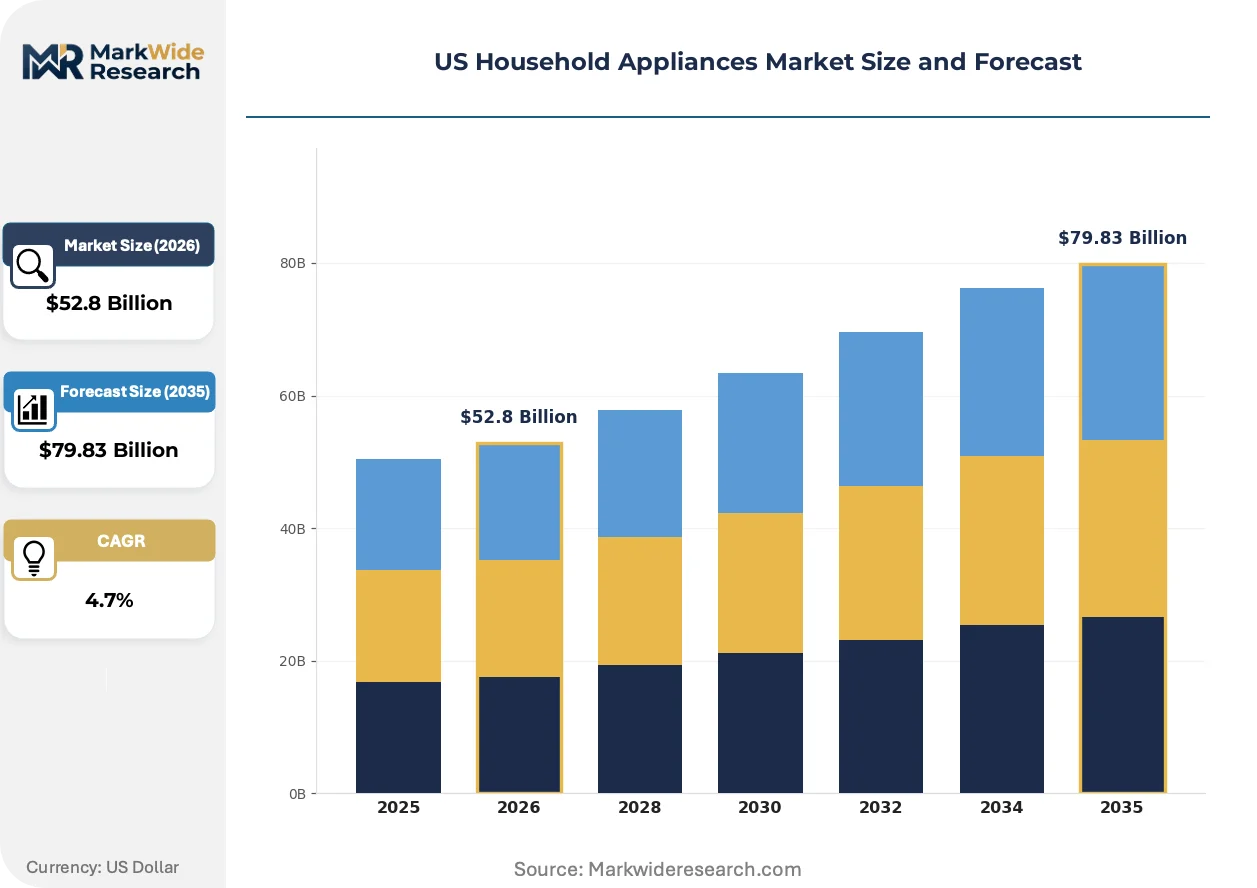
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.83 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Dishwashers, Ovens Technology: Smart Appliances, Energy-Efficient, Conventional, Hybrid End User: Single-Family Homes, Apartments, Condominiums, Vacation Homes Distribution Channel: Online Retail, Home Improvement Stores, Specialty Shops, Wholesale |
| Companies Covered | Whirlpool, Electrolux, LG Electronics, Miele, Haier Smart Home, GE Appliances, Bosch, Frigidaire, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Household Appliances Market Strategic Shifts & Innovations
Product development in the US household appliance sector is increasingly defined by the twin objectives of enhanced energy efficiency and seamless smart home integration. These forces are fundamentally altering product design, material selection, and the user experience, pushing manufacturers beyond traditional performance metrics.
Solid-state cooling technology utilizes thermoelectric principles to achieve refrigeration without compressors or chemical refrigerants. Early adoption is concentrated in the premium appliance segment for applications like wine coolers and specialized compact refrigerators. This technology is rendering obsolete the reliance on traditional vapor-compression systems for certain use cases, enabling quieter operation and innovative, space-saving product designs.
The FTC's Appliance Labeling Rule now requires more detailed information on the yellow EnergyGuide labels, including lifetime energy cost estimates. This regulatory update forces manufacturers to compete more directly on long-term operational efficiency rather than just purchase price. The rule most directly affects high-consumption categories like refrigerators, clothes washers, and dryers, where consumers are highly sensitive to utility costs.
A notable behavioral shift is the emergence of appliance-as-a-service models, particularly in urban residential markets. This trend disrupts the traditional ownership model, with property developers or specialized service companies offering appliance leasing and maintenance packages. This is most prevalent in new multi-family housing units targeting younger consumers who value flexibility and predictable monthly costs over long-term capital investment.
US Household Appliances Market Segmentation
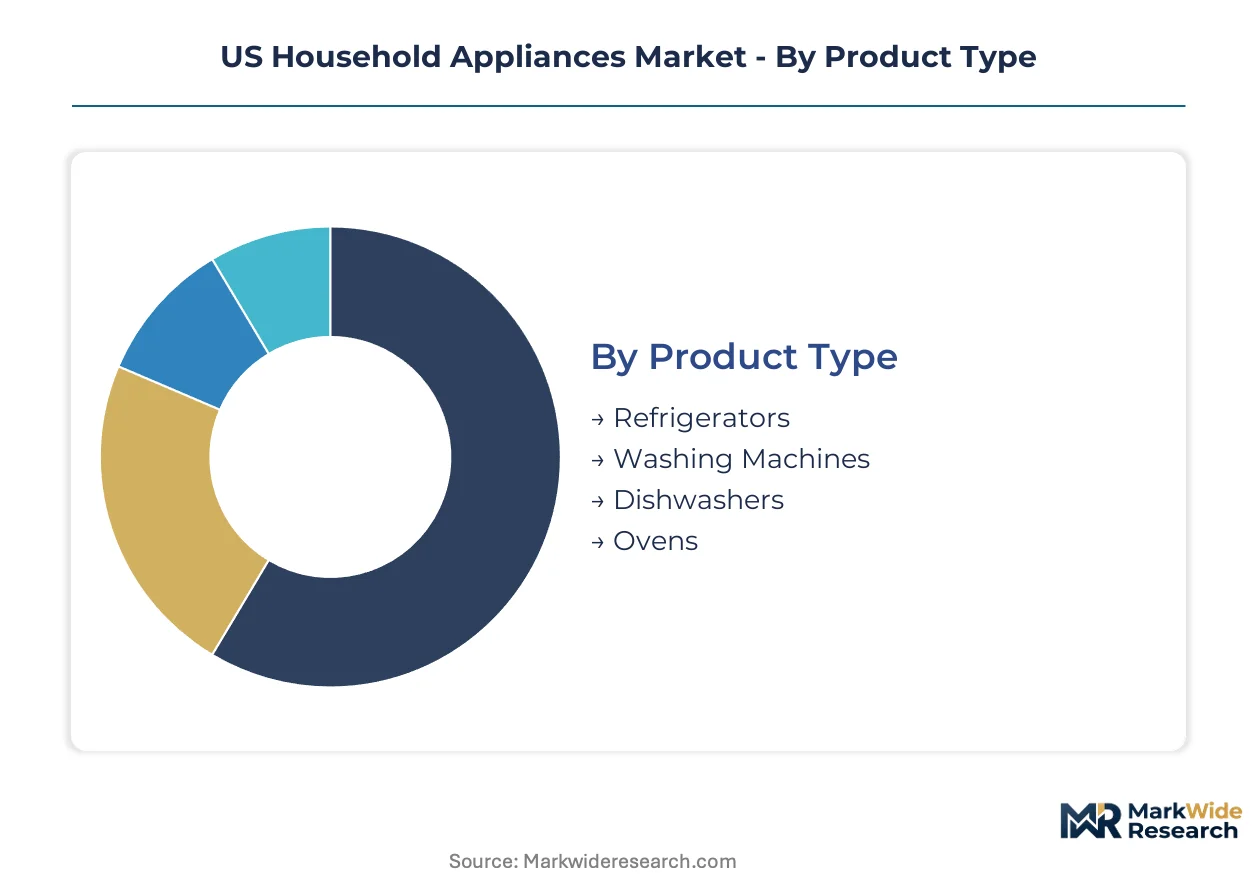
Segmentation within the US household appliances market provides a granular view of diverse consumer preferences, technological adoption rates, and procurement behaviors. This detailed breakdown helps manufacturers and retailers tailor product development, marketing strategies, and distribution networks to specific market demands across the nation.
Product Type:
The spectrum of household chores and preservation needs defines product type segmentation within the US market.
- Refrigerators:These essential units maintain specific temperature ranges for food preservation in American homes. Demand remains strong in new housing construction and replacement cycles within Sun Belt states.
- Washing Machines:Designed for textile cleaning, these appliances feature various load capacities and wash cycles for US households. EPA Energy Star standards heavily influence consumer purchasing decisions in this category.
- Dishwashers:These appliances automate dish cleaning, offering water and energy efficiency for US homes.
- Ovens:Used for cooking and baking, these units are available in electric or gas variants for American kitchens.
Established volume favors Refrigerators; emerging adoption favors Washing Machines.
Technology:
Application differentiation drives the various technological approaches in appliance design.
- Smart Appliances:These units integrate IoT for remote control, diagnostics, and automation capabilities. Consumer demand for smart home ecosystems in US urban centers boosts this segment.
- Energy-Efficient:These appliances meet or exceed EPA Energy Star criteria, reducing utility consumption for American users. Federal efficiency incentives under the Inflation Reduction Act accelerate their adoption across the US.
- Conventional:These appliances offer basic functionality without advanced connectivity or specialized efficiency features for budget-conscious US consumers.
- Hybrid:These models combine different operational principles, such as heat pump dryers, for enhanced performance in American homes.
Smart Appliances represent the fastest-growing technology segment, while conventional models maintain a stable user base.
End User:
Customer type dictates appliance specifications and purchasing volumes across the US market.
- Single-Family Homes:This segment requires full suites of appliances for new construction and replacement cycles. It drives significant demand, particularly in Sun Belt states like Texas and Florida.
- Apartments:These residential units often demand durable, space-saving, and energy-efficient models for rental properties. Property managers in US urban centers prioritize low maintenance and long lifespans.
- Condominiums:These dwellings focus on compact designs and premium features, catering to urban US dwellers.
- Vacation Homes:These properties prioritize reliability and remote management capabilities for intermittent use by US owners.
Single-Family Homes concentrate the largest volume of appliance sales, with Apartments exhibiting consistent procurement.
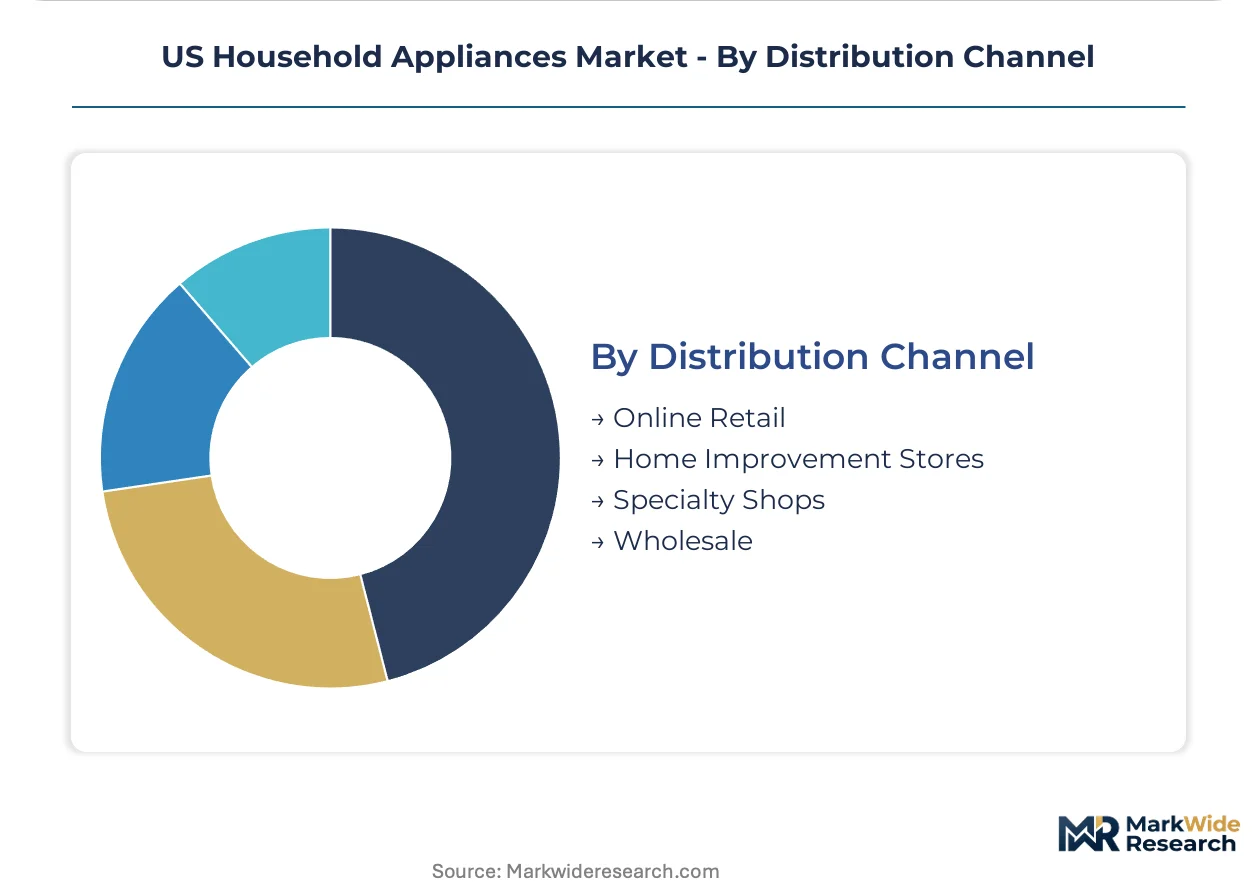
Distribution Channel:
Supply concentration and consumer access shape the varied distribution channels for household appliances in the US.
- Online Retail:This channel offers broad product selection, competitive pricing, and direct-to-consumer delivery. It gains share due to convenience and digital-first purchasing habits of US consumers.
- Home Improvement Stores:These outlets provide a physical showroom experience, installation services, and a wide array of brands. They remain critical for DIY remodelers and professional contractors in the US.
- Specialty Shops:These stores offer curated selections and personalized service, targeting niche segments of the US market.
- Wholesale:This channel supplies appliances in bulk to builders and property developers for new US housing projects.
Online Retail is rapidly gaining market share, while Home Improvement Stores maintain a foundational presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's energy efficiency standards significantly influence appliance demand and innovation across the United States. These federal guidelines drive consumer preferences toward more efficient models. This national market exhibits diverse regional dynamics shaped by population shifts and housing trends.
Texas
Demand for appliances in Texas is robust, fueled by rapid population growth and extensive new housing construction. The state's energy efficiency programs, often complementing federal incentives, influence purchasing decisions for new homes. Major metropolitan areas like Dallas and Houston consistently drive demand for full appliance suites in residential developments.
Florida
Florida's appliance market benefits from a strong influx of new residents and ongoing home renovation projects. The FTC's Appliance Labeling Rule ensures transparency, helping consumers compare energy costs in this high-consumption state. New housing starts in cities such as Orlando and Miami generate significant sales volume for major appliance categories.
California
Consumers in California prioritize energy-efficient and smart appliances, driven by stringent state-level regulations and environmental consciousness. The California Energy Commission sets some of the nation's most aggressive efficiency standards, impacting product design. Silicon Valley and other tech-centric regions show high adoption rates for connected home ecosystems.
Southeast
The Southeastern states, including Tennessee and South Carolina, experience growing appliance demand due to manufacturing investment and population migration. Federal tax credits under the Inflation Reduction Act encourage residents to upgrade to more efficient models. New manufacturing facilities in areas like Nashville and Greenville are reshaping regional supply chains and employment.
Midwest
The Midwest region sees steady appliance replacement cycles, particularly in established housing markets and agricultural communities. EPA Energy Star standards guide consumer choices for durable and efficient units, supporting long-term value. Appliance manufacturing hubs in states like Ohio and Michigan continue to serve national distribution networks.
US Household Appliances Market Key Industry Players
Capability concentration sits with one tier, focusing on advanced features and smart technology, while scale advantage sits with another, emphasizing broad market reach and cost efficiency. The US household appliance market exhibits a tiered structure, with global conglomerates competing against specialized innovators. Strategic archetypes include technology-driven leaders, value-segment providers, and brand heritage specialists. Competitive moves frequently involve strategic partnerships for smart home integration and ongoing capacity expansion to meet regional demand.
At the scale-driven end, Whirlpool leverages its extensive US manufacturing footprint to control supply chain logistics and reduce import dependency, serving a broad consumer base. Samsung Electronics exemplifies a technology-driven leader, integrating advanced smart home features and connectivity into its diverse product lines. Haier Smart Home, through its GE Appliances brand, occupies a strong position with deep relationships across the US home builder segment, ensuring consistent placement in new constructions and renovation projects. These companies collectively influence product development and distribution strategies across the market.
| Leading Market Players |
|---|
| Whirlpool |
| Electrolux |
| LG Electronics |
| Miele |
| Haier Smart Home |
| GE Appliances |
| Bosch |
| Frigidaire |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Underutilization in some US appliance manufacturing facilities drives competitive pricing strategies, influencing both supplier margins and consumer purchasing decisions. This dynamic shapes the market's response to fluctuating demand and technological shifts.
Pricing Analysis
Geographic disparities in appliance pricing reflect regional distribution costs and varying state-level regulatory compliance. The dominant pricing model remains per-unit transactional, though subscription models for services are emerging. Brand premium, after-sales service bundles, and energy efficiency certifications drive price differentiation in the premium segments. Price erosion runs through the conventional appliance segment due to intense competition among value providers, where budget-conscious US consumers exhibit the highest price sensitivity.
Supply Chain Analysis
Semiconductor dependency for smart appliance features exposes the US domestic supply chain to geopolitical risks and global component shortages. Geographic supply for critical microcontrollers and sensors centers on China and South Korea, while some finished goods originate from Mexico. Raw material dependencies include steel, copper, and resins. Distribution runs through a mixed model of home improvement stores, online retail, and wholesale channels for new US housing projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US household appliance market exhibits a shift in buyer power towards consolidated entities like property management groups in the build-to-rent sector. These buyers prioritize durability and centralized management capabilities, influencing procurement patterns.
For Market Incumbents: Build a robust service network moat by investing in specialized technician training programs for complex smart appliances. This counters the skilled technician shortage, a significant threat to brand perception and customer loyalty. Deepen relationships with home builders for consistent product placement and after-sales support.
For New Entrants and Emerging Players: Build out specialized appliance lines for the growing build-to-rent sector, emphasizing durability and centralized management features. The urban multi-family housing segment offers a penetrable white space for these offerings. Launching subscription models for consumables or premium software provides a recurring revenue go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers successfully integrating subscription-based services for consumables or premium software. The US household appliance market offers long-term viability due to consistent replacement cycles and housing market dynamics. Target technology-driven players with strong smart home integration capabilities; the rapid adoption of low-GWP refrigerant technologies is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Low-GWP Refrigerant R&D | Leading with next-generation cooling systems enhances environmental performance and meets EPA AIM Act mandates. |
| Expand Smart Home Platform Partnerships | Deeper integration with broader smart home ecosystems creates new value propositions for US consumers. |
| Develop Build-to-Rent Appliance Lines | Tailored product offerings capture demand from the growing B2B build-to-rent housing market. |
| Enhance After-Sales Service Training | Addressing the skilled technician shortage improves customer loyalty and brand perception for complex units. |
| Strengthen Online Retail Channels | Adapting to digital-first purchasing habits of US consumers expands market reach and sales volume. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA Energy Star databases, FTC Appliance Labeling Rule documents, and housing market reports. This involved interviews with product development executives, property managers, retail buyers, and home builders. The approach triangulates insights from both bottom-up market observations and top-down regulatory analyses. Manufacturer financial filings provided additional market context.
Forecast inputs considered include historical market performance, macroeconomic indicators, and regulatory changes across the modeling period. The analytical framework modeled segmentation dimensions such as product type, technology, end user, distribution channel, and regional housing starts. Compound Annual Growth Rates were derived from historical trends and projected market drivers. Energy efficiency regulation impacts and smart home adoption rates were key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology disruptors or vertically integrated manufacturers would shift outcomes. Raw material price volatility and unforeseen geopolitical events represent specific risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Israel Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Electric Fireplace Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
India Home Appliances Market