
 Germany Small Home Appliance Market | 2026-2036
Germany Small Home Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Small Home Appliance Market Foresight
The EU Ecodesign Directive is hardening efficiency benchmarks for vacuum cleaners and kitchen appliances sold in Germany. BSH Hausgeräte GmbH leverages its Stuttgart engineering base to sustain premium positioning across built-in coffee systems. Samsung Electronics GmbH anchors its Berlin operations with smart connectivity integration that competes with established European brands. Philips GmbH differentiates through specialized steam-based garment care products that dominate the domestic iron segment.
Small home appliances comprise electrically powered portable devices designed for domestic tasks, typically operating below 2.5 kW and incorporating motors, heating elements, or rechargeable lithium-ion battery packs for cordless mobility. Coffee makers and vacuum cleaners represent the largest product type segments by installed base, while cordless technology is expanding fastest as lithium-ion energy density improves and German consumers prioritize maneuverability in compact urban kitchens. Smart connectivity integration is creating new margin pools through app-enabled maintenance subscriptions and usage analytics.
Germany's Federal Environment Agency enforces Ecodesign requirements under EU framework directives, while the Federal Network Agency monitors electromagnetic compatibility standards for connected devices. REACH compliance through ECHA shapes material selection for plastics and coatings in food-contact appliances. KBA safety certifications apply to battery transport and charging systems in cordless categories. Stakeholders must monitor how forthcoming EU right-to-repair regulations will reshape spare parts availability and product lifecycle design decisions.
Market Dynamics
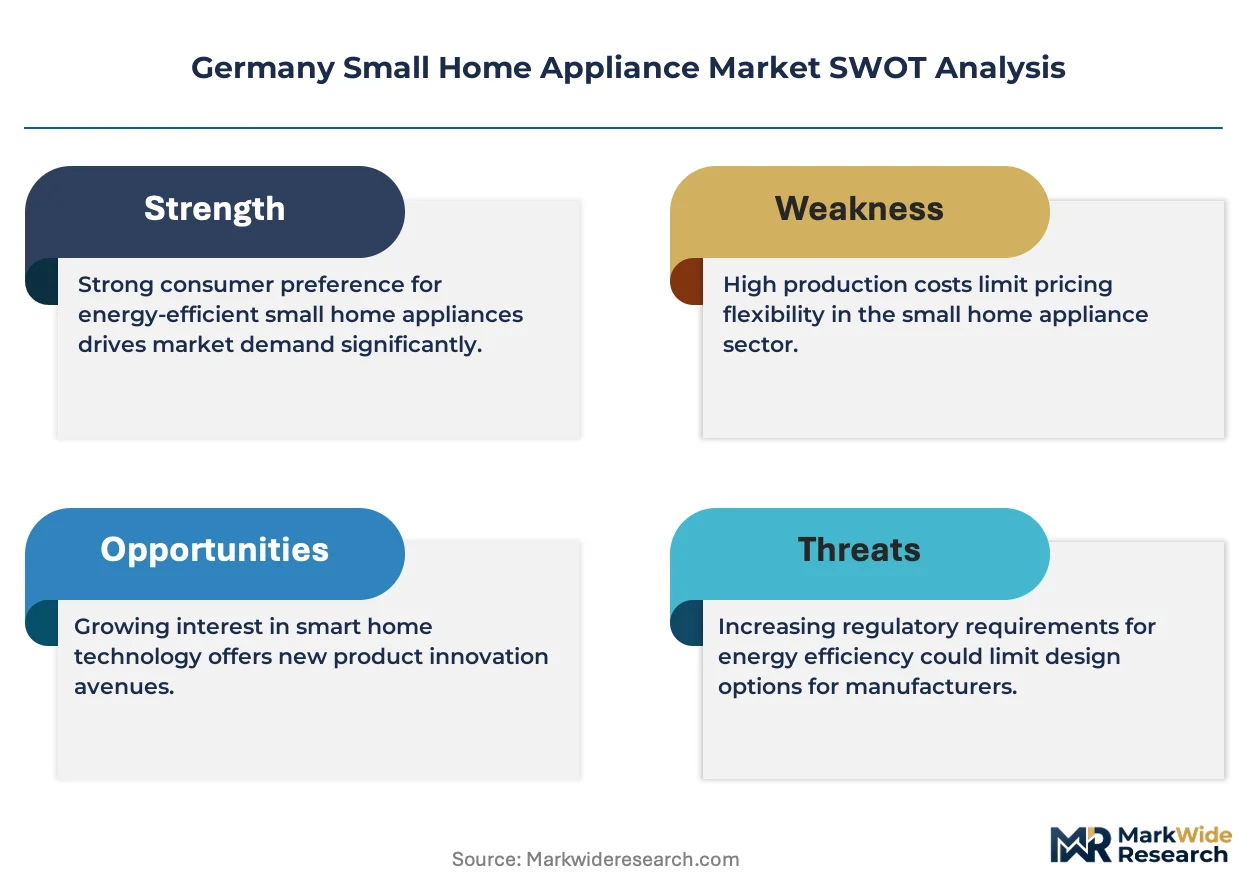
Germany's Ecodesign Directive and national appliance efficiency labeling requirements are compressing product development cycles while simultaneously opening margin pools for compliant manufacturers. This regulatory pressure intersects with urban rental household expansion in Berlin and Munich to favor compact, energy-efficient form factors.
Growth Catalysts
- EU Ecodesign Directive:Hardening efficiency benchmarks for vacuum cleaners and kitchen appliances are forcing manufacturers to redesign motor and heating systems, creating first-mover advantages for engineering-capable suppliers.
- Urban rental household expansion:Berlin and Munich rental markets are driving demand for compact appliances that fit smaller kitchens and move easily between residences.
- Lithium-ion energy density improvements:Cordless technology is expanding fastest as battery chemistry advances enable longer runtime in vacuum cleaners and handheld kitchen devices.
Market Restraints
- REACH compliance costs:ECHA material restrictions on plastics and coatings in food-contact appliances are raising input costs and limiting supplier options for German manufacturers.
- Electromagnetic compatibility testing:Federal Network Agency certification requirements for connected devices are extending product launch timelines by four to eight months.
- Right-to-repair preparation:Forthcoming EU regulations are forcing redesign of spare parts availability systems, requiring inventory investments before revenue recovery is certain.
Strategic Opportunities
- Western industrial corridor concentration:Stuttgart engineering clusters and Berlin smart connectivity operations offer geographic proximity to tier-one automotive electronics suppliers seeking appliance diversification.
- App-enabled maintenance subscriptions:Smart connectivity integration is creating recurring revenue streams through predictive maintenance alerts and consumable replenishment services.
- Steam-based garment care specialization:Technical differentiation in fabric care systems allows premium positioning outside commoditized heating-element categories.
Industry Challenges
- KBA battery safety certification:Cordless category expansion requires navigation of complex transport and charging system approvals that few product managers have mastered.
- Embedded software talent scarcity:Smart appliance development competes with automotive and industrial automation sectors for firmware engineers in southern German labor markets.
- Legacy retail inventory reconciliation:Traditional electronics chains maintain incompatible ERP systems that complicate real-time demand signaling for connected product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Small Home Appliance Market |
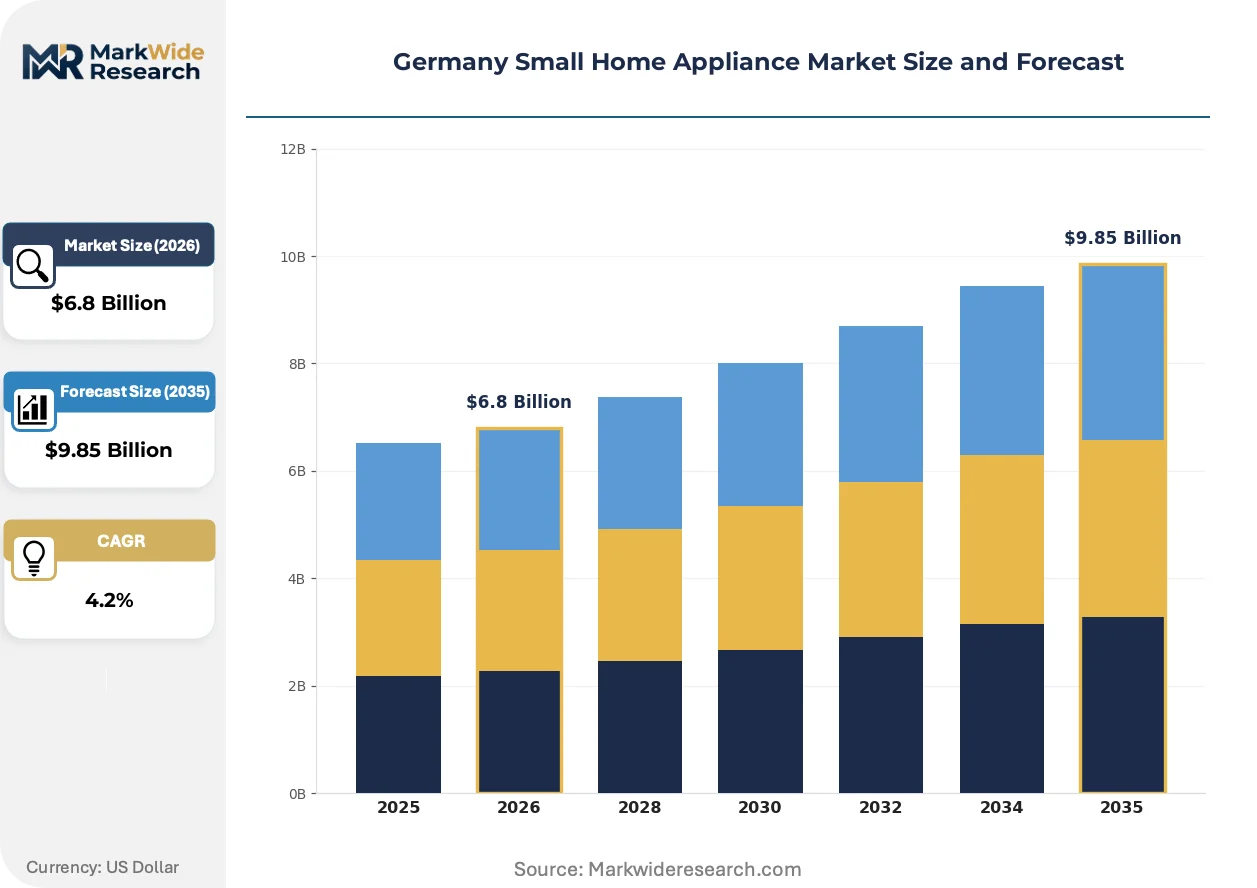
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee Makers, Blenders, Irons, Vacuum Cleaners, Toasters, Food Processors Technology: Cordless, Smart Connectivity, Steam-Based, Induction, Battery Operated, Touch Control Application: Cooking, Cleaning, Laundry Care, Food Preparation, Beverage Preparation, Personal Grooming End User: Households, Rental Apartments, Vacation Homes, Shared Living Spaces |
| Companies Covered | Gaggenau, Samsung Electronics GmbH, BSH Hausgeräte GmbH, Candy Hoover GmbH, Philips GmbH, Bauknecht Hausgeräte GmbH, AB Electrolux, Liebherr-Hausgeräte GmbH, C. Bomann GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Small Home Appliance Market Shifts & Advancements
Smart connectivity and cordless mobility are converging to redefine product architecture in German small home appliances. This dual transformation is compressing traditional category boundaries while opening new service revenue models.
Lithium-ion battery systems with higher energy density are integrating into vacuum cleaners and kitchen devices to enable cordless operation without performance sacrifice. Urban rental households in Berlin and Munich are adopting these formats fastest due to space constraints and frequent relocation patterns. This shift is integrating maneuverability and runtime into core purchasing criteria, displacing corded models in premium segments.
Germany's Federal Environment Agency is enforcing tightened Ecodesign requirements under EU framework directives that mandate minimum efficiency thresholds for motors and heating elements. Manufacturers must redesign core components to maintain market access, compressing development budgets for non-compliant product lines. Vacuum cleaners and espresso machines face the steepest redesign obligations under current implementation schedules.
Direct-to-consumer channel expansion is fragmenting traditional retail dependency for smart appliance brands. Younger urban buyers in Hamburg and Cologne are purchasing through manufacturer apps and specialized online platforms that offer subscription bundling. This pattern is most visible in coffee system and air purification categories where consumable replenishment creates recurring engagement opportunities.
Germany Small Home Appliance Market Segmentation
German small home appliance segmentation reveals how engineering specialization and regulatory pressure concentrate value in specific technical configurations. Product architecture choices in Stuttgart and Berlin manufacturing clusters directly shape competitive positioning across each dimension.
Product Type:
Supply concentration in western German industrial corridors favors manufacturers with captive motor and heating element production for high-volume categories.
- Coffee Makers:Built-in espresso systems and capsule machines dominate premium positioning, with demand concentrating in urban rental households across Berlin and Munich where compact countertop footprints are essential. BSH Hausgeräte leverages its Stuttgart engineering base to sustain margin pools in integrated coffee systems.
- Vacuum Cleaners:Cordless stick formats and robotic units are displacing corded canister models as lithium-ion energy density improvements enable runtime parity. Western industrial corridor suppliers with battery system integration capabilities capture expanding share in this transition.
- Blenders:Personal smoothie formats and high-speed kitchen systems serve food preparation demand in smaller urban kitchens.
- Irons:Steam-based garment care systems differentiate Philips GmbH offerings in fabric care categories.
- Toasters:Compact two-slice formats align with space constraints in rental apartment kitchens.
- Food Processors:Multi-function chopping and mixing systems address batch cooking trends in shared living arrangements.
Vacuum cleaners absorb the bulk of installed capacity; coffee makers are expanding most quickly through premium built-in system adoption.
Technology:
Cost tier differentiation separates premium engineering investments from commoditized feature sets across German manufacturing.
- Smart Connectivity:WiFi-enabled appliances with app control and predictive maintenance subscriptions create recurring revenue streams. Samsung Electronics GmbH anchors Berlin operations with connectivity integration that competes through usage analytics and consumable replenishment services.
- Cordless:Lithium-ion battery systems enable maneuverability without power sacrifice, with energy density improvements driving fastest adoption in vacuum cleaners and handheld kitchen devices. Urban rental households in Hamburg and Cologne prioritize these formats for relocation flexibility.
- Steam-Based:Specialized heating systems for garment care and cleaning applications command premium positioning outside standard resistive element categories.
- Induction:Precision heating technology transfers from built-in cooking appliances to small format specialty devices.
- Battery Operated:Primary cell and rechargeable formats serve low-power personal grooming and cleaning tools.
- Touch Control:Capacitive interfaces replace mechanical switches in premium product lines.
Cordless technology absorbs the bulk of installed capacity; smart connectivity is gaining share fastest through subscription revenue attachment.
Application:
Volume concentration in cooking and cleaning applications shapes component supplier relationships and retail channel placement.
- Cleaning:Vacuum cleaners and steam systems address floor care and surface sanitation demand across German household types.
- Cooking:Small heating appliances for food preparation serve compact kitchen configurations in urban rental markets.
- Food Preparation:Blenders, processors, and mixers enable meal batching behaviors in time-constrained professional households.
- Beverage Preparation:Coffee systems and electric kettles command highest per-unit margins in premium segments.
- Laundry Care:Irons and garment steamers serve fabric maintenance needs outside washing machine cycles.
- Personal Grooming:Hair care and hygiene devices operate in distinct regulatory and distribution channels.
Cleaning absorbs the bulk of installed capacity; beverage preparation is climbing the fastest through premium system upgrades.
End User:
Customer type segmentation maps directly to product form factor and portability requirements across German housing stock.
- Rental Apartments:Berlin and Munich urban renters drive demand for compact, lightweight appliances that relocate easily between residences. This segment prioritizes cordless formats and collapsible storage designs.
- Households:Owner-occupied single-family homes sustain demand for larger-capacity and built-in appliance formats with premium feature sets.
- Shared Living Spaces:Co-living arrangements and student housing create demand for durable, multi-user appliances with simplified interfaces.
- Vacation Homes:Secondary residences require intermittent-use appliances with storage efficiency and seasonal durability.
Households absorb the bulk of installed capacity; rental apartments are expanding most quickly through urban densification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors Germany's small home appliance engineering cluster, with Baden-Württemberg's industrial corridor hosting captive motor production and precision manufacturing for premium built-in systems. The western industrial belt concentrates value through proximity to automotive electronics suppliers and established testing infrastructure.
Bavaria
Munich's urban rental market drives demand for compact, energy-efficient coffee systems and cordless vacuum formats that relocate easily between apartments. The Federal Environment Agency enforces tightened Ecodesign requirements that compress development cycles for manufacturers operating in the region. Nuremberg's manufacturing base supplies precision heating elements to appliance assemblers serving southern German households.
North Rhine-Westphalia
Cologne and Düsseldorf housing markets prioritize space-efficient appliances with collapsible storage designs for rental kitchens. REACH compliance through ECHA shapes material selection for plastics in food-contact devices manufactured across the Ruhr industrial zone. Dortmund's logistics infrastructure supports distribution of cordless technology products to western German retail channels.
Baden-Württemberg
Stuttgart's engineering base sustains premium positioning in built-in coffee systems through captive motor and heating element production. KBA safety certifications for battery transport systems apply to cordless category expansion from regional manufacturers. The Neckar Valley industrial corridor integrates lithium-ion battery assembly with appliance final production.
Berlin-Brandenburg
Berlin's rental apartment concentration accelerates adoption of lightweight, maneuverable appliances suited to frequent relocation. The Federal Network Agency monitors electromagnetic compatibility standards for smart connectivity devices developed in the capital's technology cluster. Potsdam's research institutions collaborate with manufacturers on firmware engineering for connected appliance platforms.
Hamburg
The port city's direct-to-consumer channel expansion fragments traditional retail dependency for smart appliance brands targeting younger urban buyers. Ecodesign Directive implementation schedules mandate efficiency thresholds for small heating appliances distributed through northern German logistics hubs. Hamburg's trade fair infrastructure hosts product launches for beverage preparation systems with subscription bundling models.
Germany Small Home Appliance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and brand heritage dimensions, with engineering-capable suppliers capturing first-mover advantages from regulatory compression. The vendor base organizes into three strategic archetypes: Stuttgart-based engineering specialists with captive component production, Berlin-anchored connectivity integrators leveraging software talent pools, and diversified European conglomerates with multi-category portfolios. Dominant competitive moves include geographic concentration in western industrial corridors and strategic partnerships with automotive electronics suppliers seeking appliance diversification.
Among Germany-based engineering specialists, BSH Hausgeräte GmbH and Liebherr-Hausgeräte GmbH occupy positions defined by Baden-Württemberg manufacturing heritage and premium built-in system specialization. Samsung Electronics GmbH represents the connectivity-integrated archetype through its Berlin operations. Philips GmbH exemplifies technical differentiation in specialized garment care segments. These named entities anchor competitive positioning without exhaustively mapping market share or strategic initiatives.
| Leading Market Players |
|---|
| Gaggenau |
| Samsung Electronics GmbH |
| BSH Hausgeräte GmbH |
| Candy Hoover GmbH |
| Philips GmbH |
| Bauknecht Hausgeräte GmbH |
| AB Electrolux |
| Liebherr-Hausgeräte GmbH |
| C. Bomann GmbH |
| Others |
Supply & Pricing Matrix
Premium built-in system certification separates engineering-capable suppliers from commodity assemblers in Germany's small home appliance market, with this bifurcation manifesting in both value-based pricing power and captive component sourcing strategies. Stuttgart-based manufacturers with in-house motor production command margin pools unavailable to import-dependent competitors, while REACH compliance costs compress pricing flexibility across food-contact categories.
Pricing Analysis
Outcome-based pricing anchored to energy efficiency ratings dominates Germany's small home appliance market, with Ecodesign Directive tier thresholds creating discrete price bands for vacuum cleaners and coffee systems. Price differentiation rests on certification grade and brand heritage, with premium engineering suppliers capturing sustainable margins while commodity imports face downward pressure from private-label competition. Buyer price sensitivity concentrates in Berlin and Munich rental segments, whereas owner-occupied households in Baden-Württemberg exhibit lower elasticity for built-in formats.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion battery cells mandate multi-supplier qualification across German cordless appliance manufacturers, with procurement teams qualifying cells from China, South Korea, and Japan to mitigate concentration risk. Raw material dependencies center on rare earth elements for motor magnets, copper windings, and food-grade polymer resins subject to ECHA restrictions. Single-source vulnerability in precision heating element fabrication creates exposure for espresso machine assemblers. Distribution runs through western industrial corridor logistics hubs serving electronics retail chains and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's small home appliance market sits in a technology-transition phase as cordless lithium-ion systems displace corded legacy formats across vacuum and kitchen categories.
For Market Incumbents: Lock in captive supply of battery management systems and precision heating elements before automotive electronics suppliers divert component capacity. Secure KBA safety certification expertise as cordless category expansion accelerates. Defend margin position by deepening backward integration into motor production and preemptive compliance with forthcoming EU right-to-repair spare parts mandates. For New Entrants and Emerging Players: EU right-to-repair regulations in Germany open a window for independent service networks and refurbished appliance platforms. Target Berlin and Hamburg rental apartment segments with subscription-based cordless formats emphasizing relocation flexibility. Pursue direct-to-consumer launch with app-enabled maintenance bundling to bypass entrenched retail channel gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with engineering-capable mid-caps given Ecodesign Directive compliance advantages and automotive supplier diversification interest. Long-term viability favors Stuttgart-cluster manufacturers with captive component production and established Federal Environment Agency relationships. Monitor KBA certification backlog as inflection indicator for cordless category expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery System Integration | Lithium-ion cell qualification with KBA transport certification unlocks cordless category expansion. |
| Smart Connectivity Platform | WiFi-enabled predictive maintenance creates recurring revenue attachment for Berlin-developed appliances. |
| Direct-to-Consumer Channel | Manufacturer app sales bypass legacy retail ERP fragmentation in Hamburg and Cologne markets. |
| Ecodesign Compliance Investment | Stuttgart engineering resources sustain premium positioning as Federal Environment Agency tightens thresholds. |
| Spare Parts Availability System | Preemptive inventory positioning ahead of EU right-to-repair implementation secures aftermarket revenue. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with product development directors at western German appliance manufacturers, procurement leads at lithium-ion cell distributors, Federal Environment Agency compliance officers, and category buyers at electronics retail chains. Secondary sources included ECHA substance restriction databases, KBA battery safety certification registers, Federal Network Agency electromagnetic compatibility filings, and Baden-Württemberg industrial production statistics. Bottom-up segment sizing triangulated against top-down market value estimates.
Granularity-level modeling operated at product type, technology configuration, and end-user archetype dimensions, with separate run-rate assumptions for cordless adoption curves and smart connectivity penetration across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution. Industry-specific forecast inputs incorporated Ecodesign Directive implementation schedules and lithium-ion energy density improvement curves from automotive battery research.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for cordless category expansion timelines. Forecasts reflect assumptions regarding regulatory enforcement consistency and automotive supplier diversification interest. Deviation in EU right-to-repair implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
US Household Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
India Major Home Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
White Goods Market