
 Asia-Pacific Small Home Appliances Market | 2026-2036
Asia-Pacific Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Small Home Appliances Market Outlook
Buyer fragmentation across Asia-Pacific's urban middle class is realigning procurement patterns for small home appliances. Haier Smart Home Co., Ltd. leverages its captive manufacturing base to dominate domestic Chinese distribution. Panasonic Corporation anchors its regional position through deep specialization in precision heating technologies. Samsung Electronics competes aggressively on connected-kitchen ecosystems across South Korean and Indian metro markets.
Asia-Pacific small home appliances comprise compact electromechanical devices designed for domestic food preparation, heating, and beverage processing, typically operating at voltages between 110-240V with power ratings under 2,000W for countertop deployment. Microwave ovens command the largest installed base among cooking appliances, while coffee makers represent the fastest-expanding category as café culture penetrates Indonesian and Vietnamese cities. Online retail channels now capture the dominant share of first-time purchases, though specialty stores retain margin concentration for premium and luxury price tiers where tactile evaluation drives conversion.
China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility, while India's BIS mandates energy-labeling compliance before market entry. Japan's METI administers Top Runner efficiency standards that progressively tighten allowable power consumption for blenders and toasters. Stakeholders must monitor how Australia's E3 program and South Korea's MEPS framework synchronize with these regimes, as regulatory divergence threatens to fragment product portfolios and inflate compliance costs across the region.
Market Dynamics
India's BIS energy-efficiency mandates are compressing product development cycles across the Asia-Pacific small home appliances sector, forcing manufacturers to redesign heating elements and motor assemblies before market entry.
Growth Catalysts
- Urban household expansion:Southeast Asian metro areas are absorbing automated kitchen devices as apartment dwellers prioritize space-efficient food preparation tools.
- China's dual carbon goals:MEE efficiency benchmarks are accelerating inverter motor adoption in blenders and rice cookers, creating upgrade demand.
- Indonesian café culture penetration:Specialty coffee preparation is driving espresso machine volumes in Jakarta and Surabaya retail channels.
Market Restraints
- Copper and rare-earth price volatility:Electric motor windings and magnet materials face input cost swings that compress assembly margins.
- Guangdong supply concentration:Component sourcing clusters around Shenzhen and Dongguan expose procurement to regional logistics disruptions.
- Japan's Top Runner efficiency ceilings:METI's progressively tightening standards for toasters and kettles demand R&D outlays that smaller OEMs cannot absorb.
Strategic Opportunities
- Vietnamese secondary cities:Da Nang and Can Tho remain undersupplied with premium small appliances relative to Ho Chi Minh City saturation.
- Voice-activated cooking interfaces:Integration of AI assistants with induction cooktops creates differentiation in South Korean smart home ecosystems.
- Australia's E3 program alignment:Harmonized efficiency labeling with New Zealand opens streamlined certification pathways for regional product launches.
Industry Challenges
- Embedded systems firmware talent:Connected appliance development requires software engineers scarce in traditional hardware manufacturing bases.
- Multi-jurisdiction certification timelines:Sequential BIS, GB, and PSE approvals delay India-China-Japan product rollouts by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Small Home Appliances Market |
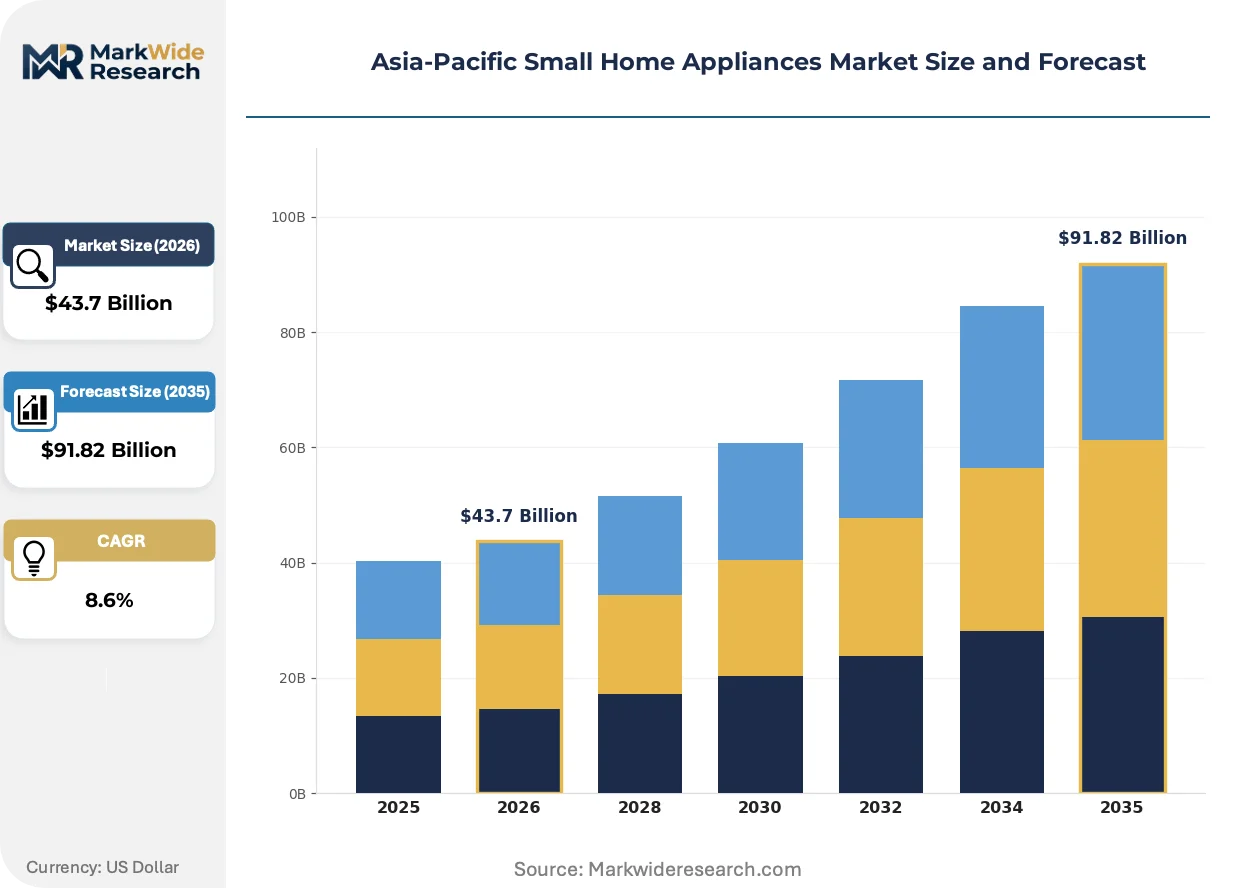
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $91.82 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Toasters, Coffee Makers, Microwave Ovens End User: Households, Hospitality, Office Use, Restaurants Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Discount Stores Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Philips, Haier Smart Home Co., Ltd., Panasonic Corporation, LG Electronics, BSH Hausgeräte GmbH, Midea Group, AB Electrolux, Sharp Corporation, Samsung Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Small Home Appliances Market Strategic Shifts
Connected kitchen ecosystems are rewiring how Asia-Pacific households interact with countertop appliances, shifting value capture from hardware margins to recurring software and consumable revenue streams.
Induction heating modules are overtaking resistive coil systems in premium rice cookers and water boilers. Japanese and South Korean buyers are specifying these units for temperature precision and energy recovery. The technology is compressing warranty claim rates while elevating average selling prices in metro retail.
China's SAMR is enforcing stricter GB standards for electromagnetic compatibility in wireless-enabled appliances. Manufacturers must redesign RF shielding and retest product portfolios before domestic distribution. Connected coffee makers and smart kettles face the steepest compliance recertification burdens.
Appliance-as-a-service pilots are emerging in Australian and Singaporean property management verticals. Landlords bundle countertop devices into rental packages, displacing individual ownership for transient urban professionals. Sydney and Melbourne high-density developments are the primary testbeds for this procurement model.
Asia-Pacific Small Home Appliances Market Segmentation
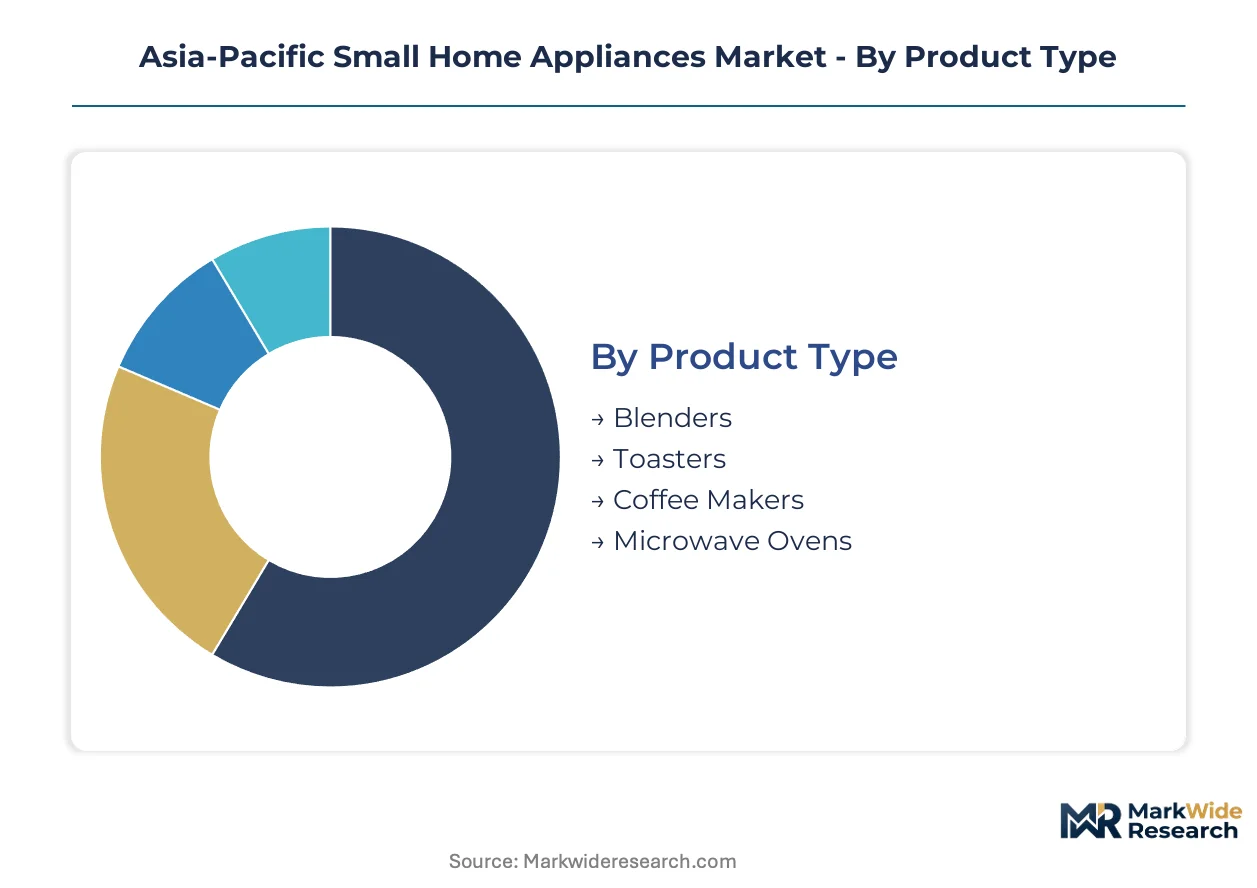
Segmentation in Asia-Pacific small home appliances reveals how procurement priorities diverge across urban middle-class households, institutional foodservice operators, and digitally native retail channels. Understanding these splits exposes where margin pools concentrate and which specifications command pricing power across tiered city markets.
Product Type:
Technical sophistication and countertop footprint drive replacement cycles differently across cooking and beverage preparation categories.
- Microwave Ovens:These 700-1200W cavity appliances with rotating turntable or flatbed configurations dominate apartment kitchens across Chinese tier-one cities where space constraints eliminate full-size oven installations. India's BIS energy-labeling mandates are forcing magnetron efficiency redesigns before import clearance.
- Coffee Makers:Espresso pump machines and automated bean-to-cup systems are penetrating Jakarta and Surabaya hospitality channels as Indonesian café culture matures beyond instant coffee consumption. Specialty roasters in Vietnamese cities are specifying dual-boiler temperature stability for commercial deployment.
- Blenders:High-speed motor assemblies with stainless-steel blade clusters serve smoothie preparation in Australian health-conscious households and South Korean protein-shake consumption patterns.
- Toasters:Pop-up and conveyor configurations with quartz or metal-sheath heating elements concentrate in Japanese residential markets where METI Top Runner standards progressively tighten allowable wattage per slice.
Microwave ovens lead volumes today; coffee makers are gaining share fastest.
End User:
Purchase frequency and specification tolerance separate domestic buyers from commercial operators who prioritize duty-cycle durability over upfront cost.
- Households:Individual consumers in Chinese and Indian metro areas select 1-2 liter capacity appliances for 2-4 person nuclear families, with connected features increasingly specified in Seoul and Tokyo smart-home ecosystems. Replacement cycles extend 5-7 years for core cooking devices.
- Hospitality:Hotels across Bangkok, Singapore, and Sydney outfit guest rooms with compact kettles and single-serve coffee systems where failure rates drive procurement toward extended-warranty suppliers.
- Restaurants:Quick-service operators in Ho Chi Minh City and Manila demand commercial-grade motor assemblies with continuous-run thermal protection for high-throughput beverage preparation.
- Office Use:Corporate pantries in Australian CBD towers and Indian tech parks specify pod-based coffee systems and electric kettles with boil-dry safety cutoffs for unattended operation.
Households absorb the largest unit volumes; hospitality channels are expanding most quickly as tourism recovery accelerates replacement schedules.
Distribution Channel:
Channel selection determines whether buyers prioritize tactile evaluation, price transparency, or immediate fulfillment speed.
- Online Retail:E-commerce platforms capture first-time appliance purchases across Chinese and Indian markets where smartphone penetration enables comparison shopping. Return logistics complexity limits this channel for bulky microwave ovens relative to compact blenders.
- Specialty Stores:Dedicated appliance retailers in Tokyo's Akihabara and Seoul's Yongsan Electronics Market command premium pricing through demonstration-based conversion for espresso machines and induction cooktops.
- Hypermarkets:Big-box formats in Australian suburbs and Malaysian urban peripheries aggregate mid-range inventory for planned replacement purchases with parking-accessible bulk carrying capacity.
- Discount Stores:Hard-discount channels in Indonesian secondary cities and Philippine provincial centers move private-label toasters and kettles on price-driven impulse.
Online retail leads transaction volumes today; specialty stores are climbing the fastest as premium appliance makers invest flagship footprint.
Price Tier:
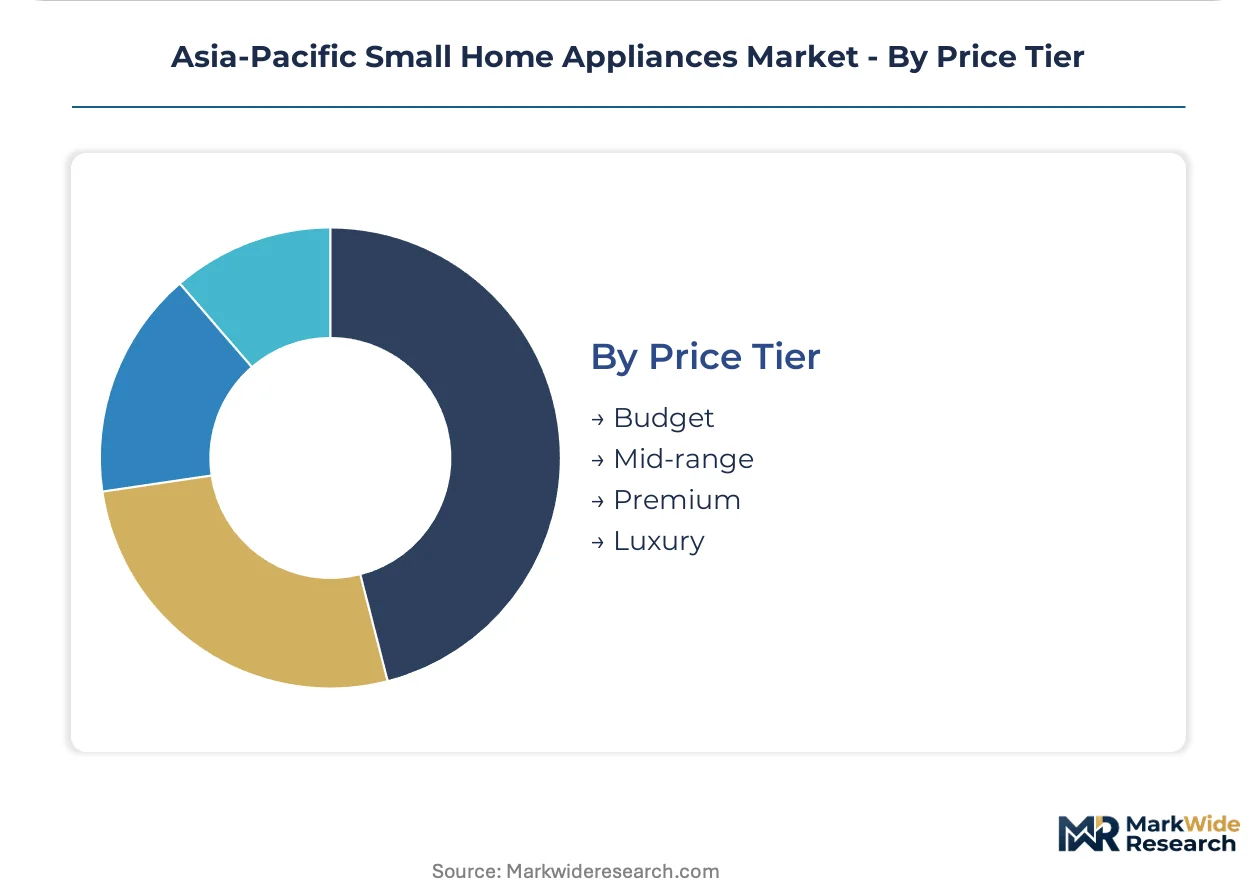
Certification grade and materials specification separate tiers more than core functionality, with efficiency labeling creating visible differentiation.
- Budget:Basic resistive-heating appliances with plastic housings and minimal safety interlocks dominate rural Indian and Indonesian markets where electrification rates are still expanding addressable demand.
- Mid-range:Stainless-steel finishes and inverter motor technology capture urban Chinese and Vietnamese households upgrading from entry-level replacements. India's BIS star-rating visibility drives selection at this tier.
- Premium:Connected features, induction heating modules, and voice-assistant compatibility concentrate in Japanese and South Korean markets where METI and MEPS efficiency benchmarks justify price elevation.
- Luxury:Design-house collaborations and commercial-grade componentry serve high-net-worth households in Singapore, Sydney, and Mumbai luxury residential towers where kitchen aesthetics signal status.
Mid-range pricing captures the largest revenue pool today; premium tier is expanding most quickly as efficiency mandates and smart-home integration reshape upgrade preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs larger appliance volumes than India, though India's regulatory velocity now outpaces its northern neighbor. Southeast Asian metros are expanding faster than mature Northeast Asian markets. Regulatory fragmentation across BIS, GB, and METI regimes complicates multi-country product launches.
China
Urban households in Shanghai, Beijing, and Shenzhen are replacing basic rice cookers with induction-heating models featuring connected interfaces. SAMR enforces stricter GB standards for electromagnetic compatibility in wireless-enabled appliances. Manufacturing clusters around Shenzhen and Dongguan dominate component sourcing for regional supply chains.
India
Tier-one cities including Mumbai, Delhi-NCR, and Bengaluru are driving microwave and blender upgrades as nuclear families expand. BIS energy-efficiency mandates now require star-labeling compliance before import clearance, compressing product development cycles. Component suppliers in Pune and Chennai are scaling inverter motor production for domestic assembly.
Japan
Tokyo and Osaka metros specify premium toasters and kettles with precision temperature control. METI's Top Runner efficiency standards progressively tighten allowable wattage per slice, forcing redesigns of heating elements. Manufacturing bases in Chubu and Kansai regions concentrate precision heating technology expertise.
South Korea
Seoul Capital Area households are integrating voice-activated cooking interfaces with smart home ecosystems. MEPS frameworks regulate standby power consumption for countertop appliances. Busan-Ulsan industrial corridors supply high-efficiency motor assemblies for domestic and export markets.
Australia
Sydney and Melbourne property managers are piloting appliance-as-a-service models in high-density rental developments. The E3 program aligns efficiency labeling with New Zealand, streamlining trans-Tasman certification pathways. Distribution networks concentrate in eastern seaboard population corridors.
Asia-Pacific Small Home Appliances Market Competitive Environment
Chinese producers anchor one tier; Japanese and South Korean specialists hold differentiated positions in precision heating and connected ecosystems. The vendor base fragments across captive manufacturing conglomerates, contract assemblers, and design-house brands. Three archetypes dominate: vertically integrated home-appliance conglomerates with captive component production; precision-technology specialists leveraging heating and motor expertise; and ecosystem players bundling hardware with software services. Capacity expansion in Vietnamese assembly plants and strategic partnerships for voice-interface licensing represent the dominant competitive vectors.
Among Chinese fabricators, Haier Smart Home Co., Ltd. and Midea Group exemplify the vertically integrated archetype with captive manufacturing bases. Panasonic Corporation and Samsung Electronics occupy differentiated positions—Panasonic through deep specialization in precision heating, Samsung through connected-kitchen ecosystem integration. These three companies represent how geographic origin and structural focus map to competitive positioning across the region's tiered demand.
| Leading Market Players |
|---|
| Philips |
| Haier Smart Home Co., Ltd. |
| Panasonic Corporation |
| LG Electronics |
| BSH Hausgeräte GmbH |
| Midea Group |
| AB Electrolux |
| Sharp Corporation |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
India's BIS energy-efficiency mandates are forcing manufacturers to redesign heating elements and motor assemblies before market entry, compelling supply base adjustments that elevate component costs and compress assembly margins across the region.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for mid-range small appliances as regional assembly plants absorb labor-intensive production from Chinese coastal zones. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and efficiency labeling visibility, with BIS star-rating compliance commanding measurable premiums. Price erosion runs through economy tiers as private-label entrants from Indonesian discount channels undercut branded equivalents. Hospitality buyers exhibit lowest price sensitivity due to failure-rate-driven procurement toward extended-warranty suppliers, while rural Indian households remain most responsive to upfront cost.
Supply Chain Analysis
Certification timelines for BIS, GB, and PSE approvals are gating component sourcing decisions and extending inventory planning horizons for multi-country product launches. Manufacturing concentrates in China, Vietnam, and India, with Guangdong province anchoring precision motor and heating element production. Copper windings and rare-earth magnet materials draw from concentrated mining jurisdictions, exposing assemblers to commodity price volatility. Single-source vulnerability around Shenzhen-Dongguan component clusters threatens regional logistics continuity. Distribution runs through e-commerce platforms for first-time purchases, with specialty retailers retaining premium-tier conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia-Pacific small home appliances rests on inverter motor cost curves flattening and premium-tier penetration accelerating in Japanese and South Korean smart-home ecosystems.
For Market Incumbents: Anchor defensive positioning through captive production of inverter motor assemblies in Vietnamese facilities, offsetting margin compression from copper and rare-earth input volatility. Deepen backward integration into precision heating module production to preserve differentiation against contract assemblers. Prioritize GB standard pre-certification for connected appliance portfolios ahead of SAMR enforcement waves. For New Entrants and Emerging Players: The premium-to-economy price gap in Vietnamese secondary cities—Da Nang, Can Tho—offers white-space entry below Ho Chi Minh City saturation levels. Voice-activated cooking interfaces remain underspecified in Indonesian and Philippine markets relative to South Korean deployment. Pursue hospitality channel partnerships with Bangkok and Sydney hotel operators seeking extended-warranty suppliers for guest room appliance refreshes. For Investors and Strategic Acquirers: Asymmetric upside sits with precision heating technology specialists possessing METI Top Runner pre-certified product pipelines. Long-term viability over the coming decade favors manufacturers with software engineering capabilities embedded in hardware development cycles. Monitor BIS certification backlog durations as inflection indicator for India market access friction and domestic assembly investment triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Heating Module Integration | Japanese and South Korean buyers specify these units for temperature precision and energy recovery. |
| Vietnamese Assembly Capacity Expansion | Regional plants absorb labor-intensive production from Chinese coastal manufacturing zones. |
| Voice-Assistant Platform Partnership | Seoul Capital Area households integrate AI cooking interfaces with smart home ecosystems. |
| Appliance-as-a-Service Pilot Launch | Sydney and Melbourne property managers bundle countertop devices into rental packages. |
| BIS Pre-Certification Investment | Star-labeling compliance accelerates India import clearance and compresses product cycles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with product development executives at appliance manufacturers, regulatory affairs leads navigating BIS and SAMR frameworks, category buyers at Australian hypermarket chains, and procurement managers at Bangkok hospitality operators. Secondary validation drew from SAMR GB standard filings, BIS energy-labeling registries, METI Top Runner efficiency databases, and customs records tracking component flows through Guangdong ports. Bottom-up unit shipment estimates triangulated against top-down consumer expenditure data across the analysis window.
Historical reference periods anchored volume and value projections over the projection horizon, with segmentation modeling across product type, end user, distribution channel, and price tier dimensions. CAGRs derived from fitted growth curves incorporating urban household formation rates, electrification expansion in rural India and Indonesia, and efficiency mandate implementation schedules. Industry-specific inputs included inverter motor adoption trajectories and connected appliance penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for induction heating module cost reduction would alter the outlook. Forecasts reflect stated assumptions regarding regulatory synchronization across BIS, GB, and METI regimes, with commodity price volatility and logistics disruption representing primary revision triggers. A model refresh is warranted upon material change in rare-earth supply chain configuration or voice-interface platform consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Slovakia Home Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
Refrigerator Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Household Appliance Market
Home Appliances
China Laundry Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
US Household Appliances Market