
 Europe and MENA Pulp Market | 2026-2036
Europe and MENA Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and MENA Pulp Market Foresight
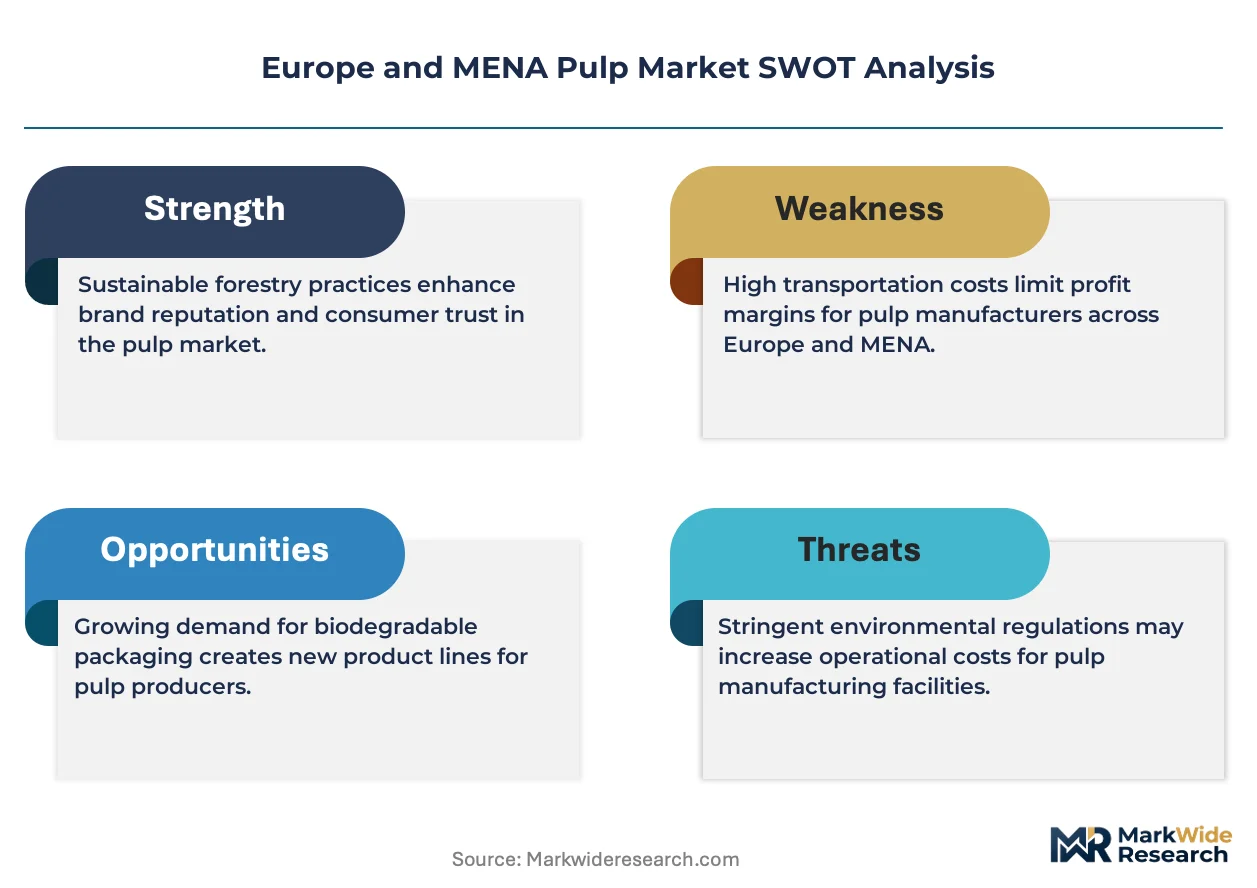
High-alpha cellulose specifications are redrawing procurement priorities among European specialty paper producers. Stora Enso leverages its Nordic softwood fiber base to sustain premium dissolving pulp output for textile applications. Sappi Limited anchors South African hardwood supply into MENA printing and writing segments through its trading arm. Mondi PLC competes on integrated packaging-grade pulp across Central European corrugated board networks.
Europe and MENA pulp encompasses mechanically or chemically processed lignocellulosic fiber derived from softwood, hardwood, or recycled sources, typically refined to 85-95% cellulose content for subsequent paper, board, or textile applications. Bleached pulp commands premium positioning among pharmaceutical and food-contact paper producers seeking low-extractable purity, while unbleached pulp dominates kraft linerboard feedstocks where burst strength metrics outweigh brightness requirements. Specialty pulp isolates margin pools in filter papers, battery separators, and nonwoven hygiene substrates where technical specifications supersede commodity pricing. Recycled pulp faces structural constraints in MENA due to limited post-consumer collection infrastructure relative to European circular economy frameworks.
EMA, REACH, and F-Gas Regulation shape European pulp chemistry and effluent standards, while Saudi Arabia's Saudi Standards, Metrology and Quality Organization and Turkey's Ministry of Environment enforce localized wastewater and air emission thresholds for integrated mills. The EU Deforestation Regulation requires geolocation traceability for virgin fiber entering European conversion facilities, elevating certified chain-of-custody documentation from pulp suppliers serving Nordic and German paper groups. Stakeholders must monitor divergence between EU carbon border adjustment mechanisms and MENA national industrial strategies as they calibrate capital allocation across bleached, unbleached, and specialty grade capacity additions.
Market Dynamics
The EU Deforestation Regulation's geolocation traceability mandate is compressing certified fiber sourcing timelines, forcing packaging converters and specialty paper producers to requalify virgin pulp suppliers ahead of compliance deadlines.
Growth Catalysts
- E-commerce fulfillment expansion:German and UAE packaging converters are scaling bleached kraft pulp offtake to serve corrugated demand from fulfillment center construction.
- EU Green Deal mandates:Deforestation-free supply chain requirements are accelerating certified chain-of-custody documentation adoption among Nordic pulp suppliers.
- High-alpha cellulose specifications:Textile sector dissolving pulp demand is pulling premium fiber grades from Nordic softwood operations into European specialty paper networks.
Market Restraints
- Post-consumer collection infrastructure gaps:MENA recycled pulp faces structural constraints from limited municipal recovery systems relative to European circular economy frameworks.
- Energy input cost volatility:Integrated mills across Central Europe face margin compression from natural gas and electricity price swings affecting chemical pulping economics.
- Hardwood supply concentration:South African hardwood fiber routes into MENA printing and writing segments create geographic dependency risk for regional converters.
Strategic Opportunities
- Turkey's Izmir industrial corridor:Integrated paperboard mill clusters anchor underexploited regional pulp consumption growth for bleached packaging grades.
- Battery separator substrates:Technical specialty pulp isolates margin pools in energy storage applications where purity specifications exceed commodity pricing benchmarks.
- Saudi Standards alignment:Wastewater and air emission threshold harmonization creates regulatory tailwind for capital-efficient mill technology transfers into Kingdom-based operations.
Industry Challenges
- Certification timeline compression:EU Deforestation Regulation geolocation documentation requirements strain supplier qualification bandwidth ahead of enforcement windows.
- REACH compliance complexity:Chemical pulping effluent standards demand continuous adaptation of bleaching sequences and closed-loop water systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and MENA Pulp Market |
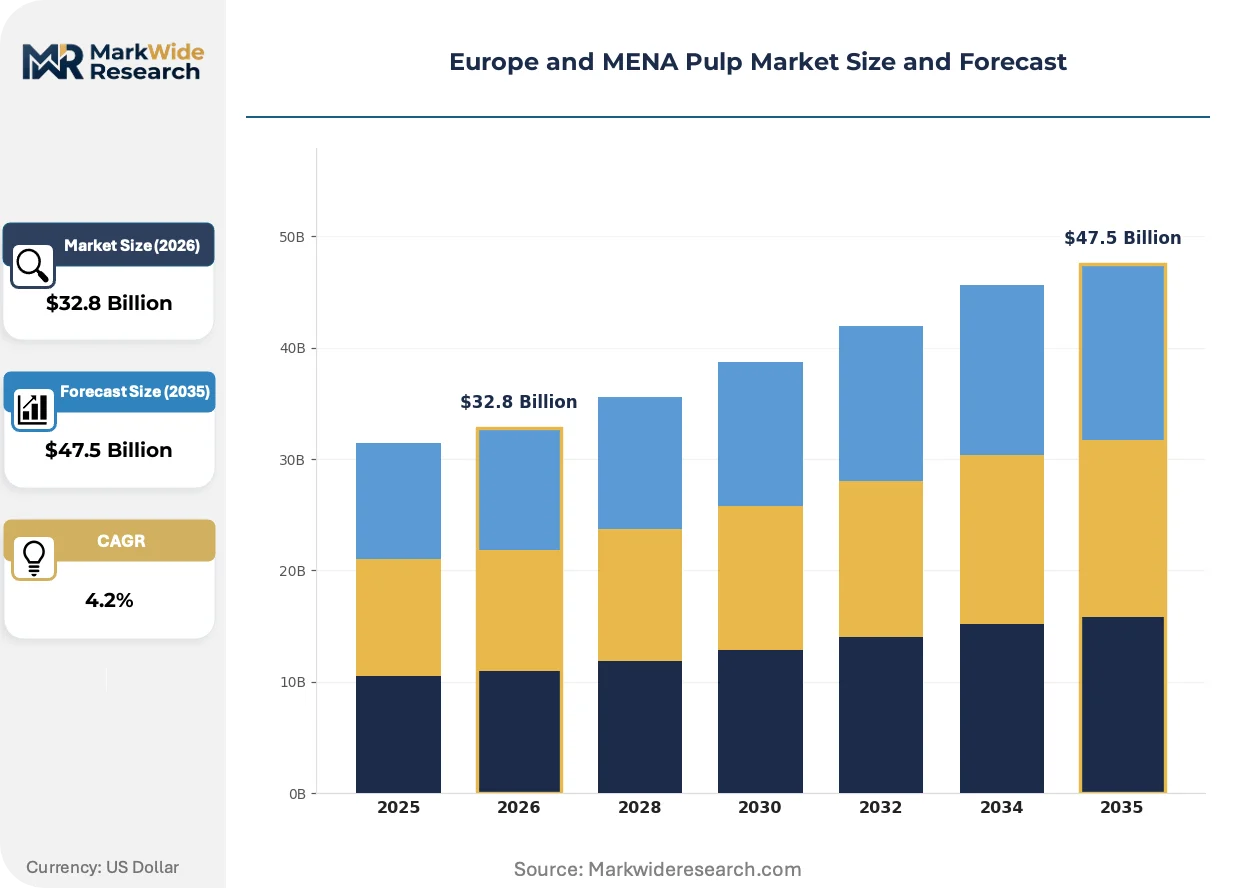
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Pulp, Unbleached Pulp, Recycled Pulp, Specialty Pulp End User: Paper Manufacturers, Packaging Industry, Textiles, Construction Grade: Food Grade, Industrial Grade, Specialty Grade, Recycled Grade Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Atrak Pulp and Paper Industries, Middle East Paper Company (MEPCO), Stora Enso, UPM, SCA, Obeikan Paper Industries Co, Saudi Paper Manufacturing Co, Sappi Limited, Mondi PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and MENA Pulp Market Shifts & Advancements
Mechanical and chemical pulping technologies are diverging in capital allocation, with sustainability-linked financing favoring closed-loop systems while legacy assets face stranded-cost risk from tightening emission thresholds.
Oxygen-delignification sequences are fragmenting traditional chlorine-based bleaching infrastructure. Pharmaceutical and food-contact paper producers are adopting these low-extractable purity systems at accelerated procurement cycles. The technology is fragmenting established supplier hierarchies by enabling smaller Nordic mills to meet premium brightness specifications without multi-stage chemical investments.
REACH and F-Gas Regulation are tightening effluent chemistry standards across European integrated mills. These mandates are forcing capital redeployment into closed-loop water recovery and alternative bleaching agent portfolios. Bleached kraft producers serving German pharmaceutical packaging segments are most affected, with several operations accelerating TCF and ECF sequence conversions to maintain market access.
Buyer concentration among e-commerce fulfillment networks is compressing procurement cycles for packaging-grade pulp. Corrugated board converters are consolidating supplier panels and demanding just-in-time fiber delivery contracts that displace traditional quarterly volume commitments. This pattern is most visible in Germany's Rhine-Ruhr logistics corridor and the UAE's Jebel Ali free zone fulfillment clusters.
Europe and MENA Pulp Market Segmentation
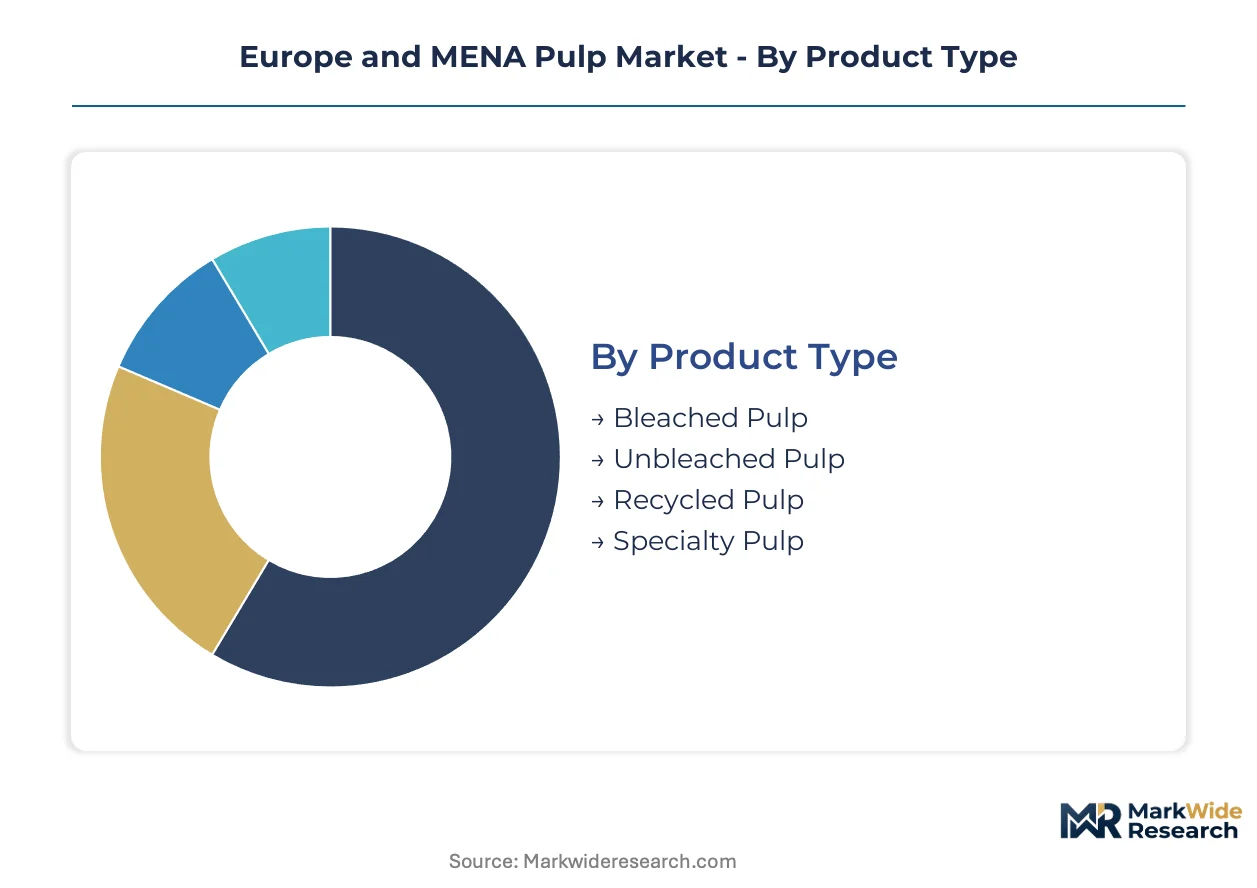
Pulp market segmentation reveals where value migrates across fiber processing tiers. Technical specifications, end-use purity requirements, and channel economics fragment procurement patterns across European and MENA conversion networks.
Product Type:
Bleached pulp commands the widest margin spread, while specialty grades isolate premium pools in technical applications.
- Bleached Pulp:Chemically processed to 90%+ brightness with multi-stage delignification sequences. German pharmaceutical packaging converters and UAE food-contact paper producers anchor offtake volumes as EU Deforestation Regulation compliance tightens certified fiber documentation requirements.
- Specialty Pulp:High-alpha cellulose isolates exceeding 95% purity for battery separators, filter media, and nonwoven hygiene substrates. Nordic softwood operations supply textile dissolving pulp into European specialty paper networks where technical specifications override commodity pricing benchmarks.
- Unbleached Pulp:Retains lignin content for burst strength in kraft linerboard feedstocks. Turkey's Izmir industrial corridor consumes substantial volumes for integrated corrugated board production.
- Recycled Pulp:Post-consumer fiber recovery faces structural constraints across MENA due to limited municipal collection infrastructure relative to European circular economy frameworks.
Bleached pulp holds installed capacity. Specialty pulp is rotating up the share rankings.
End User:
Application-driven demand concentrates in packaging fulfillment networks and technical textile feedstocks.
- Packaging Industry:E-commerce fulfillment center construction across Germany's Rhine-Ruhr corridor and UAE's Jebel Ali free zone compresses procurement cycles. Corrugated board converters consolidate supplier panels and mandate just-in-time fiber delivery contracts displacing traditional quarterly commitments.
- Textiles:Dissolving pulp for viscose and lyocell fiber production pulls premium softwood grades from Nordic operations. Stora Enso leverages its Finnish and Swedish fiber base to sustain high-alpha cellulose output for textile applications.
- Paper Manufacturers:Printing and writing segments depend on South African hardwood supply routes through Sappi Limited's trading arm into MENA markets.
- Construction:Fiber cement and gypsum board applications consume unbleached kraft pulp for dimensional stability in building materials.
Packaging Industry leads volume absorption. Textiles is climbing the fastest on value per ton metrics.
Grade:
Regulatory purity thresholds stratify procurement across food-contact, pharmaceutical, and industrial applications.
- Food Grade:Low-extractable bleached pulp meeting EFSA migration limits for direct food contact. REACH and F-Gas Regulation compliance drives TCF and ECF sequence conversions among German producers.
- Specialty Grade:Technical specifications for battery separators and pharmaceutical filtration media where purity exceeds commodity benchmarks.
- Industrial Grade:Standard brightness pulp for construction and non-food packaging applications with less stringent chemical residue limits.
- Recycled Grade:Post-consumer fiber streams constrained by collection infrastructure gaps across Saudi Arabia and UAE relative to European recovery systems.
Food Grade maintains certification complexity barriers. Specialty Grade is gaining share fastest on margin expansion.
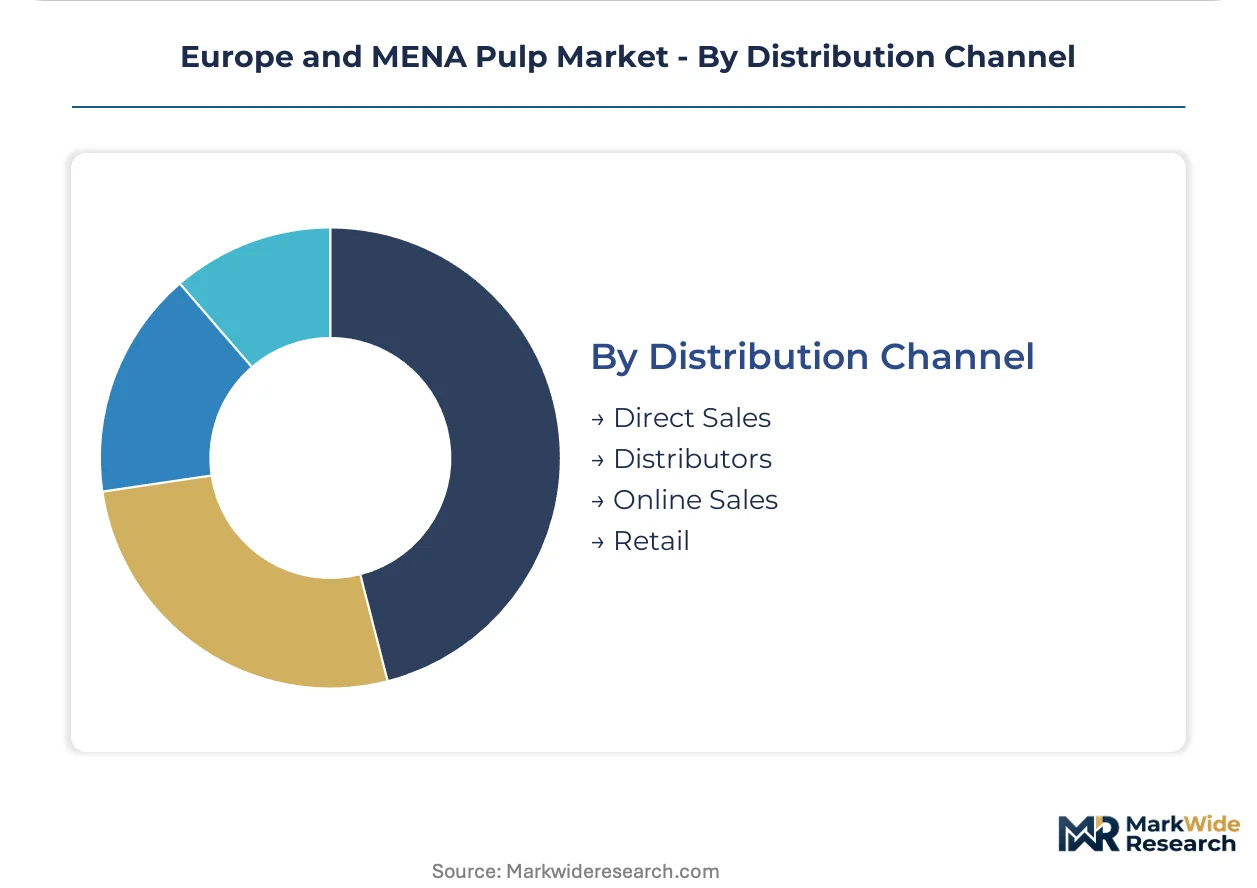
Distribution Channel:
Channel economics shift with buyer consolidation and fulfillment velocity requirements.
- Direct Sales:Mill-to-converter contracts dominate high-volume bleached pulp offtake from Nordic suppliers to German and Turkish integrated paperboard operations.
- Distributors:Regional trading arms aggregate smaller lot sizes for MENA printing and writing segments, particularly South African hardwood routes through Dubai trading hubs.
- Online Sales:Digital procurement platforms emerge for standardized recycled pulp grades in European markets with established chain-of-custody documentation.
- Retail:Limited to specialty craft and artistic paper pulp in consumer-facing channels with minimal industrial volume.
Direct Sales holds contract value concentration. Distributors is rotating up the share rankings on MENA geographic coverage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters in Germany and the UAE exhibit low price elasticity as e-commerce fulfillment demands tighten supply security priorities, while Turkish and Saudi buyers remain more sensitive to fiber cost swings amid currency volatility and import dependency.
Germany
Rhine-Ruhr logistics corridor anchors corrugated board demand from fulfillment center construction, compressing procurement cycles for bleached kraft pulp. REACH and F-Gas Regulation enforce closed-loop water recovery mandates on integrated mills. Bavarian pharmaceutical packaging producers accelerate TCF and ECF sequence conversions to maintain EU Deforestation Regulation compliance.
United Arab Emirates
Jebel Ali free zone fulfillment clusters drive just-in-time fiber delivery contracts displacing traditional quarterly commitments. MOHAP and Emirates Authority for Standardization enforce food-contact material migration limits. Dubai trading hubs aggregate South African hardwood pulp routes for MENA printing and writing segments.
Turkey
Izmir industrial corridor concentrates integrated paperboard mill demand for bleached packaging grades. The Ministry of Environment enforces wastewater and air emission thresholds tightening chemical pulping economics. Istanbul-based converters face margin pressure from lira depreciation against dollar-denominated Nordic pulp contracts.
Saudi Arabia
Domestic packaging demand rises from logistics infrastructure expansion and local manufacturing initiatives. Saudi Standards, Metrology and Quality Organization aligns wastewater regulations with European benchmarks, enabling technology transfer into Kingdom-based operations. Jeddah and Dammam industrial zones attract bleached pulp capacity targeting regional food-contact paper segments.
Finland
Nordic softwood fiber base sustains premium dissolving pulp output for European textile applications. EU Green Deal deforestation-free mandates elevate certified chain-of-custody documentation requirements. Stora Enso and UPM anchor high-alpha cellulose supply into specialty paper networks where technical specifications override commodity pricing.
Europe and MENA Pulp Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe and MENA pulp market. Nordic integrated producers dominate high-alpha cellulose and specialty grades through captive softwood fiber bases, while MENA regional mills compete on packaging-grade scale and geographic proximity to Gulf demand centers. Three archetypes define competitive positioning: Nordic specialty-grade specialists with certified fiber dominance, South African hardwood suppliers serving MENA printing and writing channels, and emerging Turkish-Saudi integrated packaging producers. Consolidation through mill acquisitions and backward integration into plantation forestry represent the dominant competitive moves.
Among Nordic-based integrated producers, Stora Enso and UPM exemplify technology-led positioning through dissolving pulp and specialty cellulose output. Sappi Limited anchors South African hardwood supply into MENA markets through trading arm structures. These three companies occupy distinct archetype positions—Stora Enso and UPM represent premium-grade fiber technology, while Sappi exemplifies geographic arbitrage between Southern Hemisphere fiber costs and Middle Eastern demand growth.
| Leading Market Players |
|---|
| Atrak Pulp and Paper Industries |
| Middle East Paper Company (MEPCO) |
| Stora Enso |
| UPM |
| SCA |
| Obeikan Paper Industries Co |
| Saudi Paper Manufacturing Co |
| Sappi Limited |
| Mondi PLC |
| Others |
Supply & Pricing Matrix
EU Deforestation Regulation geolocation traceability mandates gate both supplier qualification timelines and price differentiation across bleached kraft tiers. Certification documentation burdens compress procurement bandwidth while amplifying premiums for chain-of-custody-verified Nordic fiber.
Pricing Analysis
After-sales service contracts and technical support bundling drive lifetime value differentiation among specialty pulp suppliers. Contract-based long-term offtake dominates bleached kraft procurement from Nordic mills to German packaging converters, with price differentiation anchored in FSC certification tier and volume scale commitments. Cost compression in standard-grade unbleached pulp is intensifying because Turkish lira depreciation against dollar-denominated contracts squeezes Izmir corridor converters. E-commerce fulfillment networks exhibit lowest price sensitivity, while MENA printing and writing segments remain most exposed to hardwood fiber cost swings.
Supply Chain Analysis
Baltic Sea port congestion and Red Sea transit disruptions periodically choke Nordic-to-MENA fiber flows. Supply concentrates in Finland, Sweden, and South Africa as primary virgin pulp sources, with raw material dependencies on softwood roundwood, hardwood chips, and sulfur-based pulping chemicals. Single-source vulnerability runs through South African hardwood routes serving Gulf printing segments. Distribution runs through mill-direct contracts for high-volume German buyers and Dubai trading hubs aggregating smaller MENA lots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified fiber documentation expertise has become the scarce capability separating viable suppliers from disqualified sources. Mills lacking chain-of-custody infrastructure face accelerated exclusion from EU-compliant buyer panels.
For Market Incumbents: Secure FSC and PEFC certification coverage across all Nordic softwood supply basins before EU Deforestation Regulation enforcement windows close. Deepen backward integration into plantation forestry to substitute for spot-market fiber exposure. Anchor capacity expansion in Turkey's Izmir corridor to capture regional packaging demand growth while hedging currency risk through euro-denominated contracts. For New Entrants and Emerging Players: Anchor in Saudi Arabia's Jeddah and Dammam industrial zones where Saudi Standards alignment creates regulatory tailwind for technology transfer. Target battery separator substrate segments where technical specifications exceed commodity pricing benchmarks and incumbent capacity remains constrained. Pursue joint development agreements with European specialty paper producers seeking alternative dissolving pulp sources. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across oxygen-delignification and closed-loop water recovery systems. Long-term viability favors mills with captive fiber bases and regulatory compliance infrastructure already deployed. Acquisition target archetype: Nordic mid-cap specialty producers with certified dissolving pulp capacity. Monitor EU carbon border adjustment mechanism proposals as inflection signal for regional cost competitiveness shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Forestry | Stora Enso's Nordic softwood captive supply anchors premium dissolving pulp output against spot fiber volatility. |
| TCF and ECF Sequence Conversion | German pharmaceutical packaging producers accelerate low-extractable purity investments to maintain EU Deforestation Regulation compliance. |
| Regional Trading Hub Expansion | Dubai aggregators consolidate South African hardwood routes into MENA printing segments with improved lot-size flexibility. |
| Battery Separator Substrate Capacity Addition | Specialty pulp isolates margin pools in energy storage applications where purity specifications override commodity benchmarks. |
| Closed-Loop Water Recovery Deployment | REACH and F-Gas Regulation mandates force capital redeployment into effluent chemistry compliance across Central European integrated mills. |
Research Methodology
Desk research of customs trade data, EU regulatory filings, and pulp industry association statistics preceded structured interviews with mill procurement directors, packaging converter supply chain managers, and MENA trading house operators. Primary fieldwork with Nordic integrated producers and Turkish paperboard mill executives combined with secondary validation against ECHA chemical registration databases and forest certification registries. Bottom-up volume modeling and top-down demand triangulation cross-checked segment assumptions.
Variance decomposition across product type, end-use application, grade tier, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand projections incorporating e-commerce fulfillment center construction pipelines and textile sector dissolving pulp substitution trends. Modeled inputs included energy cost scenarios affecting chemical pulping economics and currency fluctuation impacts on dollar-denominated contract exposure.
Material uncertainties — EU carbon border adjustment implementation timing, MENA recycled fiber collection infrastructure development, and South African hardwood supply route disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement schedules and fiber substitution elasticity. Practitioners should keep alternative scenarios live as EU Deforestation Regulation compliance deadlines and Saudi industrial localization policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
NCR Laser Paper Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Writing Paper Market
Paper Products
Solid Bleached Board Market
Paper Products
Drum Pulper Market
Paper Products
Printing and Writing Papers Market
Paper Products
Inlay Paper Market
Paper Products
Global Cellulose Sponge Market
Paper Products
White Top Testliner Market
Paper Products
Specialty Paper Market
Paper Products
Veneer Sheets Market
Paper Products
Global Paper Chemical Market
Paper Products
Greaseproof Paper Market
Paper Products
Chemical Pulp Market