
 Wood Paper and Paperboard Recycling Market | 2026-2036
Wood Paper and Paperboard Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Paper and Paperboard Recycling Market Intelligence
Increased collection and sorting capacity in North America is rebalancing the flow of recovered paper feedstock away from traditional export markets. American Paper Recycling Corp leverages its extensive collection network to secure high-quality inputs for domestic mills. Meanwhile, Global Waste Recyclers Ltd specializes in processing mixed paper grades, while Hadfield Wood Recyclers focuses on wood waste streams for energy and board production.
Wood paper and paperboard recycling is the process of converting waste paper materials back into usable pulp fiber. This involves mechanical and chemical treatments, including a critical deinking stage to remove inks and contaminants for producing high-grade recycled pulp. Containerboard represents the largest product segment by volume, driven by e-commerce and logistics. The packaging end-use industry remains the primary consumer of recycled content, while demand for recycled newsprint continues to mature.
Government mandates shape market dynamics, with the US EPA setting recycling targets and the EU Green Deal promoting circularity. China's MEE policies on imported waste have significantly altered trade flows of recovered paper. Future profitability for recyclers will depend on their ability to adapt to varying regional contamination standards and invest in advanced sorting technologies.
Market Dynamics
The global reconfiguration of recovered paper trade flows represents the central force shaping the market. Divergent regulatory pressures, from the EU Green Deal's circularity mandates to China's strict contamination standards, are compelling a structural realignment of supply chains.
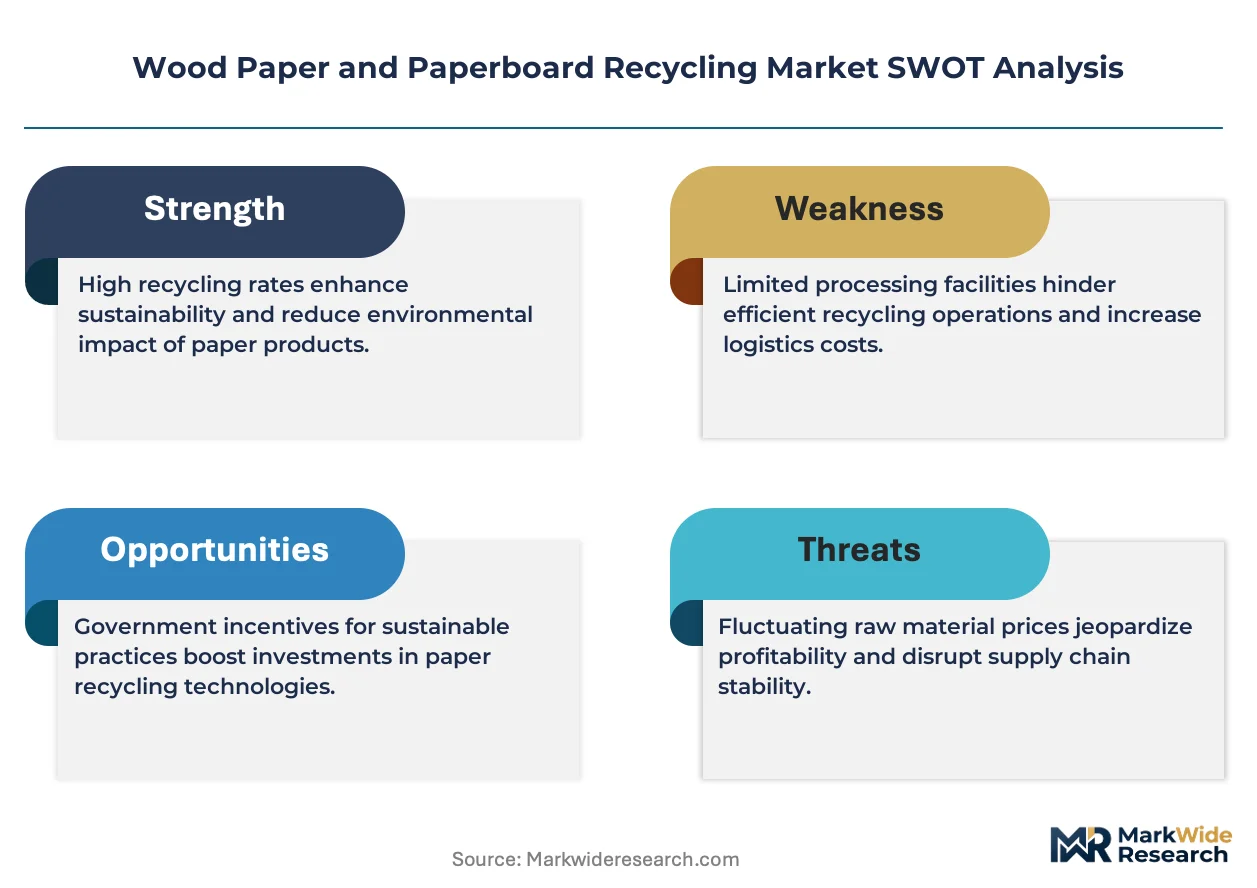
Growth Catalysts
- Corporate Sustainability Goals:Major brands in the food, beverage, and consumer goods sectors are setting aggressive targets for recycled content in packaging, creating consistent demand for high-quality recycled pulp and containerboard.
- E-commerce Expansion:The logistics and e-commerce industries remain a primary driver, requiring vast quantities of containerboard and protective paper packaging, for which recycled fiber is the principal feedstock.
- Regulatory Mandates:Frameworks like the EU's Circular Economy Action Plan and state-level extended producer responsibility (EPR) laws in the United States create structural, long-term demand for recycled materials.
Market Restraints
- Feedstock Contamination:The presence of plastics, food waste, and other non-fiber materials in collected paper streams degrades pulp quality, increases processing costs, and limits the usability of the final product.
- Volatile Input Pricing:Prices for recovered paper are subject to significant fluctuations based on collection rates, global shipping costs, and sudden shifts in import policies, creating margin uncertainty for recyclers.
- Energy and Water Intensity:The pulping, deinking, and drying processes are energy-intensive and require substantial water resources, exposing operators to rising utility costs and stricter environmental regulations.
Strategic Opportunities
- Advanced Sorting Technology:Investment in AI-driven optical sorting and robotic systems allows processors to segregate mixed paper more effectively, creating higher-value feedstock and accessing premium markets.
- New Product Development:There is an opportunity to develop novel applications for lower-grade recycled fibers, such as in molded pulp products, insulation materials, or as a component in bio-composites.
- Geographic Expansion:Developing formal collection and sorting infrastructure in underpenetrated regions like Latin America and the Middle East offers a pathway to secure new sources of feedstock.
Industry Challenges
- Capital Investment Hurdles:Upgrading or building new deinking and processing facilities to meet stringent quality standards for end-users requires significant capital expenditure, posing a barrier for smaller operators.
- Logistical Reconfiguration:Shifting vast volumes of recovered paper from traditional export routes to new domestic or regional mills requires establishing new logistics networks, contracts, and quality control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Paper and Paperboard Recycling Market |
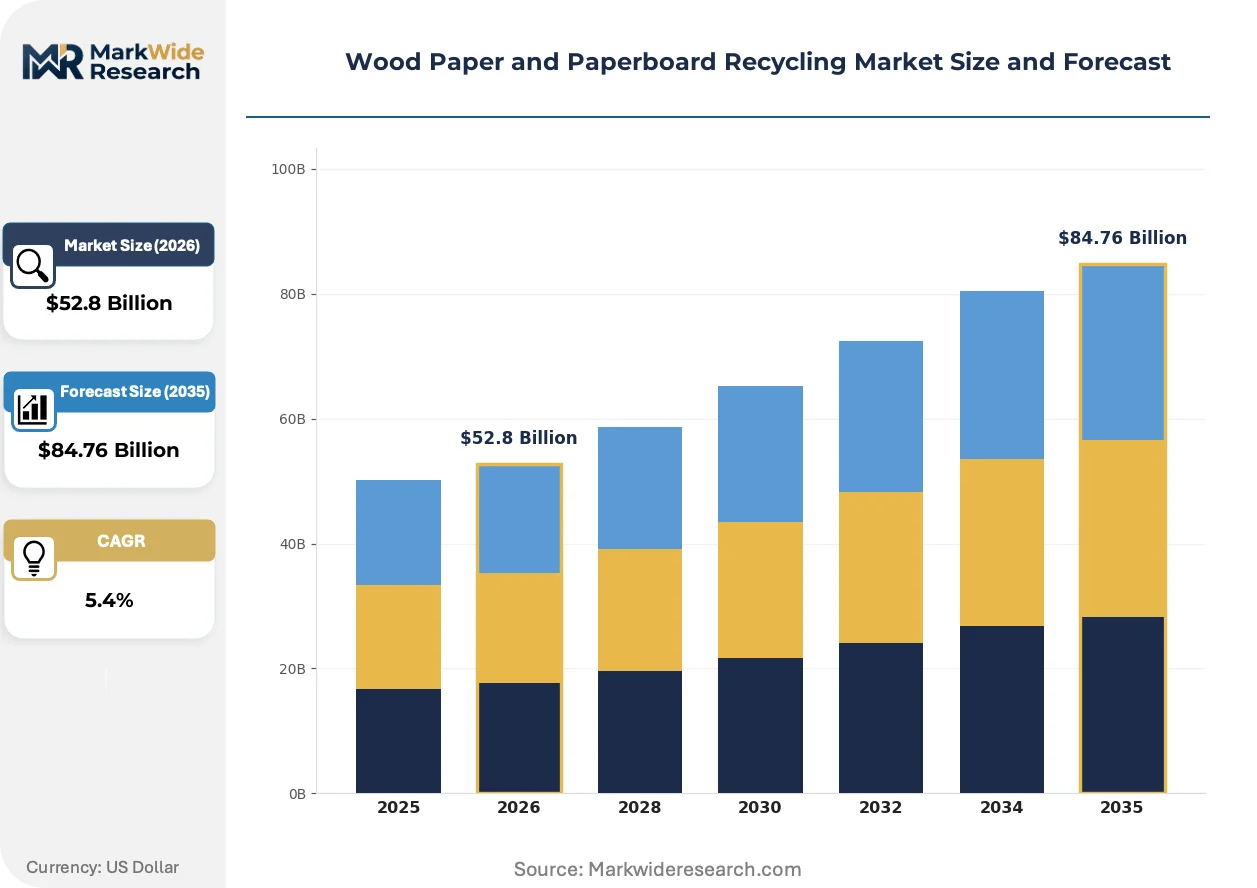
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containerboard, Newsprint, Kraft Paper, Tissue Paper, Boxboard Recycling Process: Deinking, Pulping, Bleaching, Hydrapulper, Screening End Use Industry: Packaging, Printing, Construction, Automotive Suppliers, Consumer Goods Distribution Channel: Direct Sales, Wholesalers, E-commerce, Industrial Distributors |
| Companies Covered | Hadfield Wood Recyclers, American Paper Recycling Corp, Carolina Fibre Corporation, Evergreen Paper Recycling, Hanna Paper Recycling, Huron Paper Stock, Global Waste Recyclers Ltd, InterWest Paper Inc, Ricova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Paper and Paperboard Recycling Market Strategic Shifts & Innovations
The industrialization of sorting and processing defines the current market evolution. Technology is being deployed to meet divergent quality standards set by new end-markets and stricter regulations, shifting the focus from bulk exporting to value-added domestic processing.
Advanced sorting technology, including AI-powered optical sensors and robotics, is being deployed to identify and separate different paper grades and contaminants. Material recovery facilities (MRFs) and pulp mills are adopting these systems to improve feedstock purity for containerboard production. This capability is integrating previously difficult-to-process mixed paper streams into the value chain for higher-grade applications.
The EU Green Deal and its associated Circular Economy Action Plan are creating powerful regulatory tailwinds. These policies set targets for recycling and mandate the use of recycled content in certain product categories, most notably packaging. Consequently, paper and paperboard manufacturers across Europe are recalibrating production to incorporate more recovered fiber to ensure compliance and meet customer demand.
A significant behavioral shift is occurring as consumer packaged goods companies and retailers directly specify minimum recycled content in their packaging contracts. This disrupts traditional procurement, forcing paper mills and converters to provide verifiable traceability of their recycled feedstock. This trend is most visible in North America and Europe, where corporate sustainability reporting frameworks are becoming standardized.
Wood Paper and Paperboard Recycling Market Segmentation
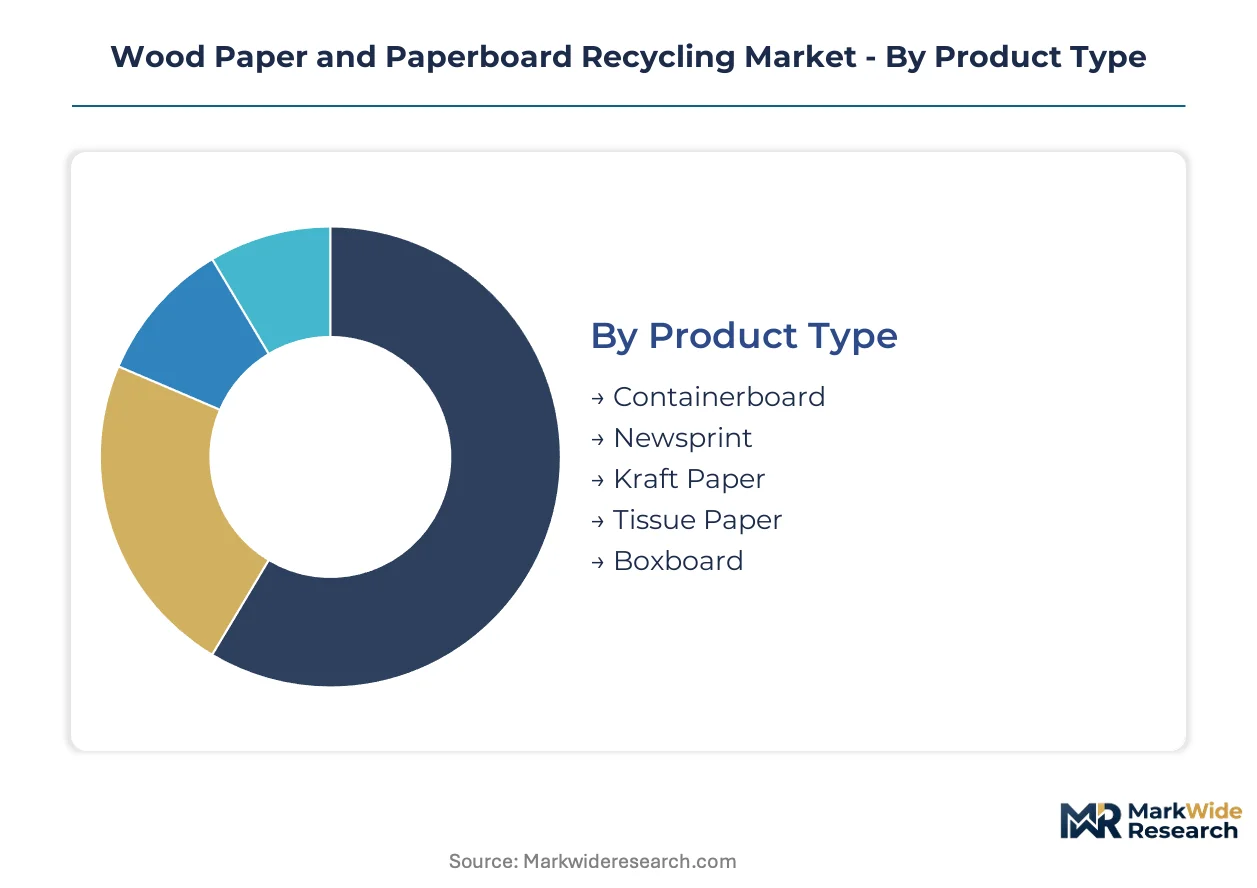
The wood paper and paperboard recycling market categorizes its diverse operations and outputs across several key dimensions. Understanding these segments provides clarity on the technical requirements, economic drivers, and value chain dynamics influencing recycled material flows. Each segment reflects specific processing needs or end-market demands for recovered fiber.
Product Type:
The market's product type segmentation highlights the various paper and paperboard grades produced from recycled fibers, defined by their technical specifications and end-use characteristics.
- Containerboard:This heavy-duty paperboard forms corrugated boxes, essential for shipping and packaging. Its demand concentrates in e-commerce and logistics, driven by the need for robust, sustainable packaging solutions.
- Newsprint:Made primarily from recycled newspapers, this grade is used for printing newspapers and other low-cost publications. Demand is concentrating in regions with established collection infrastructure, though overall consumption continues to mature globally.
- Kraft Paper:Known for its strength and durability, kraft paper finds use in bags, wrapping, and various industrial applications, often requiring strong mechanical properties.
- Tissue Paper:This soft, absorbent paper is manufactured for hygiene products like toilet paper, paper towels, and facial tissues, prioritizing cleanliness and softness.
- Boxboard:Used for folding cartons and other lighter packaging applications, boxboard serves consumer goods packaging where printability and formability are important.
Mature deployment sits with Newsprint. Newer deployment is concentrated in Containerboard.
Recycling Process:
This category delineates the primary technical applications involved in transforming waste paper into usable pulp, each step addressing specific contaminants or fiber properties.
- Deinking:This crucial process removes printing inks and other non-fiber contaminants from recovered paper through mechanical and chemical means. High-grade recycled pulp production for printing and writing papers depends heavily on effective deinking.
- Pulping:The initial mechanical process of breaking down waste paper into individual cellulose fibers using water and agitation. Pulping is fundamental for preparing all recovered paper for subsequent refining and papermaking.
- Bleaching:A chemical treatment used to whiten recycled pulp and improve its brightness, often necessary for producing higher-quality white paper and board grades.
- Hydrapulper:A large vat with a powerful rotor that efficiently slushes waste paper into a pulp slurry, serving as the first stage in many recycling lines.
- Screening:Mechanical filtration steps that remove large contaminants like plastics, staples, and other foreign objects from the pulp slurry, ensuring cleaner fiber.
The deinking process is expanding most quickly due to rising demand for high-quality recycled content.
End Use Industry:
The end-use industry segmentation reflects where recycled paper and paperboard products are primarily consumed, indicating demand drivers and market size for different applications.
- Packaging:This industry remains the largest consumer, utilizing recycled containerboard and boxboard for e-commerce, food and beverage, and consumer product packaging. Demand for recycled content in packaging is concentrating due to corporate sustainability goals and regulatory mandates.
- Printing:The printing industry uses recycled newsprint and other graphic papers for publications, magazines, and commercial print jobs. Consumption in printing is concentrating in segments requiring cost-effective and environmentally friendly paper sources.
- Construction:Recycled paper finds applications in construction materials such as insulation, gypsum board facings, and roofing felt, contributing to sustainable building practices.
- Automotive Suppliers:The automotive sector incorporates recycled paperboard for interior panels, trunk liners, and protective packaging for components, driven by lightweighting and material circularity goals.
- Consumer Goods:This broad category includes diverse applications like molded pulp products, stationery, and various household items, driven by consumer preference for sustainable products.
Packaging applications maintain the most stable demand for recycled paper and paperboard.
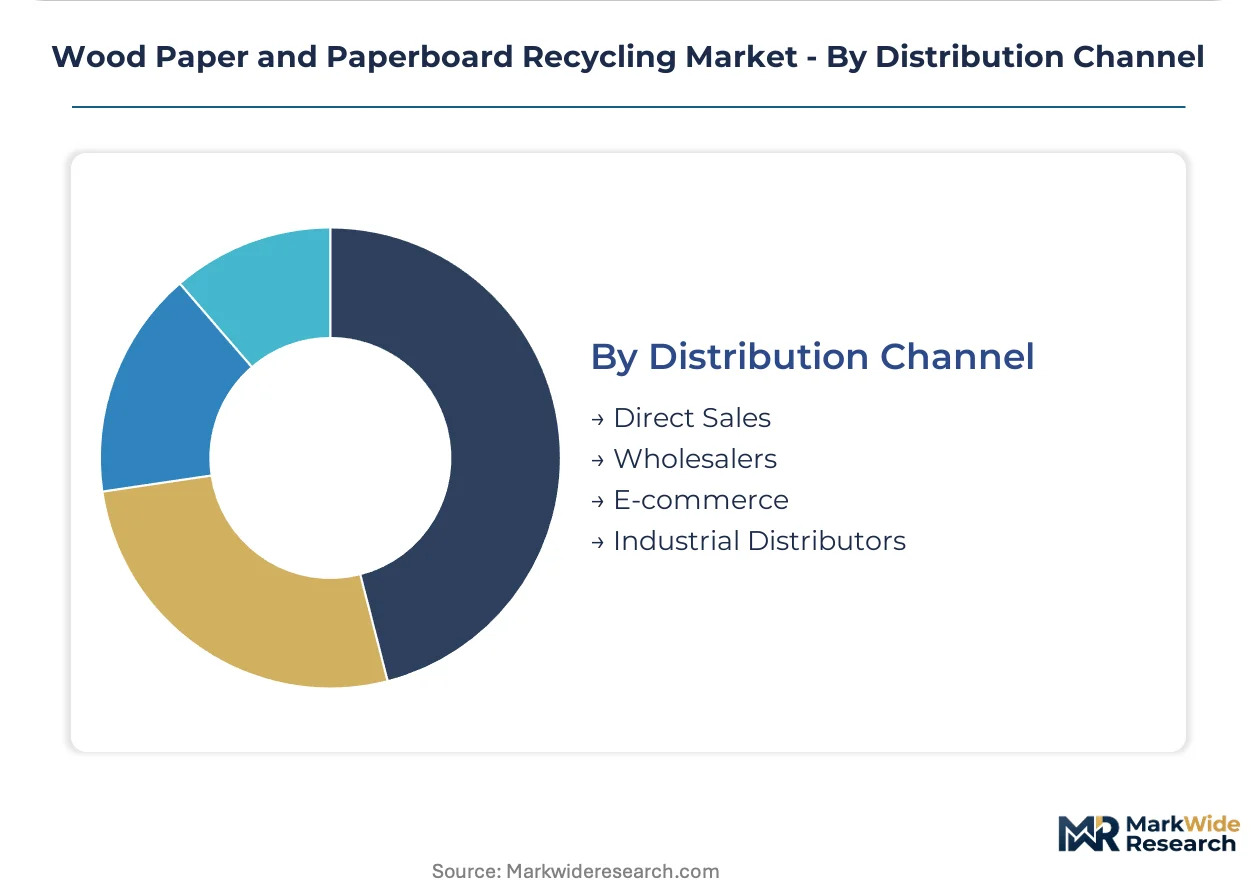
Distribution Channel:
This segment outlines the various pathways through which recycled paper and paperboard products reach their end-users, highlighting logistical and transactional structures.
- Direct Sales:Manufacturers of recycled paper and paperboard products sell directly to large industrial customers, such as packaging converters or printing houses. This channel often involves long-term contracts and customized product specifications.
- Wholesalers:Intermediaries purchase bulk quantities of recycled paper products from mills and distribute them to smaller businesses or regional markets. Wholesalers concentrate on managing inventory and logistics for a diverse customer base.
- E-commerce:Online platforms facilitate the sale of recycled paper products, particularly for smaller businesses or specialized applications, offering convenience and broader market access.
- Industrial Distributors:These specialized distributors supply recycled paper products and related materials to specific industrial sectors, often providing technical support and tailored logistics solutions.
Direct Sales represents the most established channel for large volume transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States serves as a significant source of recovered paper feedstock, anchoring collection and processing capacities within the global market. Domestic mills increasingly rely on these local supplies. Regulatory shifts and growing e-commerce demand drive regional market development.
United States
United States demand for containerboard is strong, driven by e-commerce expansion and robust logistics networks. The US EPA sets recycling targets, influencing collection infrastructure and material recovery. Major processing hubs like those in the Pacific Northwest focus on high-volume pulp production for packaging.
Germany
Germany's advanced recycling infrastructure supports high-quality recycled paper and board production for packaging. The EU Green Deal and its Circular Economy Action Plan mandate recycled content use across industries. Industrial clusters in North Rhine-Westphalia integrate advanced sorting technologies for fiber purity.
China
China's evolving domestic demand for recycled paperboard fuels significant internal processing capacity expansion. MEE policies on imported waste have reshaped global trade flows, prioritizing local sourcing. Major manufacturing centers in the Yangtze River Delta focus on producing containerboard for export and domestic consumption.
India
India's rapidly expanding packaging sector drives demand for recycled paper, particularly for containerboard and kraft paper. The country's national environmental regulations encourage resource efficiency and waste management initiatives. Industrial zones around Delhi and Mumbai are developing new collection and processing facilities.
Japan
Japan maintains strong domestic demand for recycled paper, especially for newsprint and graphic papers, due to established collection systems. METI promotes circular economy practices and targets for increased material recycling rates. Pulp and paper mills in the Kanto region integrate advanced deinking processes for high-grade output.
Wood Paper and Paperboard Recycling Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized feedstock processing and advanced sorting solutions. The market exhibits a tiered structure, with players differentiated by their access to quality feedstock and processing capabilities. Strategic archetypes include large-scale integrated recyclers, specialized fiber processors, and technology providers for sorting. Dominant competitive moves involve capacity expansion in advanced deinking facilities and strategic partnerships with packaging manufacturers.
Specialists in specific waste streams like wood recycling, Hadfield Wood Recyclers exemplifies focused processing for energy and board production. American Paper Recycling Corp represents a significant player leveraging an extensive collection network to secure high-quality inputs for domestic mills. Global Waste Recyclers Ltd occupies a position as a processor specializing in mixed paper grades, integrating these into the value chain. These companies anchor different segments of the recovered paper supply chain, from collection to specialized processing.
| Leading Market Players |
|---|
| Hadfield Wood Recyclers |
| American Paper Recycling Corp |
| Carolina Fibre Corporation |
| Evergreen Paper Recycling |
| Hanna Paper Recycling |
| Huron Paper Stock |
| Global Waste Recyclers Ltd |
| InterWest Paper Inc |
| Ricova |
| Others |
Cost & Logistics Intelligence
Specialized engineers in European deinking facilities influence pricing for premium recycled pulp, impacting spread across quality tiers. This labor-cost differential contributes to price differentiation for high-grade recycled content compared to standard mixed paper streams.
Pricing Analysis
Quality assurance guarantees bundled with higher-grade recycled pulp influence transactional pricing models. Price differentiation stems from fiber purity and geographic delivery costs. Volatile input pricing for recovered paper creates margin pressure for processors, particularly for commodity grades. The packaging industry, with its high volume demands, exhibits significant price sensitivity, while specialty applications requiring specific fiber properties are less sensitive.
Supply Chain Analysis
China's MEE policies on imported waste have significantly reshaped global sourcing for recovered paper feedstock, driving domestic processing. The supply chain for recycled paper and paperboard draws from major collection hubs in the United States, with significant processing capacity concentrated in China and Germany. Regulatory restrictions on waste imports represent a structural risk. Distribution runs through direct sales channels, connecting large mills to industrial end-users like packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood paper and paperboard recycling market operates under supply constraints, with advanced deinking capacity representing a key bottleneck propping up high-grade pulp pricing.
For Market Incumbents: Acquire advanced sorting technology providers to mitigate feedstock contamination and secure higher-quality inputs. Invest in new deinking facilities, particularly in Southeast Asian manufacturing centers, to meet growing packaging demand. Form strategic partnerships with major consumer packaged goods companies to secure long-term supply contracts, buffering against volatile input pricing and stricter quality standards.
For New Entrants and Emerging Players: Small-to-medium sized consumer goods brands seeking sustainable packaging solutions represent an underserved buyer archetype. Target underpenetrated regions like Latin America by developing formal collection and sorting infrastructure. Offer customized recycled fiber solutions for novel applications such as molded pulp products, providing a differentiated go-to-market angle against bulk commodity suppliers.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized fiber processors given the structural demand for high-quality recycled content. Long-term viability for this market is strong, driven by persistent regulatory tailwinds and ambitious corporate sustainability goals. Focus on technology providers offering advanced sorting and deinking solutions. The signal to watch is the expansion of circular economy mandates into new product categories beyond packaging.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Deinking | Increases supply of high-grade recycled pulp for packaging manufacturers. |
| Advanced Sorting Technology Integration | Improves feedstock purity, unlocking premium markets for recycled fiber. |
| Strategic Partnerships with Packaging Converters | Secures long-term offtake agreements for recycled content. |
| Geographic Expansion into Emerging Markets | Diversifies feedstock sources and reduces reliance on traditional export routes. |
| New Product Development for Lower-Grade Fibers | Creates value from previously underutilized waste streams, improving resource efficiency. |
Research Approach
Multi-period observation of recovered paper trade flows and processing capacity expansion anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research included conversations with mill operators, waste management executives, packaging procurement managers, and recycling technology developers. Secondary validation drew from US EPA reports, EU Green Deal policy documents, China MEE regulations, and relevant industry association reports. Bottom-up and top-down triangulation ensured data integrity.
A segment-weighting approach informed the market sizing, integrating product type, recycling process, end-use industry, and distribution channel dimensions. The analytical framework projected market growth across the analysis window, with CAGRs derived from historical trends and projected demand drivers. Regional regulatory frameworks and e-commerce growth rates served as key forecast inputs, shaping future market trajectories.
Revisions become necessary when significant shifts in trade policies or unforeseen technological breakthroughs materialize. Forecasts reflect assumptions regarding stable regulatory environments and sustained corporate sustainability commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Overlay Paper Market
Paper Products
Hardwood Pulp Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Veneer Sheets Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Reprographic Paper Market
Paper Products
Paper Machine Systems Market
Paper Products
GCC Paper Products Market
Paper Products
Base Paper Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Aramid Paper Market
Paper Products
Paper Core Market
Paper Products
Solid Bleached Board Market
Paper Products
Europe Coated Paper Market
Paper Products
Filtration Paper Market
Paper Products
Africa Tissue Paper Market