
 Europe Tissue and Hygiene Paper Market | 2026-2036
Europe Tissue and Hygiene Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tissue and Hygiene Paper Market Foresight
A capital-intensity divergence between integrated pulp-to-tissue producers and converters relying on merchant supply is bifurcating competitive returns in the Europe tissue and hygiene paper sector. Essity AB leverages its Nordic pulp assets and pan-European brand architecture to sustain margin resilience across retail and away-from-home channels. Lucart S.p.A. anchors its position through recycled-fiber specialization and closed-loop manufacturing systems in Italy. Metsä Tissue competes via fresh-wood fiber scale and energy-efficient drying technologies at its Finnish and Swedish mills.
Europe tissue and hygiene paper encompasses disposable cellulose-based products manufactured from virgin wood pulp, recycled fibers, or blended furnish, typically weighing 13–25 grams per square meter and engineered for absorbency, softness, and controlled wet strength. These products serve sanitation, personal hygiene, and surface-cleaning functions across household, commercial, and institutional settings. Toilet paper and paper towels represent mature volume pillars with stable replenishment cycles, while facial tissues and premium napkins capture expanding margin pools through premiumization and gifting formats. The hospitality end-user segment demonstrates accelerating demand for compact, high-sheet-count dispensers as labor costs and space constraints reshape procurement specifications.
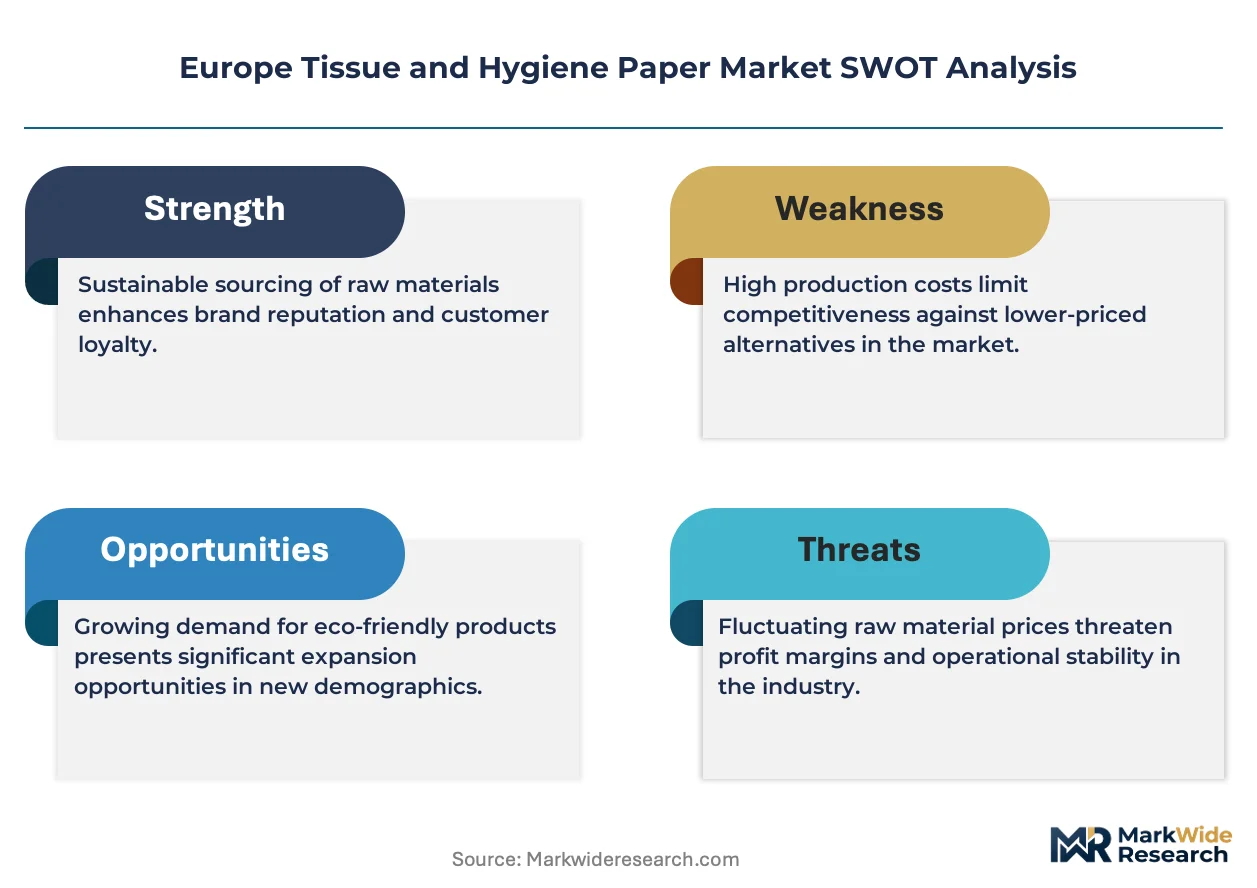
EMA guidelines on medical-grade tissue sterility, REACH chemical restrictions on pulp bleaching agents, and the EU Green Deal's carbon-border adjustments collectively tighten compliance thresholds for non-integrated European producers. CE marking and ECHA substance-of-very-high-concern listings are redirecting R&D spending toward chlorine-free processing and biodegradable wet-strength resins. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and benchmark their fiber certification portfolios against retailer sustainability scorecards to secure shelf access.
Market Dynamics
The EU Green Deal's carbon-border adjustment mechanism is forcing tissue mills to reconfigure pulping chemistry and energy sourcing ahead of compliance deadlines.
Growth Catalysts
- Healthcare procurement expansion:German, French, and British hospitals are scaling hygienic disposable volumes to meet post-pandemic infection-control protocols.
- REACH chemical restrictions:Chlorine-free bleaching mandates are redirecting R&D budgets toward biodegradable wet-strength resins that command shelf-access premiums.
- Closed-loop manufacturing:Italian and Spanish mills are deploying recycled-fiber specialization to secure retailer sustainability scorecard compliance.
Market Restraints
- Energy cost volatility:Natural gas and electricity price spikes at Nordic and German mills are compressing converter margins on merchant pulp supply.
- F-Gas Regulation compliance:Phase-down schedules for fluorinated gases used in tissue drying are extending equipment replacement timelines and capex cycles.
- Recycled fiber supply concentration:Collection infrastructure gaps in Eastern Europe limit furnish availability for premium recycled-grade production.
Strategic Opportunities
- CE marking acceleration:Medical-grade tissue sterility certifications under EMA guidelines open institutional procurement channels for compliant producers.
- Hospitality dispenser formats:Compact high-sheet-count systems are capturing away-from-home contracts as labor costs and space constraints reshape buyer specifications.
- Extended Producer Responsibility frameworks:Packaging fee structures in France and Italy reward mills with certified fiber traceability and closed-loop water systems.
Industry Challenges
- Specialized pulping engineering talent:Chlorine-free process chemists and energy-efficiency technicians are scarce across Nordic and Alpine mill clusters.
- Legacy drying asset retrofitting:Converting gas-fired Yankee dryers to electric or biomass alternatives requires extended downtime and complex utility reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tissue and Hygiene Paper Market |
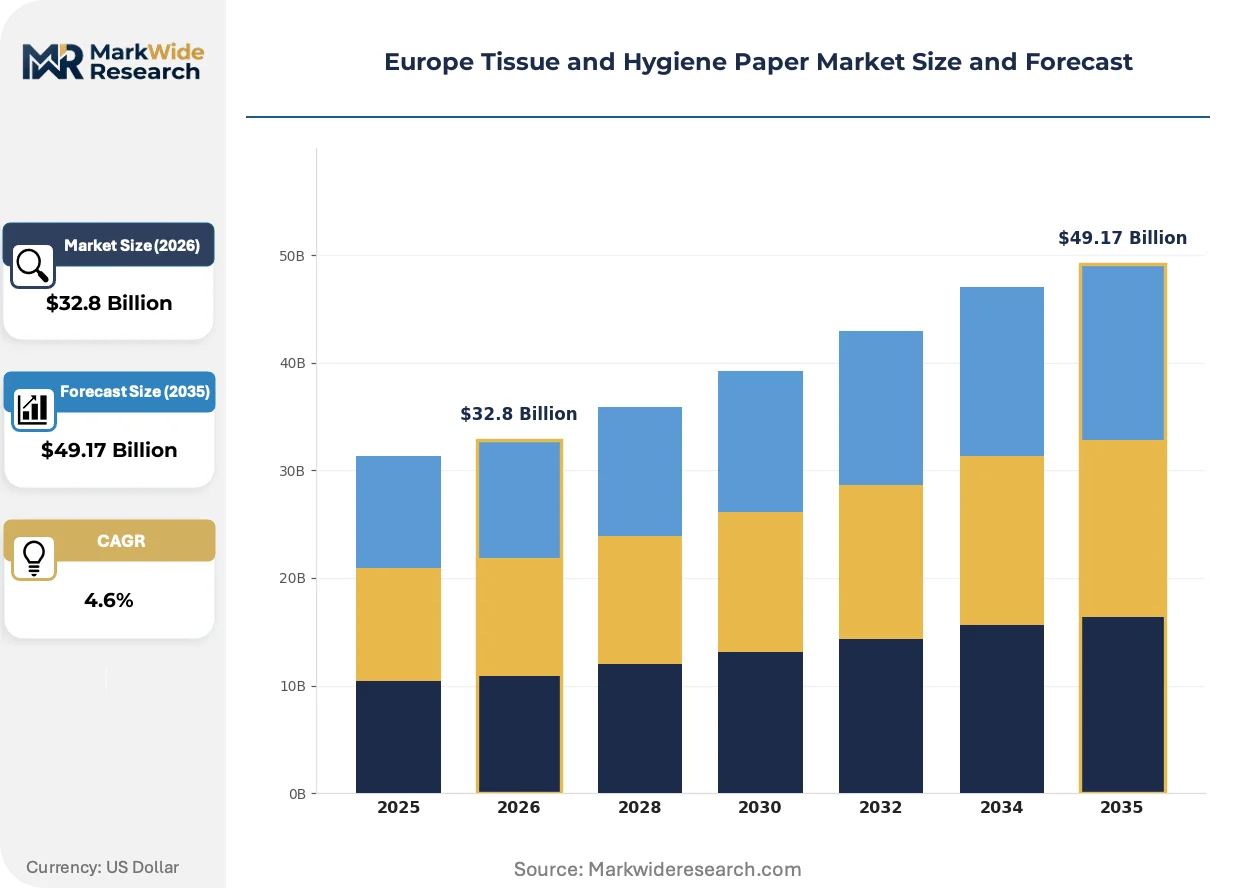
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Tissues, Toilet Paper, Paper Towels, Napkins End User: Household, Industrial, Healthcare, Hospitality Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Wholesale Material: Recycled Paper, Virgin Fiber, Tissue Blend, Others |
| Companies Covered | Metsä Tissue, Lucart S.p.A., Sofidel Group, The Navigator Company SA, Industrie Cartarie Tronchetti SpA, Essity AB, WEPA Hygieneprodukte GmbH, Ontex Group, Kimberly-Clark Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tissue and Hygiene Paper Market Shifts & Advancements
Tissue manufacturing is pivoting toward energy-efficient drying and fiber-recovery systems as carbon accounting penetrates buyer procurement scorecards.
Heat-pump drying technology is displacing conventional gas-fired Yankee cylinders in Finnish and Swedish integrated mills. Essity and Metsä Tissue are piloting these systems at flagship facilities to capture EU Green Deal transition subsidies. The shift is compressing fossil-energy exposure in margin structures while extending equipment amortization horizons.
EMA guidelines on medical-grade tissue sterility are tightening documentation requirements for pulp sourcing and wet-strength additive chemistry. CE marking now demands batch-level traceability that many merchant-dependent converters cannot supply. German hospital procurement consortia are filtering tenders to exclude uncertified suppliers.
Buyer concentration in European retail is consolidating shelf-access negotiations around sustainability certification tiers. Ahold Delhaize and Carrefour are unbundling traditional volume rebates in favor of fiber-scorecard performance bonuses. French and Benelux hypermarkets are the first channels where uncertified products face delisting pressure.
Europe Tissue and Hygiene Paper Market Segmentation
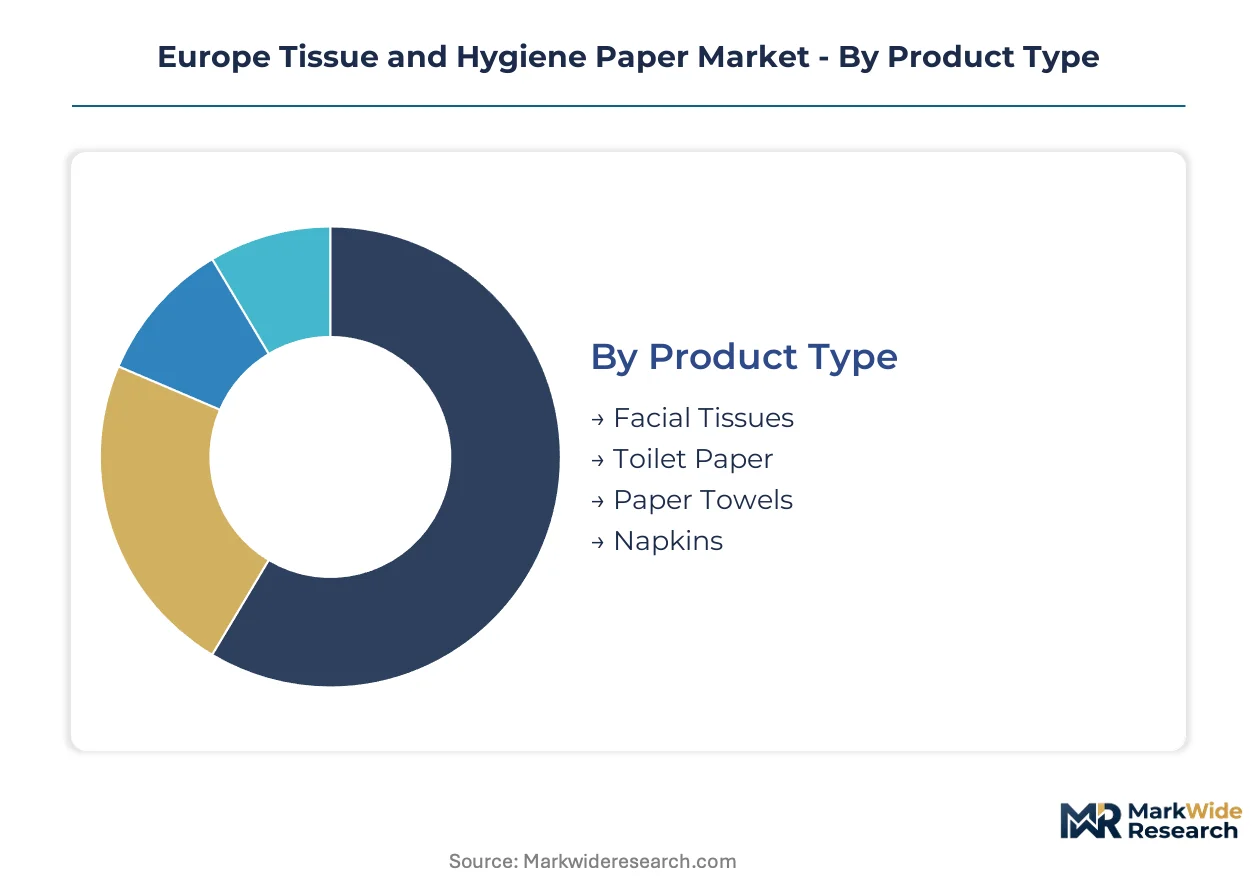
Segmentation in the Europe tissue and hygiene paper market reveals distinct procurement patterns across consumer and institutional channels. Product specifications, material sourcing, and distribution access determine margin capture and compliance exposure for mills and converters operating under EU Green Deal carbon-accounting rules.
Product Type:
Toilet paper and paper towels dominate domestic production volumes across German and Italian mills, while facial tissues and premium napkins concentrate export flows toward Benelux and Nordic retail channels.
- Toilet Paper:Virgin-fiber and recycled-grade rolls engineered for 13–22 gsm basis weight serve household replenishment cycles and away-from-home dispenser systems. German hospital procurement consortia are standardizing on high-sheet-count jumbo rolls to reduce restocking labor.
- Paper Towels:Multi-ply sheets with controlled wet-strength resin bonding absorb kitchen and industrial spills. French and British food-service distributors are specifying compact, high-capacity dispensers to align with space-constrained hospitality layouts.
- Facial Tissues:Softwood-pulp facial sheets with lotion additives target premium household and pharmaceutical retail in Switzerland and Austria.
- Napkins:Air-laid and conventional tissue napkins support table-service and quick-service restaurant formats across Spanish and Portuguese hospitality clusters.
Toilet paper commands the established base. The steepest expansion runs through paper towel dispenser formats for contract catering and healthcare.
End User:
Cost-tier differentiation separates commodity household volumes from certified institutional grades that command compliance premiums under EMA and REACH frameworks.
- Household:Mass-market retail packs and subscription-box deliveries drive replenishment demand through Carrefour, Ahold Delhaize, and pure-play e-commerce platforms. Sustainability scorecards now filter shelf access for uncertified fiber sources.
- Healthcare:Sterile and non-sterile medical-grade tissues require CE marking and batch-level pulp traceability under EMA guidelines. German, French, and British hospital procurement frameworks are excluding non-compliant tenders.
- Hospitality:Branded and private-label napkins, facial tissues, and toilet paper supply hotels, restaurants, and catering operators. Labor-cost pressures in Nordic markets are accelerating compact-dispenser adoption.
- Industrial:Heavy-duty paper towels and wipes serve manufacturing maintenance, automotive assembly, and logistics warehousing across Polish and Czech industrial zones.
Household consumption anchors volume throughput. Healthcare certification requirements are climbing the fastest as infection-control protocols tighten post-pandemic.
Distribution Channel:
Channel concentration varies by buyer type — retail consolidation favors supermarket scale, while institutional procurement runs through specialized wholesale and direct-contract structures.
- Supermarkets:Hypermarket and supermarket chains in France, Germany, and the Benelux region control premium-brand shelf placement and sustainability-scorecard negotiations. Fiber-certification tiers now override traditional volume rebates.
- E-commerce:Subscription models and bulk direct-to-consumer deliveries are gaining share in urban UK and German markets where convenience and sustainability transparency drive repurchase.
- Wholesale:Cash-and-carry and delivered wholesale supply away-from-home operators, healthcare facilities, and industrial end-users across Italian and Spanish distribution networks.
- Convenience Stores:Small-format urban retail captures emergency replenishment and travel-size tissue purchases in high-density French and British city centers.
Supermarket chains dominate value capture. E-commerce subscription mechanics are expanding most quickly among millennial household segments in Northern Europe.
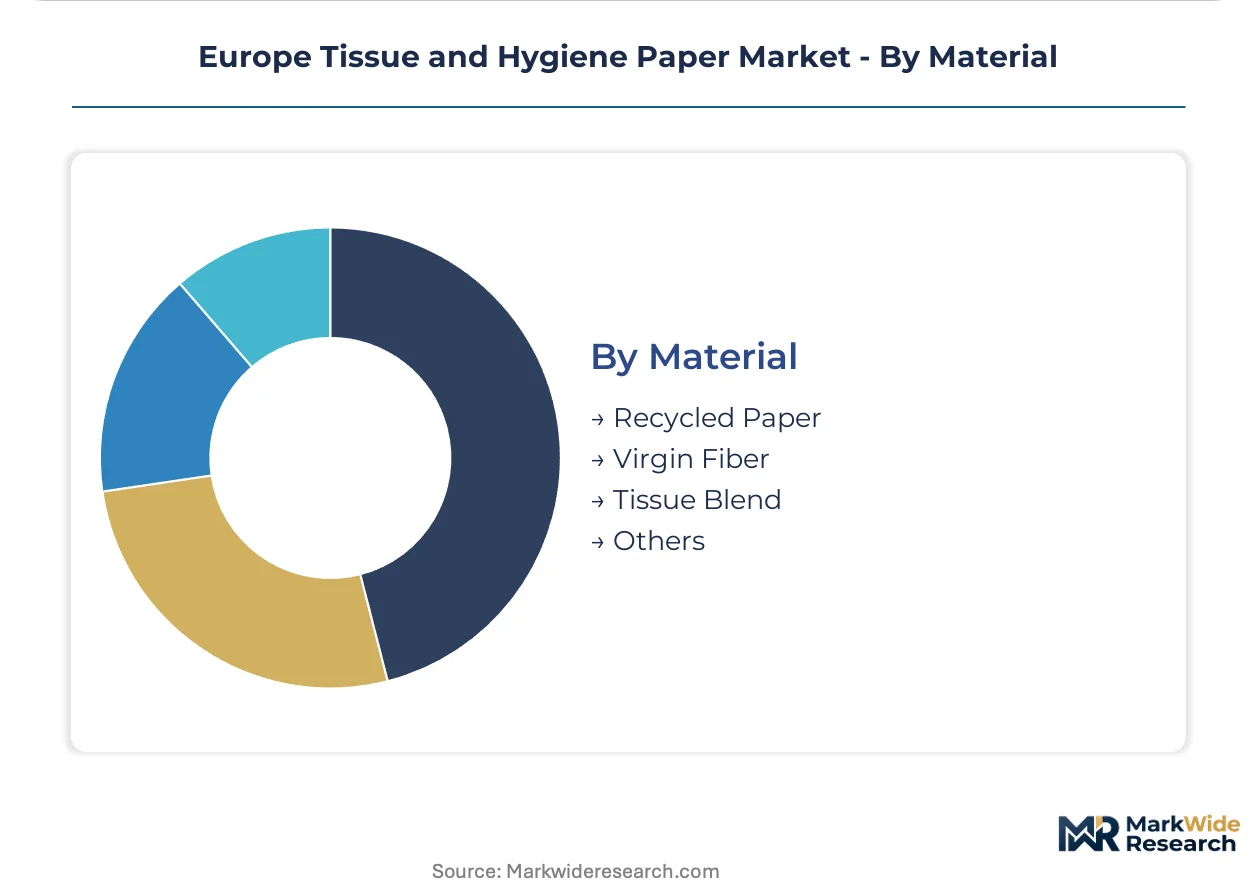
Material:
Supply concentration in recycled-fiber collection infrastructure creates geographic asymmetry — Western European mills access furnish more readily than Eastern European converters.
- Virgin Fiber:Fresh softwood and hardwood pulp from Nordic and Baltic mills delivers consistent absorbency and strength for premium tissue grades. Metsä Tissue and Essity leverage captive pulp assets to control input costs.
- Recycled Paper:Post-consumer recovered fiber processed through Italian and Spanish closed-loop systems meets retailer sustainability scorecards and EU Green Deal carbon-accounting requirements.
- Tissue Blend:Engineered combinations of virgin and recycled furnish balance performance and environmental credentials for mid-tier private-label products.
- Others:Bamboo, wheat straw, and agricultural residue fibers occupy niche premium and experimental product lines in German and Austrian specialty mills.
Virgin fiber retains the largest production base. Recycled-paper specialization is gaining share fastest as French and Italian Extended Producer Responsibility frameworks reward certified closed-loop systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across European tissue markets. German and Nordic buyers absorb certification premiums for closed-loop fiber, while Spanish and Polish procurement remains volume-driven and cost-sensitive.
Germany
Hospital procurement consortia in North Rhine-Westphalia and Bavaria are standardizing on high-sheet-count jumbo rolls to cut restocking labor. The F-Gas Regulation's phase-down schedule is forcing Yankee dryer retrofits at mills across Lower Saxony. Essity's integrated operations in Mannheim and Wiesbaden anchor captive pulp-to-tissue production serving both retail and away-from-home channels.
France
Extended Producer Responsibility frameworks in Île-de-France and Auvergne-Rhône-Alpes reward mills with certified fiber traceability and closed-loop water systems. ECHA substance-of-very-high-concern listings are redirecting R&D spending toward chlorine-free processing at facilities near Lyon. Carrefour and Ahold Delhaize hypermarkets in Paris are unbundling volume rebates in favor of sustainability-scorecard performance bonuses.
Italy
Lucart S.p.A.'s recycled-fiber specialization in Tuscany and Emilia-Romagna secures retailer compliance with EU Green Deal carbon-accounting rules. REACH chemical restrictions on pulp bleaching agents are accelerating biodegradable wet-strength resin adoption at Lucca-area mills. The country's closed-loop manufacturing systems concentrate in the paper district between Pistoia and Lucca, serving private-label contracts across Southern Europe.
United Kingdom
Post-pandemic infection-control protocols are expanding hygienic disposable volumes at NHS trusts in Greater London and the Midlands. EMA guidelines on medical-grade tissue sterility are tightening batch-level traceability requirements that exclude merchant-dependent converters. Kimberly-Clark's operations in North Wales supply institutional channels with CE-marked products meeting hospital procurement frameworks.
Sweden
Metsä Tissue's Finnish and Swedish mills deploy energy-efficient drying technologies to capture EU Green Deal transition subsidies. Heat-pump drying pilots at flagship facilities near Stockholm are compressing fossil-energy exposure in margin structures. The Nordic pulp asset base supports premium virgin-fiber grades for Benelux and German retail channels demanding consistent absorbency specifications.
Europe Tissue and Hygiene Paper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed margin structure in European tissue. Integrated pulp-to-tissue producers control input costs through captive fiber supply, while merchant-dependent converters face compressed spreads during energy price spikes. The competitive field sorts into three archetypes: Nordic pulp-asset integrators, Southern European recycled-fiber specialists, and multinational hygiene conglomerates with pan-European brand architectures. Dominant competitive moves center on sustainability certification investments and compact-dispenser format development for away-from-home contracts.
Among Nordic integrated producers, Metsä Tissue and Essity AB exemplify the pulp-asset archetype, leveraging captive softwood supply to stabilize input costs across volatile energy markets. Lucart S.p.A. anchors the recycled-fiber specialist tier, occupying a position defined by closed-loop manufacturing systems and Italian mill concentration. These three companies represent the structural poles around which European competitive dynamics organize.
| Leading Market Players |
|---|
| Metsä Tissue |
| Lucart S.p.A. |
| Sofidel Group |
| The Navigator Company SA |
| Industrie Cartarie Tronchetti SpA |
| Essity AB |
| WEPA Hygieneprodukte GmbH |
| Ontex Group |
| Kimberly-Clark Corporation |
| Others |
Supply & Pricing Matrix
Capacity utilization at Nordic integrated mills shapes price floors across virgin-fiber grades, concentrating supply-side leverage among pulp-asset owners while compressing merchant-dependent converters during energy price spikes. German hospital procurement consortia and French hypermarket buyers absorb certification premiums that Eastern European volume purchasers resist, creating geographic price elasticity divergence.
Pricing Analysis
After-sales service contracts for dispenser system maintenance and restocking logistics drive lifetime value in away-from-home channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber certification tier and CE marking compliance, with Carrefour and Ahold Delhaize unbundling volume rebates for sustainability-scorecard performance. Cost compression in recycled-grade production is intensifying because collection infrastructure gaps limit furnish availability. Healthcare procurement consortia in Germany and France demonstrate lowest price sensitivity, while Polish and Czech industrial buyers anchor the cost-sensitive tier.
Supply Chain Analysis
Inventory buffers for pulp furnish extend lead times at merchant-dependent converters, particularly when Nordic gas-fired drying capacity faces F-Gas Regulation retrofit schedules. Supply concentrates in Finland, Sweden, and Italy, with virgin softwood pulp drawing from Nordic captive assets and recycled fiber sourcing from Tuscan closed-loop systems. Natural gas price volatility and single-source vulnerability to Russian-origin energy substitutes constitute the dominant structural risk. Distribution runs through supermarket chain direct contracts, wholesale delivered supply to healthcare and hospitality, and e-commerce subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as post-pandemic healthcare procurement normalization and EU Green Deal subsidy flows restore capital deployment confidence.
For Market Incumbents: Compound pulp-asset advantages by accelerating heat-pump drying retrofits at flagship Nordic facilities to capture transition subsidies ahead of F-Gas compliance deadlines. Defend margin position against recycled-fiber specialists through backward integration into bleached-chemical-pulp supply and exclusive long-term contracts with German hospital procurement consortia.
For New Entrants and Emerging Players: CE marking fast-track investments open institutional procurement channels currently filtered to exclude non-compliant merchant converters. White-space targets concentrate in compact high-sheet-count dispenser formats for Nordic hospitality labor-cost pressures and biodegradable wet-strength resin supply to Italian closed-loop mills. Go-to-market positioning should anchor on batch-level traceability documentation that satisfies EMA guidelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated pulp-to-tissue producers with captive fiber supply and energy-efficient drying assets over merchant-dependent converters exposed to input cost volatility. Long-term viability across the projection horizon rests on EU Green Deal compliance infrastructure and certification portfolio depth. The inflection signal to monitor is Extended Producer Responsibility fee structure expansion beyond France and Italy into German federal frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Drying Retrofit | Captures EU Green Deal transition subsidies while compressing fossil-energy exposure at Nordic mills. |
| CE Marking Acceleration | Opens German hospital procurement channels that exclude uncertified merchant-dependent converters. |
| Recycled-Fiber Specialization | Secures retailer sustainability scorecard compliance under French Extended Producer Responsibility frameworks. |
| Compact Dispenser Format Development | Captures away-from-home contracts as Nordic hospitality labor costs reshape buyer specifications. |
| Closed-Loop Water System Investment | Qualifies for Italian packaging fee reductions and EU carbon-border adjustment exemptions. |
Research Methodology
Initial hypotheses were tested against primary input from mill operations directors, tissue product procurement managers at German hospital consortia, sustainability officers at French and Benelux retailers, and energy-efficiency engineering specialists, then refined through secondary validation against EU ETS emissions data, F-Gas Regulation compliance filings, REACH substance registration databases, and Nordic pulp production statistics. Bottom-up volume modeling across product grades and end-use segments triangulated with top-down macroeconomic elasticity assumptions.
Variance decomposition across the analysis window isolated volume drivers from price-mix effects and regulatory compliance cost pass-through. Segmentation dimensions modeled include product type, material source, end-user channel, and distribution format, with regional regulatory cluster differentiation for EU Green Deal implementation timing. CAGRs were derived from trend-line extrapolation of historical procurement data adjusted for policy-driven step changes in certification requirements and carbon-accounting rules.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement, stable natural gas price normalization, and no major trade policy disruption; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Sawn Wood Market
Paper Products
Reprographic Paper Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Carbonless Paper Market
Paper Products
Paper Machinery Market
Paper Products
Heat Transfer Paper Market
Paper Products
Global Copier Paper Market
Paper Products
Thermal Paper Market
Paper Products
Aramid Paper Market
Paper Products
Paper Goods Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Tissue Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Paper Pigment Market
Paper Products
Global Wood Pulp Market