
 Metallized Paper Market | 2026-2036
Metallized Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Metallized Paper Market Outlook
India's vacuum metallization corridor is rewriting regional supply dynamics for decorative and barrier-grade substrates. AR Metallizing leverages integrated coating lines across European sites to sustain margin capture in specialty grades. Nissha Co., Ltd. anchors technical precision for electronics-facing laminates in East Asian supply chains. Lecta Group competes through controlled fiber sourcing from Iberian pulp networks.
Metallized paper comprises cellulose-based substrates vacuum-deposited with aluminum or alloy layers typically measuring 20–50 nanometers, engineered to provide oxygen and moisture barrier performance alongside metallic aesthetic properties for premium commercial applications. Coated paper variants dominate value pools where print receptivity and gloss uniformity command specification premiums, while specialty paper grades capture fastest expansion in pharmaceutical blister alternatives and high-end confectionery wraps. Food packaging applications lead volume throughput across converting lines, though cosmetic packaging segments concentrate margin extraction through shorter runs and customized metallization patterns.
EU REACH frameworks govern chemical migration thresholds from metallized layers into food-contact surfaces, while ECHA substance evaluations pressure reformulation of certain adhesion promoters. Germany's national packaging regulator enforces dual sorting requirements that favor mono-material metallized constructions over multi-polymer laminates. Stakeholders must monitor evolving extended producer responsibility fee structures as these increasingly differentiate between technically recyclable and actually recycled metallized paper streams.
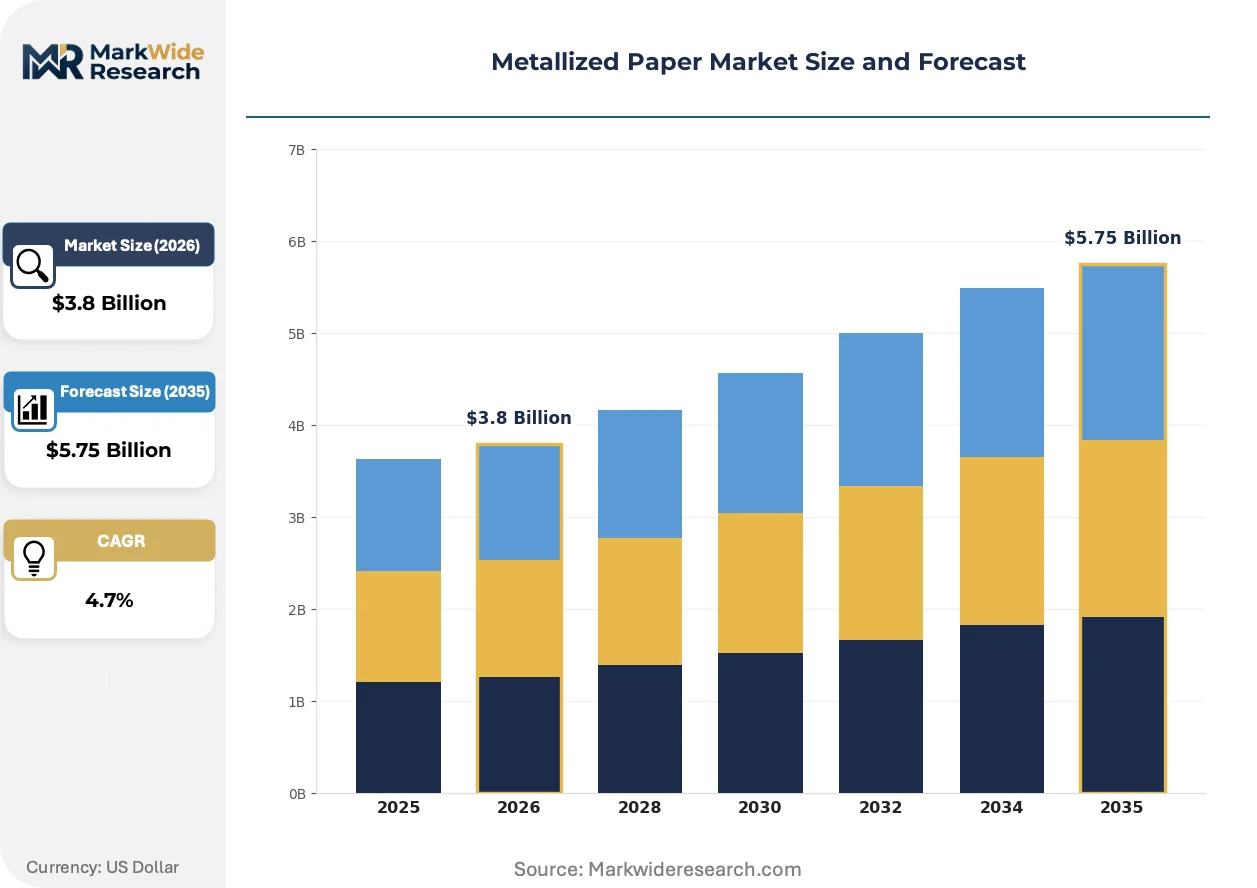
Market Dynamics
Vacuum metallization technology maturation is compressing barrier performance thresholds while EU Packaging and Packaging Waste Regulation mandates force substrate redesign across converting operations.
Growth Catalysts
- EU Green Deal packaging circularity targets:Mono-material metallized constructions qualify for reduced extended producer responsibility fees versus multi-polymer laminates, accelerating specification shifts in food-contact applications.
- Pharmaceutical blister packaging conversion:Metallized paper alternatives to aluminum-PVC laminates gain traction as CDSCO and EMA tighten child-resistance and barrier uniformity standards for solid-dose formats.
- Rhine-Ruhr packaging cluster concentration:Germany's integrated converting ecosystem enables rapid prototyping of customized metallization patterns for cosmetic short-run campaigns.
Market Restraints
- Aluminum flake supply volatility:Metallized layer deposition depends on high-purity aluminum feedstock subject to LME price swings and energy-intensive smelting constraints.
- Mono-material technical ceiling:Current cellulose substrates cannot match multi-polymer laminates for ultra-high moisture barrier applications exceeding 0.1 g/m²/day transmission rates.
- ECHA adhesion promoter scrutiny:REACH substance evaluations threaten reformulation of silane coupling agents critical for metal-to-fiber bonding, creating compliance timeline uncertainty.
Strategic Opportunities
- India vacuum metallization corridor expansion:Domestic coating line investments in Gujarat and Maharashtra reduce import dependency for decorative and barrier-grade substrates serving South Asian markets.
- Digital metallization patterning convergence:Laser ablation combined with conventional vacuum deposition enables variable-data metallic effects for anti-counterfeiting pharmaceutical serialization.
- Extended producer responsibility fee arbitrage:Technically recyclable mono-material streams command lower fees than composite laminates in Germany, France, and Italy, creating margin capture potential for compliant substrates.
Industry Challenges
- Vacuum deposition technician scarcity:Specialized knowledge of thin-film aluminum nucleation on cellulose substrates concentrates among aging European and Japanese engineering cohorts.
- Barrier certification timeline compression:Migration testing under EU REACH and FDA food-contact frameworks requires 6-18 month validation cycles that lag brand launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallized Paper Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Aluminum Laminated Paper, Specialty Paper End User: Packaging, Labels, Decoration, Stationery Application: Food Packaging, Beverage Packaging, Cosmetic Packaging, Industrial Usage Technology: Printing, Laminating, Coating, Converting |
| Companies Covered | AR Metallizing, Nissha Co., Ltd., Avery Dennison Corporation, Vacmet India Ltd., UFlex Limited, Lecta Group, Celplast Metallized Products, Dunmore, Japan Pulp & Paper Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallized Paper Market Strategic Shifts
Digital workflow integration is collapsing design-to-reel lead times while regulatory pressure on material circularity forces substrate architecture reinvention across premium packaging tiers.
Electron beam evaporation systems with real-time optical monitoring are digitizing thickness uniformity control across 20-50 nanometer aluminum layers. Cosmetic and confectionery brand owners in Western Europe are adopting these systems for sub-micron precision in holographic effects. This capability is digitizing quality assurance workflows that previously required offline laboratory verification, compressing batch release cycles from days to hours.
EU Packaging and Packaging Waste Regulation material recovery targets are mandating design-for-recycling protocols that disfavor adhesive-laminated constructions. Germany's national packaging regulator enforces dual sorting requirements that privilege mono-material metallized paper in yellow-bin collection streams. Premium cosmetic packaging segments in France and Italy are responding with specification shifts toward uncoated or water-based coated metallized substrates that retain optical density through repulping.
Brand owner direct specification of certified substrates is fragmenting traditional distributor channels in high-margin cosmetic and pharmaceutical verticals. Technical service relationships with metallized paper mills are displacing merchant converter intermediaries for barrier-critical applications. This pattern concentrates in Germany's Rhine-Ruhr corridor and Northern Italy's packaging belt, where brand technical teams maintain direct mill relationships for customized metallization patterns.
Metallized Paper Market Segmentation
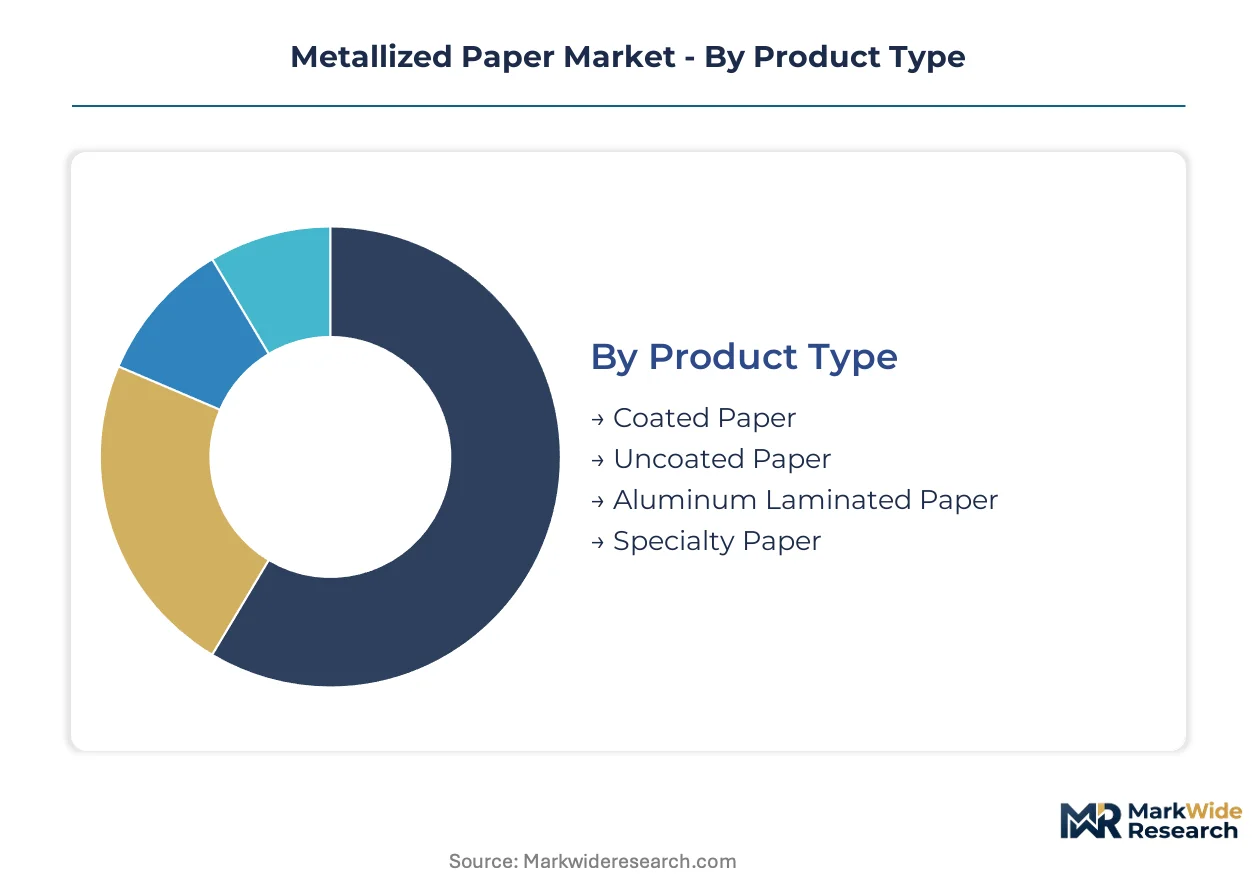
Metallized paper segmentation reveals how substrate engineering and converting technology align with end-use barrier requirements and aesthetic specifications. Product architecture and application intensity vary sharply across food-contact, cosmetic, and industrial demand clusters.
Product Type:
Mature coated substrates dominate established converting lines while emerging specialty grades capture specification premiums in regulated applications.
- Coated Paper:Cellulose substrates finished with clay or polymer coatings prior to vacuum metallization, delivering superior print receptivity and gloss uniformity. Rhine-Ruhr cosmetic converters specify these grades for short-run luxury campaigns requiring precise color matching. REACH food-contact compliance timelines concentrate demand among German and French packaging houses with validated migration protocols.
- Specialty Paper:Engineered fiber matrices with controlled porosity for pharmaceutical blister alternatives and high-barrier confectionery wraps. CDSCO and EMA tightening of child-resistance standards is accelerating qualification of metallized paper-PVC replacements in Mumbai and Ahmedabad formulation facilities. Custom metallization patterns for anti-counterfeiting serialization command 40-60% specification premiums over standard decorative grades.
- Uncoated Paper:Raw cellulose substrates metallized directly, favored for repulpability in German dual-sorting collection streams.
- Aluminum Laminated Paper:Adhesive-bonded constructions with thicker metal layers, constrained by EU Packaging and Packaging Waste Regulation material recovery targets.
Coated paper handles the majority of throughput; specialty paper is the fastest mover on share.
End User:
Cost tier stratification separates high-specification pharmaceutical and cosmetic demand from commodity food and label applications.
- Packaging:Primary demand concentration across food, beverage, and cosmetic containment formats requiring oxygen and moisture barrier performance. Germany's extended producer responsibility fee structures favor technically recyclable mono-material metallized constructions over multi-polymer laminates in yellow-bin streams. Vacuum deposition technicians in European and Japanese cohorts concentrate expertise for barrier-critical pharmaceutical specifications.
- Labels:Pressure-sensitive and wet-glue applications for beverage and consumer goods branding. Maharashtra and Gujarat coating line investments are reducing import dependency for decorative-grade substrates serving domestic FMCG label converters.
- Decoration:Gift wrap, greeting cards, and seasonal merchandise with lower barrier requirements and higher aesthetic variability.
- Stationery:Premium writing materials and corporate identity applications with specialized embossing and holographic effects.
Packaging commands the dominant value share; labels are climbing the fastest as beverage brand owners specify certified substrates directly.
Application:
Volume concentration in food-contact formats contrasts with margin extraction in cosmetic and pharmaceutical verticals.
- Food Packaging:Confectionery wraps, snack pouches, and chocolate barrier layers representing the largest metallized paper consumption by tonnage. EFSA migration thresholds and FDA food-contact frameworks require 6-18 month validation cycles that lag brand launch schedules. Electron beam evaporation with real-time optical monitoring is compressing batch release timelines from days to hours for high-throughput converting lines.
- Cosmetic Packaging:Premium skincare and fragrance boxes with customized metallization patterns and holographic effects. Western European brand technical teams maintain direct mill relationships in Northern Italy's packaging belt, displacing traditional distributor channels. Shorter run lengths and pattern customization command margin premiums of 25-35% over standard food-grade specifications.
- Beverage Packaging:Labels and secondary packaging for alcoholic and non-alcoholic drinks with moisture resistance requirements.
- Industrial Usage:Insulation facing, electronics laminates, and technical barrier applications with specification diversity.
Food packaging anchors volume throughput; cosmetic packaging shows the steepest expansion trajectory in value terms.
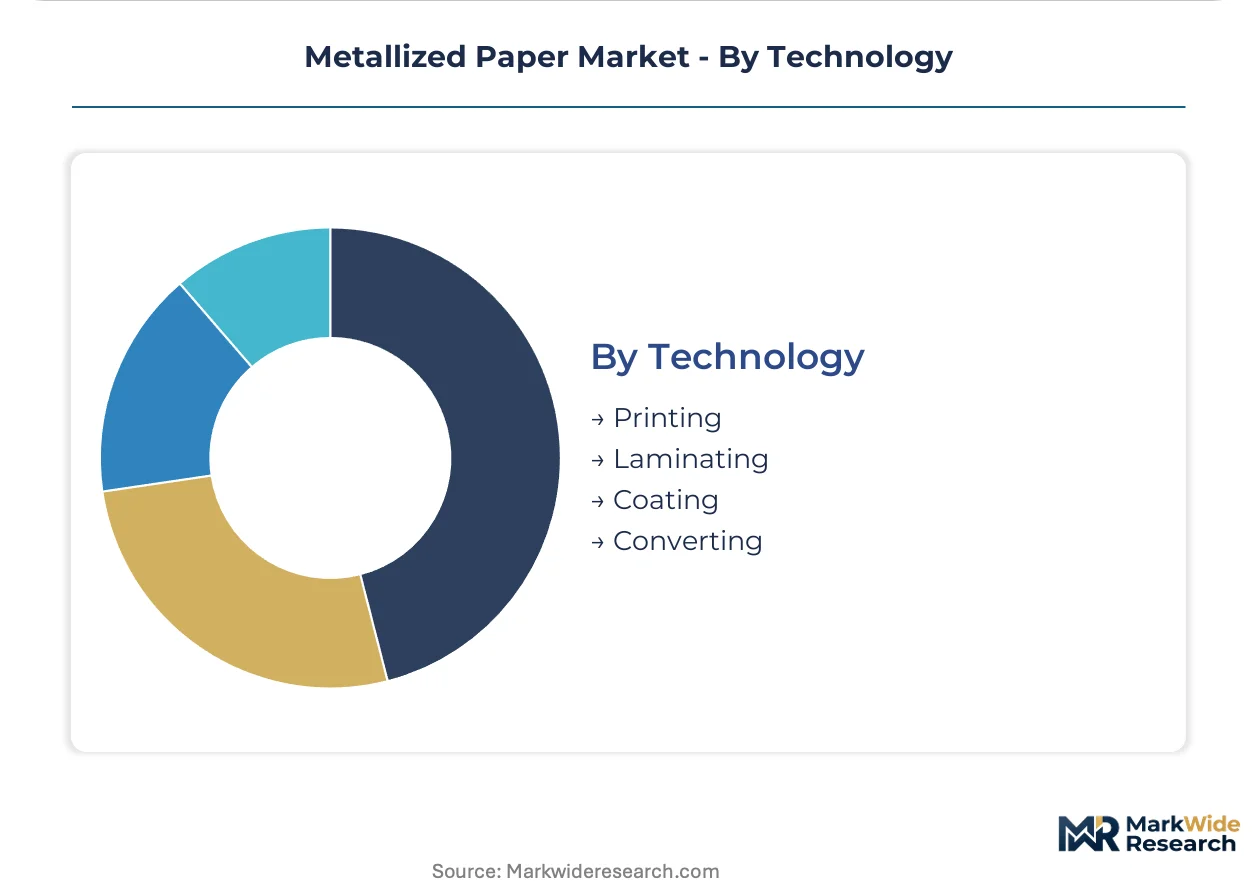
Technology:
Supply concentration in vacuum metallization expertise shapes competitive access across converting technology tiers.
- Printing:Flexographic, gravure, and offset methods adapted to metallized surface energy characteristics. Cosmetic short-run campaigns in France and Italy leverage digital workflow integration for variable-data metallic effects.
- Laminating:Adhesive and extrusion bonding processes facing regulatory pressure under EU design-for-recycling protocols.
- Coating:Pre-metallization surface preparation and post-metallization protective layers governing barrier durability.
- Converting:Slitting, sheeting, and die-cutting operations integrating metallized paper into finished packaging formats.
Printing absorbs the greatest equipment investment; coating is gaining share fastest as barrier uniformity standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Western European cosmetic brands prioritize metallized paper for sustainable luxury packaging, while South Asian markets emphasize cost-efficient decorative grades for domestic FMCG labels.
Germany
Rhine-Ruhr packaging converters drive specification shifts toward mono-material metallized constructions. The national packaging regulator enforces dual sorting requirements that privilege technically recyclable substrates in yellow-bin collection streams. Düsseldorf-based technical teams maintain direct mill relationships for customized metallization patterns in short-run cosmetic campaigns.
India
Gujarat and Maharashtra coating line investments reduce import dependency for decorative and barrier-grade substrates. CDSCO tightening of pharmaceutical packaging standards accelerates qualification of metallized paper blister alternatives. Mumbai formulation facilities increasingly specify domestic metallized substrates for solid-dose formats.
France
Premium cosmetic packaging segments respond to EU Packaging and Packaging Waste Regulation with specification shifts toward uncoated metallized substrates. ANSM evaluations of food-contact migration thresholds pressure reformulation of adhesion promoters. Northern Italy's packaging belt extends influence into French luxury brand supply chains for holographic effects.
Japan
Electronics-facing laminate demand concentrates technical precision requirements in East Asian supply chains. METI standards govern barrier uniformity for semiconductor packaging applications. Kanto region coating specialists maintain expertise in thin-film aluminum nucleation on cellulose substrates.
United States
FDA food-contact frameworks require extended validation cycles that lag brand launch schedules for metallized paper adoption. Beverage label converters in the Midwest specify certified substrates directly, fragmenting traditional distributor channels. California-based cosmetic brands pilot mono-material metallized constructions for EPR compliance positioning.
Metallized Paper Market Competitive Environment
Capability concentration sits with European and Japanese specialists; scale advantage sits with integrated Asian converters. The vendor base stratifies across three tiers: integrated pulp-to-metallization mills controlling fiber sourcing, regional coating specialists with vacuum deposition expertise, and merchant converters serving commodity label applications. Two strategic archetypes dominate: backward-integrated substrate engineers and technology-licensed regional coaters. Competitive moves center on capacity expansion in South Asian corridors and direct brand technical service relationships displacing distributor intermediaries.
Among European integrated specialists, AR Metallizing and Lecta Group exemplify the pulp-captive metallization archetype. Japanese precision engineering in electronics-facing laminates is represented by Nissha Co., Ltd. These three occupy distinct competitive positions: AR Metallizing anchors integrated coating line operations across multiple European sites, Lecta Group leverages Iberian pulp network control, and Nissha Co., Ltd. sits within the high-barrier electronics substrate tier where technical specifications command premium positioning.
| Leading Market Players |
|---|
| AR Metallizing |
| Nissha Co., Ltd. |
| Avery Dennison Corporation |
| Vacmet India Ltd. |
| UFlex Limited |
| Lecta Group |
| Celplast Metallized Products |
| Dunmore |
| Japan Pulp & Paper Company Limited |
| Others |
Value Chain & Pricing Dynamics
Germany's Rhine-Ruhr packaging cluster concentrates vacuum metallization capacity that translates into downstream pricing power for specialty-grade substrates. EU Packaging and Packaging Waste Regulation fee structures reward technically recyclable mono-material constructions, compressing margin capture for non-compliant imports while elevating domestic converter premiums.
Pricing Analysis
Western European metallized paper commands 15-25% premiums over South Asian decorative grades due to REACH compliance overhead and shorter lead times for barrier-critical pharmaceutical specifications. Three-tier pricing structure across premium, standard, and economy levels separates certified food-contact substrates from cosmetic holographic grades and commodity label stock. Cost compression in standard-grade decorative paper is intensifying because Gujarat and Maharashtra coating lines are scaling domestic capacity for Indian FMCG converters. Pharmaceutical blister packaging buyers exhibit lowest price sensitivity due to 6-18 month validation lock-in, while beverage label converters prioritize unit cost minimization.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize relationships between European metallized paper mills and Rhine-Ruhr cosmetic converters, with supply-chain finance facilities increasingly intermediating working capital. Germany, Italy, and Japan anchor global vacuum metallization expertise, while India draws from domestic aluminum feedstock and Iberian pulp networks for substrate supply. Single-source vulnerability concentrates in high-purity aluminum flake for electron beam evaporation systems, where LME price volatility transmits directly to coating line input costs. Distribution runs through direct mill relationships for premium cosmetic and pharmaceutical tiers, with merchant converters handling commodity label throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metallized paper incumbents face substitution pressure from bio-based barrier films and molded fiber alternatives that threaten premium packaging specification share. Defense requires insulating core barrier-grade revenue streams while capturing circularity premiums from regulatory arbitrage.
For Market Incumbents: Insulate pharmaceutical blister packaging relationships through CDSCO and EMA certification investments that extend validation-cycle moats against bio-film substitutes. Backward integration into Iberian pulp networks secures fiber cost stability against Asian coated paper imports. Direct technical service teams in Northern Italy's packaging belt displace distributor intermediaries for cosmetic short-run campaigns.
For New Entrants and Emerging Players: India's domestic pharmaceutical formulation facilities represent the most penetrable entry point for barrier-grade metallized paper qualification under tightening CDSCO child-resistance standards. Maharashtra and Gujarat coating line partnerships offer toll-manufacturing footholds without vacuum deposition technician scarcity constraints. Go-to-market positioning as EPR-compliant mono-material specialists targets German extended producer responsibility fee arbitrage.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated paper conglomerates with underutilized metallization assets and captive cosmetic brand relationships. Five-to-ten year viability hinges on substrate circularity credentials rather than barrier performance alone. The signal to watch is EU Packaging and Packaging Waste Regulation enforcement intensity on dual-sorting collection stream purity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Iberian fiber network control reduces input cost volatility for Lecta Group and AR Metallizing. |
| Pharmaceutical Certification Investment | CDSCO and EMA validation cycles lock in barrier-grade specifications against bio-film substitutes. |
| Digital Metallization Patterning | Laser ablation capabilities enable anti-counterfeiting serialization for Mumbai formulation facilities. |
| EPR-Compliant Mono-Material Expansion | Germany's dual-sorting requirements privilege technically recyclable substrates in yellow-bin streams. |
| Direct Brand Technical Service | Northern Italy packaging belt relationships displace distributor intermediaries for cosmetic short-runs. |
Study Parameters
Initial hypotheses were tested against primary input from vacuum deposition technicians, cosmetic packaging converters, pharmaceutical formulation facility procurement managers, and EU regulatory affairs specialists, and refined through secondary validation. Primary fieldwork combined structured interviews with coating line engineers and brand technical directors with trade data from customs records and SEC filings from publicly traded paper conglomerates. Bottom-up capacity modeling across Gujarat, Maharashtra, and Rhine-Ruhr coating lines triangulated against top-down demand estimates from EFSA migration threshold compliance timelines.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning substrate type, end-use application, barrier performance tier, and regional regulatory cluster. CAGRs were derived from installed coating line capacity expansion schedules and brand owner specification shift surveys. Industry-specific forecast inputs included EU Packaging and Packaging Waste Regulation implementation timelines and CDSCO pharmaceutical packaging standard revision cycles.
Macroeconomic conditions sit as an overlay; deviation in aluminum LME pricing, European energy costs, or Asian pulp freight rates would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity for bio-based barriers. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Pigment Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Dissolving Pulp Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Pulp and Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
Paper Machinery Market
Paper Products
Glassine Paper Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Compressed Fiberboard Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Carbonless Paper Market
Paper Products
Woodfree Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
North America Medium-Density Fiberboard Market