
 Competitive Inhibitors Market | 2026-2036
Competitive Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Competitive Inhibitors Market Analytics
Maintenance and performance-monitoring service contracts for installed inhibitor screening platforms is shifting how vendors capture recurring revenue from pharmaceutical buyers. Pfizer Inc. leverages its internal assay development infrastructure to sustain long-term client relationships beyond initial compound sales. Novartis AG anchors its competitive inhibitor portfolio through integrated discovery-to-clinic workflows across multiple therapy areas. Roche Holding AG differentiates by controlling access to proprietary high-throughput screening datasets that inform inhibitor optimization cycles.
Competitive inhibitors are molecules that structurally resemble a natural substrate and bind reversibly to the active site of an enzyme, typically achieving inhibition through nanomolar to picomolar binding affinities measured by Ki values. Their primary industrial purpose centers on drug discovery pipelines, where medicinal chemists deploy them to modulate disease-relevant enzymes with dose-dependent, recoverable activity profiles. Reversible inhibitors occupy the largest commercial position due to their favorable safety windows and established regulatory precedents across oncology and cardiovascular programs. Allosteric inhibitors represent the fastest-expanding structural category, as drug developers pursue selective targeting of regulatory sites that orthosteric compounds cannot access. Injectable formulations concentrate margin pools because parenteral delivery demands specialized stability testing, cold-chain logistics, and sterility validation that command premium pricing over oral alternatives.
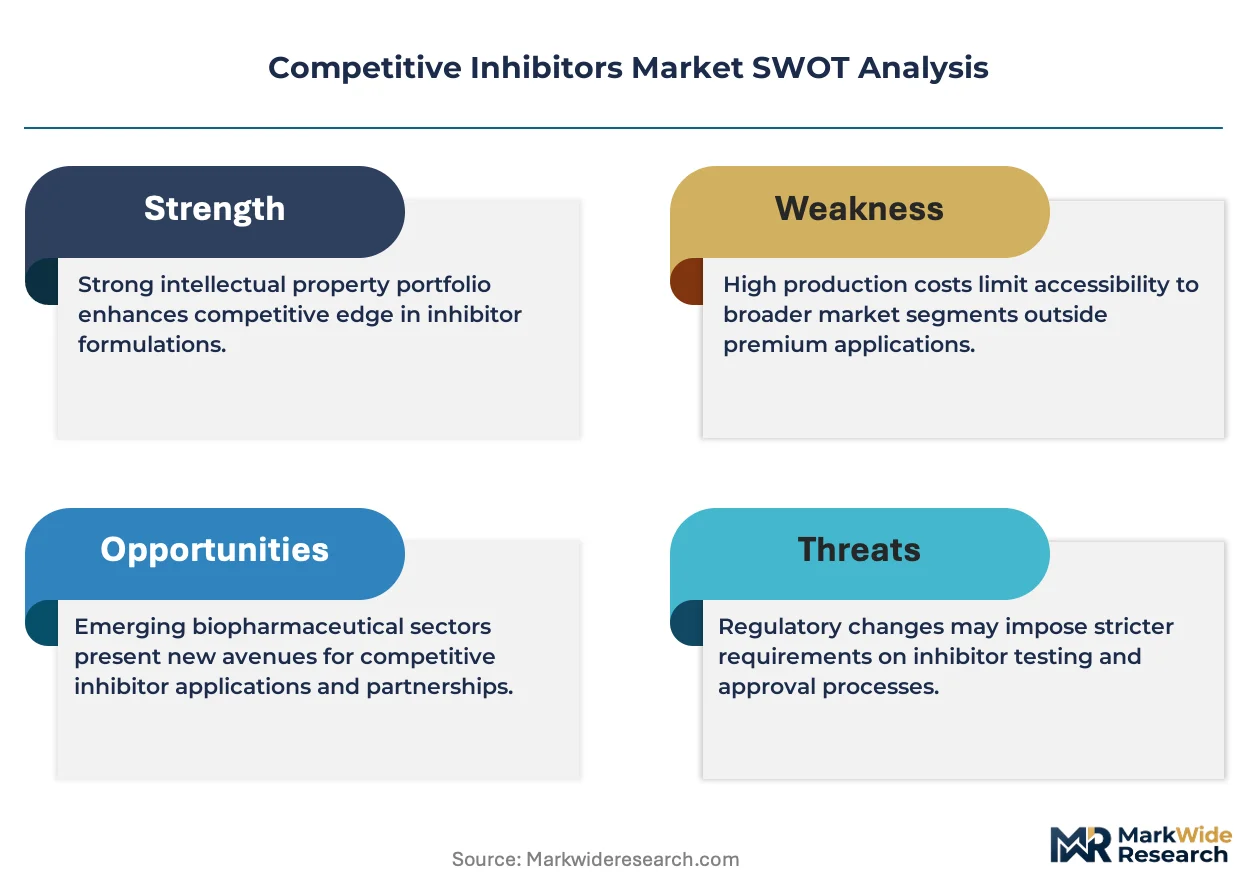
FDA's IND-enabling toxicology requirements and EMA's CHMP scientific advice procedures shape competitive inhibitor development timelines, with both agencies tightening expectations for off-target binding characterization in kinase inhibitor submissions. REACH compliance in Europe and EPA chemical substance reporting in the United States further constrain the synthetic intermediates and solvents used in inhibitor manufacturing, elevating costs for multi-step peptide and small-molecule synthesis. Stakeholders must monitor evolving pharmacovigilance obligations for reversible inhibitors, where regulatory bodies are expanding post-market surveillance requirements for immune-related adverse events in combination oncology regimens.
Market Dynamics
FDA's tightened kinase inhibitor submission standards and EMA's expanded pharmacovigilance mandates are compressing development timelines while forcing sponsors to front-load off-target binding studies, reshaping how medicinal chemistry teams prioritize scaffold selection and safety profiling.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy and EMA's PRIME designations compress Phase I-to-approval timelines for oncology inhibitors, rewarding sponsors who generate robust biomarker data early.
- Peptide Synthesis Automation:Solid-phase and flow-chemistry platforms slash cycle times for competitive inhibitor analog libraries, enabling contract manufacturers to fulfill high-throughput screening contracts at scale.
- China:NMPA's streamlined IND review procedures and domestic biotech funding pools draw Western sponsors to establish joint discovery programs with Shanghai and Suzhou-based CROs.
Market Restraints
- Specialized Starting Materials:Fluorinated aromatic intermediates and non-natural amino acids face supply concentration among German and Swiss specialty chemical houses, exposing sponsors to 12-18 month qualification timelines.
- Orthosteric Site Saturation:Kinase ATP-pocket inhibitors encounter diminishing returns as targetable space contracts, pushing programs toward riskier allosteric approaches with unvalidated pharmacology.
- REACH Compliance Costs:ECHA's expanded substance-of-very-high-concern listings force reformulation of common synthesis solvents and protecting groups, elevating manufacturing overhead for European production.
Strategic Opportunities
- Allosteric Inhibitor White Space:Regulatory sites on phosphatases and E3 ligases remain underexploited, offering first-mover advantages for platforms that solve structural biology and screening challenges.
- India:CDSCO's relaxed clinical trial approval timelines and BIS-certified CMO capacity create cost-advantaged pathways for generic competitive inhibitor development and export.
- AI-Driven Hit Expansion:Convergence of generative chemistry models and cryo-EM structural data compresses lead optimization cycles, enabling smaller discovery teams to rival large pharma output.
Industry Challenges
- Structural Biology Talent Scarcity:Crystallography and cryo-EM expertise concentrates among a handful of academic centers and contract facilities, creating bottlenecks for allosteric inhibitor programs requiring complex protein-ligand characterization.
- Multi-Territory Regulatory Divergence:Discordant FDA-EMA-PMDA expectations for immune-related adverse event reporting in combination oncology regimens force sponsors to maintain parallel safety databases and submission strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Competitive Inhibitors Market |
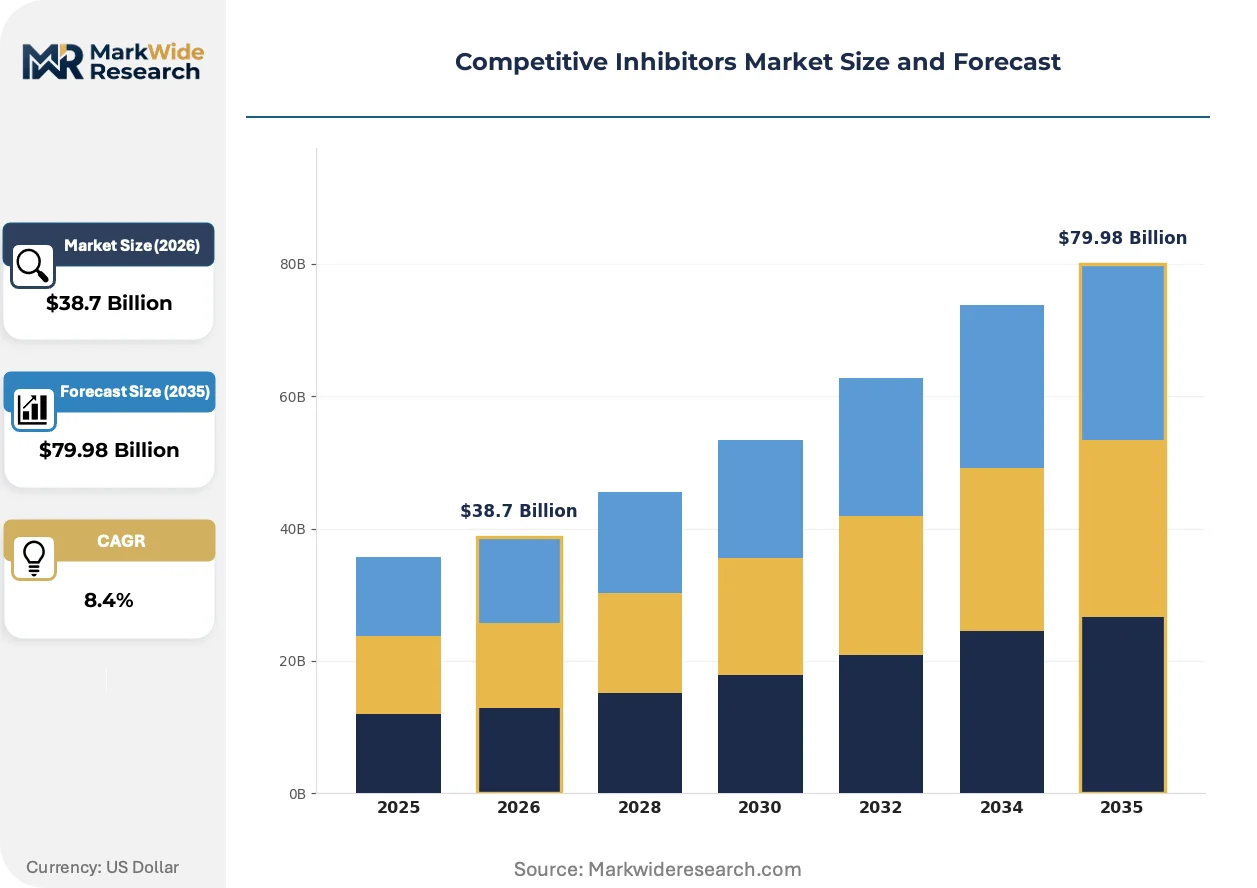
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reversible Inhibitors, Irreversible Inhibitors, Allosteric Inhibitors, Competitive Inhibitors Therapy Area: Oncology, Neurology, Infectious Diseases, Cardiovascular End User: Pharmaceutical Companies, Research Laboratories, Contract Manufacturing Organizations, Academic Institutions Formulation Type: Liquid Formulations, Solid Formulations, Injectable Formulations, Oral Formulations |
| Companies Covered | Pfizer Inc., Novartis AG, Roche Holding AG, Merck & Co., Inc., AstraZeneca PLC, GlaxoSmithKline plc, Eli Lilly and Company, AbbVie Inc., Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Competitive Inhibitors Market Evolving Landscape
Distributed computing architectures and cloud-based molecular dynamics simulations are fragmenting the competitive inhibitor discovery stack, displacing centralized supercomputing dependencies and enabling mid-tier biotechs to access previously gated capabilities.
Cryo-electron microscopy combined with structure-based design platforms is decentralizing target validation workflows. Biotech sponsors in Boston and San Diego now contract European and Asian cryo-EM facilities for rapid turnarounds, compressing the structural biology bottleneck that previously favored large pharma internal infrastructure. This capability diffusion erodes location-based competitive moats.
REACH authorization requirements for novel synthetic intermediates are tightening substance volume thresholds and elevating safety data package expectations. European CMOs absorb compliance costs into long-term supply agreements, while non-EU manufacturers face exclusion from EU-bound active pharmaceutical ingredient supply chains unless they establish REACH-authorized local entities.
Service unbundling now separates inhibitor screening platform installation from performance-monitoring contracts. Academic core facilities and mid-sized biotechs in the United States negotiate à la carte assay development and data interpretation services rather than accepting bundled multi-year commitments, pressuring vendors to demonstrate recurring value through outcome metrics rather than hardware lock-in.
Competitive Inhibitors Market Segmentation
Competitive inhibitor procurement patterns diverge sharply across molecular mechanism, therapeutic application, and manufacturing scale. Buyers in pharmaceutical discovery pipelines demand differentiated technical specifications than those in late-stage manufacturing, creating distinct segment economics that reshape vendor positioning.
Product Type:
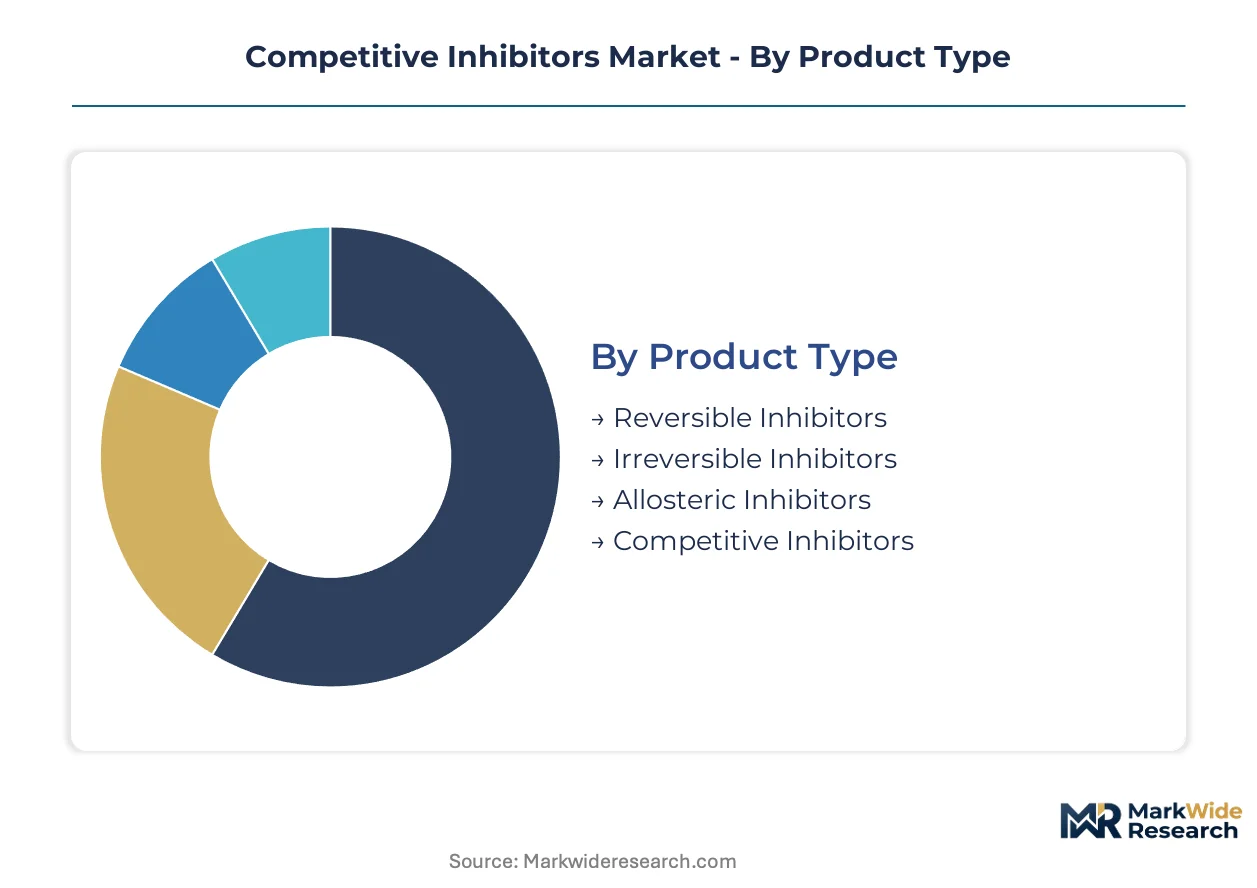
Customization intensity varies from off-the-shelf reversible inhibitors to bespoke allosteric scaffolds requiring structural biology co-development.
- Reversible Inhibitors:These compounds bind transiently to enzyme active sites through non-covalent interactions, enabling dose-titration and rapid washout in clinical settings. Demand concentrates among United States-based contract research organizations running high-throughput kinase screens, driven by FDA's preference for recoverable pharmacology in first-in-human studies.
- Allosteric Inhibitors:Regulatory site binders achieve selectivity unavailable to orthosteric competitors by exploiting conformational pockets distant from catalytic centers. Sponsors in Boston and Basel therapeutic areas prioritize these for undruggable phosphatase targets, though cryo-EM characterization bottlenecks constrain program velocity.
- Irreversible Inhibitors:Covalent warhead chemistry creates permanent enzyme inactivation. Oncology programs seeking durable target suppression drive procurement.
- Competitive Inhibitors:Substrate-mimetic structures vie directly with endogenous ligands for active site occupancy. Medicinal chemistry teams deploy these for mechanistic probe development.
Leading the category by volume: Reversible Inhibitors. Expanding most quickly: Allosteric Inhibitors.
Therapy Area:
Development risk profiles and reimbursement pathways segment demand across therapeutic domains.
- Oncology:Kinase and immune checkpoint inhibitors dominate competitive antagonist pipelines, with breakthrough therapy designations compressing timelines. United States and China sponsors account for the majority of IND filings.
- Cardiovascular:Anticoagulant and lipid-modulating enzymes represent mature targets with established safety benchmarks. European regulators maintain stringent QT-prolongation monitoring requirements.
- Neurology:Blood-brain barrier permeability constraints elevate formulation complexity for CNS-targeted inhibitors. Programs concentrate in Massachusetts and California research clusters.
- Infectious Diseases:Viral polymerase and bacterial cell-wall inhibitors face resistance surveillance obligations. Procurement fluctuates with pandemic preparedness funding cycles.
Revenue concentration peaks in Oncology. Steepest expansion trajectory: Neurology applications leveraging blood-brain barrier shuttle technologies.
End User:
Scale economies and technical capabilities stratify buyer sophistication across the value chain.
- Pharmaceutical Companies:Integrated discovery-to-commercialization infrastructure supports internal inhibitor libraries exceeding 10,000 compounds. Pfizer and Novartis maintain captive medicinal chemistry teams in Connecticut and Basel.
- Contract Manufacturing Organizations:Peptide synthesis automation and multi-kilogram GMP capacity attract sponsor outsourcing. Indian and Chinese CMOs compete on cost; Swiss and German counterparts command premium for complex stereochemistry.
- Research Laboratories:Tool compound procurement for target validation drives smaller-volume, higher-variety demand. Academic cores negotiate à la carte screening services.
- Academic Institutions:Grant-funded probe development generates episodic purchases without long-term supply commitments.
Contract Manufacturing Organizations lead procurement volume. Pharmaceutical Companies are gaining share fastest through pipeline reprioritization toward precision oncology.
Formulation Type:
Stability requirements and administration routes determine manufacturing complexity and margin structure.
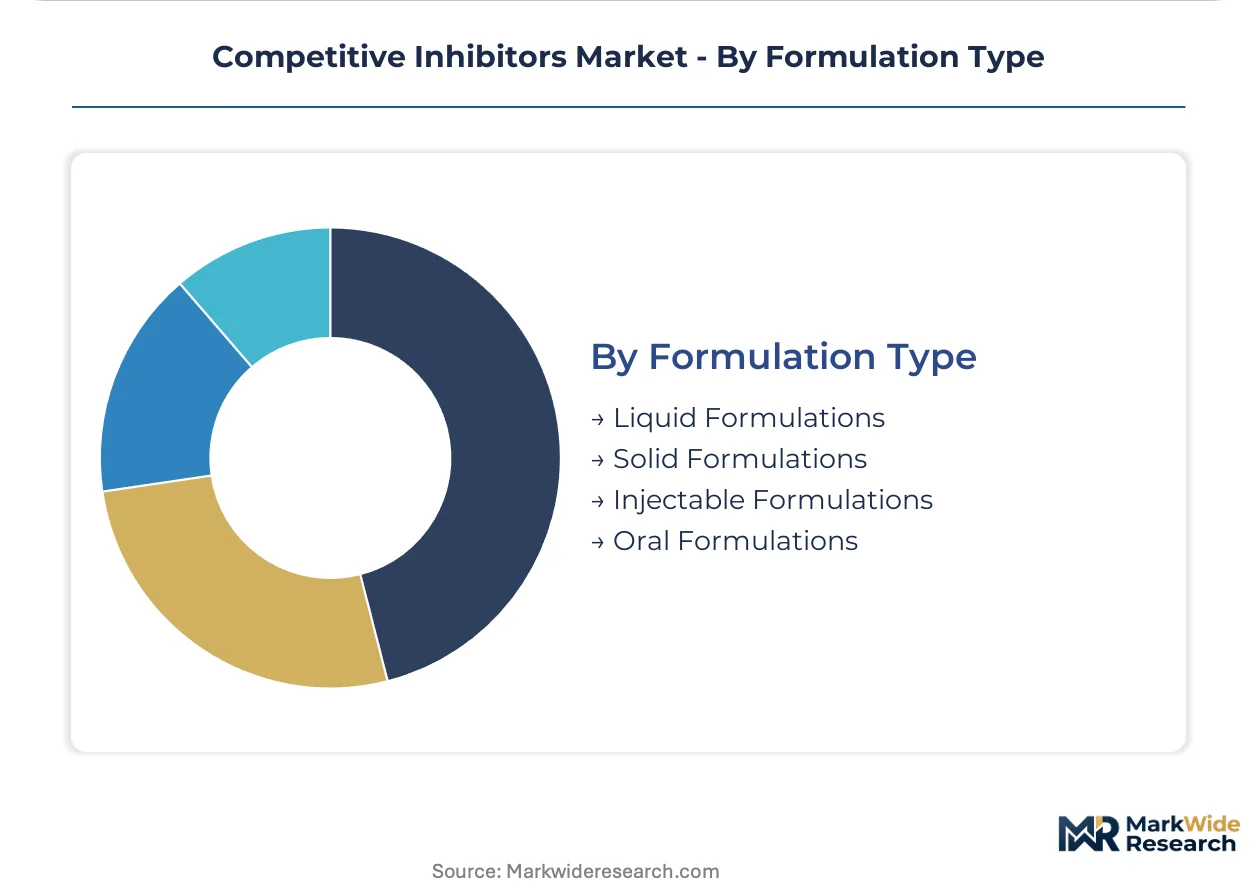
- Injectable Formulations:Parenteral delivery demands sterile processing, endotoxin testing, and cold-chain validation that elevate COGS substantially above oral alternatives. United States biotechs pay premiums for subcutaneous depot formulations enabling extended dosing intervals.
- Oral Formulations:Bioavailability optimization through salt selection and polymorph screening occupies formulation scientists. Solubility-enhancing technologies command technology transfer fees.
- Liquid Formulations:Solution stability and preservative compatibility constrain shelf-life. Used primarily for IV infusion in hospital settings.
- Solid Formulations:Tablet and capsule manufacturing scales efficiently for chronic administration. Compression and coating equipment depreciates across high-volume production runs.
Injectable Formulations dominate value capture. Oral Formulations scale fastest as sponsors pursue patient-administered chronic therapies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Diego anchor the United States competitive inhibitor discovery infrastructure, with European and Asian cryo-EM facilities now serving these clusters through remote contracting arrangements that compress structural biology timelines.
United States
FDA breakthrough therapy designations and IND-enabling toxicology requirements drive sponsor concentration in Massachusetts and California research corridors. The agency's tightened kinase inhibitor submission standards force front-loaded off-target binding studies. Cambridge-based biotechs leverage cloud-based molecular dynamics to displace supercomputing dependencies.
Germany
REACH compliance costs and ECHA substance-of-very-high-concern listings elevate manufacturing overhead for European production. EMA's CHMP scientific advice procedures shape development timelines for sponsors seeking centralized marketing authorization. Bavarian specialty chemical houses concentrate supply of fluorinated aromatic intermediates facing 12-18 month qualification timelines.
Switzerland
Swissmedic regulatory frameworks and established pharmaceutical infrastructure support integrated discovery-to-clinic workflows. Basel anchors competitive inhibitor portfolio development across multiple therapy areas. Swiss CMOs command premium pricing for complex stereochemistry in peptide synthesis automation.
China
NMPA's streamlined IND review procedures and domestic biotech funding pools draw Western sponsors to Shanghai and Suzhou-based CROs. The national pharmaceutical regulator's accelerated pathways compress Phase I-to-approval timelines for oncology inhibitors. Yangtze River Delta contract manufacturers scale peptide-based inhibitor production for export markets.
India
CDSCO's relaxed clinical trial approval timelines and BIS-certified CMO capacity create cost-advantaged pathways for generic competitive inhibitor development. The national pharmaceutical regulator's streamlined procedures attract sponsor outsourcing from Western markets. Maharashtra and Gujarat manufacturing clusters compete on cost for multi-kilogram GMP capacity.
Competitive Inhibitors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the competitive inhibitor value chain. Large pharmaceutical incumbents maintain captive medicinal chemistry infrastructure exceeding 10,000 compound libraries, while mid-tier biotechs access previously gated capabilities through distributed computing and cloud-based screening platforms. Three archetypes dominate: integrated discovery-to-commercialization houses, specialized contract manufacturers with automated peptide synthesis, and technology licensors controlling proprietary high-throughput datasets. Competitive intensity centers on M&A for cryo-EM structural biology capabilities and strategic partnerships spanning Boston-Suzhou discovery corridors.
Among integrated pharmaceutical developers, Pfizer Inc., Novartis AG, and Roche Holding AG exemplify distinct strategic positioning. Pfizer anchors its competitive inhibitor presence through internal assay development infrastructure that sustains long-term client relationships beyond initial compound transactions. Novartis occupies a position defined by discovery-to-clinic workflow integration across multiple therapy areas. Roche represents the data-control archetype, where proprietary high-throughput screening datasets inform optimization cycles and create defensive moats against asset-light competitors.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Roche Holding AG |
| Merck & Co., Inc. |
| AstraZeneca PLC |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| AbbVie Inc. |
| Bristol-Myers Squibb |
| Others |
Value Network & Pricing Analysis
Captive peptide synthesis infrastructure anchors both supply security and pricing power for competitive inhibitor manufacturers, as sponsors who control automated solid-phase production platforms in Massachusetts and Basel command premium positioning against outsourced competitors facing REACH compliance cost inflation in European supply chains.
Pricing Analysis
Margin tightening in injectable formulations reflects cold-chain validation burdens and sterility testing overhead that oral alternatives avoid. Three-tier pricing structure across GMP-certified, research-grade, and tool-compound levels stratifies buyer segments, with pharmaceutical companies showing lowest price sensitivity due to breakthrough therapy timeline pressures while academic cores negotiate aggressively on per-mg costs.
Supply Chain Analysis
REACH-authorized production status gates EU-bound active pharmaceutical ingredient flows, forcing non-European manufacturers to establish local entities or forfeit market access. Fluorinated aromatic intermediates draw from German and Swiss specialty chemical houses, while peptide synthesis automation equipment sources from United States and Japanese vendors. Single-source vulnerability concentrates in cryo-EM structural biology services. Distribution runs through CMO long-term supply agreements rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA pharmacovigilance expansion and FDA kinase inhibitor submission tightening erect barrier-to-entry moats favoring sponsors with pre-built toxicology infrastructure.
For Market Incumbents: Deepen backward integration into automated peptide synthesis platforms to deflect CMO cost escalation and capture margin pools from mid-tier biotechs lacking captive capacity. Expand cryo-EM structural biology partnerships across Boston-Suzhou corridors before talent scarcity bottlenecks allosteric program velocity. Prioritize REACH-authorized European manufacturing nodes to maintain API supply chain access against regulatory exclusion risk. For New Entrants and Emerging Players: Enter via allosteric inhibitor white space on phosphatase and E3 ligase targets where orthosteric saturation has driven large pharma toward riskier, unvalidated pharmacology. Target CDSCO-fast-tracked generic development pathways in India where BIS-certified CMO capacity enables cost-advantaged export positioning. Pursue AI-driven hit expansion as primary go-to-market angle, leveraging generative chemistry models to compress lead optimization cycles without legacy infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pharmaceutical houses seeking cryo-EM capabilities and discovery-to-clinic workflow assets. Long-term viability favors platforms solving structural biology bottlenecks with validated pharmacology on undruggable targets. Watch NMPA IND review timeline compression as signal for China joint-venture valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cryo-EM Structural Biology Acquisition | Resolves talent scarcity bottlenecks for allosteric inhibitor programs in Boston and Basel clusters. |
| REACH-Authorized EU Manufacturing Entity | Preserves API supply chain access under ECHA substance-of-very-high-concern expansion. |
| AI-Driven Hit Expansion Platform | Compresses lead optimization cycles using generative chemistry and cryo-EM structural data convergence. |
| Peptide Synthesis Automation Scale-Up | Captures high-throughput screening contract demand from United States-based CROs and biotech sponsors. |
| China Joint Discovery Program | Leverages NMPA streamlined IND review and Yangtze River Delta CMO capacity for oncology pipeline acceleration. |
Research Methodology
FDA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone for competitive inhibitor pipeline tracking and regulatory timeline analysis. Primary interviews with medicinal chemistry directors, regulatory affairs leads at kinase inhibitor sponsors, CMO procurement managers, and academic core facility directors validated scaffold selection priorities and manufacturing outsourcing patterns. Bottom-up compound library enumeration and top-down therapeutic area revenue triangulation anchored market sizing across the analysis window.
Bottom-up modeling aggregated individual program data across reversible, allosteric, and irreversible inhibitor categories, while top-down analysis cross-referenced pharmaceutical R&D expenditure flows and CMO capacity utilization. Segmentation dimensions included molecular mechanism, therapy area, end-user archetype, and formulation type, with administration route and regional regulatory cluster as additional pharma-specific stratifiers. CAGRs derived from fitted growth curves incorporating accelerated approval pathway impact and peptide synthesis automation diffusion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH authorization delays or kinase inhibitor safety-related regulatory reversals. Model outputs reflect documented assumptions on IND filing velocity and CMO qualification timelines. A model refresh is warranted upon material change in FDA-EMA pharmacovigilance divergence or cryo-EM facility capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Acidulants Market
Additives
Enzyme Stabilizer Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Plasticizer Concrete Admixtures Market
Additives
Nucleotide Premix Market
Additives
Global Low-Profile Additive Market
Additives
Europe Citric Acid Market
Additives
Crosslinking Agents Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Sorbitan Esters Market
Additives
Engine Oil Additive Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Anti-Wear Additives Market
Additives
Global Performance Additives Market
Additives
Foundry Additives Market
Additives
Global Caprylhydroxamic Acid Market