
 Global Dye Sublimation Paper Market | 2026-2036
Global Dye Sublimation Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dye Sublimation Paper Market Analysis
The EU Green Deal is expanding compliance requirements for textile chemical management across European supply chains. Neenah Coldenhove B.V. leverages its Dutch coating expertise to serve premium apparel decorators seeking REACH-certified substrates. Million Ton New Material Co., Ltd. anchors volume production through integrated pulp-to-paper operations in Shandong province. Zhejiang Jinchang Special Paper Co., Ltd. differentiates via proprietary silica barrier coatings that reduce ink bleed during high-speed rotary pressing.
Dye sublimation paper functions as a temporary carrier medium engineered with a coated receptor layer, typically silica or polymer-based, that releases disperse dyes when subjected to heat above 180°C and pressure for 30-45 seconds, enabling permanent image transfer onto polyester fabrics and polymer-coated hard substrates. Roll formats dominate commercial textile printing due to continuous-feed compatibility with wide-format inkjet systems, while sheet configurations serve the electronics segment where precision-cut aluminum panels require discrete placement. The signage application category sustains above-average growth as retail chains replace vinyl graphics with fabric-based visual merchandising that permits recycling.
REACH compliance in Europe, GB standards under China's SAMR, and EPA discharge guidelines in the United States collectively elevate barrier-coating specifications and restrict volatile solvent use in manufacturing. The EU F-Gas Regulation additionally shapes equipment choices, indirectly filtering paper specifications compatible with lower-temperature heat press systems. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these chemicals currently appear in some premium release coatings.
Market Dynamics
Coating mill concentration in China's Zhejiang province is compressing supply chains and forcing European converters to secure long-term offtake agreements for REACH-certified grades. This geographic clustering creates asymmetric pricing power and accelerates specification divergence between premium silica-barrier papers and commodity polymer-coated alternatives.
Growth Catalysts
- EU Green Deal chemical discharge rules:German sportswear manufacturers are expanding purchases of high-release sublimation papers to meet tightened textile finishing standards. This regulatory pressure is pulling premium-grade volumes across European supply chains.
- Rotary heat press adoption:Wide-format textile printers in Vietnam and Indonesia are upgrading to high-speed rotary systems that demand coated papers with reduced ink bleed. Equipment replacement cycles are shortening specification tolerance windows.
- Recyclable fabric signage:Retail chains in France and the Netherlands are replacing vinyl graphics with polyester-based visual merchandising. This material pivot requires compatible carrier papers that release cleanly without substrate contamination.
Market Restraints
- Pulp cost volatility:Integrated producers in Shandong province face margin compression when hardwood pulp prices spike. Non-integrated converters lack upstream hedging mechanisms and absorb input swings directly.
- Silica coating supply concentration:Specialty silica for barrier layers concentrates among three chemical suppliers in China. Any disruption to fumed silica production immediately restricts coating mill output in Zhejiang.
- Fluorochemical coating restrictions:Per- and polyfluoroalkyl substance bans under REACH and emerging EPA guidelines are eliminating some premium release formulations. Reformulation timelines lag regulatory enforcement dates by 18-24 months.
Strategic Opportunities
- Lower-temperature heat press compatibility:The EU F-Gas Regulation is pushing equipment manufacturers toward reduced-energy transfer systems. Paper coatings optimized for 160-170°C operation capture specification premiums in regulated markets.
- Electronics segment sheet formats:Precision-cut aluminum panels for consumer devices require discrete placement rather than roll feeding. Japanese and South Korean electronics assemblers represent underpenetrated demand for calibrated sheet products.
- Southeast Asian printing house expansion:Clustered coating mills in Zhejiang already supply Vietnamese and Indonesian converters. Direct mill relationships bypass distributor markups and accelerate delivery timelines for high-volume accounts.
Industry Challenges
- REACH certification timeline compression:European converters face 6-12 month validation cycles for new coating formulations. Batch testing delays at ECHA-recognized laboratories bottleneck product launches.
- Legacy rotary press integration:High-speed textile printers built for 200°C+ operation require mechanical retrofitting to handle lower-temperature papers. Capital expenditure decisions stall during equipment compatibility assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dye Sublimation Paper Market |
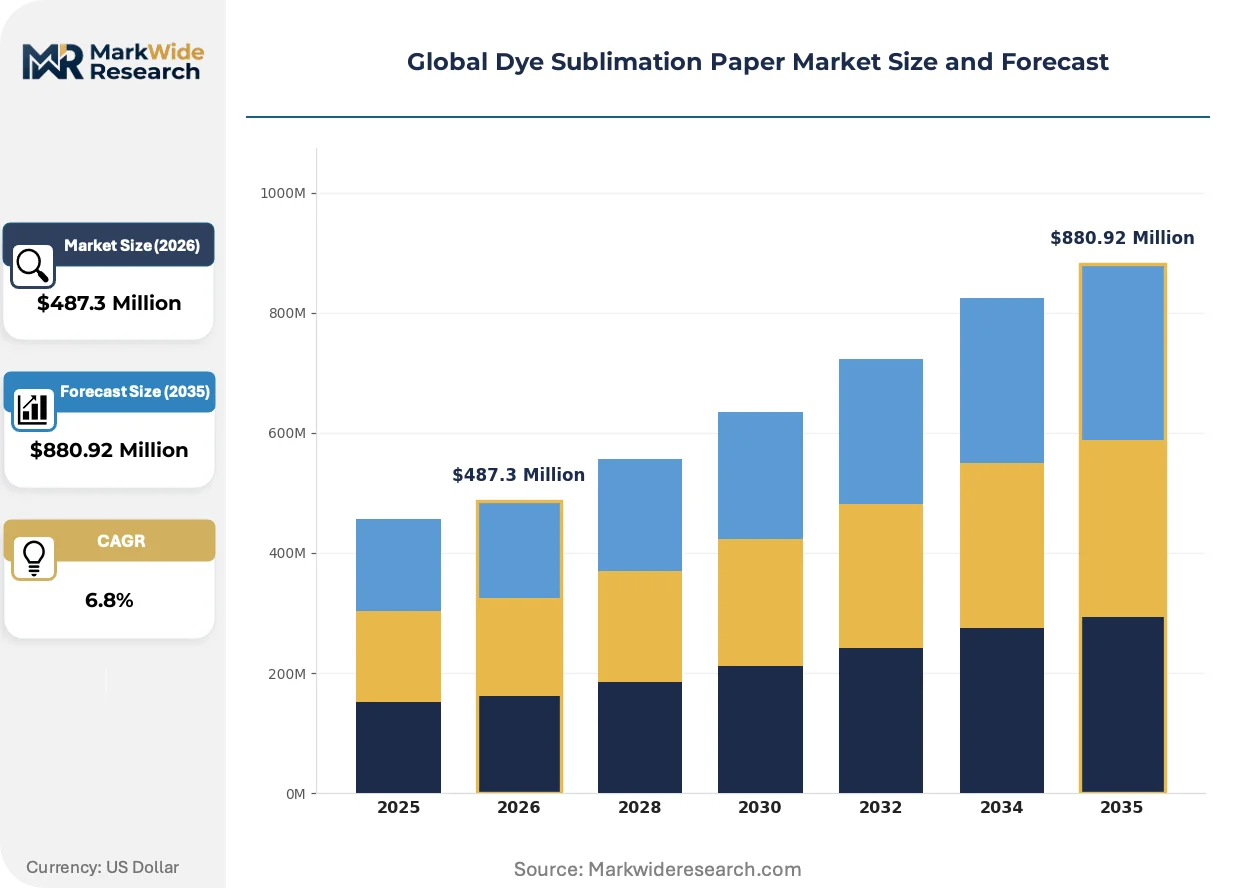
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll, Sheet, Pre-Cut, Double-Sided Application: Textiles, Electronics, Signage, Home Decor Technology: Inkjet, Laser, Thermal Transfer, Dye-Based End User: Manufacturers, Retailers, Institutions, Hobbyists |
| Companies Covered | Million Ton New Material Co., Ltd., Zhejiang Jinchang Special Paper Co., Ltd., Neenah Coldenhove B.V., Hangzhou Hydrotech Co., Ltd., Cuangyi Special Paper Co.,Ltd, Beaver Paper, Petals India Inc, Nanjing Oracle Digital Technology Co.,Ltd, Jiangyin Wellye Paper Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dye Sublimation Paper Market Emerging Trajectories
Silica-barrier coating formulations are actively displacing polymer alternatives as release performance becomes the primary purchasing criterion for high-speed textile operations. This technical pivot is compressing specification tolerance windows and rewarding proprietary coating expertise.
Proprietary silica barrier coatings with engineered pore structures are overtaking conventional polymer release layers in premium textile applications. German and Italian apparel decorators specify these formulations for high-speed rotary pressing above 200 meters per minute. The technology is overtaking commodity alternatives by eliminating ghosting defects that trigger rejection clauses in luxury brand supply agreements.
REACH restrictions on per- and polyfluoroalkyl substances are forcing coating reformulations across European supply chains. ECHA substance evaluation timelines are compressing product development cycles and eliminating legacy fluorochemical release agents. Premium apparel segments in France and Italy are responding by qualifying alternative silicone-modified silica coatings that maintain release performance without restricted substances.
Direct mill procurement is displacing distributor-mediated purchasing among large-format textile printers in Southeast Asia. Vietnamese and Indonesian converters with monthly volumes above 50,000 square meters are establishing direct offtake relationships with Zhejiang coating mills. This channel compression is most visible in Ho Chi Minh City and Jakarta, where landed cost advantages of 8-12 percent are restructuring regional supply relationships.
Global Dye Sublimation Paper Market Segmentation
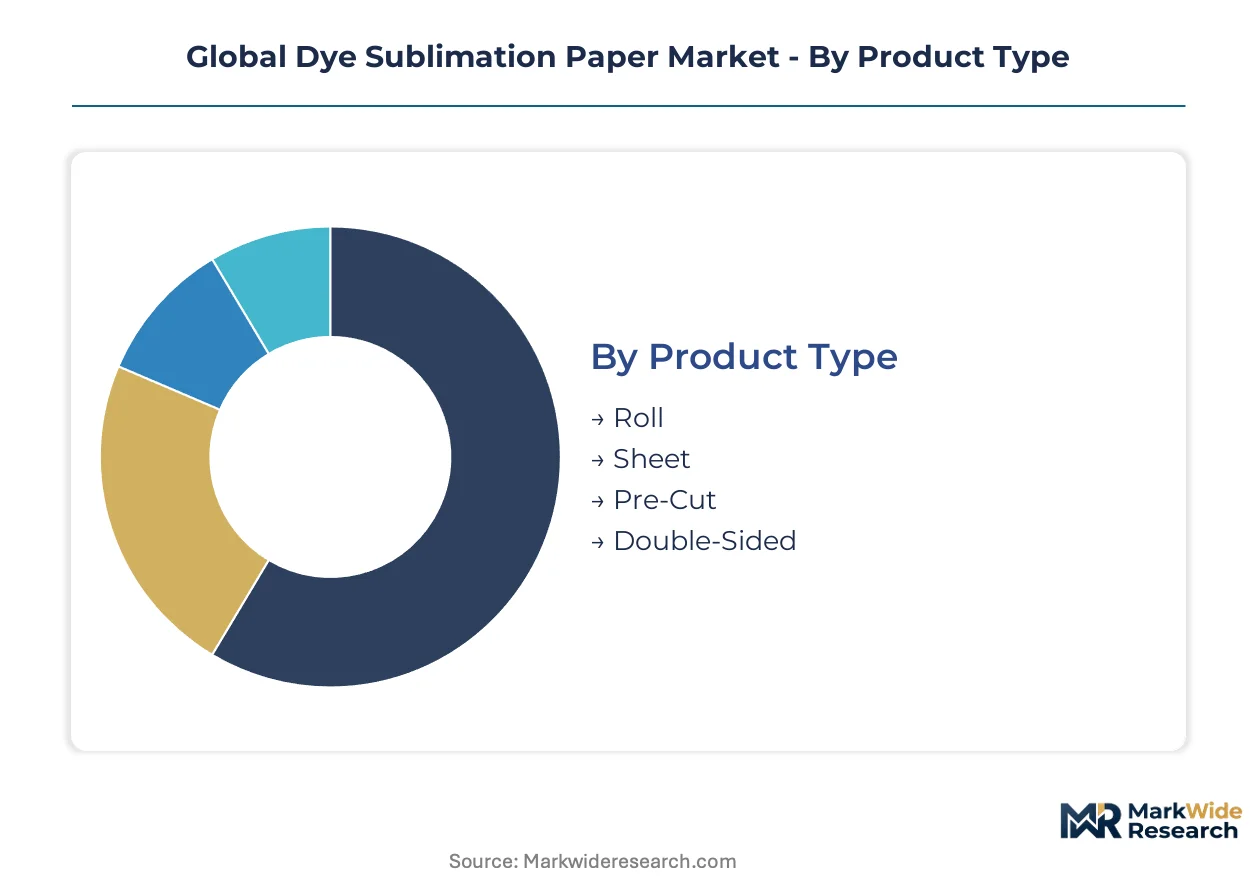
Segmentation in dye sublimation paper reveals how coating chemistry, format geometry, and end-use thermal requirements create distinct specification tiers. Each dimension carries different margin profiles and regulatory exposure, forcing suppliers to prioritize development resources across incompatible technical paths.
Product Type:
Volume concentration sits with roll formats serving continuous-feed textile operations, while premium pricing attaches to specialized geometries for precision manufacturing.
- Roll:Continuous-web construction enables high-speed rotary heat press feeding at speeds exceeding 200 meters per minute. German and Italian apparel decorators specify these for luxury brand contracts where ghosting defects trigger rejection clauses.
- Sheet:Discrete cut dimensions serve electronics assemblers in Japan and South Korea mounting precision-cut aluminum panels. Discrete placement requirements in consumer device manufacturing resist automation and sustain calibrated product premiums.
- Pre-Cut:Dimensionally finished sheets eliminate converter cutting operations for small-batch decorators and hobbyist segments. Ready-to-press formats reduce setup waste in retail customization shops.
- Double-Sided:Dual receptor coatings enable simultaneous two-sided image transfer for symmetrical textile applications. Specialized sportswear manufacturers in Germany utilize these for uniform interior branding.
Today's leader: Roll. Tomorrow's challenger: Sheet.
Application:
Margin structure inverts between high-volume textile decoration and specification-intensive electronics transfer, with signage emerging as a recycling-driven growth corridor.
- Textiles:Polyester fabric decoration dominates tonnage consumption across Zhejiang coating mill output. REACH-certified grades command specification premiums in EU supply chains tightening chemical discharge rules.
- Signage:Fabric-based visual merchandising displaces vinyl graphics in French and Dutch retail chains. Recyclable polyester substrates require compatible carrier papers releasing without contamination.
- Electronics:Polymer-coated hard substrates demand precision release characteristics for aluminum and glass panel decoration. Japanese electronics assemblers represent underpenetrated demand for calibrated sheet formats.
- Home Decor:Ceramic, metal, and wood sublimation applications utilize lower-temperature coating formulations. Consumer personalization trends drive hobbyist channel volume.
Textiles anchor current revenue. Signage climbs the fastest on sustainability mandates.
Technology:
Equipment replacement cycles in Southeast Asian printing houses are shortening specification tolerance windows and favoring coating formulations compatible with emerging printhead chemistries.
- Inkjet:Piezoelectric drop-on-demand systems dominate wide-format textile printing across Vietnamese and Indonesian converter installations. High-release silica barrier coatings reduce ink bleed during high-speed rotary pressing.
- Laser:Toner-based transfer systems serve industrial marking applications requiring durability under mechanical stress. Lower temperature requirements align with EU F-Gas Regulation equipment trends.
- Thermal Transfer:Ribbon-fed systems persist in barcode and label decoration where color range requirements remain narrow. Legacy equipment bases in institutional segments sustain residual demand.
- Dye-Based:Aqueous disperse ink formulations dominate environmentally regulated European markets. SAMR GB standards in China similarly constrain solvent-based alternatives.
Inkjet holds installed base dominance. Dye-based formulations gain on regulatory filtration.
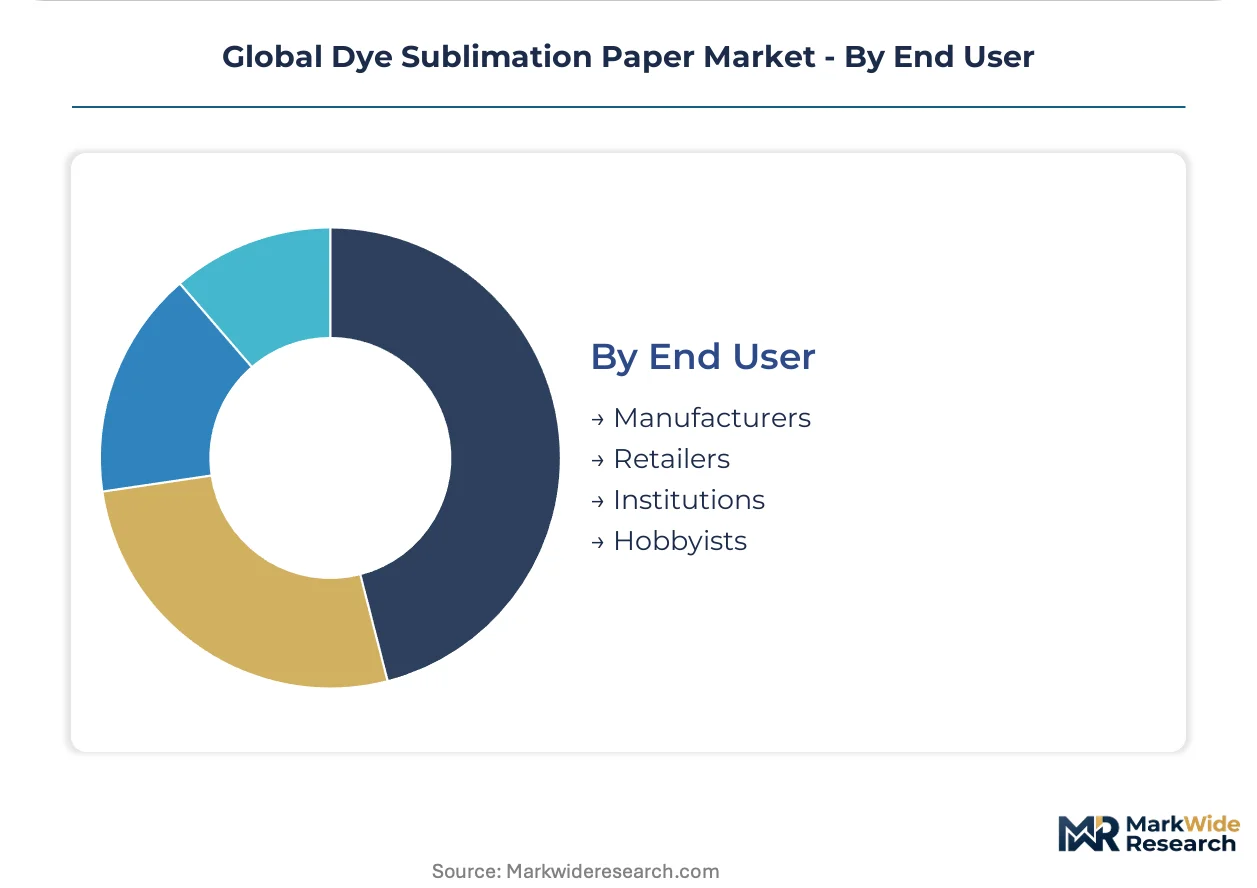
End User:
Procurement scale and technical sophistication create four distinct customer archetypes with incompatible service requirements and pricing expectations.
- Manufacturers:Integrated textile producers and electronics assemblers purchase through direct mill relationships bypassing distributor markups. Monthly volumes above 50,000 square meters qualify for offtake agreements with Zhejiang coating mills.
- Retailers:Customization shops and visual merchandising chains require just-in-time delivery and format flexibility. Channel compression is visible in Ho Chi Minh City and Jakarta where landed cost advantages restructure supply relationships.
- Institutions:Educational and governmental procurement operates through formal tender processes with extended qualification timelines. REACH certification documentation requirements extend sales cycles.
- Hobbyists:Consumer segments purchase through distributor and e-commerce channels in small lot sizes. Pre-cut formats and starter kits reduce technical barriers to entry.
Manufacturers concentrate volume power. Retailers are reshaping channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating technology for dye sublimation paper originated in European paper finishing traditions before migrating to East Asian manufacturing clusters. The Netherlands developed early silica-barrier expertise that now competes with integrated pulp-to-paper operations in China's Shandong province. Today's supply geography reflects this bifurcation between REACH-certified European converters and high-volume Zhejiang coating mills.
China
Shandong province anchors integrated pulp-to-paper production through captive hardwood supply chains. SAMR GB standards constrain solvent-based coating chemistries and favor aqueous disperse ink compatibility. Zhejiang's clustered coating mills in Shaoxing and Jinhua supply both domestic apparel exporters and Southeast Asian printing houses with high-release formulations.
Germany
Custom sportswear manufacturers in Bavaria and North Rhine-Westphalia are expanding purchases of high-release sublimation papers. The EU Green Deal tightens chemical discharge rules for textile finishing under ECHA enforcement timelines. Stuttgart-based apparel decorators specify REACH-certified substrates for luxury brand contracts with zero-tolerance ghosting clauses.
Netherlands
Premium apparel decorators in Amsterdam and Rotterdam seek Dutch coating expertise for complex polyester transfers. The EU F-Gas Regulation pushes equipment choices toward lower-temperature heat press systems. Eindhoven-region technical paper converters leverage historical coating knowledge to serve specification-intensive EU supply chains.
Vietnam
Wide-format textile printers in Ho Chi Minh City upgrade to high-speed rotary systems demanding reduced ink bleed. Direct mill procurement from Zhejiang suppliers compresses distributor markups by 8-12 percent. Vietnamese converters with monthly volumes above 50,000 square meters now establish direct offtake relationships bypassing regional distributors.
Japan
Electronics assemblers in Kanto and Kansai regions represent underpenetrated demand for calibrated sheet formats. Precision-cut aluminum panels for consumer devices require discrete placement rather than roll feeding. METI industrial standards shape coating specifications for polymer-coated hard substrate decoration.
Global Dye Sublimation Paper Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent capability requirements. Integrated pulp-to-paper operations in Shandong province command upstream cost advantages during hardwood price spikes. Three archetypes dominate: vertically integrated Chinese mills with captive pulp supply, European coating specialists with REACH certification infrastructure, and Southeast Asian converters building direct mill relationships. Competitive dynamics center on capacity expansion in Zhejiang and strategic partnerships securing silica coating supply.
Among Chinese integrated producers, Million Ton New Material Co., Ltd. and Zhejiang Jinchang Special Paper Co., Ltd. exemplify the scale-driven archetype with Shandong and Zhejiang geographic anchors respectively. Neenah Coldenhove B.V. represents the European specialist tier with Dutch coating expertise serving premium apparel decorators. These three occupy positions across the specification spectrum from commodity polymer-coated volumes to REACH-certified silica-barrier grades.
| Leading Market Players |
|---|
| Million Ton New Material Co., Ltd. |
| Zhejiang Jinchang Special Paper Co., Ltd. |
| Neenah Coldenhove B.V. |
| Hangzhou Hydrotech Co., Ltd. |
| Cuangyi Special Paper Co.,Ltd |
| Beaver Paper |
| Petals India Inc |
| Nanjing Oracle Digital Technology Co.,Ltd |
| Jiangyin Wellye Paper Industry Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Coating chemistry expertise concentrated in the Netherlands and Germany creates labor-cost differentials that widen pricing spreads between REACH-certified premium grades and commodity polymer-coated volumes from Shandong province. European converters absorb higher formulation labor costs while Zhejiang mills exploit clustered technical workforce pools to compress standard-tier pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silica-barrier REACH-certified grades from polymer-coated mid-tier volumes and uncoated base papers. Price differentiation hinges on certification tier and volume scale, with German sportswear manufacturers least sensitive and Southeast Asian hobbyist channels most reactive to per-square-meter fluctuations. Cost compression in the standard tier intensifies because hardwood pulp volatility transmits directly through non-integrated converters lacking upstream hedging.
Supply Chain Analysis
Regional distribution centers in Ho Chi Minh City and Jakarta operate hub-and-spoke patterns feeding Vietnamese and Indonesian printing houses. Geographic supply concentration centers on China, with Shandong province anchoring integrated pulp-to-paper operations and Zhejiang hosting clustered coating mills. Raw material dependencies draw from hardwood pulp supply, fumed silica for barrier formulations, and aqueous coating chemistries. Single-source vulnerability in specialty silica concentrates among three Chinese chemical suppliers. Distribution runs through direct mill relationships for high-volume accounts and distributor networks for fragmented retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Dye Sublimation Paper Market functions as a stable compounder, with regulatory filtration of coating chemistries under REACH and emerging EPA guidelines sustaining steady specification-upgrade cycles across replacement demand.
For Market Incumbents: Anticipate fluorochemical coating bans by accelerating silicone-modified silica reformulation timelines ahead of ECHA enforcement dates. Prioritize capacity addition in Zhejiang to capture Southeast Asian direct procurement shifts. Defend against margin erosion by securing long-term offtake agreements with German apparel decorators before REACH certification bottlenecks intensify.
For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for lower-temperature coating formulations compatible with reduced-energy heat press systems. Target the electronics segment sheet format demand in Japan and South Korea, where precision-cut aluminum panel decoration remains underpenetrated by calibrated products. Establish go-to-market positioning through METI standards compliance to access Kanto-region assemblers.
For Investors and Strategic Acquirers: Specialty chemicals firms with coating expertise are the most active acquirer in this space, seeking REACH certification infrastructure to extend formulation portfolios. Long-term viability rests on regulatory compliance capabilities rather than commodity scale. Watch for silica coating supply disruptions as inflection indicators that would trigger consolidation among Zhejiang mills dependent on concentrated chemical suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | ECHA-recognized laboratory validation unlocks premium pricing in EU supply chains tightening chemical discharge rules. |
| Backward Integration into Hardwood Pulp | Captive supply in Shandong province insulates margin compression during global pulp price spikes. |
| Lower-Temperature Formulation Development | EU F-Gas Regulation compatibility captures specification premiums from equipment manufacturers reducing energy transfer systems. |
| Direct Mill Relationship Expansion | Bypassing distributor markups in Ho Chi Minh City and Jakarta captures 8-12 percent landed cost advantages. |
| Silicone-Modified Silica Coating Transition | Eliminating restricted fluorochemicals maintains release performance for French and Italian luxury brand contracts. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating mill technical directors, German apparel decorator procurement leads, Zhejiang distribution channel partners, and ECHA regulatory affairs specialists with secondary validation. Sources included customs and trade data from Chinese pulp imports, SEC filings from integrated paper producers, SAMR GB standard documentation, and ECHA substance evaluation timelines. Bottom-up mill capacity aggregation and top-down end-use demand estimation provided cross-verification.
Historical reference periods anchored volume and value trajectories across the modeling period, with segmentation dimensions covering coating chemistry tier, format geometry, application thermal requirements, and regional regulatory clusters. CAGRs emerged from fitted growth curves applied to verified baseline data. Forecast inputs incorporated equipment replacement cycles in Southeast Asian printing houses and REACH reformulation lag times affecting premium grade availability.
Revisions become necessary when silica coating supply disruptions, hardwood pulp price spikes, or accelerated fluorochemical bans materialize beyond modeled timelines. Forecasts reflect documented assumptions about regulatory enforcement schedules and equipment adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Household Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Paper Glass Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Pharma Grade Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Fluff Pulp Market
Paper Products
Clay Coated Paper Market
Paper Products
Glassine Paper Market
Paper Products
Softwood Pulp Market
Paper Products
Filtration Paper Market
Paper Products
Acrylic Paper Market
Paper Products
Sanitary Paper Products Market