
 Printing Paper Market | 2026-2036
Printing Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Printing Paper Market Intelligence
The proliferation of high-speed digital inkjet technology is rewriting the requirements for paper substrates, demanding new surface treatments and absorption characteristics. Major producers are responding to this shift. International Paper Company leverages its scale to develop specialized papers for digital presses. UPM-Kymmene Corporation differentiates through its portfolio of sustainable and lightweight coated papers suitable for high-volume digital printing. Sappi Limited focuses on premium coated grades for graphic-intensive applications.
Printing paper consists of processed cellulose fibers, engineered to specific grammage, brightness, and opacity levels. Its primary function is to serve as a stable and receptive substrate for the transfer of ink or toner in various printing processes. While uncoated paper continues to dominate office use and publishing by volume, coated paper commands higher margins in commercial printing. The packaging application represents the fastest-growing vector, particularly for specialty papers designed for branding and product information.
Producers must navigate a complex web of environmental regulations. The EU Green Deal and its Corporate Sustainability Reporting Directive (CSRD) mandate transparent sourcing, while US Environmental Protection Agency (EPA) guidelines encourage recycled content. China's dual carbon goals impact energy use and emissions within its pulp and paper industry. Successfully balancing raw material sustainability, compliance costs, and the performance demands of new printing technologies remains the central strategic challenge for all manufacturers.
Market Dynamics
The printing paper market is defined by the structural tension between accelerating digital media substitution and rising demand for sustainable, fiber-based materials in packaging. This dual pressure forces producers to simultaneously innovate for new print technologies while overhauling supply chains for environmental transparency.
Growth Catalysts
- E-commerce Packaging Demand:The expansion of e-commerce necessitates a greater volume of paper-based secondary and tertiary packaging, often requiring high-quality printing for branding and logistics information, which supports demand for specific paper grades.
- Digital Inkjet Substrates:The proliferation of high-speed production inkjet presses creates a distinct demand category for papers with specialized surface treatments and absorption properties, driving new product development.
- Sustainable Sourcing Mandates:Corporate ESG policies and consumer preferences for certified products are elevating the value of papers with verifiable supply chains, such as those with Forest Stewardship Council (FSC) or PEFC certification.
Market Restraints
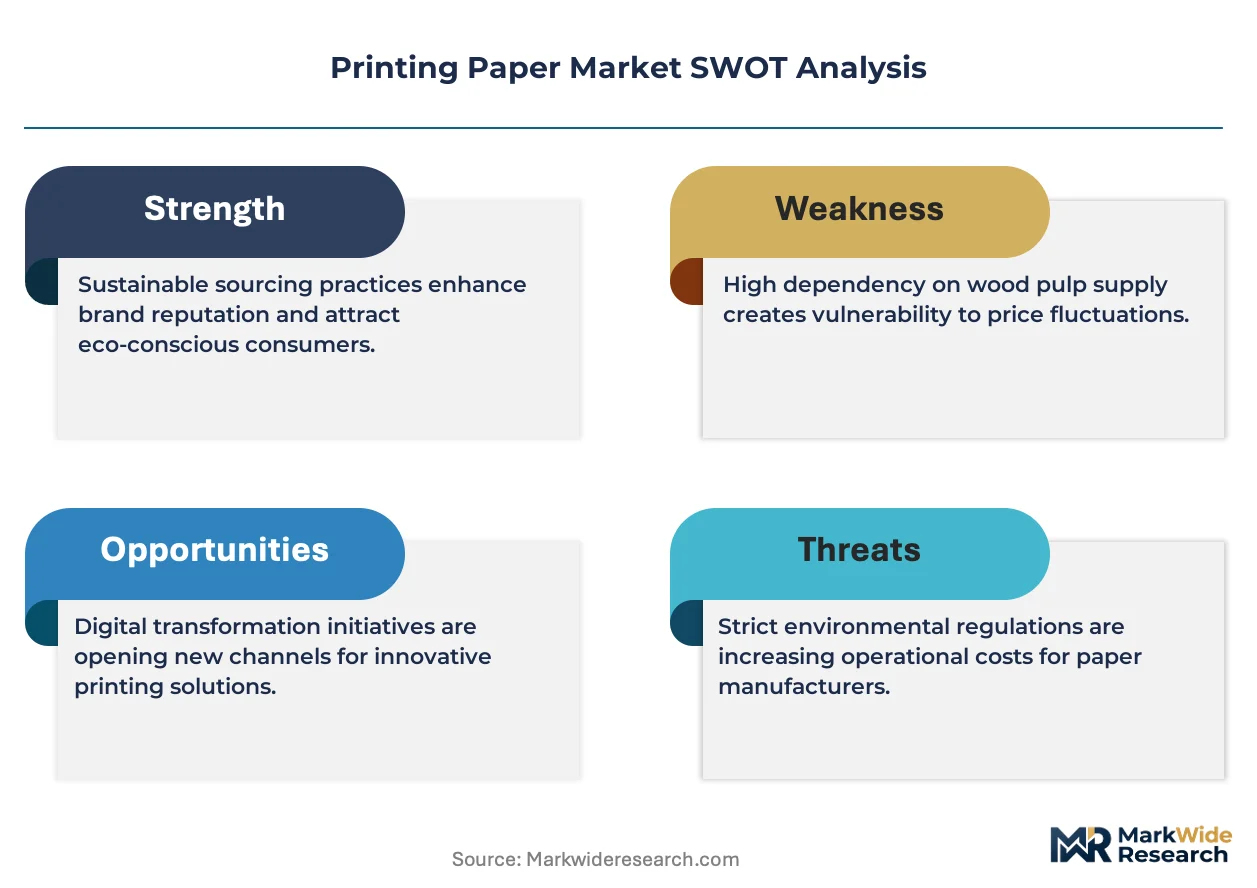
- Pulp and Energy Volatility:Manufacturer margins are directly exposed to price fluctuations in key inputs, including wood pulp, recycled fiber, and the energy required for milling processes, creating significant cost uncertainty.
- Digital Media Substitution:The ongoing shift to paperless communication in office environments and digital formats for traditional publishing directly erodes demand for conventional office and publication paper grades.
- Regulatory Compliance Burden:Navigating a fragmented global landscape of environmental rules, from the EU's Corporate Sustainability Reporting Directive (CSRD) to US EPA guidelines, increases operational costs and complexity.
Strategic Opportunities
- Functional Paper Development:An opportunity exists in engineering papers with enhanced properties, such as barrier coatings for food packaging or embedded conductivity for smart labels, opening new value-added applications.
- Commercial Printing in India:Expanding commercial and educational sectors in India represent a significant geographic opportunity, where demand for printed materials continues to grow counter to trends in more mature economies.
- Recycled Fiber Innovation:Advances in de-inking and processing technologies for recycled pulp enable the creation of higher-brightness and stronger papers, allowing recycled content to penetrate more demanding, premium applications.
Industry Challenges
- High Capital Reinvestment:Converting or upgrading paper machines to produce different grades or meet stricter environmental standards requires substantial capital expenditure, posing a significant hurdle for smaller producers.
- Logistical Network Adaptation:The decline in large, centralized orders for publication paper and the rise of decentralized, just-in-time demand for packaging and commercial print require a complete overhaul of legacy distribution models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printing Paper Market |
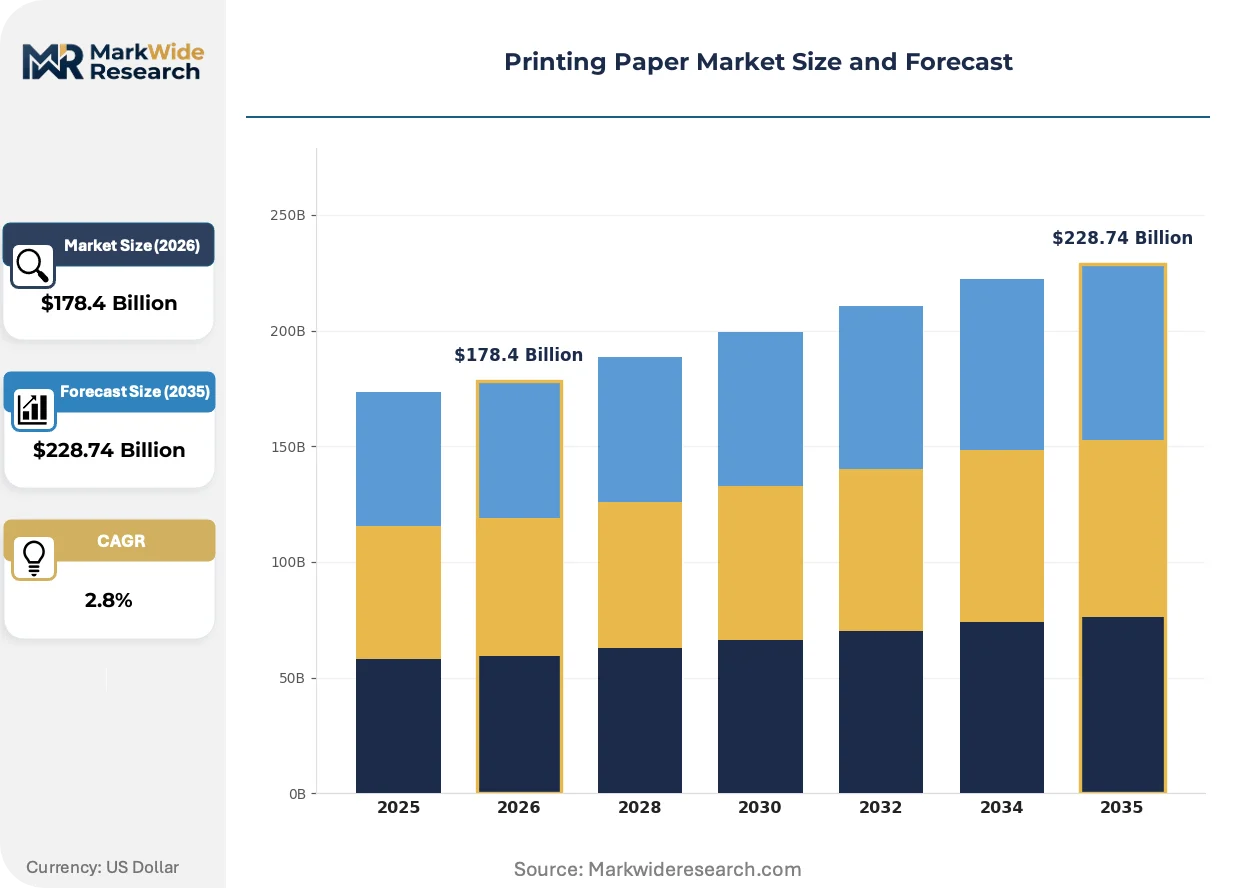
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $228.74 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Bond Paper, Recycled Paper, Specialty Paper Application: Commercial Printing, Publishing, Packaging, Photographic Printing, Office Use End User: Corporate Offices, Educational Institutions, Government Agencies, Print Shops, Advertising Agencies Packaging Type: Sheet, Roll, Reels, Bundled Packs, Bulk Packs |
| Companies Covered | Stora Enso Oyj, UPM-Kymmene Corporation, International Paper Company, Sappi Limited, Mondi plc, WestRock Company, Asia Pulp & Paper Co., Ltd., Sylvamo Corporation, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printing Paper Market Strategic Shifts & Innovations
Intensifying environmental scrutiny and the maturation of digital printing are the primary forces acting on the printing paper market. These trends compel manufacturers to innovate in both material science and supply chain management, shifting the basis of competition from pure volume to specialized performance and sustainability credentials.
High-Speed Production Inkjet High-speed production inkjet technology delivers cost-effective, variable-data printing at volumes that were previously exclusive to offset lithography. Commercial printers and direct mail houses are rapidly adopting this equipment for applications ranging from books to transactional statements. This technological shift is collapsing the historical divide between offset quality and digital flexibility, forcing paper mills to engineer new substrates with precise ink absorption and surface characteristics.
China's Dual Carbon Policy China's national "dual carbon" policy establishes ambitious targets for reaching peak carbon emissions and achieving carbon neutrality. This framework is driving significant energy efficiency upgrades and a transition away from coal-fired power within the nation's vast pulp and paper industry. The policy disproportionately impacts older, less efficient mills and influences global pulp procurement as Chinese manufacturers seek lower-carbon raw material inputs to meet compliance mandates.
Certification-Driven Procurement Corporate buyers are increasingly standardizing their paper procurement policies to require verifiable proof of sustainable sourcing, most commonly through Forest Stewardship Council (FSC) or Programme for the Endorsement of Forest Certification (PEFC) credentials. This trend disrupts traditional purchasing decisions based purely on price, elevating certification to a critical market access requirement. This shift is most pronounced in North America and Europe, particularly for corporate reporting and marketing collateral.
Printing Paper Market Segmentation
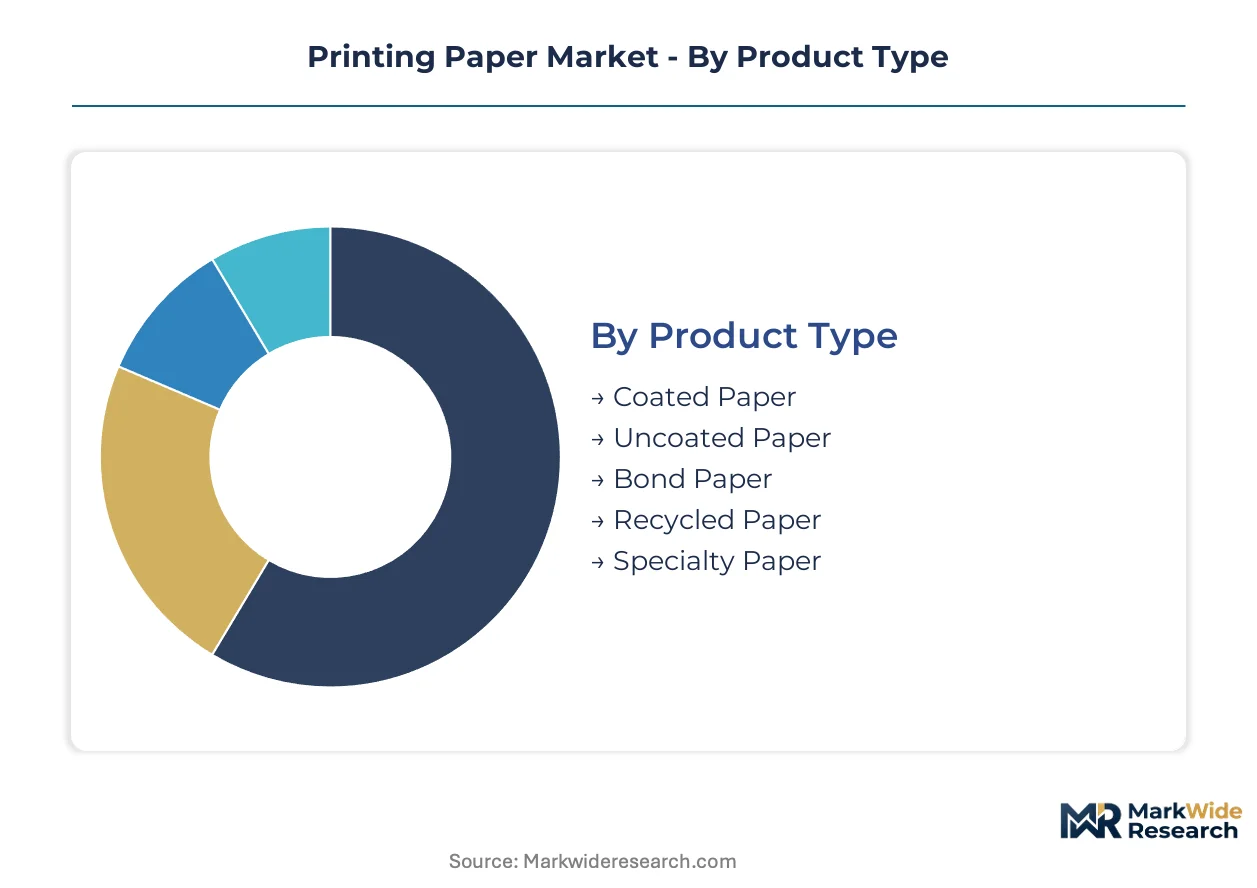
The printing paper market differentiates across distinct product types and applications, reflecting the varied demands of commercial, industrial, and consumer end-users. Understanding these segmentation nuances is critical for manufacturers to align production capabilities with evolving market needs and regulatory pressures. Each segment responds uniquely to technological advancements and sustainability mandates.
Product Type:
The market's product offerings span a broad use-case spectrum, from everyday communication to highly specialized industrial applications.
- Coated Paper:This paper features a surface coating, often clay-based, that enhances brightness, smoothness, and ink holdout, critical for high-quality graphic reproduction in magazines and brochures. Demand concentrates in commercial printing and advertising, driven by the need for vibrant imagery and sharp text.
- Recycled Paper:Manufactured from post-consumer or pre-consumer waste fibers, this paper addresses environmental concerns and regulatory mandates for sustainable sourcing. Its demand is increasing across corporate and government sectors, influenced by ESG policies and consumer preference for eco-friendly products.
- Uncoated Paper:Lacking a surface coating, this paper offers a natural, often more porous, finish, widely used for writing, textbooks, and general office documents.
- Bond Paper:Characterized by its strength and durability, bond paper is typically used for stationery, letterheads, and official documents requiring a professional feel.
- Specialty Paper:This category includes papers engineered for specific functional properties, such as barrier coatings for food packaging or thermal sensitivity for labels, opening new value-added applications.
Established volume favors Uncoated Paper; emerging adoption favors Recycled Paper.
Application:
Printing paper consumption is driven by diverse application focuses, each with distinct quality and volume requirements.
- Packaging:This segment involves paper and paperboard used for primary, secondary, and tertiary packaging, often requiring high-quality printing for branding and product information. The expansion of e-commerce necessitates a greater volume of paper-based packaging, particularly in markets like India.
- Commercial Printing:This application includes brochures, catalogs, direct mail, and marketing collateral, demanding high-quality substrates suitable for both offset and digital printing technologies. The proliferation of high-speed digital inkjet presses creates distinct demand for specialized papers in this sector.
- Publishing:This category encompasses newspapers, magazines, books, and journals, primarily using uncoated and lightweight coated papers. Digital media substitution continues to erode demand for traditional print publications in mature economies.
- Office Use:Standard copy paper, stationery, and internal documents constitute this segment, which faces direct erosion from the ongoing shift to paperless communication.
- Photographic Printing:This niche application demands highly specialized, often coated, papers with specific absorbency and color reproduction properties for high-fidelity image output.
The highest growth rates are observed in Packaging, while Commercial Printing maintains stable demand.
End User:
The end-user landscape for printing paper reflects varied purchasing patterns and material specifications across different customer types.
- Print Shops:These entities are direct consumers of bulk paper, serving commercial, publishing, and individual client needs, often requiring a wide range of paper types. Print shops navigate the shift from offset to digital technologies, influencing their paper procurement.
- Corporate Offices:Businesses utilize printing paper for internal documents, reports, and marketing materials, with procurement increasingly influenced by sustainability policies and digital transformation initiatives. Demand here is stable but faces pressure from paperless trends.
- Educational Institutions:Schools, colleges, and universities consume significant volumes of paper for textbooks, assignments, and administrative purposes. This segment's demand remains consistent, particularly in developing economies with expanding educational sectors.
- Government Agencies:Public sector bodies require paper for official documents, forms, and public communication, often subject to strict procurement guidelines including recycled content mandates.
- Advertising Agencies:These agencies specify paper for client campaigns, requiring high-quality coated and specialty papers for brochures, posters, and promotional materials to meet branding objectives.
Demand for printing paper from Educational Institutions remains consistent, whereas Print Shops represent a dynamic, evolving segment.
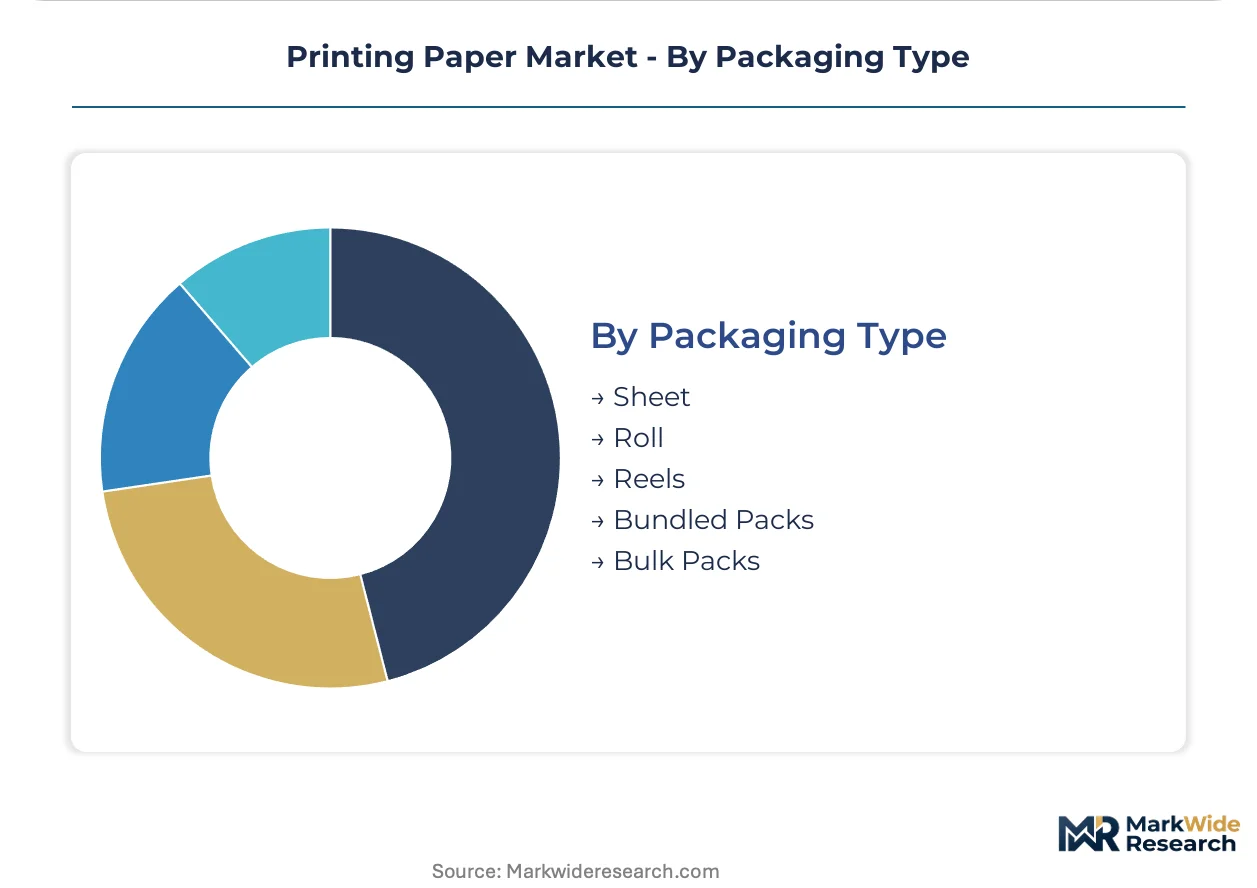
Packaging Type:
The market's packaging types are shaped by volume and logistics, dictating how paper is handled and transported through the supply chain.
- Sheet:Paper supplied in individual cut sheets, typically used for commercial printing, office use, and smaller-scale applications requiring precise handling. This format offers versatility for various printing presses.
- Roll:Large continuous rolls of paper, primarily used in high-volume industrial printing applications like newspapers, magazines, and certain packaging lines. This format optimizes efficiency for long print runs.
- Reels:Similar to rolls but often referring to narrower widths or specific winding for web-fed presses, common in publishing and high-speed digital printing.
- Bundled Packs:Smaller, pre-packaged quantities of paper, often found in retail for office or home use, offering convenience for consumers.
- Bulk Packs:Large quantities of paper, often palletized, designed for industrial consumers or large print shops to minimize handling costs and maximize efficiency.
Large-scale industrial consumption relies on Roll; Bundled Packs serve niche, specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global printing paper market exhibits a complex interplay of regional demand and supply, with certain areas serving as net exporters of pulp and paper products while others are significant importers. This dynamic balance influences pricing and raw material availability across continents, particularly for specialized paper grades.
India
Expanding commercial printing activities and a growing educational sector drive demand for printing paper in India. The government's 'Make in India' initiative supports domestic paper production, encouraging local manufacturing capacity. Major paper mills in states like Maharashtra and Gujarat are upgrading facilities to meet the rising demand for both uncoated and specialty papers.
Germany
Germany maintains a strong demand for high-quality coated and uncoated papers, particularly from its robust publishing and commercial printing industries. The EU Green Deal and its Corporate Sustainability Reporting Directive (CSRD) mandate transparent and sustainable sourcing practices for German paper manufacturers. The Rhine-Ruhr region, a traditional industrial hub, sees ongoing investment in advanced paper recycling and processing technologies.
United States
The United States printing paper market faces pressure from digital media substitution in office and publishing segments, though packaging applications continue to grow. US Environmental Protection Agency (EPA) guidelines encourage recycled content and sustainable forestry practices for domestic paper producers. Paper manufacturing clusters in the Pacific Northwest and the Southern states are adapting their product portfolios to include more packaging and specialty papers.
China
China's vast printing paper market is shaped by its dual carbon goals, which compel the pulp and paper industry to reduce emissions and improve energy efficiency. Demand for packaging paper remains robust due to the country's extensive e-commerce sector. Provinces along the Yangtze River Delta are seeing significant investment in modern, energy-efficient paper mills and advanced recycling facilities.
Brazil
Brazil is a major global supplier of pulp and paper, benefiting from its extensive forest resources and efficient eucalyptus plantations. The country's strong agricultural sector creates demand for packaging materials, while expanding literacy initiatives drive consumption of educational printed materials. Production facilities in the state of São Paulo and the southern regions are key players in both domestic supply and international export markets.
Printing Paper Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, ranging from large integrated global players to specialized regional manufacturers. This structure allows for both scale-driven efficiency and niche market responsiveness. Key strategic archetypes include integrated pulp and paper giants, specialty paper innovators, and regional commodity producers. Dominant competitive moves involve portfolio diversification into packaging and strategic alliances for sustainable raw material sourcing.
Integrated pulp and paper giants, such as International Paper Company, exemplify the scale-driven approach to global supply, leveraging extensive forestland and milling operations. UPM-Kymmene Corporation represents a strong focus on sustainable and lightweight coated papers, catering to evolving market demands for eco-friendly solutions. Sappi Limited occupies a position as a premium coated paper specialist, serving graphic-intensive applications and high-end commercial printing needs across various geographies.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| UPM-Kymmene Corporation |
| International Paper Company |
| Sappi Limited |
| Mondi plc |
| WestRock Company |
| Asia Pulp & Paper Co., Ltd. |
| Sylvamo Corporation |
| Oji Holdings Corporation |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's expanding paper manufacturing capacity directly influences global pricing power for commodity paper grades. This concentration of production capacity creates competitive pricing dynamics for both domestic and international buyers.
Pricing Analysis
The technology-generation pricing gap differentiates legacy offset paper from specialized digital inkjet substrates. Transactional, per-unit pricing dominates for commodity grades, while specialty papers command value-based pricing. Price differentiation stems from quality grade, such as brightness and opacity, and specific certifications like FSC or PEFC. Pricing softness for office and publishing papers reflects digital media substitution. Packaging applications, requiring high-performance specialty papers, exhibit the least price sensitivity.
Supply Chain Analysis
Upstream feedstock, primarily wood pulp from Brazil and recycled fiber, dictates much of the printing paper supply chain. Geographic supply concentration for pulp originates in Brazil and Nordic countries, while major manufacturing hubs exist in China and the United States. Raw material dependencies include wood pulp, recycled fiber, and the significant energy required for milling. Commodity price volatility for pulp and energy represents a structural supply chain risk. Distribution runs through large-scale industrial channels for rolls and fragmented commercial networks for sheets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The printing paper market presents a service-attach opportunity, with sustainable supply chain management tools and digital print workflow integration expanding faster than core paper volumes.
For Market Incumbents: Build specialized product portfolio moats by investing in advanced coatings and surface treatments for digital inkjet papers. Diversify aggressively into fiber-based packaging solutions, leveraging existing mill infrastructure. Counter digital media substitution by emphasizing paper's tactile benefits and sustainable credentials. Invest in FSC certification and R&D for enhanced barrier properties in packaging grades.
For New Entrants and Emerging Players: India's commercial printing and educational sectors represent significant geographic underpenetration. Target functional papers for e-commerce packaging, such as those with barrier coatings, and high-brightness recycled papers for corporate reporting. The most penetrable segment is the expanding educational market in developing economies. Partner with local distributors to offer specialized, sustainably certified paper grades.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists in sustainable materials and advanced coating technologies. The long-term viability of fiber-based packaging offers a stable investment horizon, counterbalancing declines in traditional print. Target niche producers with proprietary de-inking processes for recycled pulp or advanced barrier coating capabilities. Increased M&A activity for specialty paper producers is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Packaging | Leverages existing fiber expertise for the fastest-growing application segment. |
| Investment in Digital Inkjet Substrates | Addresses the evolving technical demands of high-speed commercial printing. |
| FSC/PEFC Certification Expansion | Meets escalating corporate ESG mandates and consumer preference for sustainable products. |
| Advanced Recycled Fiber Processing | Enables higher-quality papers from recycled content, reducing virgin fiber dependency. |
| Strategic Alliances for Raw Material Sourcing | Mitigates commodity price volatility and ensures access to sustainable inputs. |
Research Approach
Operator-level perspectives from mill managers, commercial printers, packaging buyers, and sustainability officers anchored the qualitative base of this analysis. Primary interviews were triangulated with extensive secondary data from industry association reports, government environmental agency guidelines, corporate sustainability reports, and trade publications. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down validation.
The scenario-bracketing framework guided the analytical approach across the analysis window. Segmentation dimensions modeled included product type, application, end-user, geographic region, and sustainability certification. Compound Annual Growth Rates were derived from historical trends and projected technological adoption rates for digital printing. Key forecast inputs included projected pulp price movements and e-commerce packaging demand growth.
Practitioners should monitor energy price spikes, new environmental regulations, and accelerated digital substitution for early signals of market shifts. Forecasts reflect assumptions documented through this methodology. Cross-checking against industry association forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Leatheroid Paper Market
Paper Products
Pulp Market
Paper Products
White Top Testliner Market
Paper Products
Veneer Sheets Market
Paper Products
Global Carpet Backing Material Market
Paper Products
Plywood Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Graphic Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Paper Machine Systems Market
Paper Products
Ceramic Paper Market
Paper Products
Billing Paper Market
Paper Products
Base Paper Market
Paper Products
Compressed Fiberboard Market
Paper Products
Africa Tissue Paper Market