
 Potassium Derivatives Market | 2026-2036
Potassium Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Derivatives Market Outlook
Electrolytic membrane upgrading in chlor-alkali coproduction is rewriting how potassium hydroxide feedstocks reach derivative manufacturers. Nutrien Ltd. leverages its Saskatchewan mining complex to sustain integrated supply from ore to refined potassium chloride. Uralkali anchors volume availability through its Berezniki and Solikamsk operations, while Mosaic Company competes via phosphate-potash co-location in Florida and Saskatchewan.
Potassium derivatives encompass salts and compounds derived from potassium-bearing ores or brines, typically processed through flotation, crystallization, or electrolytic refinement to achieve purities ranging from agricultural-grade to battery-electrolyte specifications. These compounds serve as essential inputs for crop nutrition, pharmaceutical buffering, food preservation, and industrial catalysis. Potassium chloride dominates volume flows due to its foundational role in NPK fertilizer blending, while potassium nitrate commands premium positioning in high-value horticulture and pyrotechnic applications. Potassium sulfate differentiates through low-chloride suitability for chloride-sensitive crops, and food-grade potassium carbonate occupies concentrated margin pools within baking and cocoa processing.
EPA water-quality standards and REACH substance restrictions shape permissible impurity profiles in agricultural and food-contact grades across North America and Europe. India's BIS certification mandates and China's GB standards for industrial chemicals further segment market access by purity tier. Stakeholders must monitor evolving fertilizer subsidy mechanisms and carbon-border adjustment frameworks to align capacity investments with regulatory trajectory.
Market Dynamics
Electrolytic membrane upgrading in chlor-alkali coproduction is compressing feedstock pathways for potassium hydroxide derivatives, forcing manufacturers to recalibrate sourcing strategies around membrane-cell output quality and regional chlorine-alkali capacity distribution.
Growth Catalysts
- India's PLI scheme for agrochemicals:Domestic production incentives are accelerating captive potassium derivative consumption for NPK fertilizer blending, reducing import dependency for chloride and sulfate variants.
- Precision agriculture adoption:Specialty potassium sulfate and nitrate demand is expanding through fertigation and foliar application systems in chloride-sensitive horticulture segments.
- China's dual carbon goals:Process efficiency mandates are tightening energy-intensity standards for carbonate and hydroxide production, favoring membrane-electrolysis upgrades over mercury-cell legacy infrastructure.
Market Restraints
- Feedstock concentration risk:Saskatchewan and Berezniki-Solikamsk ore bodies control the majority of potassium chloride supply, creating geographic chokepoints for derivative manufacturers without backward integration.
- REACH substance restrictions:ECHA impurity thresholds for agricultural and food-contact grades are raising purification costs for European derivative producers.
- Natural gas price volatility:Energy-intensive electrolytic and thermal processing stages expose margin structures to input cost swings in European and Asian production clusters.
Strategic Opportunities
- Battery-electrolyte grade potassium hydroxide:Purity specifications for potassium-ion and solid-state battery chemistries are opening premium margin pools beyond traditional industrial applications.
- Indonesia's downstream fertilizer push:NPK subsidy expansion and domestic blending capacity buildout are creating import-substitution openings for sulfate and nitrate derivative suppliers.
- Digital agronomy platforms:Soil-sensor and variable-rate application systems are enabling precision potassium prescription services that lock in derivative offtake through subscription models.
Industry Challenges
- Membrane-cell technical talent scarcity:Chlor-alkali process engineering expertise required for electrolytic upgrading is concentrated among a narrow cohort of specialists in Germany and Japan.
- Multi-jurisdiction certification timelines:Simultaneous BIS, GB standards, and EPA water-quality approvals for agricultural-grade derivatives extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Derivatives Market |
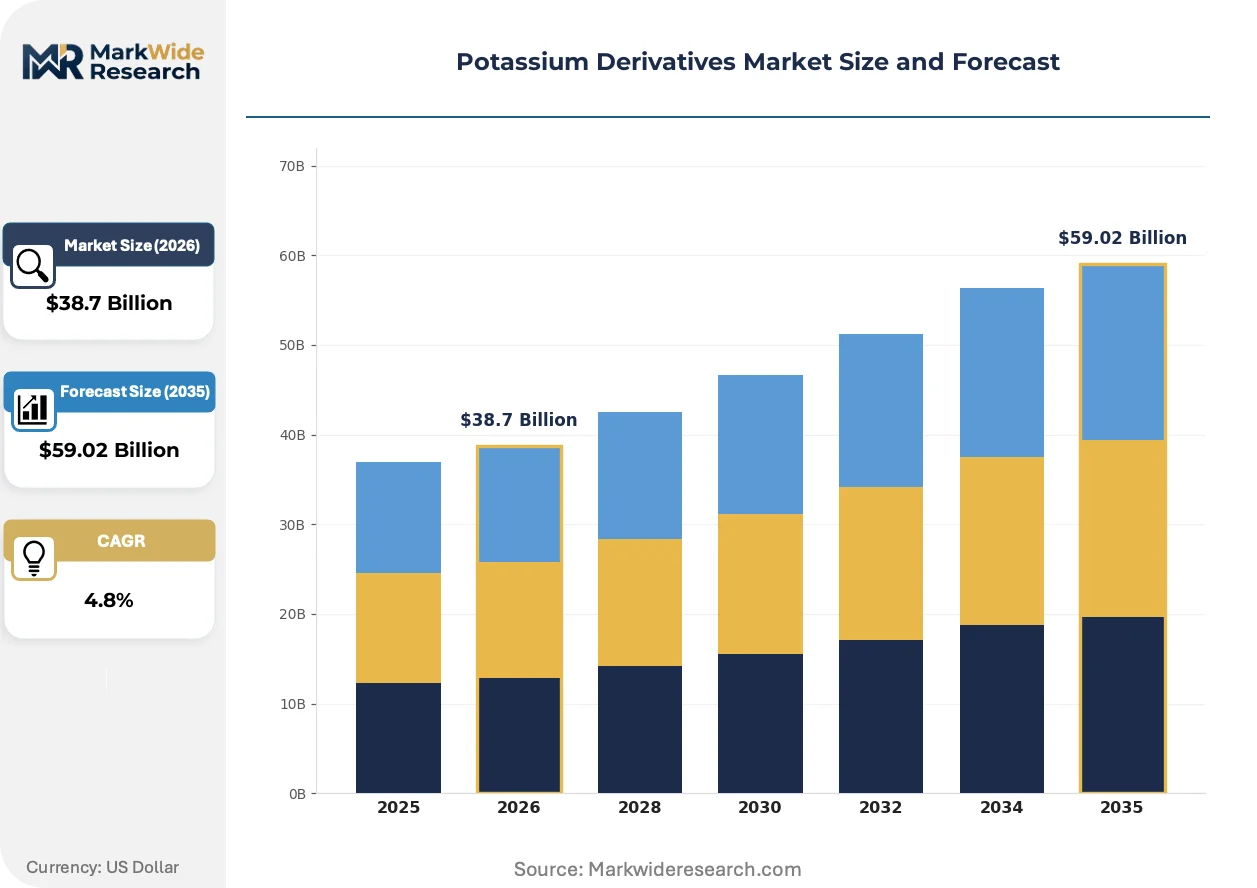
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Nitrate, Potassium Chloride, Potassium Sulfate, Potassium Carbonate Application: Agriculture, Pharmaceuticals, Food Processing, Industrial Uses End User: Agricultural Sector, Chemical Manufacturers, Food Industry, Healthcare Form: Granular, Liquid, Powder, Crystal |
| Companies Covered | Nutrien Ltd., Uralkali, Mosaic Company, Eurochem, K+S AG, Intrepid Potash Inc., Compass Minerals Intl. Ltd., JSC Belaruskali, ICL Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Derivatives Market Strategic Shifts
Digital twin modeling of crystallization circuits and membrane-electrolysis trains is compressing process optimization cycles, while regulatory carbon-accounting requirements are forcing transparency into scope-three emissions across potassium derivative supply chains.
Membrane-electrolysis virtualization is virtualizing how potassium hydroxide feedstock quality is monitored and adjusted in real time. Fertilizer blenders and pharmaceutical buffer manufacturers are adopting cloud-connected conductivity and impurity sensors at membrane-cell outputs. This virtualization is compressing the traditional laboratory verification bottleneck, enabling just-in-time derivative specification matching without intermediate storage buffers.
REACH substance restrictions are tightening permissible heavy-metal and halide profiles in agricultural-grade potassium derivatives. ECHA's updated candidate list for authorization is forcing carbonate and chloride producers to deploy additional ion-exchange and recrystallization stages. Food-contact potassium carbonate manufacturers in the Netherlands and Belgium are responding with segregated production lines certified to FSSC 22000 standards.
Buyer concentration among large-scale NPK blenders is consolidating procurement decisions for agricultural-grade potassium derivatives. Mid-tier distributors are losing volume to direct manufacturer relationships with cooperatives and plantation operators. This channel compression is most visible in Brazil's Mato Grosso soybean belt and India's Punjab-Haryana wheat corridor, where input purchasing has shifted to platform-based collective buying.
Potassium Derivatives Market Segmentation
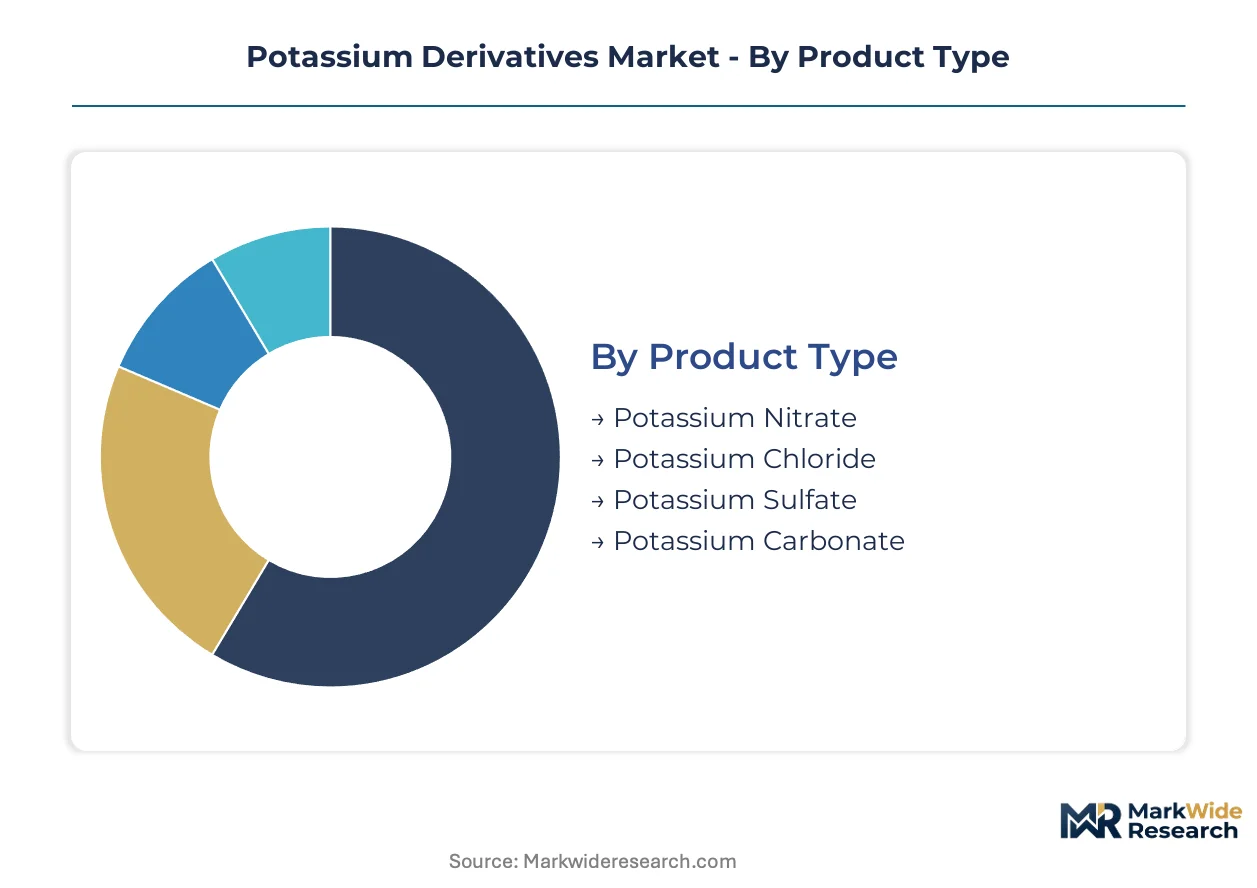
Potassium derivative specifications vary sharply across end-use requirements, with fertilizer-grade chloride demanding minimal technical support while battery-electrolyte hydroxide requires continuous purity monitoring. Segmentation clarity enables manufacturers to align purification investments with margin capture potential across agricultural, pharmaceutical, and industrial tiers.
Product Type:
After-sales intensity escalates dramatically from commodity chloride to specialty carbonate, with technical service teams dedicating disproportionate resources to electrolyte-grade quality assurance.
- Potassium Chloride:Agricultural-grade KCl dominates volume flows through flotation and crystallization processing, typically achieving 95-98% purity for NPK blending. Demand concentrates in India's Punjab-Haryana wheat corridor where NPK subsidy reforms are accelerating domestic consumption, though Saskatchewan and Berezniki-Solikamsk ore concentration creates feedstock vulnerability for non-integrated derivative manufacturers.
- Potassium Sulfate:Low-chloride sulfate suits chloride-sensitive horticulture through sulfate precipitation or Mannheim process production, commanding premium positioning in precision fertigation systems. Momentum is building in Indonesia's downstream fertilizer push where NPK subsidy expansion favors specialty sulfate imports for palm oil and cocoa cultivation.
- Potassium Nitrate:Dual-nutrient nitrate serves high-value horticulture and pyrotechnic applications through nitric acid neutralization, with hygroscopic crystal specifications requiring moisture-controlled logistics.
- Potassium Carbonate:Food and industrial carbonate demands heavy-metal purification for baking and cocoa processing, with REACH substance restrictions tightening ECHA impurity thresholds for European producers.
Potassium Chloride holds the largest share; momentum sits with Potassium Sulfate.
Application:
Cost tier stratification separates commodity agricultural inputs from pharmaceutical buffering and food preservation grades, with certification burden and pricing power inversely correlated to volume throughput.
- Agriculture:NPK fertilizer blending and specialty fertigation consume the majority of chloride, sulfate, and nitrate derivatives, with precision agriculture adoption expanding prescription-based potassium services. Brazil's Mato Grosso soybean belt and India's cooperative purchasing platforms are compressing distributor margins through direct manufacturer relationships.
- Pharmaceuticals:Buffer-grade potassium derivatives require USP and EP certification with tight endotoxin and heavy-metal specifications, serving parenteral formulation and dialysis applications.
- Food Processing:Potassium carbonate and citrate function as leavening agents, pH stabilizers, and salt substitutes, with FSSC 22000 certification mandatory for European food-contact production.
- Industrial Uses:Glass manufacturing, detergents, and chemical synthesis absorb technical-grade carbonates and hydroxides, with China's dual carbon goals tightening energy-intensity standards for carbonate production.
Agriculture commands absolute volume; pharmaceuticals deliver steepest margin expansion.
End User:
Customer concentration patterns diverge sharply, with agricultural cooperatives consolidating procurement power while pharmaceutical and food manufacturers fragment across certification tiers.
- Agricultural Sector:Large-scale NPK blenders and plantation operators are consolidating direct manufacturer relationships, displacing mid-tier distributors in Brazil and India through platform-based collective buying.
- Chemical Manufacturers:Chlor-alkali coproducers and specialty chemical houses require electrolytic-grade potassium hydroxide for downstream derivative synthesis, with membrane-cell technical talent scarcity concentrated in Germany and Japan.
- Food Industry:Industrial bakeries and cocoa processors specify food-grade potassium carbonate with segregated production lines and batch traceability systems.
- Healthcare:Hospital networks and dialysis centers demand pharmaceutical-grade potassium for clinical applications, with multi-jurisdiction certification timelines extending product launch cycles.
Agricultural Sector dominates offtake; Chemical Manufacturers are gaining share fastest through battery-electrolyte grade demand.
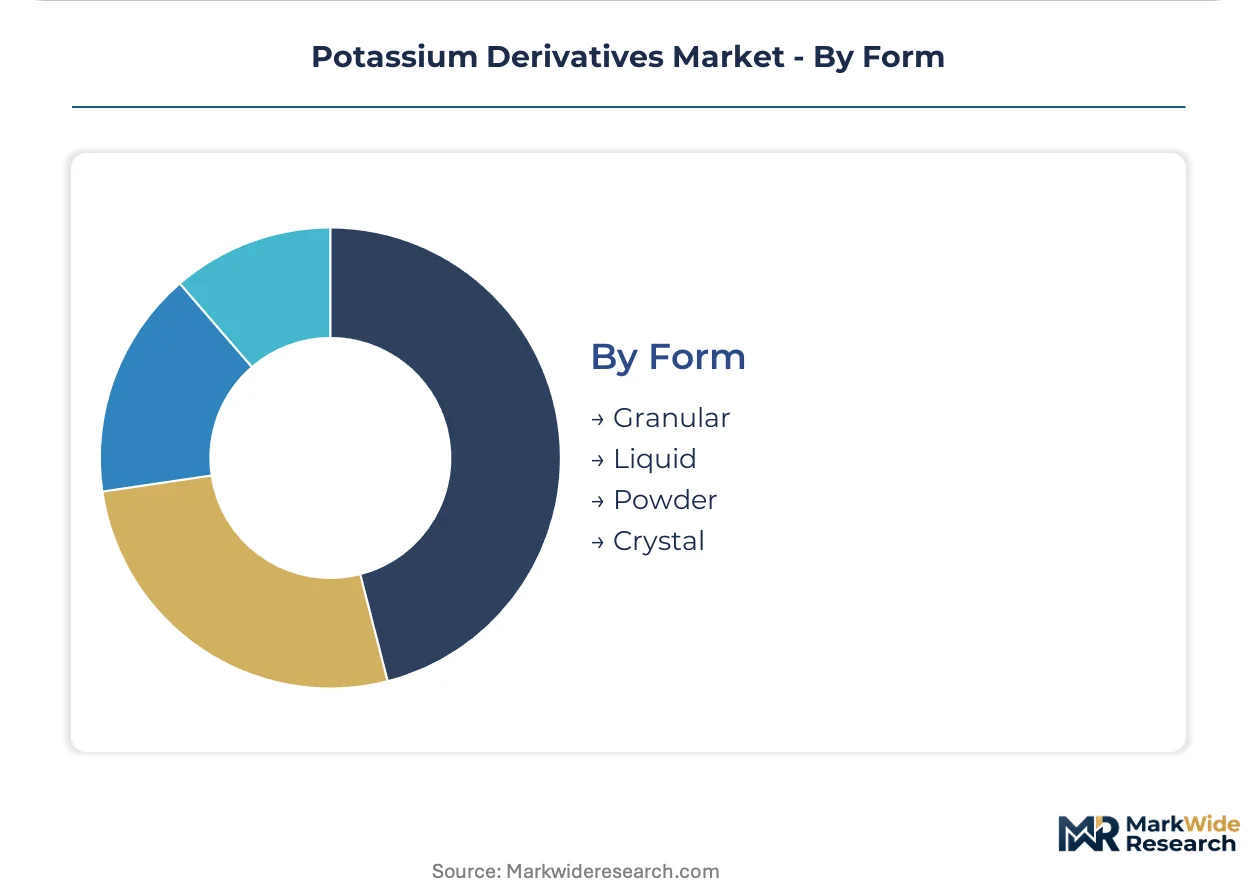
Form:
Volume economics favor granular and powder specifications for bulk fertilizer handling, while liquid and crystal forms capture premium positioning in precision application and high-purity industrial segments.
- Granular:Spherical granules optimized for mechanical spreading equipment dominate agricultural chloride and sulfate distribution, with crush strength and size uniformity specifications varying by regional equipment standards.
- Liquid:Solution-grade potassium hydroxide and carbonate serve fertigation systems and industrial processes, with concentration and impurity profiles customized to membrane-electrolysis output quality.
- Powder:Fine-milled potassium derivatives facilitate rapid dissolution in pharmaceutical buffering and food processing, with particle size distribution critical to reactivity control.
- Crystal:High-purity crystalline nitrate and carbonate serve pyrotechnic, electronic, and laboratory applications, with optical clarity and moisture content specifications driving recrystallization intensity.
Granular forms hold the largest share; Liquid forms are expanding most quickly through precision agriculture and battery-electrolyte demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian potash exports through Vancouver and Thunder Bay corridors supply Asian agricultural markets, while Russian volumes move through Baltic terminals into India and Southeast Asia. Trade-flow concentration creates sourcing vulnerabilities for derivative manufacturers without captive ore positions.
Canada
Saskatchewan's potash belt feeds North American and Asian fertilizer blenders through Nutrien's integrated mining complex. EPA water-quality standards shape permissible impurity profiles for agricultural-grade derivatives crossing into the United States. Calgary-based trading houses coordinate rail and port logistics for chloride shipments to India and Indonesia.
Russia
Berezniki and Solikamsk operations anchor volume availability for sulfate and chloride derivatives serving European and Asian markets. ECHA REACH substance restrictions tighten heavy-metal thresholds for carbonate and chloride imports into EU member states. Volga River logistics connect Ural mining districts to Baltic Sea export terminals.
India
Punjab-Haryana wheat corridor demand accelerates through NPK subsidy reforms and PLI scheme incentives for domestic agrochemical production. BIS certification mandates segment market access by purity tier for food-contact and pharmaceutical grades. Gujarat's chemical manufacturing clusters are expanding captive derivative capacity for fertilizer blending.
China
GB standards for industrial chemicals and dual carbon goals tighten energy-intensity requirements for carbonate and hydroxide production. Yangtze River Delta membrane-electrolysis facilities supply battery-electrolyte grade potassium hydroxide for emerging energy storage chemistries. Shandong Province retains thermal-process legacy capacity facing forced efficiency upgrades.
Brazil
Mato Grosso soybean belt procurement is compressing distributor margins through platform-based collective buying by large cooperatives. ANVISA pharmaceutical regulations govern buffer-grade derivative imports for parenteral formulation applications. Paraná state's fertilizer blending capacity is expanding direct manufacturer relationships displacing traditional distribution channels.
Potassium Derivatives Market Competitive Environment
Channel-controlling players compete with product-specialist players across differentiated purity tiers. Consolidation around integrated mining-to-derivative operations in Saskatchewan and the Urals has created geographic chokepoints for non-integrated manufacturers. Three strategic archetypes dominate: ore-integrated majors with captive feedstock, membrane-electrolysis specialists serving battery-grade specifications, and regional blenders with direct cooperative relationships. Capacity expansion and backward integration into ore sourcing represent the dominant competitive moves.
Within the ore-integrated tier, Nutrien Ltd. and Uralkali exemplify archetypes of geographic concentration and volume availability. Mosaic Company occupies a position bridging phosphate-potash co-location advantages in Florida and Saskatchewan. These three entities anchor supply security for derivative manufacturers dependent on chloride feedstock quality and volume commitments.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Uralkali |
| Mosaic Company |
| Eurochem |
| K+S AG |
| Intrepid Potash Inc. |
| Compass Minerals Intl. Ltd. |
| JSC Belaruskali |
| ICL Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Vancouver and Thunder Bay rail-port corridors carry Saskatchewan potash to Asian markets, with freight cost volatility translating directly into delivered-price spreads between ore-integrated majors and non-integrated derivative manufacturers. This logistics concentration amplifies pricing power for Nutrien and Uralkali while forcing mid-tier compounders to absorb margin compression or pass through cost increases to NPK blenders.
Pricing Analysis
Membrane-electrolysis generation pricing gaps separate legacy mercury-cell potassium hydroxide from next-generation battery-electrolyte grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity certification, with FSSC 22000 food-contact and battery-grade specifications commanding substantial premiums over agricultural chloride. Cost compression in standard-grade sulfate runs through natural gas price volatility in European thermal processing clusters. Agricultural cooperatives in Brazil's Mato Grosso belt exhibit highest price sensitivity, while pharmaceutical buffer manufacturers demonstrate lowest sensitivity due to endotoxin specification rigidity.
Supply Chain Analysis
Contract manufacturing concentration for electrolytic upgrading sits with membrane-cell specialists in Germany and Japan, where technical talent scarcity constrains capacity expansion. Geographic supply concentrates in Canada, Russia, and Belarus for potassium chloride feedstock, with Shandong Province and Gujarat clusters handling downstream derivative synthesis. Raw material dependencies center on Saskatchewan ore, Baltic ammonia for nitrate neutralization, and sulfuric acid for Mannheim process sulfate production. Single-source vulnerability pervades the Berezniki-Solikamsk corridor due to sanctions exposure and logistics chokepoints. Distribution runs through direct manufacturer relationships with large-scale NPK blenders, displacing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment defensive moat, where REACH substance restrictions and multi-jurisdiction certification timelines create structural barriers that protect incumbent positions while raising capital requirements for challengers.
For Market Incumbents: Insulate margin structures by deepening backward integration into Saskatchewan or Ural ore sourcing, eliminating feedstock concentration risk from Berezniki-Solikamsk dependence. Expand membrane-electrolysis capacity in Yangtze River Delta clusters to capture battery-electrolyte grade premiums before technical talent scarcity worsens. Prioritize FSSC 22000 and USP certification maintenance as ECHA impurity thresholds tighten.
For New Entrants and Emerging Players: Establish a beachhead in Indonesia's downstream fertilizer push, where NPK subsidy expansion and domestic blending capacity buildout create import-substitution demand for sulfate and nitrate derivatives. Target precision agriculture subscription services linking soil-sensor data to potassium prescription fulfillment, locking in offtake through digital agronomy platforms rather than commodity spot competition.
For Investors and Strategic Acquirers: China's dual carbon goals reshaping energy-intensity standards for carbonate production reshape the acquisition landscape toward membrane-electrolysis specialists with battery-grade qualification pathways. Long-term viability centers on electrolyte-grade potassium hydroxide exposure as solid-state battery chemistries mature. Target membrane-cell operators with existing GB standards compliance and Yangtze Delta logistics access. Watch ECHA authorization list updates as signal for purification investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Sourcing | Captive Saskatchewan supply eliminates Berezniki-Solikamsk chokepoint vulnerability for derivative manufacturers. |
| Membrane-Electrolysis Capacity Expansion | Yangtze Delta deployment serves battery-electrolyte grade demand from emerging energy storage chemistries. |
| Multi-Jurisdiction Certification Investment | Simultaneous BIS, GB standards, and EPA approvals compress 18-24 month product launch cycles. |
| Precision Agriculture Platform Partnership | Soil-sensor integration locks in potassium derivative offtake through subscription prescription models. |
| Green Manufacturing Transition | Dual carbon goals compliance in Shandong Province forces thermal-process legacy capacity upgrades. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fertilizer blenders, pharmaceutical buffer manufacturers, membrane-cell process engineers, and agricultural cooperative procurement heads. Secondary validation drew from customs and trade flow databases, SEC filings of ore-integrated majors, ECHA substance restriction updates, and India's PLI scheme implementation reports. Bottom-up volume modeling across grade tiers triangulated against top-down macroeconomic demand projections.
Calibration against historical capacity utilization rates and announced expansion timelines anchored projections across the analysis window. Segmentation dimensions modeled include product type, application tier, end-user concentration pattern, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating NPK subsidy reform impacts and precision agriculture adoption curves. Industry-specific inputs included membrane-electrolysis yield improvements and REACH authorization list revision schedules.
Macroeconomic conditions sit as an overlay; deviation in natural gas price trajectories and Baltic ammonia supply would shift the trajectory for thermal-process derivative margins. Forecasts reflect documented assumptions regarding subsidy continuity and certification timeline stability. Quarterly review of ECHA candidate list updates and India's BIS mandate revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Solketal Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Fluoropolymer Masterbatch Market