
 Woodfree Paper Market | 2026-2036
Woodfree Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Woodfree Paper Market Outlook
Project finance tied to biomass cogeneration and energy-efficiency retrofits is fragmenting the competitive landscape, allowing mid-scale entrants to secure capacity without full capital ownership. Sappi leverages its South African pulp integration to control fiber costs across European and North American mills. The Navigator Company anchors its position through eucalyptus fiber dominance and sustained exports from Portuguese operations. UPM-Kymmene differentiates via biochemicals and biorefining co-location with woodfree paper assets in Finland.
Woodfree paper designates paper manufactured from chemical pulp with lignin removed, yielding a sheet with superior brightness, opacity, and printability compared to mechanical grades; typical basis weights range from 60 to 300 gsm depending on end-use. The coated segment occupies the largest value share due to its dominance in high-end advertising, annual reports, and magazine publishing where surface smoothness commands premium pricing. Uncoated grades compete aggressively in book publishing and business stationery where cost efficiency and writability matter more than gloss. Specialty woodfree paper leads margin pools, serving archival, security, and luxury packaging applications where technical certification barriers limit supply.
EMA and REACH frameworks in Europe govern chemical additives and fiber traceability, while EPA rules in the United States enforce effluent limitations and air emissions from kraft pulping operations. These regulations shape demand by raising compliance costs for older integrated mills and redirecting investment toward recycled-fiber blends and closed-loop water systems. Stakeholders must monitor how evolving extended producer responsibility schemes alter the cost structure of virgin versus recycled fiber sourcing.
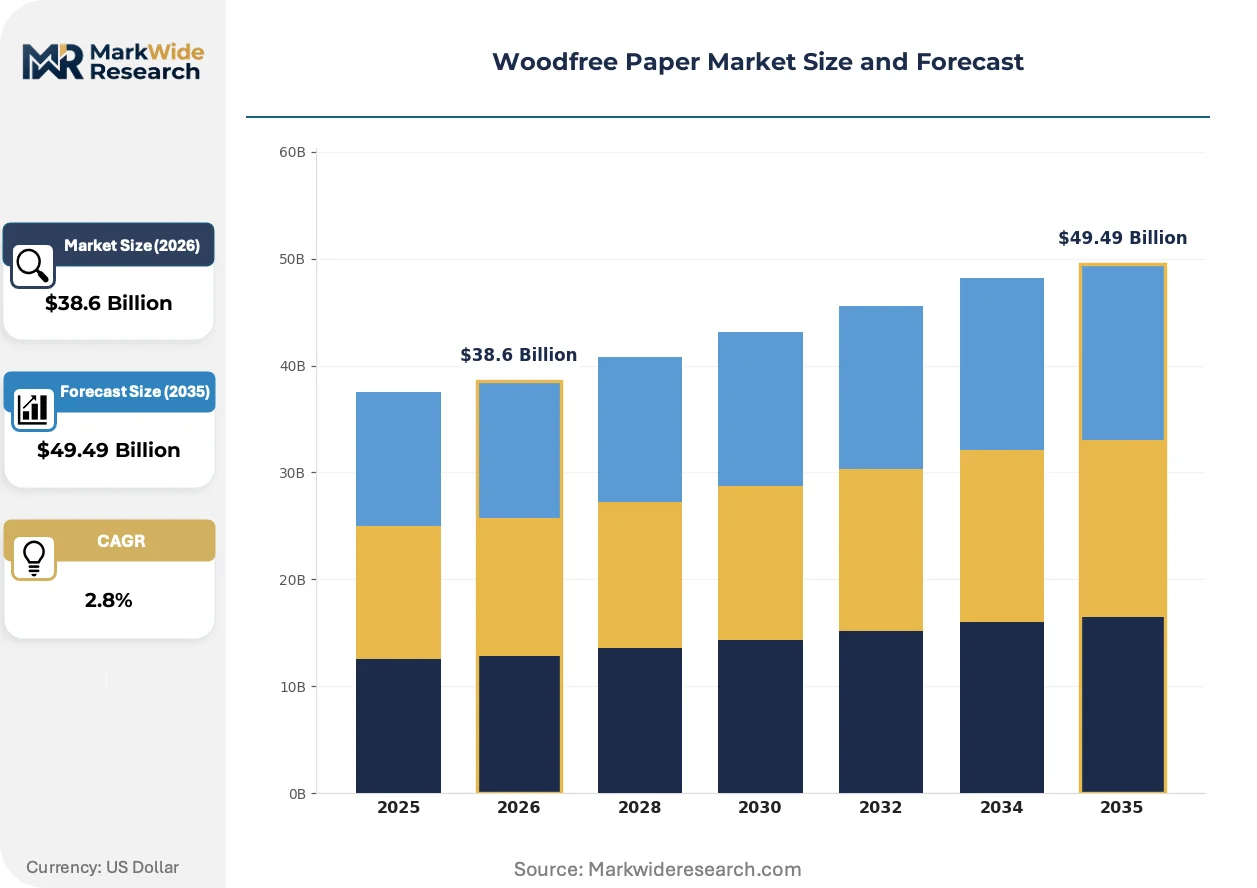
Market Dynamics
The EU Green Deal is forcing virgin fiber sourcing constraints across European mills while specialty publishing houses expand uncoated grade consumption, creating simultaneous cost pressure and demand bifurcation across coated and uncoated segments.
Growth Catalysts
- EU Green Deal mandates:Tightened recyclability requirements and extended producer responsibility schemes redirect investment toward closed-loop water systems and certified fiber traceability, favoring integrated mills with compliance infrastructure.
- Premium book publishing:Specialty publishing houses are expanding uncoated woodfree adoption for high-end literary and art books where tactile quality and archival permanence command reader willingness to pay.
- German export packaging:Concentrated demand from high-quality printing and export-oriented packaging sectors sustains above-average consumption of coated and specialty woodfree stocks in this manufacturing hub.
Market Restraints
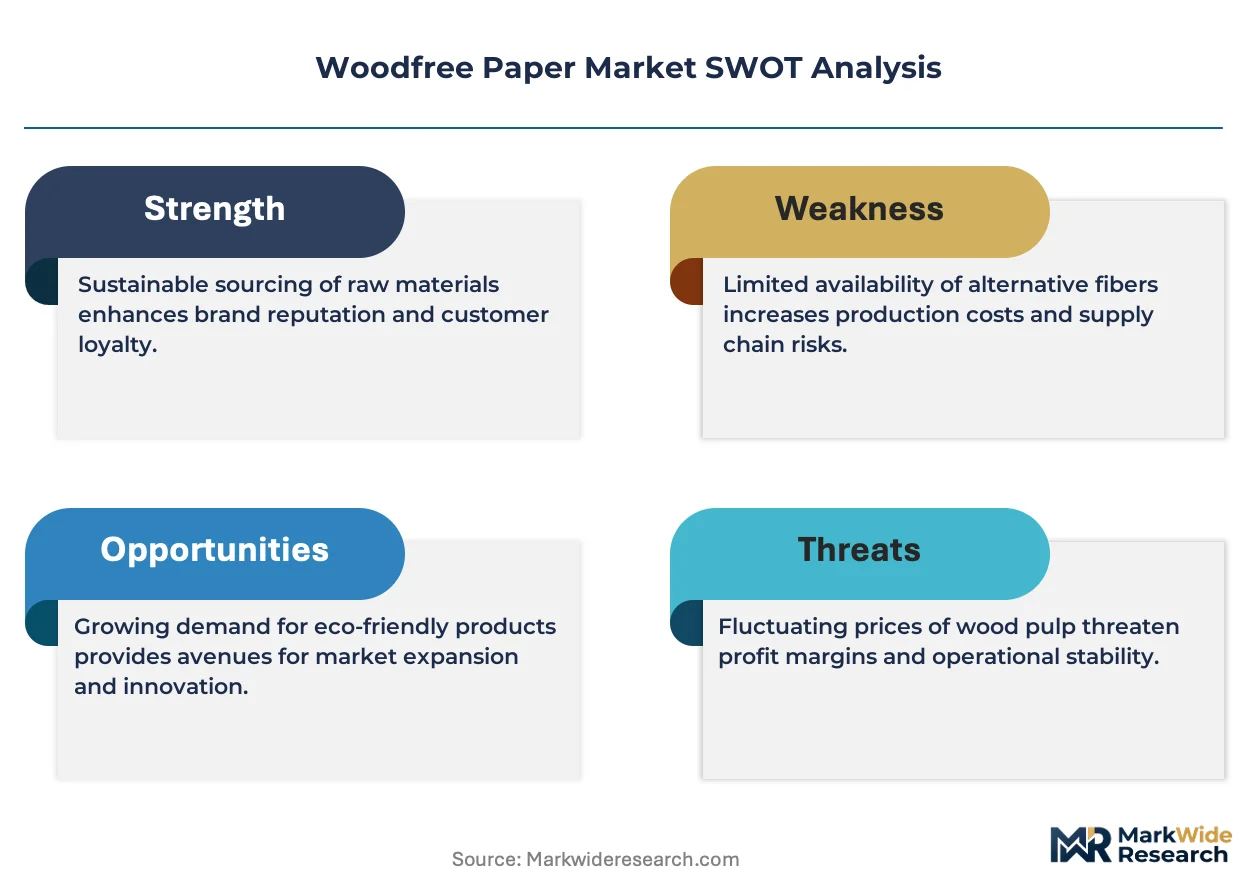
- Eucalyptus pulp concentration:Portuguese and Brazilian eucalyptus fiber dominance creates supply bottleneck risk for European mills dependent on Iberian pulp imports, amplifying input cost volatility during currency swings.
- Digital substitution:Annual reports, corporate stationery, and transactional documents face accelerating displacement by digital distribution platforms, compressing volume in traditional woodfree strongholds.
- REACH chemical compliance:ECHA additive restrictions and fiber traceability mandates raise formulation costs for optical brighteners and sizing agents, disproportionately burdening smaller non-integrated producers.
Strategic Opportunities
- Luxury packaging white space:Technical certification barriers in security and archival applications limit qualified supply, creating margin pools for mills investing in substrate engineering and tamper-evident coating technologies.
- Biochemical co-location:Finnish biorefining clusters demonstrate viable pathway to lignin valorization and extractive byproduct streams, converting woodfree paper assets into multi-output biorefinery platforms.
- Biomass cogeneration finance:Project finance structures for energy-efficiency retrofits allow mid-scale entrants to secure capacity without full capital ownership, fragmenting competitive concentration.
Industry Challenges
- Water system integration:Closed-loop water recycling retrofits require simultaneous chemical process re-engineering and biological treatment upgrades, extending commissioning timelines for older kraft pulping operations.
- Certification timeline compression:FSC and PEFC chain-of-custody audits face backlogs as mills rush to meet EU Green Deal fiber sourcing deadlines, delaying market access for uncertified virgin fiber inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodfree Paper Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $49.49 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, Specialty, Lightweight Application: Printing, Packaging, Stationery, Art Supplies End User: Publishing, Education, Retail, Commercial Packaging Type: Reams, Sheets, Rolls, Pads |
| Companies Covered | Sappi, The Navigator Company, International Paper, Nippon Paper, Asia Pulp & Paper, Stora Enso, Oji Holdings, WestRock, UPM-Kymmene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodfree Paper Market Strategic Shifts
Digital workflow integration is virtualizing prepress and proofing stages, compressing production cycles while regulatory frameworks tighten chemical disclosure requirements. These forces reshape how mills configure fiber sourcing, coating investments, and customer technical service.
Digital print-ready substrate engineering is virtualizing traditional make-ready and offline proofing workflows. Magazine publishers and catalog houses are adopting these substrates to eliminate plate-making delays and reduce startup waste. The technology is virtualizing inventory holding patterns by enabling shorter run lengths and just-in-time replenishment.
REACH chemical disclosure expansion now mandates granular additive reporting across coating formulations and wet-end chemistry. This regulatory pressure is redirecting R&D spending toward bio-based sizing agents and mineral filler alternatives. Coated woodfree producers serving advertising and annual report segments face the steepest compliance cost escalation.
Consolidated procurement by multinational publishing groups is compressing supplier rosters and demanding integrated sustainability reporting. Direct mill relationships are replacing merchant intermediaries for volume book and magazine contracts. German and Nordic markets exhibit the most advanced buyer concentration, with three publishing groups controlling majority share of coated woodfree offtake.
Woodfree Paper Market Segmentation
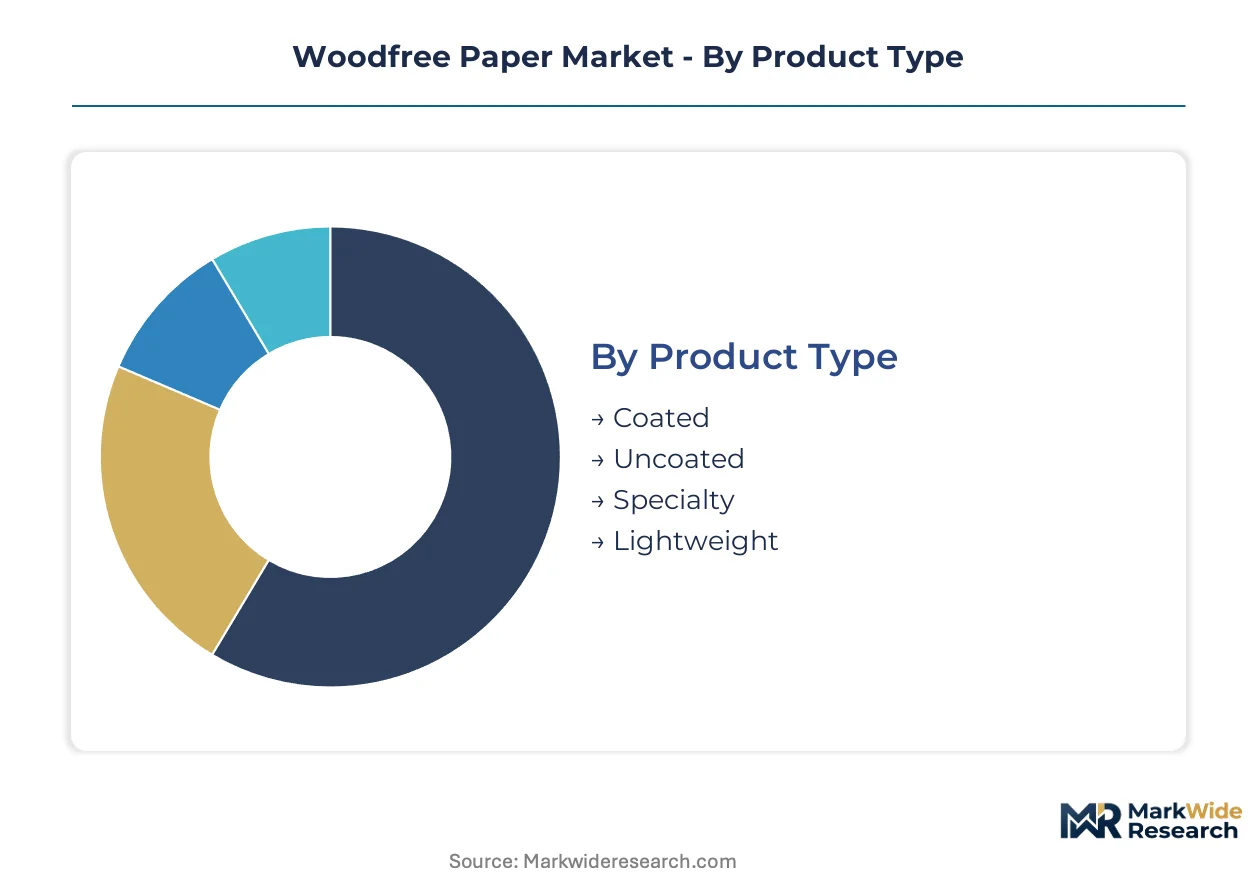
Woodfree paper segmentation reflects divergent value capture across surface treatment technologies and end-use durability requirements. Coated and specialty grades command premium positioning in advertising and archival applications, while uncoated volumes concentrate in cost-sensitive publishing workflows.
Product Type:
Cost tier differentiation separates commodity mechanical grades from chemical-pulp woodfree stocks across brightness, opacity, and printability specifications.
- Coated:Clay and mineral-coated surfaces deliver high gloss and ink holdout for annual reports and magazine publishing. German advertising agencies and catalog houses sustain concentrated demand where surface smoothness justifies premium pricing over uncoated alternatives.
- Uncoated:Absorbent surfaces without mineral coating optimize writability and tactile response for literary publishing and business correspondence. Specialty publishing houses across France and Italy are expanding uncoated adoption for premium art books where archival permanence drives reader willingness to pay.
- Specialty:Substrates engineered for security printing, archival storage, and luxury packaging with technical certification barriers limiting qualified supply.
- Lightweight:Basis weights below 60 gsm reduce postage and distribution costs for direct mail and airline magazines.
Coated holds installed capacity. Specialty is rotating up the share rankings.
Application:
Functional use cases span communication durability requirements from ephemeral advertising to permanent record-keeping.
- Printing:Magazine, catalog, and commercial sheetfed applications demanding precise color reproduction and dimensional stability. Nordic publishing groups concentrate procurement for coated woodfree offtake, compressing supplier rosters toward direct mill relationships.
- Packaging:Folding carton and luxury box applications requiring structural rigidity and printability. Export-oriented German packaging converters sustain above-average consumption of coated and specialty stocks for high-quality consumer goods presentation.
- Stationery:Corporate identity systems and premium correspondence papers.
- Art Supplies:Archival drawing papers and conservation-grade supports.
Printing dominates volume throughput. Packaging is climbing the fastest on value expansion.
End User:
Customer type segmentation captures divergent procurement scale and sustainability certification requirements across institutional and commercial buyers.
- Publishing:Book, magazine, and directory publishers with consolidated multinational procurement demanding integrated chain-of-custody documentation. Three publishing groups control majority coated woodfree offtake in German and Nordic markets, replacing merchant intermediaries with direct mill contracts.
- Education:Textbook and academic workbook publishers with price-sensitive specifications and high-volume seasonal purchasing patterns.
- Retail:Private-label stationery and packaging programs with variable quality tiers across premium and economy positioning.
- Commercial:Corporate marketing departments and print service bureaus with project-based demand and accelerated digital substitution pressure.
Publishing anchors procurement concentration. Commercial is fragmenting across digital workflow adoption.
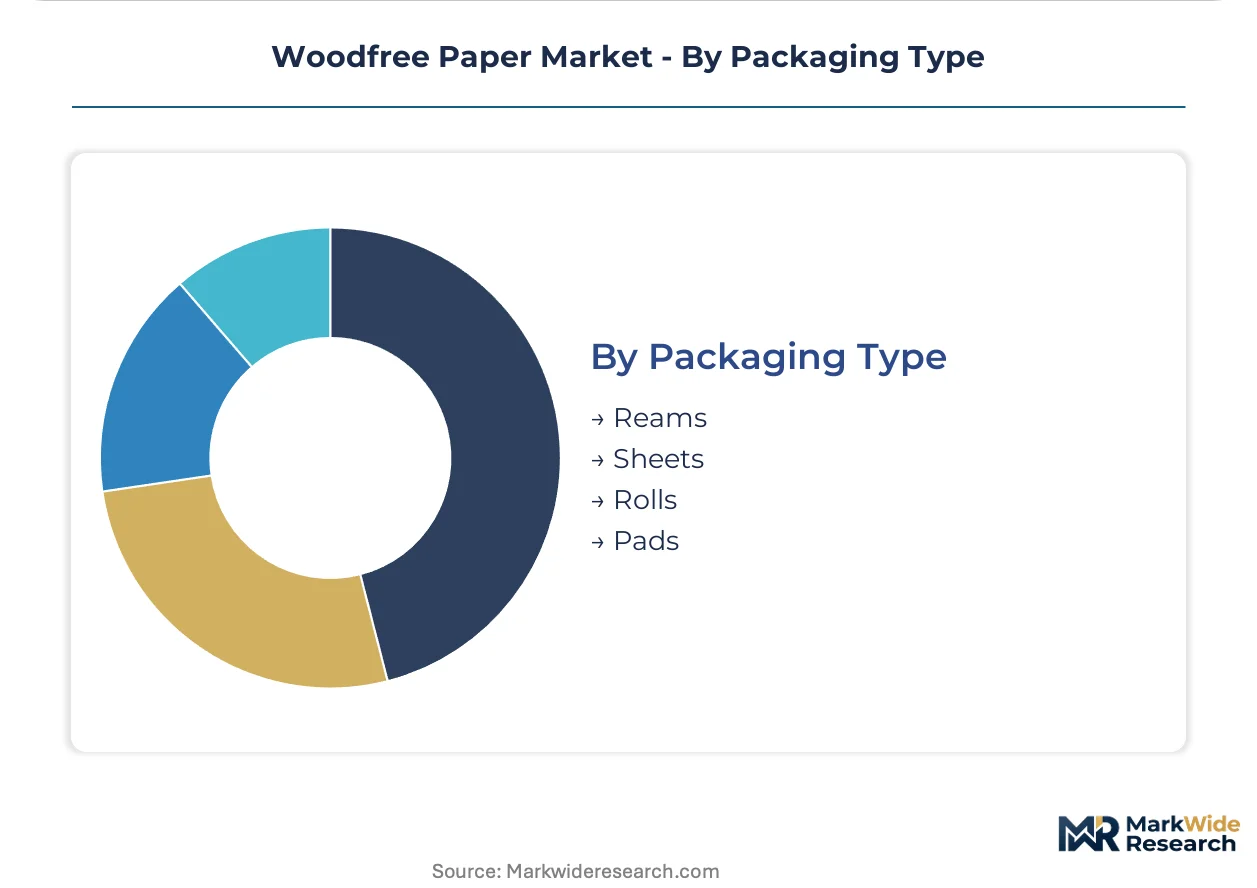
Packaging Type:
Physical format determines logistics economics and converting equipment compatibility across the value chain.
- Reams:Standard 500-sheet packages for office and educational distribution. REACH chemical disclosure mandates on optical brighteners and sizing agents are redirecting R&D toward bio-based alternatives for ream-packed business papers.
- Sheets:Cut-size formats for commercial printing and packaging converting. Just-in-time inventory patterns are compressing sheet order quantities as digital print-ready substrates enable shorter production runs.
- Rolls:Web-fed press configurations for high-volume publication gravure and offset.
- Pads:Glued or spiral-bound assemblies for art, legal, and educational use.
Reams hold established distribution infrastructure. Sheets is gaining share fastest on digital print integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented mills in Germany and Finland ship coated woodfree grades across European borders, while Portuguese eucalyptus pulp feeds Iberian production. Asian producers in China and Japan balance domestic magazine demand against specialty paper exports.
Germany
High-quality printing houses and export packaging converters sustain above-average coated woodfree consumption. The EU Green Deal mandates tightened virgin fiber traceability through FSC chain-of-custody certification. The Rhine-Ruhr industrial corridor hosts integrated mills retrofitting closed-loop water systems to meet ECHA chemical discharge limits.
Finland
Biorefinery co-location with woodfree assets creates lignin valorization revenue streams alongside traditional paper output. REACH frameworks govern optical brightener formulations and wet-end chemistry disclosure. The Kymenlaakso region anchors UPM-Kymmene's multi-output platform linking pulp, paper, and biochemical production.
China
Domestic magazine publishers and security printing applications drive coated and specialty grade demand. MIIT enforces dual carbon goals that redirect investment toward energy-efficient kraft pulping retrofits. The Yangtze River Delta cluster concentrates capacity serving both domestic consumption and Asia-Pacific export markets.
Portugal
The Navigator Company anchors Iberian eucalyptus fiber dominance for European pulp supply. EMA and ECHA frameworks govern chemical additives in coated surface formulations. The Setúbal industrial zone sustains sustained export volumes of bleached eucalyptus kraft pulp to mills across France and Italy.
Japan
Precision printing and archival applications sustain demand for high-brightness uncoated grades. METI standards enforce rigorous effluent limitations on integrated pulp and paper operations. The Kanto region around Tokyo concentrates specialty paper converters serving security printing and luxury packaging segments.
Woodfree Paper Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fiber supply and chemical formulation. The market structures around vertically integrated pulp-to-paper producers, merchant converters, and regional distributors. Three archetypes dominate: South African pulp-integrated multinationals, Iberian eucalyptus specialists, and Nordic biorefinery platforms. Competitive moves center on biomass cogeneration project finance and biochemical co-location investments that fragment capital requirements.
Among the integrated multinational tier, Sappi exemplifies pulp-cost control through South African fiber integration across European and North American mill networks. The Navigator Company anchors the eucalyptus-specialist archetype through Portuguese operations. UPM-Kymmene occupies the biorefinery-platform position, demonstrating lignin valorization pathways from Finnish woodfree assets.
| Leading Market Players |
|---|
| Sappi |
| The Navigator Company |
| International Paper |
| Nippon Paper |
| Asia Pulp & Paper |
| Stora Enso |
| Oji Holdings |
| WestRock |
| UPM-Kymmene |
| Others |
Value Chain & Pricing Dynamics
Eucalyptus pulp import dependency from Portuguese and Brazilian sources determines both the spread between coated and uncoated grade pricing and the geographic configuration of European mill networks. Currency volatility in fiber sourcing amplifies input cost swings that compress margins for non-integrated producers while rewarding South African and Iberian pulp-integrated operators with captive supply buffers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on FSC certification level and volume scale commitments. Price differentiation stems from optical brightener formulation costs under REACH disclosure mandates and geographic delivery premiums for Rhine-Ruhr corridor access. Pricing pressure intensifies in uncoated grades as digital substitution erodes transactional document volumes. Education publishers exhibit highest price sensitivity; luxury packaging converters demonstrate lowest.
Supply Chain Analysis
Extended payment terms from German publishing groups and supply-chain finance facilities from Nordic banking clusters sustain working capital cycles across the value chain. Geographic concentration centers on Finland, Germany, and Portugal for integrated production, with China and Japan supplying specialty grade imports. Raw material dependencies include bleached eucalyptus kraft pulp, clay coating minerals, and bio-based sizing agents. Single-source vulnerability runs through Iberian pulp supply to southern European mills. Distribution runs through direct mill relationships replacing merchant intermediaries for volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Woodfree paper sits in early-cycle expansion as EU Green Deal fiber traceability mandates accelerate certified virgin pulp adoption ahead of recyclability deadlines. Premium packaging substrate demand outpaces digital erosion in core publishing segments.
For Market Incumbents: Build certification moats through accelerated FSC chain-of-custody investment ahead of EU Green Deal enforcement backlogs. Secure eucalyptus pulp offtake agreements with Portuguese suppliers to buffer currency exposure. Defend against biochemical co-location entrants by valorizing lignin extractives in Finnish biorefinery clusters. For New Entrants and Emerging Players: Mid-scale biomass cogeneration project finance in the Rhine-Ruhr corridor represents the most penetrable entry point without full capital ownership requirements. Target security printing and archival specialty grades where technical certification barriers limit qualified supply. Pursue direct relationships with consolidated German publishing groups bypassing traditional merchant channels. For Investors and Strategic Acquirers: EU Green Deal implementation timelines reshape the acquisition landscape toward integrated mills with closed-loop water infrastructure. Long-term viability favors biorefinery-platform operators with multi-output revenue streams beyond commodity paper. Monitor ECHA chemical disclosure expansion as signal for formulation cost escalation favoring scaled producers.| Strategic Initiative | Industry Significance |
|---|---|
| Biochemical Co-location Investment | UPM-Kymmene's Kymenlaakso platform demonstrates lignin valorization revenue alongside traditional paper output. |
| Certification Acceleration Program | FSC chain-of-custody completion ahead of EU Green Deal deadlines secures German publishing procurement access. |
| Eucalyptus Pulp Integration | The Navigator Company's Setúbal operations anchor Iberian fiber dominance for European mill supply security. |
| Biomass Cogeneration Finance | Project finance structures fragment capital requirements allowing mid-scale Rhine-Ruhr entrants without full mill ownership. |
| Digital Print-Ready Substrate Engineering | Virtualized make-ready workflows enable just-in-time inventory patterns for magazine publishers and catalog houses. |
Study Parameters
Initial hypotheses were tested against primary input from pulp procurement directors, coating formulation chemists, publishing group supply chain managers, and merchant converter operations heads and refined through secondary validation. Trade data from Eurostat customs filings, Cefic chemical industry reports, FSC chain-of-custody audit records, and SEC 10-K disclosures from listed producers anchored quantitative foundations. Bottom-up mill capacity modeling and top-down end-use demand estimation were cross-referenced for triangulation.
Demand-supply balance dynamics across the projection horizon were modeled through segmented analysis of coated, uncoated, specialty, and lightweight grades by application in printing, packaging, stationery, and art supplies. CAGRs were derived from volume trajectory analysis against macroeconomic indicators and regulatory implementation schedules. Forecast inputs incorporated EU Green Deal compliance cost curves, eucalyptus pulp price volatility patterns, and digital substitution rates in corporate documentation.
Practitioners should monitor ECHA additive restriction proposals and FSC audit backlog durations for early signals of supply constraint or certification delay. Forecasts reflect assumptions on regulatory implementation pacing and fiber substitution economics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Europe Thermal Paper Market
Paper Products
Europe Decor Paper Market
Paper Products
Paper Goods Market
Paper Products
Overlay Paper Market
Paper Products
North America Coated Paper Market
Paper Products
North America Medium-Density Fiberboard Market
Paper Products
Liquid Paperboard Market
Paper Products
Medical Grade Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Reprographic Paper Market
Paper Products
Pulp Market
Paper Products
Decor Paper Market
Paper Products
Chemical Pulp Market
Paper Products
Glassine Paper Market
Paper Products
Europe Paper Market