
 Recyclable Thermal Insulation Packs Market | 2026-2036
Recyclable Thermal Insulation Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Recyclable Thermal Insulation Packs Market Analytics
E-commerce cold-chain shippers is reorganizing demand away from traditional construction contractors toward parcel-delivery and pharmaceutical logistics buyers. BASF SE leverages its polyurethane chemistry portfolio to serve temperature-controlled packaging specifications. Owens Corning Corporation anchors its position through glass-wool insulation adapted for reusable shipping containers. Kingspan Group PLC competes with rigid foam systems designed for multi-trip pharmaceutical totes.
Recyclable thermal insulation packs are engineered enclosures using recycled plastic, paper fibers, or bio-based composites to maintain stable internal temperatures during transit, typically achieving R-values between 3.5 and 6.0 per inch depending on material density and lamination structure. Their primary commercial purpose is protecting temperature-sensitive payloads in pharmaceutical, food, and specialty chemical distribution where single-use expanded polystyrene faces regulatory phase-out. Fiber-based products lead volume in European pharmaceutical corridors due to paper-recycling infrastructure compatibility, while polyurethane segments capture premium margin pools in ultra-low-temperature vaccine shipping where thinner profiles reduce dimensional weight charges. Bio-based materials represent the fastest-growing specification as brand-owners pursue Scope 3 emissions reductions and composting certifications.
The EU Packaging and Packaging Waste Regulation and REACH restrictions on persistent organic pollutants are reshaping material eligibility for cross-border shipments. EPA guidelines on industrial recycling content and California's extended producer responsibility frameworks are tightening specification requirements for packs entering North American pharmaceutical channels. Stakeholders must monitor how fragmented national recycling infrastructure investments determine which material platforms achieve viable end-of-life economics at scale.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitution away from expanded polystyrene toward fiber-based and bio-based alternatives across pharmaceutical and food cold-chain corridors. This regulatory compression is reshaping supplier qualification criteria and procurement specifications simultaneously.
Growth Catalysts
- REACH restrictions on persistent organic pollutants:The ECHA framework is disqualifying conventional foam chemistries from cross-border pharmaceutical shipments, redirecting specification toward recyclable fiber and bio-composite platforms.
- Cold-chain pharmaceutical logistics:Vaccine distribution networks are mandating multi-trip thermal protection with verified end-of-life pathways, creating specification pull for reusable insulation systems.
- German pharmaceutical distribution hubs:Stricter recycling mandates in this cluster are accelerating adoption of paper-fiber insulation compatible with existing municipal recycling infrastructure.
Market Restraints
- Recycled paper fiber input volatility:OCC pricing fluctuations and regional collection rate disparities create margin compression for fiber-based insulation manufacturers.
- Polyurethane chemical supply concentration:MDI and polyol production clusters in Northeast Asia and the US Gulf Coast expose premium bio-based foam producers to feedstock disruption risk.
- Performance gap at ultra-low temperatures:Bio-based alternatives currently require thicker profiles than expanded polystyrene to achieve equivalent R-values, increasing dimensional weight charges.
Strategic Opportunities
- Indian pharmaceutical cold-chain expansion:CDSCO temperature integrity requirements for biologics distribution are creating first-mover advantage for recyclable insulation suppliers establishing local production.
- Composting certification alignment:EN 13432 and ASTM D6400 compliance is enabling premium positioning in European organic food subscription channels.
- Reusable tote pooling systems:Integration with pharmaceutical logistics platforms is creating captive demand cycles for rigid foam systems designed for multi-trip validation.
Industry Challenges
- Thermal validation protocol complexity:ISTA 7E and WHO PQS certification timelines extend 12-18 months, delaying product commercialization for novel bio-based materials.
- Reverse logistics infrastructure gaps:Collection and reprocessing networks for multi-trip pharmaceutical totes remain underdeveloped outside German and Dutch distribution corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recyclable Thermal Insulation Packs Market |
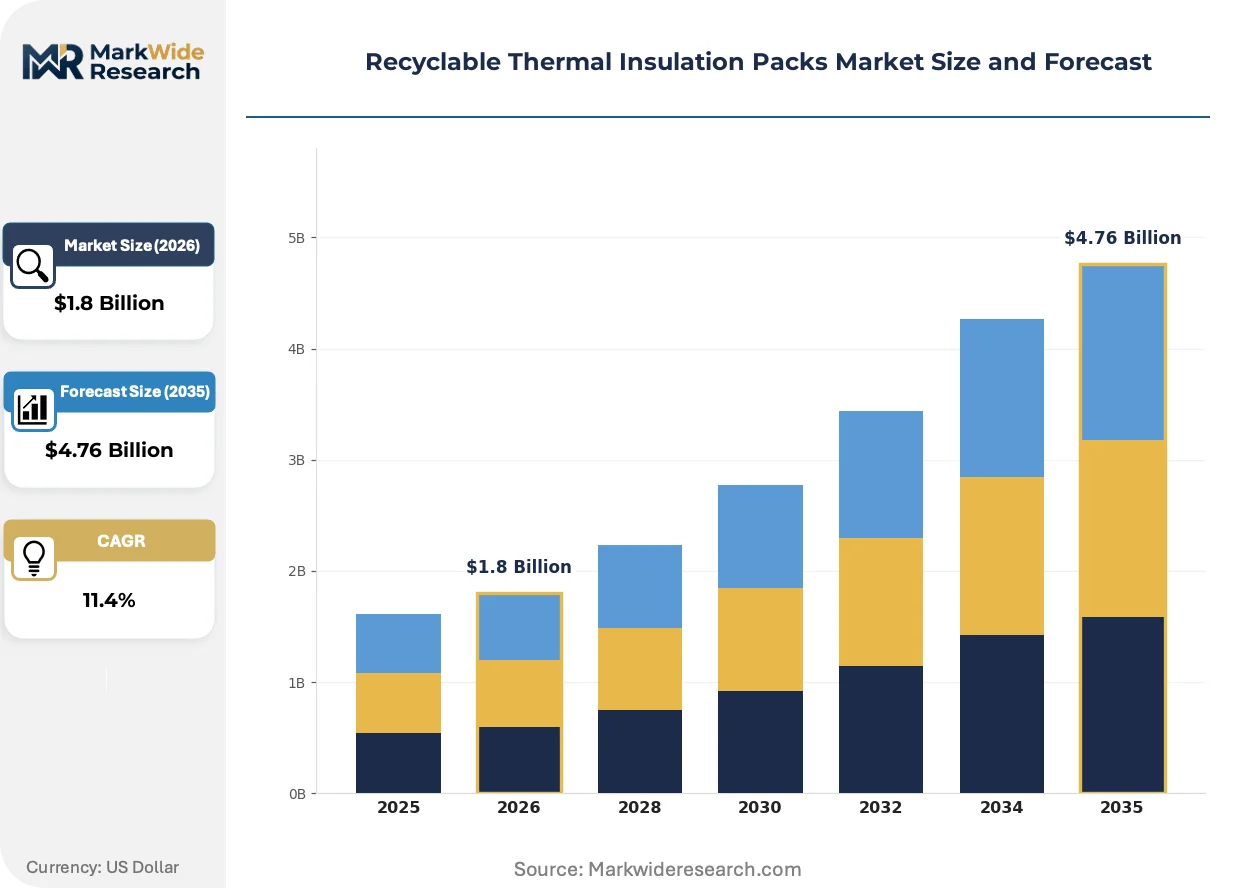
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPS, XPS, Polyurethane, Fiber-based Application: Construction, HVAC, Automotive, Shipping End User: Manufacturers, Contractors, Distributors, Retailers Material: Recycled Plastic, Paper, Bio-based, Composite |
| Companies Covered | Rockwool International A/S, BASF SE, Owens Corning Corporation, Armacell International S.A., Huntsman International LLC, Kingspan Group PLC, Saint-Gobain S.A., Knauf Insulation, Inc., Johns Manville Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recyclable Thermal Insulation Packs Market Evolving Landscape
Material science advances and regulatory compression are converging to displace single-use expanded polystyrene from temperature-controlled packaging. Three interconnected developments are restructuring competitive positioning and procurement criteria.
Cellulose aerogel composites are fragmenting the premium insulation segment by delivering R-values exceeding 4.0 per inch at densities below 0.15 g/cm³. Pharmaceutical shippers requiring ultra-thin profiles for international express parcels are adopting these materials despite 40-60% cost premiums over conventional fiber boards. The technology is fragmenting supplier tiers by enabling new entrants with materials science backgrounds to bypass established foam chemistry incumbents.
REACH Annex XVII restrictions on persistent organic pollutants are tightening material eligibility for cross-border pharmaceutical shipments. The ECHA framework is disqualifying halogenated flame retardants used in conventional expanded polystyrene, forcing reformulation toward phosphorus-based or bio-based alternatives. German and Benelux pharmaceutical distributors are responding by pre-qualifying insulation suppliers against 2026 compliance deadlines, compressing vendor selection timelines.
Subscription meal-kit operators are consolidating supplier relationships around vertically integrated packaging platforms. These buyers are displacing spot-market procurement with multi-year framework agreements that bundle thermal insulation with outer corrugate and refrigerant gel packs. The Netherlands and Denmark represent the most advanced adoption corridors, where operational scale justifies dedicated reverse logistics for reusable cold-chain containers.
Recyclable Thermal Insulation Packs Market Segmentation
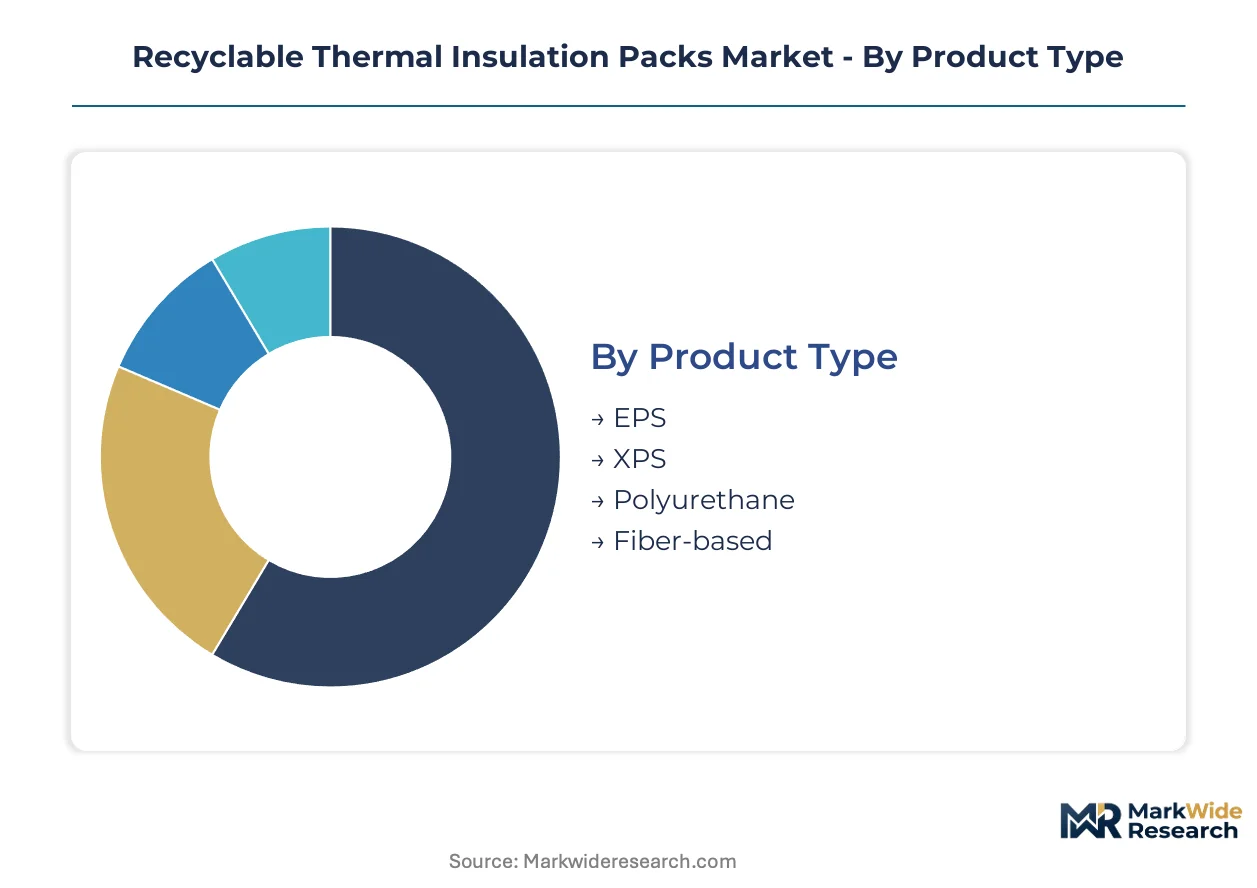
Segmentation in recyclable thermal insulation packs determines which material platforms achieve viable end-of-life economics and which applications justify premium pricing. Procurement specifications diver sharply between pharmaceutical cold-chain corridors requiring validated multi-trip systems and construction contractors prioritizing lowest installed cost.
Product Type:
REACH Annex XVII restrictions on persistent organic pollutants are disqualifying halogenated chemistries from pharmaceutical shipments, fragmenting qualification pathways across material platforms.
- Fiber-based:Engineered from recycled corrugated containers and kraft fibers with R-values between 3.5 and 4.5 per inch. German pharmaceutical distributors specify these packs for their compatibility with municipal paper-recycling infrastructure and verified end-of-life pathways.
- Polyurethane:Rigid foam systems delivering R-values exceeding 6.0 per inch in profiles half the thickness of fiber alternatives. Ultra-low-temperature vaccine shippers absorb 25-40% cost premiums to reduce dimensional weight charges on international express parcels.
- EPS:Conventional expanded polystyrene facing regulatory phase-out across EU pharmaceutical corridors under Packaging and Packaging Waste Regulation timelines.
- XPS:Extruded polystyrene foam with higher compressive strength than EPS, retaining niche construction applications where load-bearing performance outweighs recyclability mandates.
Fiber-based systems handle the majority of European pharmaceutical throughput; polyurethane is gaining share fastest in ultra-low-temperature vaccine distribution.
Application:
Cost tier stratification separates multi-use pharmaceutical systems from single-trip construction applications where material substitution faces lowest resistance.
- Shipping:Temperature-controlled parcel protection for pharmaceuticals, meal kits, and specialty chemicals. E-commerce cold-chain operators in the Netherlands and Denmark are consolidating procurement around vertically integrated packaging platforms bundling insulation with outer corrugate and refrigerant gel packs.
- Construction:Building envelope insulation using recycled content boards. Contractors prioritize lowest installed cost, slowing adoption of bio-based alternatives until performance gaps at equivalent R-values narrow.
- HVAC:Ductwork and equipment insulation requiring fire-rated specifications. REACH restrictions on halogenated flame retardants are forcing reformulation toward phosphorus-based systems.
- Automotive:Thermal management for battery packs and climate control systems. OEMs are specifying recycled-content insulation to meet EU corporate sustainability reporting requirements.
Shipping commands premium pricing per unit; construction moves the largest material volumes on aggregate demand.
Material:
Supply concentration in Northeast Asian MDI and polyol clusters exposes bio-based foam producers to feedstock disruption risk, while paper-fiber supply tracks OCC collection rate volatility.
- Paper:Recycled corrugated containerboard and kraft fiber processed into molded pulp or laminated board insulation. German distribution hubs specify paper-based systems to satisfy stricter recycling mandates and municipal infrastructure compatibility.
- Bio-based:Mycelium, starch, and agricultural residue composites achieving composting certification under EN 13432. European organic food subscription channels absorb 30-50% cost premiums for verified end-of-life pathways.
- Recycled Plastic:Post-consumer PET and HDPE processed into fiber or foam insulation. California's extended producer responsibility frameworks are tightening content requirements for packs entering North American pharmaceutical channels.
- Composite:Hybrid structures combining fiber facing with bio-based or recycled foam cores. Cellulose aerogel composites are fragmenting the premium segment by delivering R-values exceeding 4.0 per inch at densities below 0.15 g/cm³.
Paper dominates current volume; bio-based alternatives are climbing fastest on brand-owner Scope 3 emissions reduction commitments.
End User:
Customer type determines procurement complexity, with pharmaceutical distributors imposing 12-18 month validation protocols that exclude spot-market suppliers.
- Distributors:Pharmaceutical and food cold-chain logistics operators specifying multi-trip thermal protection with verified end-of-life pathways. German and Benelux distributors are pre-qualifying suppliers against 2026 REACH compliance deadlines.
- Manufacturers:Insulation pack producers and packaging converters selecting material inputs based on recycled content mandates and chemical compliance requirements.
- Contractors:Construction installers prioritizing lowest material cost and familiar handling characteristics, slowing adoption of novel bio-based formats.
- Retailers:Meal-kit and specialty food subscription services consolidating supplier relationships around framework agreements bundling thermal protection with outer packaging and refrigerants.
Distributors drive specification innovation; retailers are expanding volume fastest through subscription model scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distributors and meal-kit subscription services concentrate demand across four distinct national markets, each imposing unique regulatory compliance frameworks and recycling infrastructure requirements on insulation pack specifications.
Germany
Pharmaceutical distribution hubs in Frankfurt and Munich drive specification upgrades for fiber-based insulation compatible with municipal paper-recycling streams. The country's national packaging regulator enforces stricter recycling mandates through the Verpackungsgesetz amendments. North Rhine-Westphalia hosts the densest cluster of cold-chain logistics operators pre-qualifying suppliers against 2026 REACH compliance deadlines.
United States
California's extended producer responsibility frameworks tighten content requirements for packs entering pharmaceutical channels, while meal-kit operators in the Northeast consolidate procurement around vertically integrated platforms. The EPA issues guidelines on industrial recycling content that reshape qualification criteria for cross-border shipments. Greater Boston anchors biotech corridor demand for validated multi-trip thermal protection systems.
Netherlands
Subscription meal-kit operators achieve operational scale sufficient to justify dedicated reverse logistics for reusable cold-chain containers. The country's national environmental agency enforces Packaging and Packaging Waste Regulation timelines that accelerate material substitution away from expanded polystyrene. The Randstad conurbation concentrates Europe's most advanced adoption corridor for vertically integrated packaging platforms.
India
CDSCO temperature integrity requirements for biologics distribution create first-mover advantage for recyclable insulation suppliers establishing local production. The national pharmaceutical regulator mandates cold-chain validation protocols that extend 12-18 months for novel bio-based materials. Maharashtra's Mumbai-Pune pharmaceutical manufacturing belt attracts specification-driven procurement from multinational vaccine distributors.
Denmark
Organic food subscription channels absorb cost premiums for composting-certified insulation under EN 13432 compliance frameworks. The country's environmental protection agency enforces strict organic waste diversion targets that favor bio-based alternatives. Copenhagen anchors Nordic demand for reusable tote pooling systems integrated with pharmaceutical logistics platforms.
Recyclable Thermal Insulation Packs Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates and specialized building materials producers with adjacent cold-chain packaging capabilities. The market exhibits moderate consolidation at the premium tier, where polyurethane chemistry expertise and fiber-processing scale create qualification barriers. Three archetypes dominate: integrated chemical producers leveraging polymer portfolios, construction insulation specialists adapting products for shipping applications, and emerging bio-composite innovators targeting composting certification. Capacity expansion and strategic partnerships represent the dominant competitive moves, with incumbents securing recycled fiber supply agreements and novel material developers pursuing validation protocol acceleration.
Among European-based diversified producers, BASF SE and Saint-Gobain S.A. occupy positions that exemplify chemistry-to-application integration strategies. Owens Corning Corporation anchors the North American tier where glass-wool expertise translates into reusable shipping container specifications. Kingspan Group PLC represents the rigid foam systems segment competing on multi-trip pharmaceutical tote validation. These three companies illustrate how incumbent positioning in construction insulation creates adjacent market entry pathways into temperature-controlled packaging.
| Leading Market Players |
|---|
| Rockwool International A/S |
| BASF SE |
| Owens Corning Corporation |
| Armacell International S.A. |
| Huntsman International LLC |
| Kingspan Group PLC |
| Saint-Gobain S.A. |
| Knauf Insulation, Inc. |
| Johns Manville Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German paper-fiber processing plants sits above 85%, compressing margin buffers for fiber-based insulation converters and elevating price floors for pharmaceutical distributors. This scale concentration reinforces Northeast Asian polyurethane feedstock clusters as alternative supply anchors, fragmenting procurement leverage across material platforms.
Pricing Analysis
Cost-plus contracts with OCC indexation dominate fiber-based tier negotiations, while polyurethane segments track MDI spot benchmarks from Northeast Asian trading hubs. Three-tier pricing structure across pharmaceutical validation-grade, standard commercial, and economy construction tiers separates premium R-value performance from municipal recycling compatibility. Cost compression in fiber-based tiers is intensifying because OCC collection rate volatility and energy input spikes squeeze converter margins. Construction contractors exhibit highest price sensitivity, while vaccine distributors absorbing dimensional weight penalties show lowest elasticity.
Supply Chain Analysis
Inbound logistics costs from Rotterdam-Antwerp port congestion and container availability constraints on Asia-Europe trade lanes elevate landed costs for MDI and polyol feedstocks. Supply concentrates in Germany for fiber processing, China and South Korea for MDI/polyol production, and the US Gulf Coast for specialty polyol variants. Raw material dependencies span recycled corrugated containers, mycelium substrates, and post-consumer PET streams. Single-source vulnerability in Northeast Asian isocyanate clusters exposes bio-based foam producers to feedstock disruption. Distribution runs through pharmaceutical logistics platforms in German and Benelux corridors, with construction channels fragmented across regional building-material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated meal-kit operators and pharmaceutical logistics platforms, compressing supplier margins and forcing qualification protocol acceleration. E-commerce cold-chain consolidation around framework agreements has halved spot-market procurement volumes in advanced European corridors.
For Market Incumbents: Secure long-term OCC supply agreements with German municipal collection networks to defend fiber-based margin positions against price volatility. Anchor capacity utilization through multi-year pharmaceutical validation contracts that lock in specification tiers before REACH compliance deadlines tighten. Counter cellulose aerogel entrants by accelerating in-house composting certification pathways under EN 13432 frameworks. For New Entrants and Emerging Players: Differentiate on composting certification alignment to capture premium positioning in European organic food subscription channels where brand-owners absorb 30-50% cost premiums. Target Indian pharmaceutical cold-chain expansion corridors where CDSCO validation requirements create first-mover windows for local production establishment. Pursue partnership-based go-to-market models with Dutch meal-kit operators seeking dedicated reverse logistics integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical logistics platforms with multi-trip tote pooling systems, offering superior cash flow predictability over construction spot-market exposure. Five-to-ten year viability favors material science innovators with validated thermal protocols and backward integration into recycled fiber supply. Monitor composting certification adoption rates in Nordic markets as inflection indicator for bio-based segment premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Supply | Secures OCC input stability for German pharmaceutical corridor dominance. |
| Composting Certification Acceleration | Unlocks premium positioning under EN 13432 for European organic food channels. |
| Multi-Trip Tote Validation Investment | Captures pharmaceutical logistics platform demand with verified end-of-life pathways. |
| Local Production Establishment in India | Addresses CDSCO temperature integrity requirements for biologics distribution growth. |
| Cellulose Aerogel R&D Partnership | Fragments premium insulation segment with R-values exceeding 4.0 per inch. |
Research Methodology
Desk research of EU regulatory filings, REACH Annex XVII amendments, and pharmaceutical cold-chain validation databases preceded structured interviews with logistics procurement directors, packaging converters, and regulatory compliance officers. Primary fieldwork with German pharmaceutical distributors and Dutch meal-kit operators validated secondary demand estimates. Customs trade data, ECHA substance restriction timelines, and municipal recycling infrastructure reports furnished supply-side calibration. Bottom-up volume modeling triangulated against top-down market sizing from industry association disclosures.
Variance decomposition across material platform, application tier, and geographic adoption pattern shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled include product type, end-use application, material composition, and customer archetype, with regulatory compliance tier as industry-specific overlay. CAGRs derived from logistic curve fitting to adoption rate data, cross-referenced with capacity expansion announcements and validation protocol timelines. Forecast inputs incorporated REACH enforcement intensity assumptions and municipal recycling infrastructure investment trajectories.
Decision-makers should treat outputs as directional under sustained EU Packaging and Packaging Waste Regulation enforcement and stable OCC collection rate assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without contingency for abrupt feedstock supply disruptions or accelerated halogenated chemistry phase-outs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Electrical Insulation Materials Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Protective Building Materials Market