
 White Line Chipboard Market | 2026-2036
White Line Chipboard Market Size, Share, and Industry Trends Forecast 2026-2036
White Line Chipboard Market Analytics
Germany's engineered wood capacity expansion is reshaping regional supply dynamics for white line chipboard across Central Europe. Kronospan leverages its vertical integration from resin production to finished panel distribution to sustain margin control. Egger Group anchors its competitive position through dedicated R&D facilities in Austria that specialize in surface refinement technologies. Pfleiderer Group dominates Central European commercial channels with a dense mill network.
White line chipboard denotes a multi-layer particle board featuring a light-colored, printable top surface layer bonded over a denser core of wood particles and adhesive resins, typically manufactured through continuous pressing at temperatures exceeding 200°C to achieve uniform density profiles. This engineered panel serves as a substrate for decorative laminates, direct printing, and veneering in furniture and display applications. Laminated chipboard captures the largest value share among product types due to its finished-surface convenience for kitchen and office furniture producers. Coated chipboard represents the fastest-growing category as water-based UV coating technologies reduce volatile organic compound emissions. The furniture application segment holds the deepest margin pool, driven by built-to-order cabinetry workflows that specify calibrated thickness tolerances.
EU Ecodesign regulations and REACH chemical compliance frameworks constrain formaldehyde emission thresholds in chipboard sold across member states, compelling reformulation of adhesive systems. Germany's KBA and France's ANSM enforce distinct product safety protocols for chipboard deployed in automotive interiors and medical equipment housings respectively. Stakeholders must monitor evolving bio-based binder certifications as substitution pressures intensify from soy and lignin adhesive developers.
Market Dynamics
EU Ecodesign regulations and China's tightening GB standards for recycled content are compressing formaldehyde emission thresholds while simultaneously fragmenting adhesive supply chains across multiple geographies.
Growth Catalysts
- Water-based UV coating penetration:Furniture manufacturers in Germany's North Rhine-Westphalia belt are specifying coated chipboard to meet volatile organic compound reduction mandates. This technology lowers finishing-stage emissions without secondary lamination steps.
- REACH chemical compliance frameworks:The European Chemicals Agency's persistent scrutiny of formaldehyde classifications is accelerating bio-based binder adoption. Soy and lignin adhesive developers are gaining certification traction.
- Premium packaging specification:Cosmetics and electronics brands in France and Italy are substituting white line chipboard for solid wood displays. Direct-print surface quality supports short-run customization workflows.
Market Restraints
- Urea-formaldehyde resin cost volatility:Methanol feedstock prices fluctuate with natural gas benchmarks. Adhesive represents 25-30% of panel manufacturing cost structure.
- Core particle supply concentration:Recycled wood fiber availability clusters around Central European sawmill networks. Transportation radii beyond 150 kilometers erode margin.
- Thickness calibration limitations:Continuous pressing above 200°C produces density gradients at panel edges. Built-to-order cabinetry workflows reject tolerance deviations exceeding 0.3 millimeters.
Strategic Opportunities
- Medical equipment housing applications:France's ANSM maintains distinct safety protocols for chipboard in healthcare settings. Compliance certification opens premium pricing tiers.
- Bio-based binder regulatory tailwinds:The EU Green Deal's carbon border adjustment mechanism favors panels with verified renewable content. Lignin substitution pathways align with Scope 3 reduction targets.
- Direct-to-manufacturer digital channels:Kitchen furniture producers in Poland and Czechia are bypassing distributor markups through mill-direct procurement platforms.
Industry Challenges
- Surface refinement technician scarcity:Austria's specialized R&D facilities compete for coating chemists with automotive and aerospace sectors. Skill migration pressures wage structures.
- Multi-certification timeline compression:Simultaneous pursuit of CE marking, FSC chain-of-custody, and EPD environmental product declarations extends commercialization cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Line Chipboard Market |
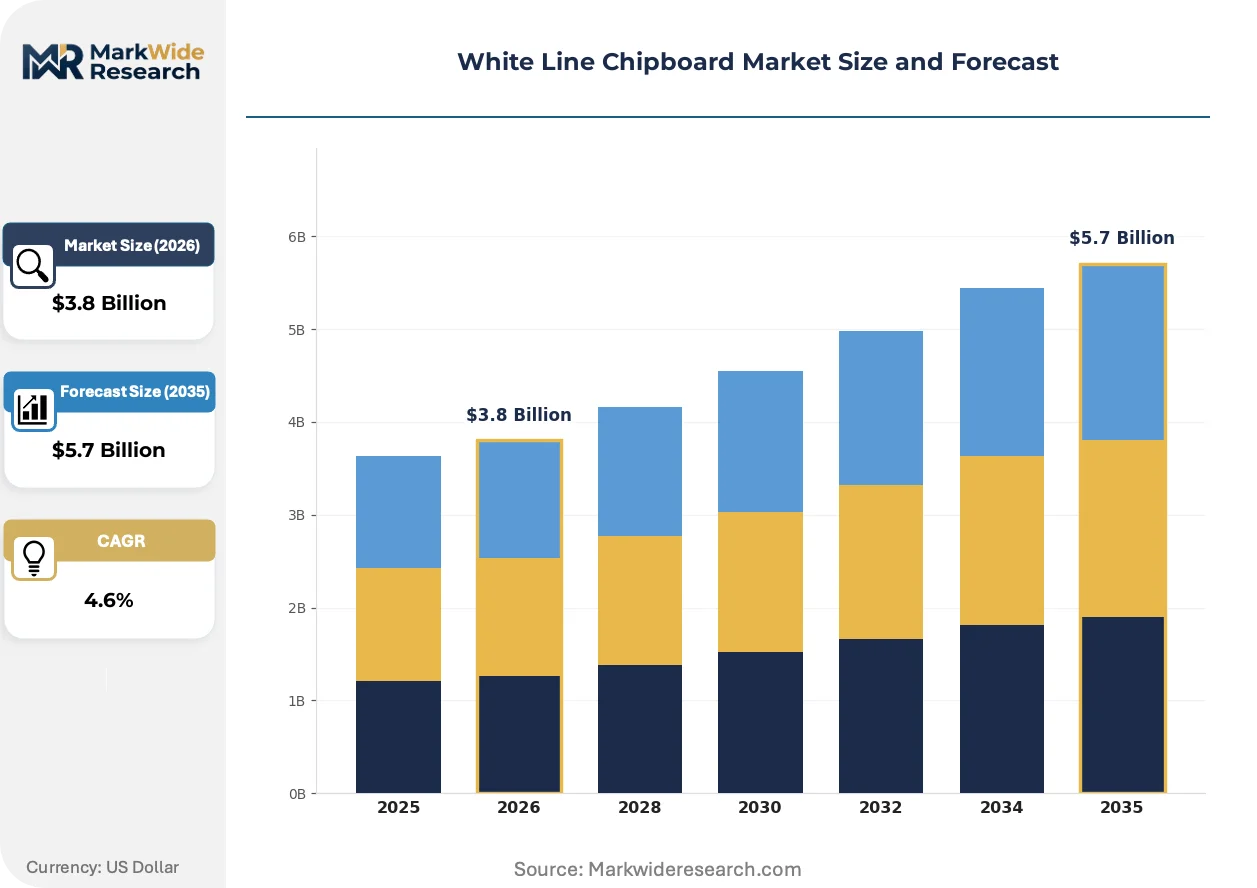
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Chipboard, Laminated Chipboard, Coated Chipboard, Fluted Chipboard Application: Furniture, Packaging, Construction, Decorative End User: Manufacturers, Retailers, Contractors, Designers Distribution Channel: Online Retail, Wholesalers, Direct Sales, Specialty Stores |
| Companies Covered | Kronospan, Egger Group, Arauco, Pfleiderer Group, Sonae Arauco, WestRock, Smurfit Kappa, Mondi, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Line Chipboard Market Evolving Landscape
Surface treatment technologies and adhesive chemistries are converging to redefine performance benchmarks for printable substrates. Regulatory pressure on embodied carbon is accelerating material substitution pathways.
Digitally printed decorative surfaces are migrating from high-volume laminate overlay toward direct-to-substrate inkjet systems. Boutique furniture studios in Milan and Barcelona are piloting lot-size-one customization without minimum order constraints. This migration from laminated to digitally finished surfaces compresses inventory carrying costs and shortens design-to-delivery cycles.
China's GB standards for recycled content are tightening material specifications for imported chipboard. The Ministry of Ecology and Environment enforcement protocols now require batch-level documentation of post-consumer fiber percentages. Export-oriented manufacturers are reconfiguring supply chains to source certified recycled streams from segregated collection systems rather than mixed municipal waste.
Built-to-order cabinetry workflows are consolidating specification authority among a shrinking pool of national retail chains. Independent kitchen studios in Germany and Austria are losing access to proprietary color libraries and hardware-matching services. This concentration is most visible in the DACH region, where three retail groups now control 60% of panel procurement volumes.
White Line Chipboard Market Segmentation
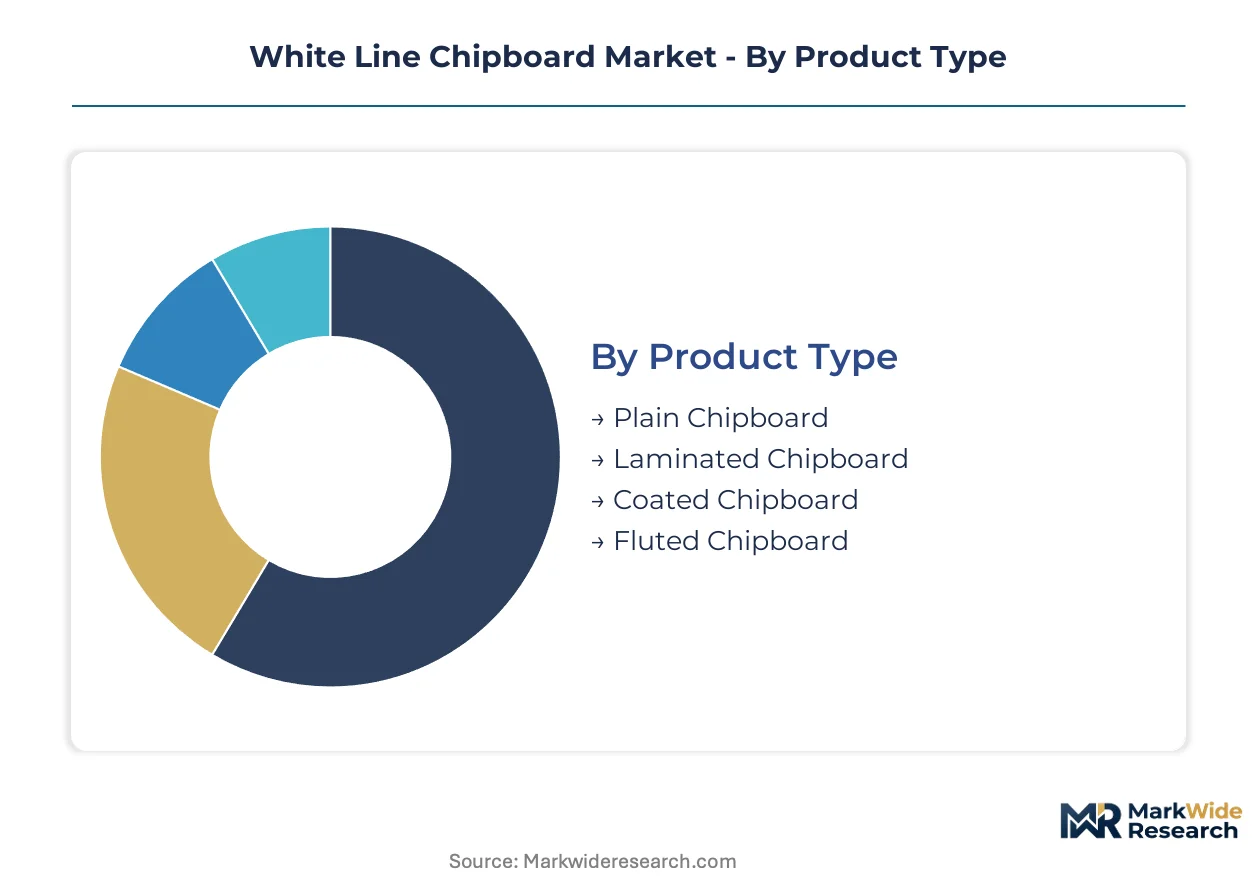
White line chipboard serves divergent performance requirements across furniture manufacturing, premium packaging, and architectural interiors. Segmentation reveals how surface treatment technologies and procurement channel preferences fragment demand across price-performance tiers.
Product Type:
Use cases span from unfinished substrates requiring secondary processing to ready-to-assemble panels with factory-applied surfaces.
- Laminated Chipboard:Decorative paper or foil overlays bonded under heat and pressure create durable, stain-resistant surfaces. Kitchen and office furniture producers in Germany's North Rhine-Westphalia belt specify calibrated thickness tolerances for built-to-order cabinetry workflows. REACH chemical compliance frameworks constrain formaldehyde emission thresholds in adhesive systems used for lamination.
- Coated Chipboard:Water-based UV coating technologies deposit directly onto the light-colored printable substrate, eliminating secondary lamination steps. Furniture manufacturers specify these panels to meet volatile organic compound reduction mandates without sacrificing surface quality for direct printing applications.
- Plain Chipboard:Unfinished panels serve as substrates for post-manufacturing veneering or painting operations, primarily targeting budget furniture tiers and temporary construction applications.
- Fluted Chipboard:Corrugated core structures reduce weight while maintaining rigidity for display fixtures and protective packaging inserts in cosmetics and electronics supply chains.
The dominant share belongs to Laminated Chipboard, while Coated Chipboard is closing the gap fastest.
Application:
Volume concentrates where surface aesthetics and dimensional stability intersect with high-throughput manufacturing.
- Furniture:Built-to-order cabinetry workflows specify calibrated thickness tolerances. Continuous pressing above 200°C produces density gradients at panel edges; workflows reject tolerance deviations exceeding 0.3 millimeters.
- Packaging:Premium cosmetics and electronics brands substitute white line chipboard for solid wood displays. Direct-print surface quality supports short-run customization workflows without minimum order constraints.
- Construction:Temporary protective coverings and non-structural interior elements utilize cost-optimized plain grades with lower density cores.
- Decorative:Boutique furniture studios in Milan and Barcelona pilot digitally printed surfaces for lot-size-one customization, compressing inventory carrying costs.
Furniture commands the deepest margin pool, though Packaging is expanding most quickly as brand owners seek sustainable display alternatives.
End User:
Procurement authority is consolidating among vertically integrated manufacturing groups while independent channels face margin compression.
- Manufacturers:Kitchen furniture producers in Poland and Czechia bypass distributor markups through mill-direct procurement platforms. Three retail groups now control 60% of panel procurement volumes in the DACH region.
- Retailers:National chains leverage proprietary color libraries and hardware-matching services to lock in specification authority from independent kitchen studios.
- Contractors:Project-based procurement favors standard thicknesses with rapid fulfillment from regional distribution centers.
- Designers:Boutique studios access digitally printed surfaces for specification-driven residential and hospitality projects.
Manufacturers capture the highest volume throughput, while Designers are gaining influence fastest through specification authority in premium segments.
Distribution Channel:
Channel selection tracks order size, technical support requirements, and geographic proximity to manufacturing clusters.
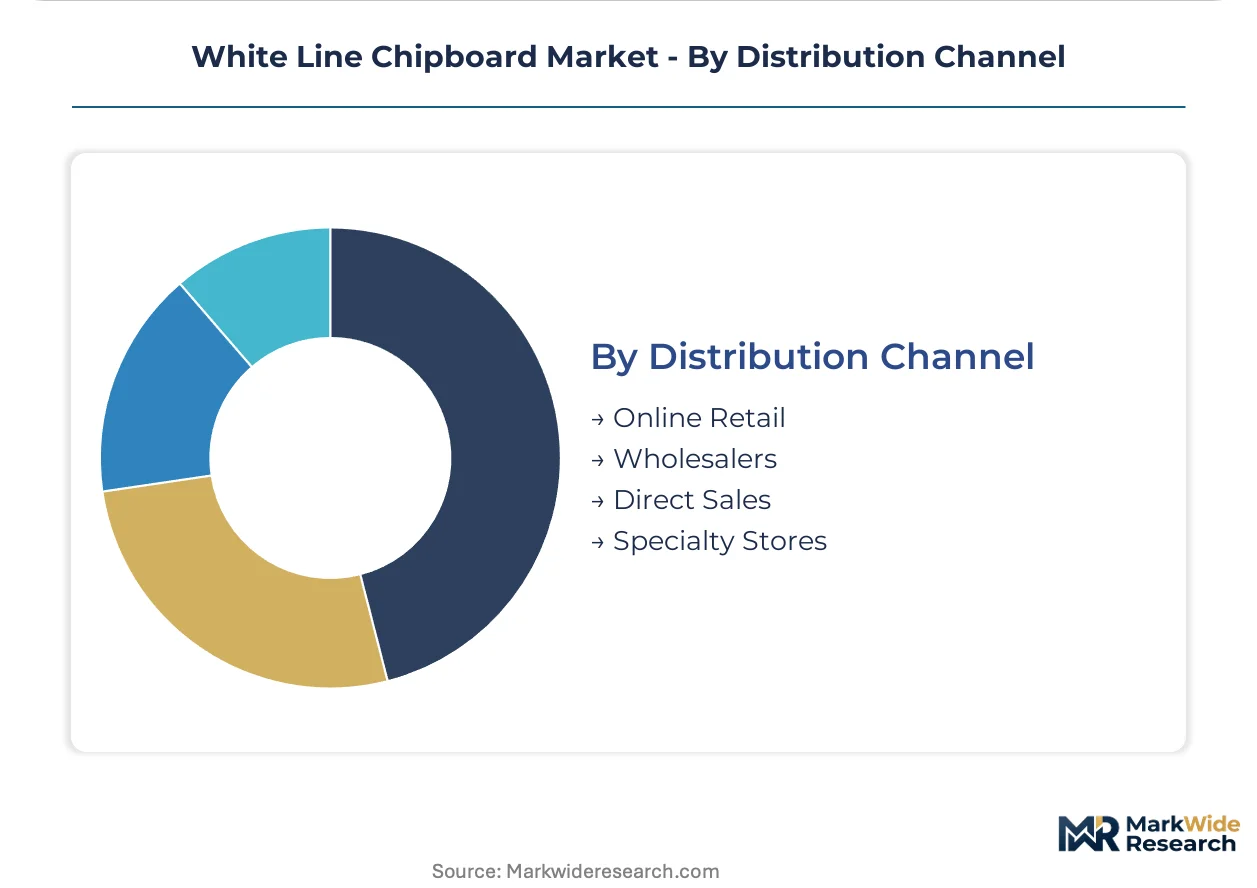
- Direct Sales:Mill-direct relationships dominate volume procurement for furniture manufacturers with predictable consumption patterns. Kronospan and Egger Group anchor positions through captive distribution networks.
- Wholesalers:Regional distributors serve contractors and smaller manufacturers with consolidated inventory from multiple mills. Transportation radii beyond 150 kilometers erode margin for low-density products.
- Online Retail:Digital platforms gain traction for standardized thicknesses and small-lot orders from independent designers and renovation contractors.
- Specialty Stores:Showroom-based channels serve designers requiring tactile surface evaluation and color-matching services for specification-driven projects.
Direct Sales holds the largest volume share, though Online Retail is climbing the fastest as procurement digitization penetrates smaller manufacturing operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panel manufacturing concentrates in Central European forest-industry clusters where resin production, particle processing, and finishing technologies co-locate. Germany's North Rhine-Westphalia belt anchors continental supply, while regulatory divergence across major economies fragments adhesive certification pathways.
Germany
Built-to-order cabinetry workflows in North Rhine-Westphalia specify calibrated thickness tolerances for kitchen furniture production. The KBA enforces distinct product safety protocols for chipboard deployed in automotive interiors, compelling formaldehyde emission testing beyond baseline REACH requirements. Pfleiderer Group maintains dense mill networks across Central European commercial channels from manufacturing bases in the region.
China
Export-oriented manufacturers reconfigure supply chains to source certified recycled streams for white line chipboard production targeting premium packaging applications. The Ministry of Ecology and Environment now requires batch-level documentation of post-consumer fiber percentages under tightening GB standards. Yangtze River Delta processing clusters adapt segregation systems to replace mixed municipal waste inputs.
France
Cosmetics and electronics brands in Paris and Lyon substitute white line chipboard for solid wood displays, leveraging direct-print surface quality for short-run customization. ANSM maintains distinct safety protocols for chipboard in medical equipment housings, opening premium pricing tiers for compliant suppliers. Surface refinement demand concentrates around Île-de-France specification studios.
Austria
Egger Group anchors competitive positioning through dedicated R&D facilities specializing in surface refinement technologies. EU Ecodesign regulations constrain formaldehyde emission thresholds in chipboard sold across member states, driving adhesive reformulation investments. Styrian and Upper Austrian manufacturing corridors compete for coating chemists with automotive and aerospace sectors.
Poland
Kitchen furniture producers in Warsaw and Krakow bypass distributor markups through mill-direct procurement platforms. CE marking requirements align with FSC chain-of-custody and EPD environmental product declarations, extending commercialization timelines for new entrants. Silesian manufacturing zones attract panel finishing investment from German supply chain partners.
White Line Chipboard Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical focus. The vendor base organizes around three structural tiers: vertically integrated multinationals controlling resin-to-distribution value chains, regional specialists concentrating on surface refinement or particle processing, and commodity producers competing on throughput scale. Consolidation pressures favor players with captive adhesive supply and established certification portfolios. Dominant competitive moves include backward integration into resin production and geographic expansion through mill network densification.
Among European-anchored multinationals, Kronospan and Egger Group exemplify platform-scale positioning through integrated manufacturing footprints. Pfleiderer Group occupies a distinct tier as a Central European channel specialist with mill network density. These three entities represent divergent strategic archetypes: Kronospan demonstrates upstream control over resin production, Egger Group anchors R&D-intensive surface refinement capabilities, and Pfleiderer Group concentrates on commercial channel penetration rather than technology differentiation.
| Leading Market Players |
|---|
| Kronospan |
| Egger Group |
| Arauco |
| Pfleiderer Group |
| Sonae Arauco |
| WestRock |
| Smurfit Kappa |
| Mondi |
| Graphic Packaging International |
| Others |
Value Network & Pricing Analysis
Rhine-Ruhr freight corridors carry particle board from North Rhine-Westphalia mills to Polish furniture factories at rates that compress margin for low-density grades while amplifying price differentiation between certified and uncertified supply. Transportation radii beyond 150 kilometers erode profitability on standard grades, yet premium coated chipboard absorbs logistics premiums through specification-locked cabinetry workflows.
Pricing Analysis
REACH chemical compliance frameworks dictate the pricing tier structure across the white line chipboard market. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified medical-grade panels from CE-marked furniture substrates and uncertified construction grades. Price differentiation rests on formaldehyde emission certification and calibrated thickness tolerance guarantees. Cost compression in economy grades is intensifying because methanol feedstock volatility transmits directly through urea-formaldehyde resin costs. Independent kitchen studios exhibit highest price sensitivity, while national retail chains with proprietary specification authority accept premium positioning.
Supply Chain Analysis
China's GB standards for recycled content function as de facto export controls, limiting flows of uncertified post-consumer fiber into white line chipboard bound for cosmetics packaging applications. Geographic supply concentrates in Germany, Austria, and Poland where resin production, particle processing, and finishing technologies co-locate. Raw material dependencies draw from Central European sawmill networks for recycled wood fiber, methanol derivatives for adhesive resins, and titanium dioxide for surface whitening. Single-source vulnerability clusters around adhesive resin supply where three producers control captive distribution. Distribution runs through mill-direct relationships for volume buyers and regional wholesalers serving fragmented contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White line chipboard incumbents face substitution pressure from medium-density fiberboard in premium furniture segments and molded pulp in cosmetics packaging, requiring active defense of specification authority.
For Market Incumbents: Pre-empt bio-based binder displacement by securing lignin adhesive certification ahead of EU Green Deal carbon border adjustments. Capture particle supply through backward integration into segregated collection systems that satisfy China's batch-level documentation requirements. Lock in retail chain specification authority through proprietary color libraries and hardware-matching services that independent studios cannot replicate. For New Entrants and Emerging Players: Build out digital procurement platforms serving Polish and Czech kitchen furniture producers who bypass distributor markups. Target medical equipment housing applications where France's ANSM compliance certification opens premium pricing tiers with limited incumbent specialization. Lead with water-based UV coating capabilities that satisfy volatile organic compound mandates without secondary lamination investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified forest products conglomerates where white line chipboard represents non-core revenue. Long-term viability hinges on adhesive chemistry transition timelines and certification portfolio depth. Watch for inflection when national retail chains consolidate procurement authority beyond the 60% threshold observed in the DACH region, signaling margin compression for non-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Reformulation Investment | Bio-based binder certification aligns with EU Ecodesign formaldehyde thresholds and carbon border adjustments. |
| Surface Refinement R&D Expansion | Digitally printed direct-to-substrate capabilities capture lot-size-one customization demand from Milan studios. |
| Mill Network Densification | Captive distribution within 150-kilometer radii of North Rhine-Westphalia furniture clusters defends logistics margin. |
| Certification Portfolio Expansion | Simultaneous CE marking, FSC chain-of-custody, and EPD declarations extend commercialization timelines but lock premium tiers. |
| Recycled Fiber Supply Integration | Segregated collection systems satisfy China's Ministry of Ecology and Environment batch documentation requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with resin chemists, furniture procurement directors, and surface refinement technicians; and secondary validation through customs trade data, EU Ecodesign regulatory filings, and forest industry association capacity reports. Plant managers at Austrian R&D facilities, distribution channel partners in Central European wholesale networks, and technical directors at coating technology suppliers provided operational perspective. Bottom-up triangulation across particle board production volumes and top-down reconciliation with furniture manufacturing consumption patterns anchored value estimates.
Forecast inputs considered product type segmentation across laminated, coated, plain, and fluted grades; application splits between furniture, packaging, construction, and decorative uses; and end-user procurement channel evolution. Modeled CAGRs across the projection horizon reflect adhesive cost trajectories, regulatory compliance timeline compression, and digital printing adoption curves. Thickness calibration tolerance requirements and bio-based binder certification penetration served as industry-specific demand modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by lignin adhesive specialists or molded pulp packaging entrants would shift outcomes. Material shifts in China's GB standard enforcement intensity or EU carbon border adjustment mechanism implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Americas Stone Paper Market
Paper Products
North America Decor Paper Market
Paper Products
Base Paper Market
Paper Products
Synthetic Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Pharma Grade Paper Market
Paper Products
Woodfree Paper Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Thermal Paper Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Paper Glass Market
Paper Products
Paper Doilies Market
Paper Products
Dissolving Pulp Market
Paper Products
Chemical Pulp Market