
 Global Thin Papers Market | 2026-2036
Global Thin Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thin Papers Market Outlook
Direct sales channels serving pharmaceutical and luxury packaging houses is reconfiguring how thin paper producers allocate technical service resources. Mondi Group leverages its integrated pulp-to-paper footprint to secure long-term supply contracts with European converters. Stora Enso anchors its competitive position through proprietary lightweight fiber formulations that reduce basis weight without sacrificing print fidelity. Bolloré Thin Papers specializes in ultra-thin Bible and dictionary grades where few competitors sustain comparable caliper consistency.
Thin papers are engineered substrates manufactured below 40 grams per square meter, typically produced via extended nip pressing or hybrid forming to achieve uniform density at minimal caliper for high-volume printing and precision packaging. The uncoated paper segment dominates volume flows into religious text and legal document applications where opacity and fold endurance matter more than surface gloss. Specialty paper is reshaping margin pools as pharmaceutical serialization and anti-counterfeit packaging demand customized security substrates with controlled porosity. Lightweight paper competes aggressively against synthetic alternatives in food wrapper segments where EU Single-Use Plastics Directive compliance pressures brand owners toward fiber-based solutions.
FDA substrate contact regulations for pharmaceutical packaging, REACH restrictions on chemical additives in coated grades, and FSC chain-of-custody certification requirements collectively determine market access thresholds for thin paper suppliers serving regulated end-uses. The EU Green Deal's packaging waste reduction targets are forcing reformulation of traditional coatings to maintain barrier properties without compromising repulpability. Stakeholders must monitor how evolving extended producer responsibility schemes in France, Germany, and Italy reshape cost allocation between paper mills and downstream converters.
Market Dynamics
EU Green Deal packaging waste reduction targets are forcing thin paper mills to reformulate barrier coatings without sacrificing repulpability, compressing R&D timelines and reallocating technical service resources toward converter co-development programs.
Growth Catalysts
- EU F-Gas Regulation:Phasing down fluorinated gases accelerates demand for fiber-based food wrappers with natural barrier properties, displacing synthetic laminates in German and French retail chains.
- Pharmaceutical serialization mandates:Track-and-trace requirements for anti-counterfeit packaging pull customized security substrates with controlled porosity into blister and sachet applications.
- Lightweighting:Hybrid forming and extended nip pressing technologies enable sub-35 gsm calipers without opacity loss, opening premium dictionary and religious text segments.
Market Restraints
- Pulp cost volatility:Hardwood fiber prices swing with Brazilian and Nordic supply disruptions, squeezing margin pools on uncoated Bible grades where pass-through clauses lag quarterly resets.
- REACH chemical restrictions:ECHA scrutiny of optical brighteners and sizing agents in coated grades forces costly reformulation cycles before market access.
- Polymer substitution threat:Biaxially oriented polypropylene maintains cost advantage in moisture-critical pharmaceutical pouches where fiber barriers still underperform.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO serialization deadlines and domestic API manufacturing expansion create first-mover advantage for FSC-certified thin paper suppliers establishing local slitting operations.
- Cellulose nanofiber barrier convergence:Combining microfibrillated cellulose with traditional furnish yields grease resistance without polyethylene lamination, unlocking EU Single-Use Plastics Directive compliance.
- Direct mill-to-brand procurement:Luxury cosmetics houses in Milan and Paris bypass converters for security substrate specification, capturing margin and technical control.
Industry Challenges
- FSC chain-of-custody certification timelines:Pharmaceutical and food contact buyers demand audited traceability, extending supplier qualification cycles by 12-18 months for mills lacking existing forest management credentials.
- Coating line reconfiguration:Water-based barrier systems require drying capacity upgrades incompatible with legacy solvent-coating infrastructure, stranding mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thin Papers Market |
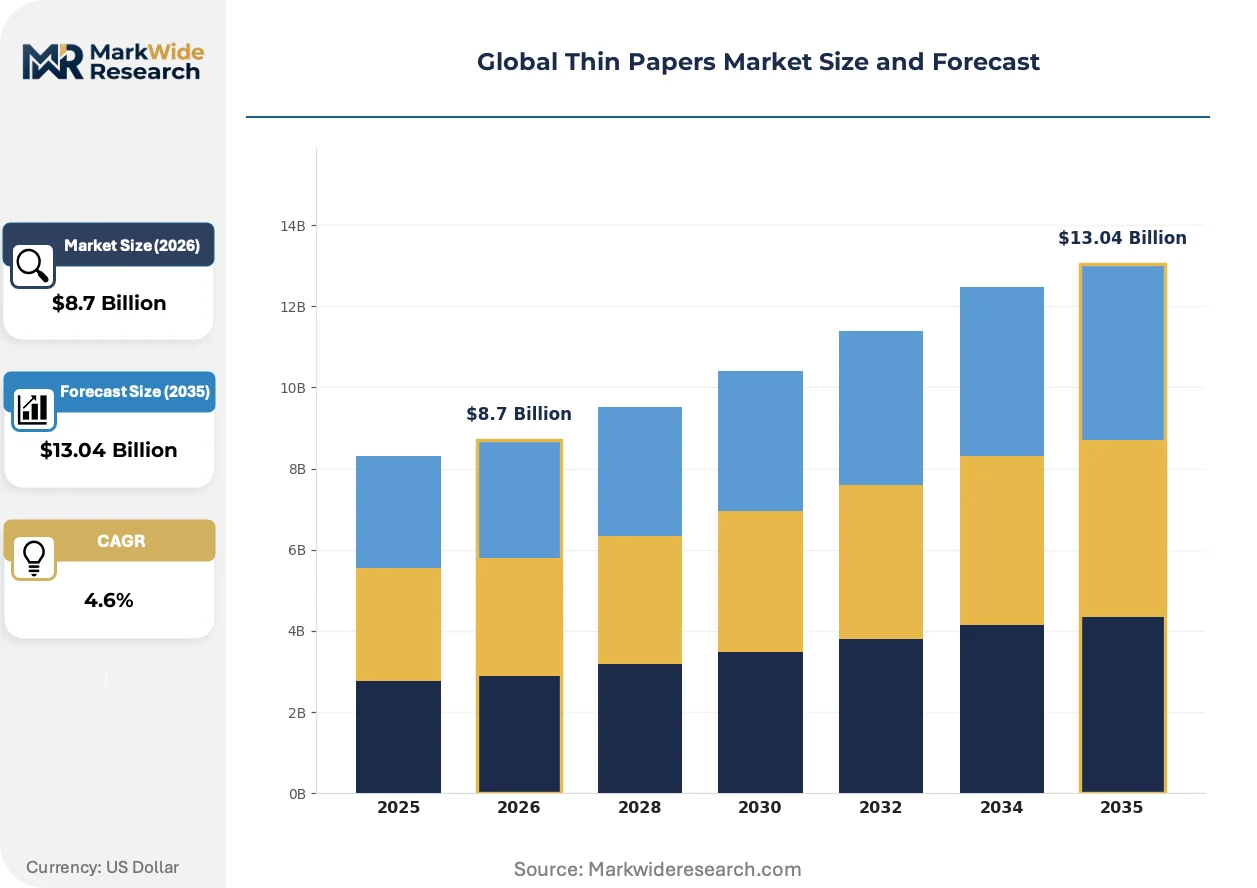
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight Paper, Coated Paper, Uncoated Paper, Specialty Paper Application: Packaging, Printing, Stationery, Industrial Use End User: Consumer Goods, Publishing, Manufacturing, Arts & Crafts Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Mondi Group, International Paper, Stora Enso, Ahlstrom-Munksjö, Nippon Paper Industries, Sappi Limited, WestRock Company, Bolloré Thin Papers, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thin Papers Market Strategic Shifts
Thin paper manufacturing is pivoting from commodity volume toward engineered substrate solutions where barrier functionality and print fidelity must coexist with circular economy compliance.
Cellulose nanofiber reinforcement is rendering obsolete conventional polyethylene-laminated grease barriers in fast-food wrapper applications. Quick-service chains in Germany and the Netherlands are piloting these substrates at scale. The technology is rendering obsolete legacy coating lines dependent on fossil-derived polymers.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical treatments from food-contact papers by 2025. Mills serving French and Italian converter networks are accelerating bio-based sizing agent trials. Pharmaceutical blister packaging faces the steepest compliance curve as EFSA tightens migration limits.
Specification authority is migrating upstream from converters to brand-owning pharmaceutical and luxury goods houses. Technical service teams at major mills now embed directly with Bayer, L'Oréal, and comparable entities during substrate development. This pattern concentrates most visibly in the Rhine-Ruhr corridor where pharmaceutical packaging clusters co-locate with paper industry R&D facilities.
Global Thin Papers Market Segmentation
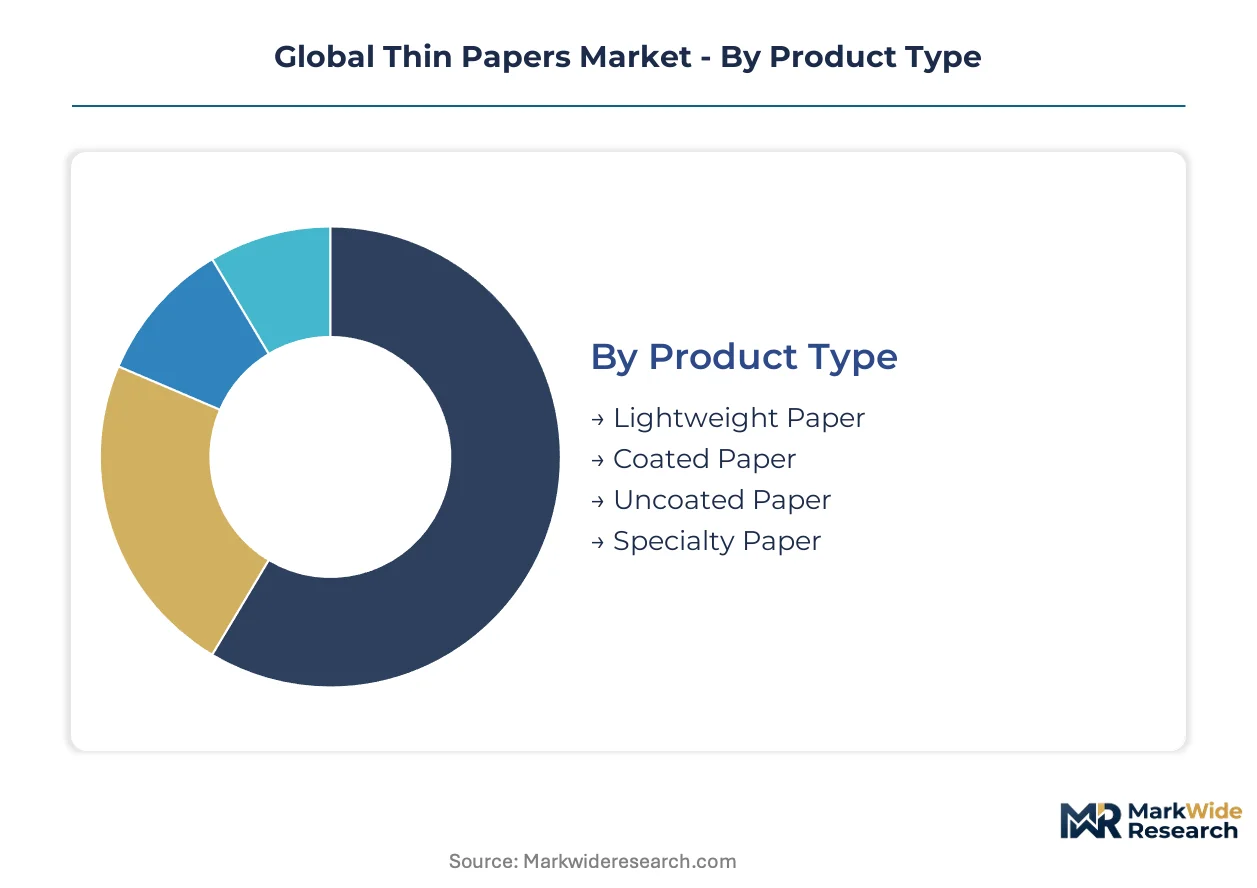
Thin paper specifications diverge sharply across end-use requirements, with pharmaceutical serialization and EU packaging regulations fragmenting demand into highly specialized substrate categories. Segmentation discipline separates commodity volume plays from engineered solutions commanding technical service premiums.
Product Type:
Mature furnish technologies dominate established segments while nanofiber barrier innovations reshape emerging grades.
- Uncoated Paper:Bible and legal document substrates rely on extended nip pressing to achieve sub-40 gsm calipers with fold endurance exceeding 5,000 double folds. Religious text publishers in Germany and the Netherlands specify these grades for compact editions where opacity trumps surface finish.
- Specialty Paper:Pharmaceutical blister and sachet applications demand controlled porosity substrates with anti-counterfeit serialization compatibility. EU F-Gas Regulation compliance is pulling customized security papers into track-and-trace packaging for German and French drug manufacturers.
- Lightweight Paper:Hybrid forming enables sub-35 gsm food wrappers displacing synthetic laminates in retail chains.
- Coated Paper:Surface sizing with bio-based agents responds to REACH restrictions on optical brighteners.
Uncoated paper retains volume leadership; specialty paper holds the steepest expansion curve.
Application:
Regulatory pressure on packaging waste streams is accelerating fiber substitution across food service and pharmaceutical end-uses.
- Packaging:Cellulose nanofiber grease barriers are displacing polyethylene-laminated fast-food wrappers in German and Dutch quick-service chains. EU Single-Use Plastics Directive compliance deadlines are forcing reformulation of traditional barrier coatings without sacrificing repulpability.
- Printing:Dictionary and religious text publishers in the Rhine-Ruhr corridor specify ultra-thin grades where caliper consistency below 0.04 mm enables compact binding.
- Stationery:Premium letterhead applications in Milan and Paris luxury houses favor lightweight cotton fiber blends.
- Industrial Use:Interleaving and separation papers for precision metal stamping require lint-free surfaces.
Packaging commands the fastest share gain; printing maintains the deepest specification heritage.
End User:
Direct procurement patterns concentrate authority upstream from converters toward brand-owning entities with substrate certification requirements.
- Publishing:Religious and legal document houses in Germany anchor demand for high-opacity Bible grades with FSC chain-of-custody documentation.
- Consumer Goods:Food contact applications face EFSA migration limit tightening on barrier coatings.
- Manufacturing:Pharmaceutical serialization mandates from EMA are pulling technical service resources toward blister packaging development.
- Arts & Crafts:Specialty lightweight sheets for conservation framing and archival storage occupy niche specification tiers.
Publishing sustains the most stable demand base; manufacturing presents the most volatile compliance curve.
Distribution Channel:
Technical service intensity determines channel selection, with engineered substrates bypassing traditional converter networks.
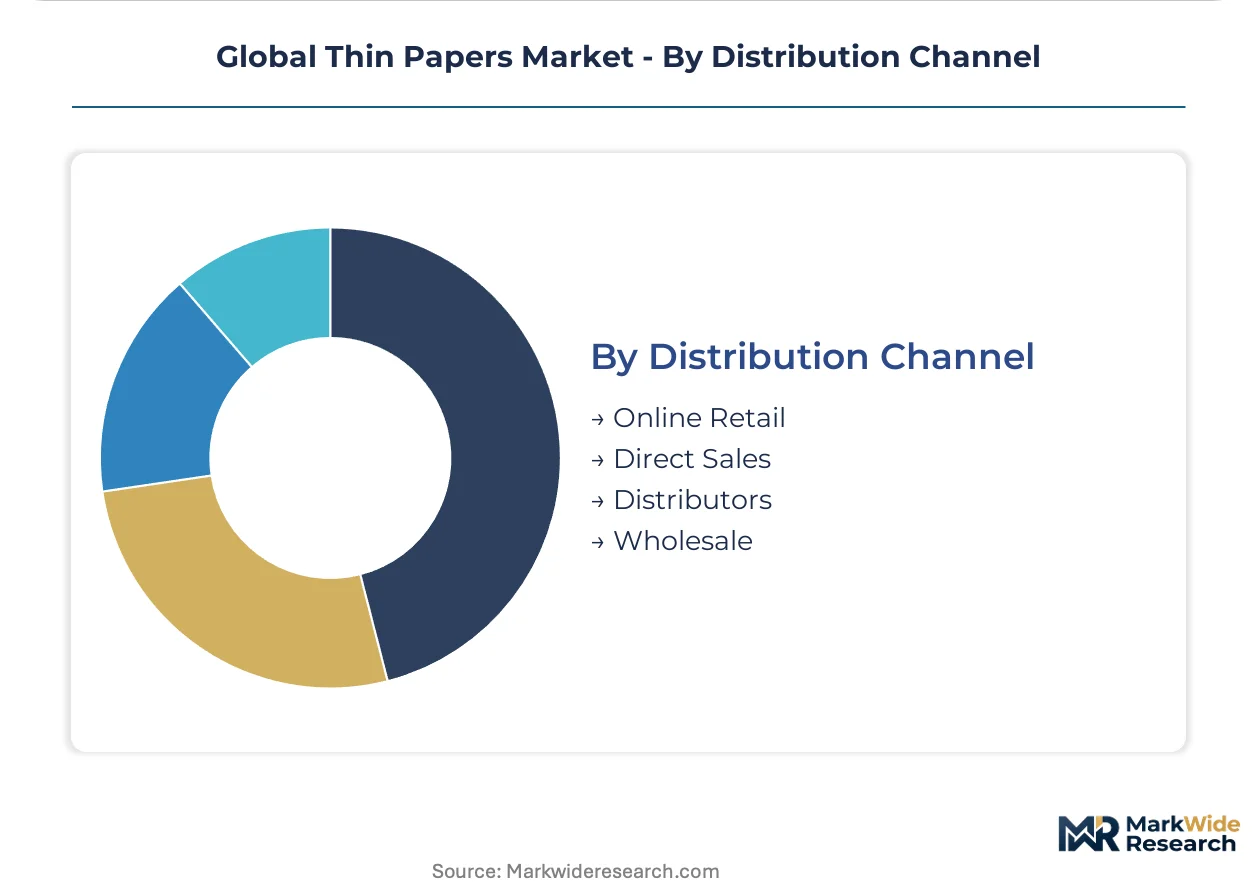
- Direct Sales:Bayer, L'Oréal, and comparable brand houses in the Rhine-Ruhr corridor specify security substrates through embedded mill technical teams. This pattern captures margin and accelerates development cycles for pharmaceutical serialization grades.
- Distributors:Converter networks in France and Italy rely on stocked Bible and dictionary grades where specification standardization permits inventory holding.
- Online Retail:Arts and crafts segments source specialty lightweight sheets through digital procurement platforms.
- Wholesale:Volume uncoated grades for legal document applications flow through traditional paper merchant channels.
Direct sales expand most quickly in value terms; distributors retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command premium pricing for pharmaceutical-grade thin papers while Indian buyers negotiate on commodity Bible grades, creating a two-tier value architecture across regional demand pools.
Germany
Pharmaceutical blister packaging clusters in the Rhine-Ruhr corridor and premium printing houses in Baden-Württemberg drive high-specification consumption. EU F-Gas Regulation compliance deadlines force reformulation of barrier coatings without sacrificing repulpability. Düsseldorf-based converters co-develop security substrates directly with mill technical teams, bypassing traditional distribution channels.
United States
FDA substrate contact regulations for pharmaceutical packaging and serialization mandates pull customized security papers into blister applications. Extended producer responsibility schemes in California and New York reshape cost allocation between mills and converters. Chicago-area legal document publishers anchor demand for high-opacity uncoated grades with FSC chain-of-custody documentation.
India
CDSCO serialization deadlines and domestic API manufacturing expansion create demand for FSC-certified thin papers in pharmaceutical packaging. BIS standards for food contact materials pressure reformulation of traditional coatings. Maharashtra-based converters are establishing local slitting operations to capture first-mover advantage in track-and-trace substrate supply.
France
Luxury cosmetics houses in Paris and Milan bypass converters for security substrate specification, concentrating procurement authority upstream. EFSA migration limit tightening on barrier coatings accelerates bio-based sizing agent trials. Lyon-area quick-service chains pilot cellulose nanofiber grease barriers to meet EU Single-Use Plastics Directive compliance.
Japan
PMDA serialization requirements and precision printing traditions sustain demand for ultra-thin dictionary grades with caliper consistency below 0.04 mm. METI carbon neutrality targets push mills toward lightweight fiber formulations. Osaka-Kobe industrial corridor hosts specialized coating line upgrades for water-based barrier systems incompatible with legacy solvent infrastructure.
Global Thin Papers Market Competitive Environment
Integrated pulp-to-paper conglomerates and specialized lightweight substrate producers split the market along capability-intensity lines. The vendor base concentrates around three strategic archetypes: backward-integrated forestry owners controlling fiber supply, technology-focused specialists in sub-35 gsm calipers, and diversified packaging conglomerates leveraging converter relationships. Competitive moves center on capacity reconfiguration for water-based coating lines and embedded technical service teams at pharmaceutical packaging clusters.
Within the integrated forestry tier, Mondi Group and Stora Enso exemplify archetypes securing long-term supply contracts through captive pulp supply. Bolloré Thin Papers occupies a specialist position where caliper consistency in ultra-thin Bible and dictionary grades differentiates technical capability. These three anchors demonstrate how geographic proximity to Rhine-Ruhr pharmaceutical clusters and Nordic fiber sourcing converge in competitive positioning.
| Leading Market Players |
|---|
| Mondi Group |
| International Paper |
| Stora Enso |
| Ahlstrom-Munksjö |
| Nippon Paper Industries |
| Sappi Limited |
| WestRock Company |
| Bolloré Thin Papers |
| Smurfit Kappa |
| Others |
Value Chain & Pricing Dynamics
Pulp cost volatility from Brazilian and Nordic supply disruptions determines both the customization-premium spread between pharmaceutical security substrates and commodity Bible grades, and the geographic clustering of coating line investments around Rhine-Ruhr pharmaceutical hubs.
Pricing Analysis
The customization-premium spread separates pharmaceutical security substrates with controlled porosity from standard uncoated Bible grades. Three-tier pricing structure across premium, standard, and economy levels reflects FSC chain-of-custody certification status and caliper consistency below 0.04 mm. Price differentiation hinges on technical service embedding and serialization compatibility. Cost compression in commodity uncoated tiers intensifies because hardwood fiber pass-through clauses lag quarterly resets. Pharmaceutical buyers show least price sensitivity; religious text publishers negotiate most aggressively on volume contracts.
Supply Chain Analysis
Tariff exposure between Brazil and Germany dominates raw material cost planning for European thin paper mills. Supply concentrates in Nordic countries for softwood fiber, Brazil for hardwood pulp, and Germany for pharmaceutical-grade coating and finishing. The chain draws from extended nip pressing equipment suppliers in Japan, microfibrillated cellulose precursor mills in Finland, and optical brightener compounders facing REACH restrictions. Single-source vulnerability sits with Brazilian hardwood pulp contracts. Distribution runs through converter networks in France and Italy for standard grades, while direct mill technical teams serve Rhine-Ruhr pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical capability in sub-35 gsm caliper consistency with barrier functionality is scarce and concentrates competitive advantage among mills with hybrid forming expertise and pharmaceutical certification track records.
For Market Incumbents: Pre-empt polymer substitution in moisture-critical pharmaceutical pouches by accelerating cellulose nanofiber barrier convergence before biaxially oriented polypropylene cost advantages widen. Secure backward integration into microfibrillated cellulose supply through offtake agreements with Nordic precursor mills. Anchor converter relationships via embedded technical service teams at Bayer and L'Oréal specification committees. For New Entrants and Emerging Players: Build out local slitting operations in Maharashtra to capture first-mover advantage from CDSCO serialization deadlines and domestic API manufacturing expansion. Target India's pharmaceutical packaging segment where FSC-certified substrate supply remains underdeveloped. Enter through technical partnership with established European mills lacking Indian distribution infrastructure. For Investors and Strategic Acquirers: The market sits at a reformulation-intensive phase that favors mills with water-based coating line capacity and existing pharmaceutical serialization relationships. Long-term viability favors specialists with sub-35 gsm caliper consistency expertise over commodity volume players facing pulp cost volatility. Watch for EFSA migration limit tightening on barrier coatings as inflection signal for bio-based sizing agent adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Cellulose Nanofiber Barrier Convergence | Combining microfibrillated cellulose with traditional furnish unlocks EU Single-Use Plastics Directive compliance for quick-service chains. |
| Direct Mill-to-Brand Procurement | Embedded technical teams at Bayer and L'Oréal capture margin and accelerate development cycles for serialization grades. |
| Water-Based Coating Line Reconfiguration | Drying capacity upgrades replace legacy solvent infrastructure to meet REACH restrictions on per- and polyfluoroalkyl substances. |
| FSC Chain-of-Custody Certification Investment | Audited traceability extends supplier qualification cycles but secures access to pharmaceutical and food contact buyers. |
| Local Slitting Operations in India | Maharashtra-based facilities capture first-mover advantage from CDSCO serialization deadlines and API manufacturing expansion. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EU F-Gas Regulation implementation documents, ECHA REACH restriction filings, and FSC chain-of-custody audit records. Primary interviews engaged technical directors at thin paper mills, procurement leads at pharmaceutical packaging converters, regulatory affairs specialists at EMA and CDSCO, and sustainability officers at quick-service retail chains. Secondary validation drew from customs trade data for pulp and paper flows, SEC filings of integrated forestry conglomerates, and extended producer responsibility scheme disclosures in France, Germany, and Italy. Bottom-up volume modeling triangulates against top-down value estimates across the analysis window.
Forecast inputs include segmented demand trajectories by product type, application, and end user, with cross-validation against regulatory compliance timelines. The analytical framework models uncoated paper, specialty paper, lightweight paper, and coated paper segments across packaging, printing, stationery, and industrial use applications. End-user splits capture publishing, consumer goods, manufacturing, and arts and crafts demand patterns. CAGRs derive from regression analysis of historical volume-price relationships, adjusted for pulp cost volatility and coating reformulation capex cycles. EU Green Deal packaging waste reduction targets and FDA substrate contact regulations serve as scenario anchors.
Stress conditions across hardwood fiber price swings, REACH chemical restriction enforcement intensity, and pharmaceutical serialization mandate delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about coating line reconfiguration timelines and FSC certification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Global Paper Chemical Market
Paper Products
North America Thermal Paper Market
Paper Products
Liquid Paperboard Market
Paper Products
Paper and Board Technologies Market
Paper Products
Specialty Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
Paper Making Machine Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
GCC Stone Paper Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Plywood Market
Paper Products
Metallized Paper Market
Paper Products
NCR Laser Paper Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Heat Transfer Paper Market
Paper Products
Paper Based Laminates Market