
 Europe Coated Paper Market | 2026-2036
Europe Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coated Paper Market Foresight
Modular packaging configurations is shifting buyer preference toward customizable coated paper solutions that combine protective and aesthetic functions in single substrates. Metsä Group leverages integrated pulp-to-paper operations to control raw material quality across Nordic mills. Stora Enso anchors its position through biobased coating innovations that reduce petrochemical dependency. UPM-Kymmene Corporation dominates Central European distribution channels for magazine and catalog grades.
Europe coated paper consists of base paper substrates treated with mineral or synthetic coatings to achieve controlled surface smoothness, brightness, and ink receptivity, typically measured by ISO brightness values exceeding 88% and gloss levels ranging from matte at 15-30 GU to high-gloss art papers above 70 GU. The coating layer, applied through blade or air-knife processes, enables sharp halftone reproduction for commercial printing and premium packaging. Glossy paper and art paper command the highest margin pools in publishing and advertising segments where visual impact determines substrate selection. Matte paper sustains steady demand in corporate communications and soft-touch packaging where tactile differentiation matters more than reflectivity. Clay coated grades retain volume leadership in magazine production despite polymer coated alternatives gaining share in moisture-resistant packaging applications.
The EU Green Deal and REACH frameworks mandate reduction of volatile organic compounds in coating formulations, while F-Gas Regulation restricts fluorinated compounds used in specialty barrier coatings. ECHA substance evaluations are accelerating reformulation timelines for clay and polymer coating chemistries across German, Finnish, and Italian mill networks. Stakeholders must monitor pending Packaging and Packaging Waste Regulation revisions that will recalibrate recyclability requirements for coated substrates entering circular economy streams.
Market Dynamics
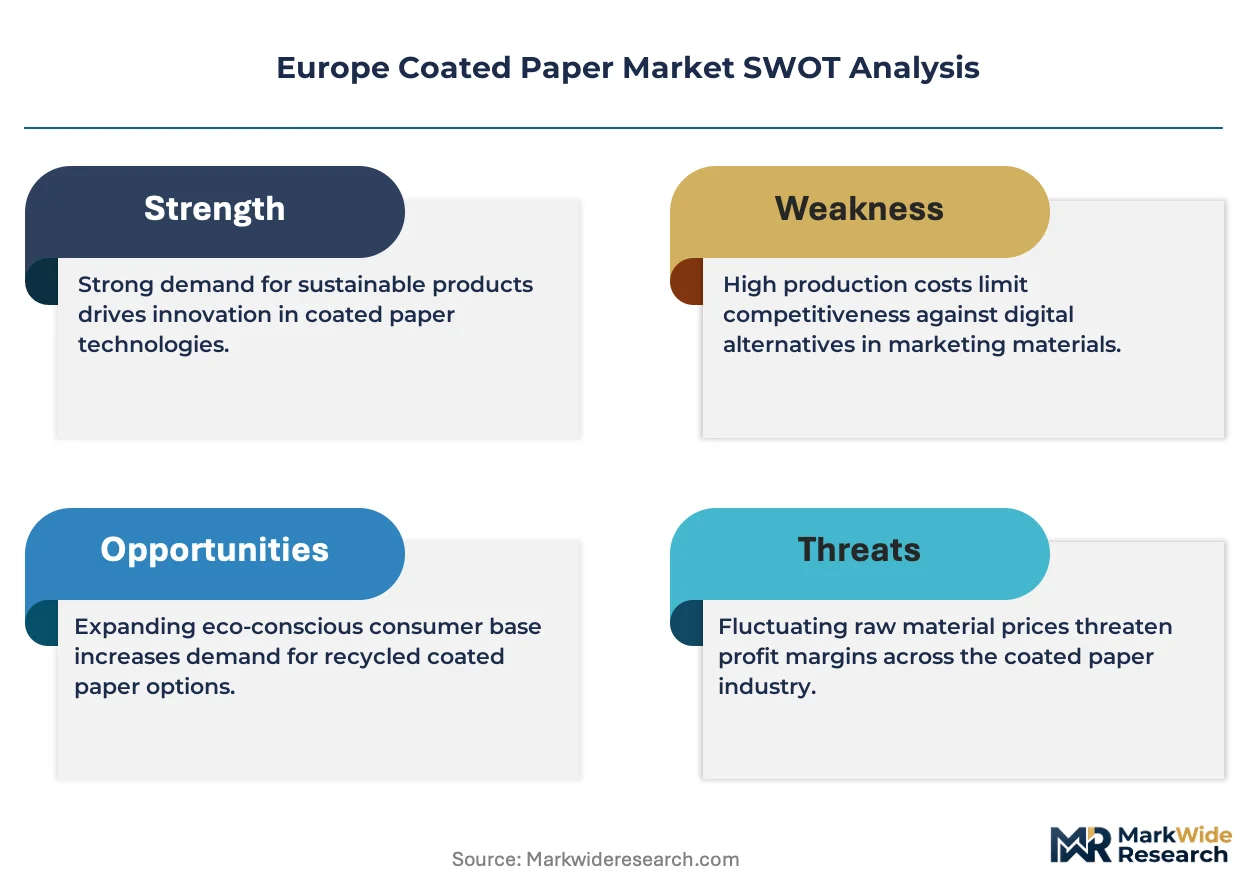
The EU Green Deal and REACH frameworks are forcing accelerated reformulation of coating chemistries across German, Finnish, and Italian mill networks, compressing timelines for compliant substrate development.
Growth Catalysts
- Premium packaging demand:Cosmetics and luxury goods manufacturers in France and Italy are expanding adoption of high-gloss art papers for tactile differentiation.
- F-Gas Regulation:Restrictions on fluorinated barrier compounds are accelerating investment in biobased coating alternatives across Nordic integrated pulp-to-paper operations.
- Magazine grade stability:Central European catalog and publishing segments sustain volume pull for clay coated substrates despite digital substitution pressures.
Market Restraints
- Coating chemical input volatility:Kaolin clay and calcium carbonate supply concentration in select quarries creates margin pressure for art paper producers.
- Recyclability friction:Pending Packaging and Packaging Waste Regulation revisions threaten circular economy eligibility for polymer coated grades.
- Digital substitution:Corporate communications and direct mail volumes face structural displacement from electronic distribution channels.
Strategic Opportunities
- Eastern European underpenetration:Poland and Czech Republic packaging converters represent expansion targets for matte paper in soft-touch applications.
- Biobased coating convergence:Starch-latex hybrid formulations combined with blade coating automation enable petrochemical reduction without gloss sacrifice.
- CSRD disclosure mandates:Corporate sustainability reporting requirements are creating certified substrate premiums for coated paper with verified carbon footprints.
Industry Challenges
- Coating formulation talent scarcity:ECHA substance evaluation expertise sits concentrated among retiring chemists at German and Finnish research centers.
- ISO brightness certification timelines:Third-party validation for 88%+ brightness claims extends product launch windows by 6-12 months.
- Legacy blade-to-air-knife retrofit complexity:Capital equipment transitions disrupt production schedules at mid-capacity Italian mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coated Paper Market |
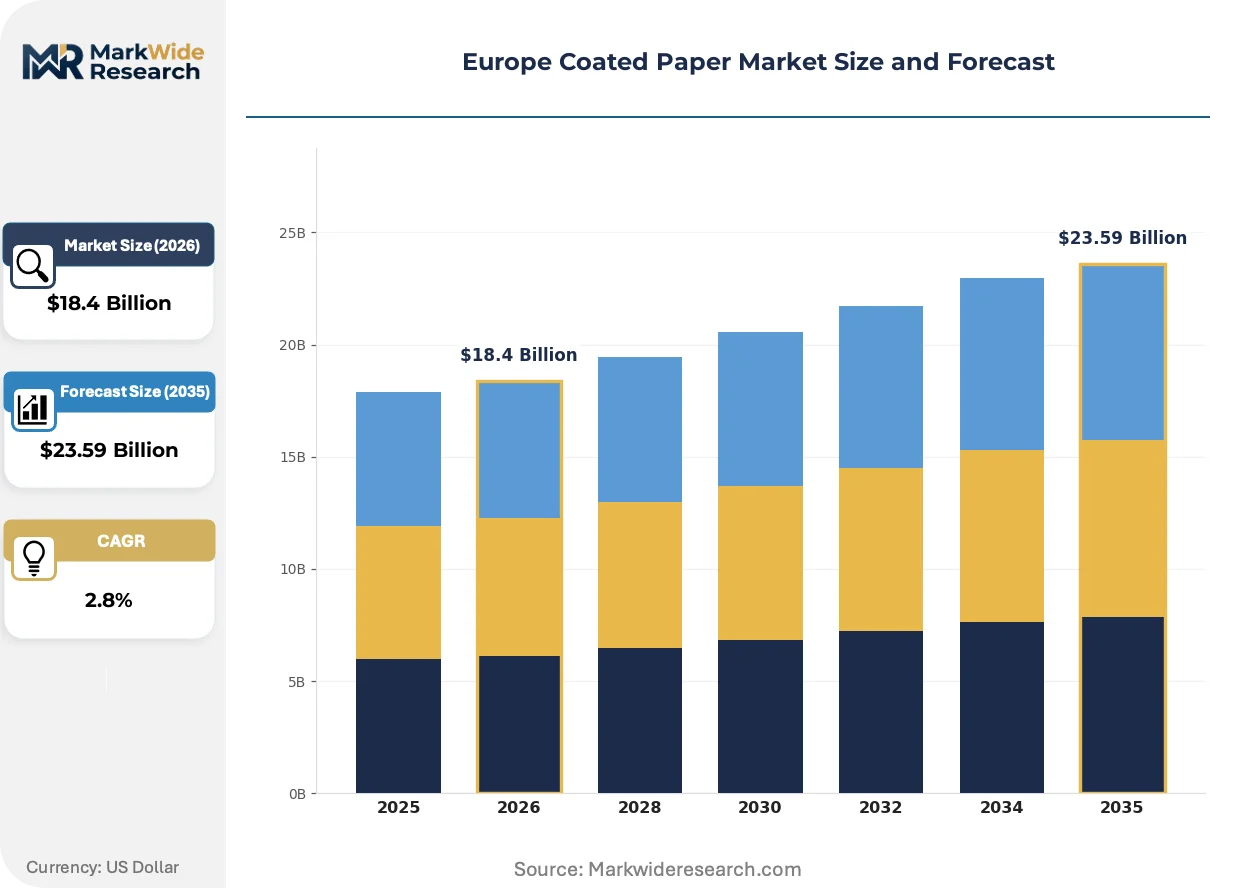
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $23.59 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Art Paper, Glossy Paper, Matte Paper, Silk Paper End Use Industry: Publishing, Packaging, Printing, Advertising Coating Type: Satin Coated, Clay Coated, Polymer Coated, Uncoated Weight: Lightweight, Medium Weight, Heavyweight, Specialty Weight |
| Companies Covered | Metsä Group, Sappi, Stora Enso, Burgo Group, Lecta Group, UPM-Kymmene Corporation, Smurfit Westrock, Koehler Holding, Mondi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coated Paper Market Shifts & Advancements
Coating process digitization and substrate functionalization are compressing development cycles while regulatory chemistry constraints force material science breakthroughs.
Blade coating automation systems equipped with real-time thickness sensors are automating quality control across Nordic mills. Magazine and catalog printers in Germany are adopting these lines to reduce halftone variation. The technology is automating labor-intensive inspection roles while tightening gloss tolerance bands.
REACH substance evaluations and ECHA restriction proposals are accelerating clay coating reformulation timelines. Finnish integrated producers face compressed windows to validate alternative mineral fillers. Art paper grades bound for French luxury packaging are most affected, with mills substituting precipitated calcium carbonate for select kaolin applications.
Brand owners are consolidating coated paper suppliers to reduce certification burden. Central European cosmetics houses now demand single-source accountability for carbon footprint and recyclability claims. This concentration is visible in German premium packaging procurement, where three-tier qualification separates approved from provisional vendors.
Europe Coated Paper Market Segmentation
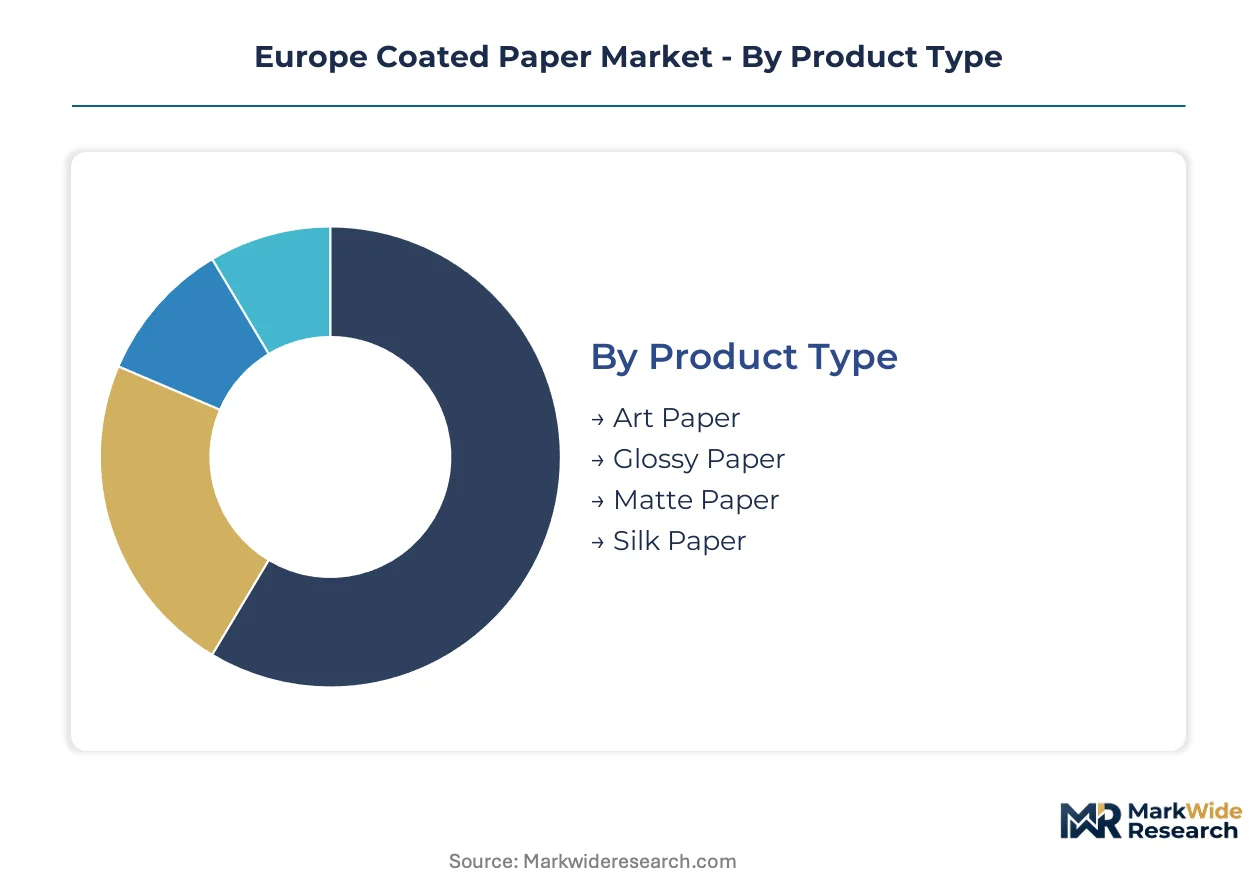
Coated paper demand in Europe fragments across surface finish preferences, end-use durability requirements, and regulatory compliance tiers. Each segmentation axis reveals distinct margin structures and customer concentration patterns that shape mill investment priorities.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity gloss grades to bespoke art paper specifications requiring mill-specific calibration.
- Art Paper:High-brightness substrates with multi-layer mineral coatings achieve ISO values above 90% and gloss levels exceeding 70 GU. French and Italian luxury packaging houses specify these grades for cosmetics primary packaging where visual impact commands premium pricing.
- Glossy Paper:Single or double-coated sheets deliver 45-65 GU reflectivity through blade-applied calcium carbonate formulations. German magazine printers sustain volume demand despite digital headwinds in catalog distribution.
- Matte Paper:Low-sheen finishes at 15-30 GU serve corporate communications and soft-touch packaging segments. Nordic mills are expanding capacity for these grades as tactile differentiation gains priority over reflectivity.
- Silk Paper:Intermediate gloss positioning combines smooth hand-feel with moderate light reflection. Stationery and high-end brochure applications in Benelux markets favor this balance.
Most installed capacity flows through Glossy Paper. Expansion is steepest in Art Paper.
End Use Industry:
Application-driven specification intensity separates price-sensitive commodity buyers from performance-validated premium purchasers.
- Publishing:Magazine and book segments require consistent halftone reproduction across long print runs. Clay coated grades dominate this segment, though volume pressure from electronic media is compressing run lengths.
- Packaging:Folding carton and luxury box applications demand moisture resistance and structural rigidity. REACH-compliant barrier coatings are becoming mandatory for food-contact approvals.
- Printing:Commercial sheetfed and web offset operations prioritize ink holdout and dimensional stability. Central European trade shops specify coated stocks by brightness tier rather than brand.
- Advertising:Direct mail and point-of-sale display segments face structural displacement from digital channels. Remaining volume concentrates in dimensional mailers requiring substrate stiffness.
Revenue concentration sits heaviest in Packaging. Volume erosion is most pronounced in Advertising.
Coating Type:
Formulation chemistry determines recyclability eligibility and regulatory compliance burden across EU member state implementations.
- Satin Coated:Intermediate sheen formulations balance aesthetic appeal with fingerprint resistance. German publishing houses specify these grades for annual reports requiring professional presentation without high-gloss ostentation.
- Clay Coated:Kaolin-based barrier layers provide cost-effective printability for magazine and catalog segments. ECHA substance evaluations are accelerating precipitated calcium carbonate substitution timelines.
- Polymer Coated:Synthetic barrier compounds deliver moisture and grease resistance for food packaging. Pending Packaging and Packaging Waste Regulation revisions threaten circular economy eligibility for these grades.
- Uncoated:Base paper substrates without surface treatment serve price-sensitive applications where print quality requirements are modest. Environmental claims advantage is offset by functional limitations.
Production volume leadership remains with Clay Coated. Regulatory pressure is intensifying fastest against Polymer Coated.
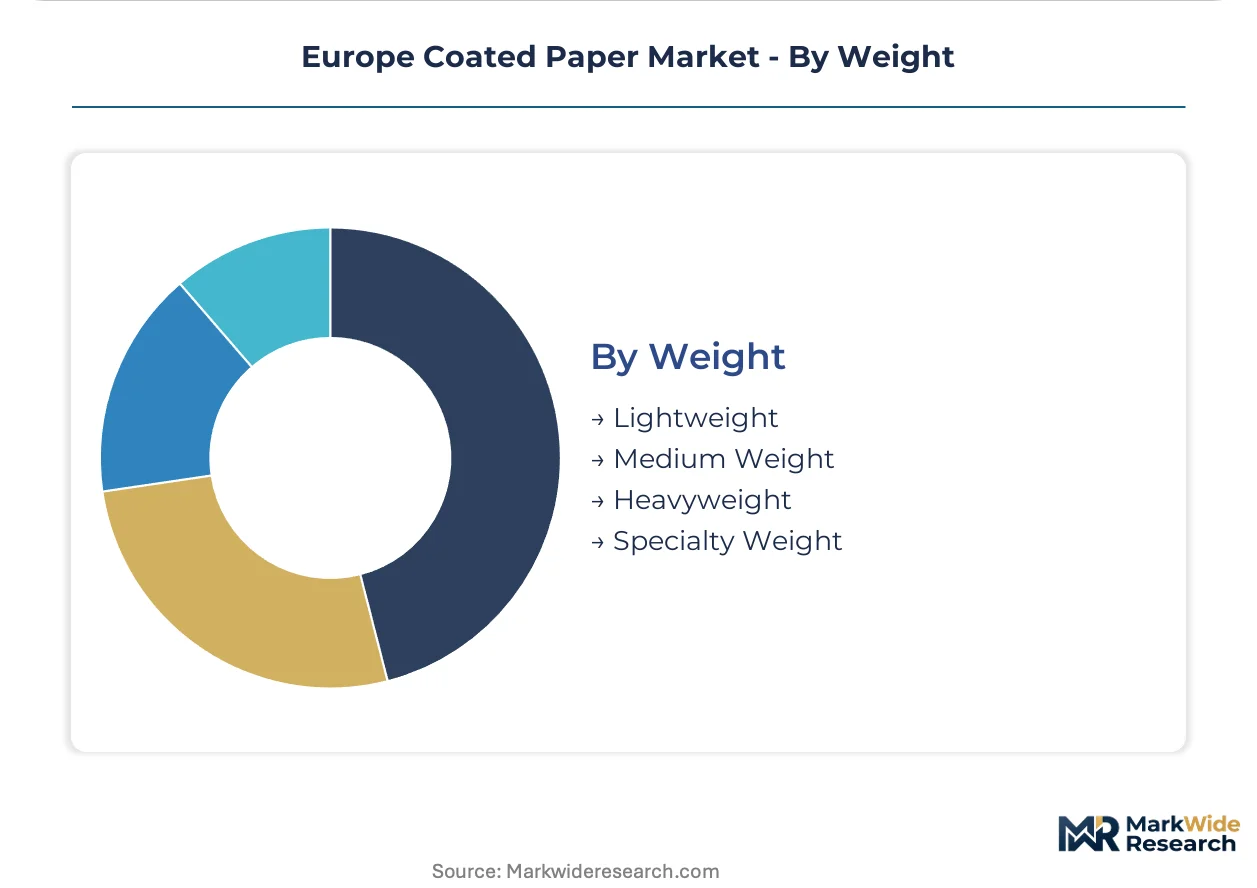
Weight:
Basis weight selection correlates with end-use structural requirements and postal optimization constraints.
- Lightweight:Sub-70 gsm substrates reduce postal costs for high-volume direct mail campaigns. Nordic mills optimize these grades for inkjet compatibility as transactional printing shifts to digital.
- Medium Weight:70-150 gsm range captures magazine and commercial printing volume. Finnish integrated producers achieve cost leadership through pulp-to-paper optimization at this tier.
- Heavyweight:150-300 gsm boards serve folding carton and premium packaging applications. Italian converters specify these grades for cosmetics secondary packaging requiring rigidity.
- Specialty Weight:Custom caliper specifications outside standard ranges address dimensional stability requirements for luxury box and display applications. Mill qualification timelines extend 6-12 months for these grades.
Capacity utilization peaks in Medium Weight. Specification complexity is highest in Specialty Weight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coated paper production in Europe traces its industrial lineage to 19th-century German and Finnish pulp-to-paper integration, with modern capacity clustering along Nordic timber belts and Alpine limestone quarries that supply coating minerals.
Germany
Magazine-grade glossy paper demand from Heidelberg and Munich printing clusters sustains medium-weight coated volumes despite catalog circulation declines. The EU Green Deal's REACH enforcement accelerates kaolin substitution timelines at Baden-Württemberg mills. Saxony-Anhalt coating facilities retrofit blade lines for calcium carbonate formulations to meet ECHA substance evaluation deadlines.
Finland
Integrated pulp-to-paper operations anchor art paper exports to French luxury packaging houses seeking ISO brightness above 90%. F-Gas Regulation restrictions on fluorinated barriers drive biobased coating R&D at Espoo research centers. Tampere mill networks automate blade coating with real-time thickness sensors to tighten gloss tolerance bands.
Italy
Cosmetics secondary packaging specifications from Milan and Florence converters pull heavyweight coated board for rigid box applications. Pending Packaging and Packaging Waste Regulation revisions threaten polymer-coated grade recyclability eligibility. Lucca paper district mills face compressed reformulation windows for clay-to-precipitated calcium carbonate transitions.
France
Luxury goods primary packaging demand in Paris and Lyon commands premium art paper pricing for tactile differentiation. CSRD disclosure mandates create certified substrate premiums for carbon-footprint-verified coated stocks. Grenoble coating chemistry specialists confront talent scarcity as ECHA expertise concentrates among retiring chemists.
Poland
Underpenetrated soft-touch packaging applications in Warsaw and Kraków converters represent matte paper expansion targets. The EU Green Deal emissions standards tighten coating process compliance requirements for new mill investments. Silesian industrial zones attract blade coating automation technology transfers from Nordic integrated producers.
Europe Coated Paper Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating formulation sophistication and certification burden management. The vendor base stratifies into three tiers: integrated pulp-to-paper Nordic groups with captive mineral supply, mid-cap Southern European specialists in luxury packaging grades, and commodity converters dependent on merchant pulp. Strategic moves concentrate on biobased coating R&D partnerships and blade-to-air-knife equipment transitions.
Among Nordic integrated producers, Metsä Group, Stora Enso, and UPM-Kymmene Corporation exemplify the premium-tier archetype through upstream pulp control and biobased coating innovation pipelines. These Finland-based entities occupy positions where ECHA regulatory proximity and research center concentration enable faster reformulation cycles than Southern European competitors. Their scale anchors Central European distribution channels while their coating chemistry capabilities represent the industry's response to REACH and F-Gas Regulation constraints.
| Leading Market Players |
|---|
| Metsä Group |
| Sappi |
| Stora Enso |
| Burgo Group |
| Lecta Group |
| UPM-Kymmene Corporation |
| Smurfit Westrock |
| Koehler Holding |
| Mondi |
| Others |
Supply & Pricing Matrix
EU Green Deal emissions mandates gate both qualified supply and premium-tier pricing access, as REACH-compliant coating chemistry certification separates approved vendors from provisional suppliers in German and Finnish mill networks. Mills without validated reformulation timelines face exclusion from French luxury packaging procurement, while certified producers command carbon-footprint premiums under CSRD disclosure requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates European coated paper transactions, with art paper grades bound for French cosmetics houses commanding substantial premiums over magazine-grade glossy volumes. Price differentiation hinges on ISO brightness certification tiers and verified carbon footprint documentation, with sustainability-attested stocks carrying measurable premiums. Cost compression in clay-coated magazine grades is intensifying because kaolin supply concentration limits formulation flexibility. Mid-weight catalog printers exhibit highest price sensitivity, while luxury packaging houses prioritize tactile performance over unit economics.
Supply Chain Analysis
Coating formulation chemist scarcity in German and Finnish research centers constrains mill network expansion timelines and reformulation velocity. Supply concentration rests in Finland, Germany, and Italy, with Nordic integrated producers anchoring art paper exports and Italian converters specializing in heavyweight rigid board. Raw material dependencies draw from kaolin quarries, calcium carbonate deposits, and biobased starch-latex formulations. Single-source vulnerability in specialty mineral fillers threatens consistent coating layer performance. Distribution runs through Central European printing clusters and cosmetics packaging converters with consolidated supplier qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European coated paper functions as a late-cycle quality story, with buyer consolidation toward premium art paper specifications for cosmetics primary packaging displacing commodity-grade volume chasing. Specification intensity now favors mills with integrated pulp control and certified coating chemistry pipelines.
For Market Incumbents: Anticipate REACH substance evaluation deadlines by accelerating precipitated calcium carbonate substitution trials before ECHA restrictions crystallize. Deepen backward integration into captive kaolin and calcium carbonate supply to buffer input volatility. Prioritize blade coating automation investments at Finnish and German facilities to tighten gloss tolerance bands and defend margin position against mid-cap Italian competitors. For New Entrants and Emerging Players: Polish and Czech soft-touch packaging converters represent the most penetrable buyer archetype, with matte paper specifications for corporate communications and tactile differentiation applications underserved by incumbent Nordic mills. Target biobased coating partnerships with regional starch suppliers to bypass petrochemical barrier chemistry qualification burdens. Pursue CSRD-certified substrate positioning to capture sustainability premium pools as corporate reporting mandates expand. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Italian specialists with heavyweight board capacity and cosmetics converter relationships but limited coating chemistry R&D depth. Long-term viability favors integrated pulp-to-paper groups with ECHA regulatory proximity and research center concentration. Watch F-Gas Regulation enforcement intensity as inflection indicator for biobased coating investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Coating R&D Partnership | Finnish research centers accelerate starch-latex hybrid validation ahead of fluorinated compound restrictions. |
| Blade-to-Air-Knife Equipment Transition | Italian mills automate quality control to meet French luxury packaging gloss tolerance requirements. |
| CSRD Certification Investment | German mills capture verified carbon footprint premiums from cosmetics houses consolidating suppliers. |
| Eastern European Distribution Expansion | Nordic producers transfer blade coating automation to Polish converters targeting soft-touch applications. |
| Mineral Filler Backward Integration | Finnish integrated groups secure captive calcium carbonate supply against kaolin quarry concentration risk. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mill operations directors, coating chemistry R&D leads, cosmetics packaging procurement managers, and Central European catalog printers with secondary validation. Trade data from Eurostat and Cefic industry reports, ECHA substance evaluation documentation, and EU regulatory filings anchored volume and pricing estimates. Bottom-up capacity assessments at named Finnish, German, and Italian mill networks triangulated against top-down end-use demand modeling.
Segment-weighting approaches distributed value and volume across surface finish tiers, coating chemistry types, and end-use application intensity. Product type segmentation modeled art paper, glossy paper, matte paper, and silk paper specifications with distinct margin structures. End-use dimensions captured publishing, packaging, printing, and advertising demand trajectories. Weight classifications addressed postal optimization and structural rigidity requirements. CAGRs derived from installed capacity utilization trends, substitution elasticity estimates, and regulatory compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; art paper and heavyweight board specifications carry tighter precision than commodity magazine grades dependent on volatile clay coating input costs. Forecasts reflect documented assumptions regarding REACH enforcement timelines, F-Gas Regulation implementation, and digital substitution velocity in corporate communications. Material deviation in EU Green Deal emissions standards or Packaging and Packaging Waste Regulation recyclability revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Hardwood Pulp Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Carbonless Paper Market
Paper Products
Thermal Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Global Paperboard Market
Paper Products
Sawn Wood Market
Paper Products
Global Kraft Paper Market
Paper Products
Plywood Market
Paper Products
Softwood Pulp Market
Paper Products
Tissue Paper Market
Paper Products
Wood-Based Panel Market
Paper Products
Middle-East and Africa Paper and Paperboard Market
Paper Products
Thin Printing Paper Market
Paper Products
Photographic Paper Market
Paper Products
Solar Paper Market