
 Plant Oil Based Printing Inks Market | 2026-2036
Plant Oil Based Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Oil Based Printing Inks Market Analytics
Modular ink formulation systems is rebalancing procurement patterns among mid-sized commercial printers who now mix base vehicles with additive packages rather than buying finished products. Sun Chemical leverages captive resin synthesis to control raw material quality across its flexo and gravure portfolios. Siegwerk Druckfarben anchors European supply through its Cologne technical center, where application laboratories customize linseed oil blends for folding carton converters. DIC Corporation competes in Asia-Pacific through integrated pigment manufacturing that reduces third-party dependency.
Plant oil based printing inks substitute alkyd and mineral oil vehicles with triglyceride esters from soy, linseed, or rapeseed feedstocks, achieving volatile organic compound reductions below 5% by weight while maintaining lithographic transfer efficiency above 85% on coated stocks. The offset inks segment dominates volume due to established newspaper and sheet-fed commercial infrastructure, though flexo inks exhibit the fastest structural expansion as corrugated and flexible packaging converters face retailer sustainability scorecards. Low VOC formulations command margin premiums in North American food contact applications where FDA compliance documentation adds qualification costs that smaller resin suppliers cannot absorb.
EPA VOC rules under 40 CFR 59 and REACH Annex XVII restrictions on aromatic solvent content are forcing reformulation investments across formulation houses serving regulated jurisdictions. FDA food contact notification requirements for plant oil carriers in indirect additives create documentation barriers that favor established players with regulatory affairs capacity. Stakeholders must monitor bio-based feedstock price spreads against petroleum alkyds, as crop yield volatility and renewable diesel competition for vegetable oil offtake reshape input cost structures faster than ink price adjustment mechanisms can respond.
Market Dynamics
Flexible food packaging converters across North America and Europe are accelerating reformulation timelines as REACH and EPA VOC emission limits tighten, forcing ink houses to rebuild vehicle chemistry around soy and linseed oil carriers rather than petroleum alkyds.
Growth Catalysts
- REACH Annex XVII aromatic solvent restrictions:European folding carton converters must eliminate mineral oil vehicles by 2025, creating immediate pull for linseed oil alkyd replacements.
- Retailer sustainability scorecards:Major grocery chains in Germany and France now mandate bio-based ink documentation for corrugated secondary packaging, embedding plant oil formulations into supplier qualification.
- Renewable diesel competition:Vegetable oil offtake pressure from fuel refiners is compressing feedstock costs for ink-grade triglycerides relative to petroleum intermediates.
Market Restraints
- Input cost volatility:Soybean and rapeseed oil prices swing with drought cycles in Argentina and Ukraine, outpacing ink price adjustment mechanisms.
- Supply concentration risk:Germany hosts the majority of EU alkyd resin capacity for lithographic applications, creating single-point vulnerability for continental formulation houses.
- Technical limitation:Plant oil oxidization rates lag petroleum vehicles on high-speed heatset web presses above 15,000 impressions per hour.
Strategic Opportunities
- Underpenetrated flexible packaging in India:BIS standards for food contact inks remain permissive on mineral oil content, positioning early movers before anticipated FSSAI alignment with EU norms.
- Water-based flexo convergence:Hybrid plant oil emulsion systems are opening corrugated board segments previously locked in solvent-based flexo.
- EU Green Deal procurement mandates:Public sector print contracts above EUR 200,000 now require bio-based content verification, institutionalizing demand for certified formulations.
Industry Challenges
- Formulation chemist scarcity:Expertise in triglyceride esterification and oxidative drying kinetics concentrates among retiring specialists at legacy German and Japanese ink houses.
- FDA food contact notification timelines:New plant oil carriers require 12-18 month pre-market clearance for indirect food additives, freezing product pipelines for mid-tier suppliers without regulatory affairs capacity.
- Legacy press compatibility:Converters running 1990s-era Heidelberg and Komori sheet-fed equipment face fountain solution recalibration costs that erode margin on low-volume sustainable ink contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Oil Based Printing Inks Market |
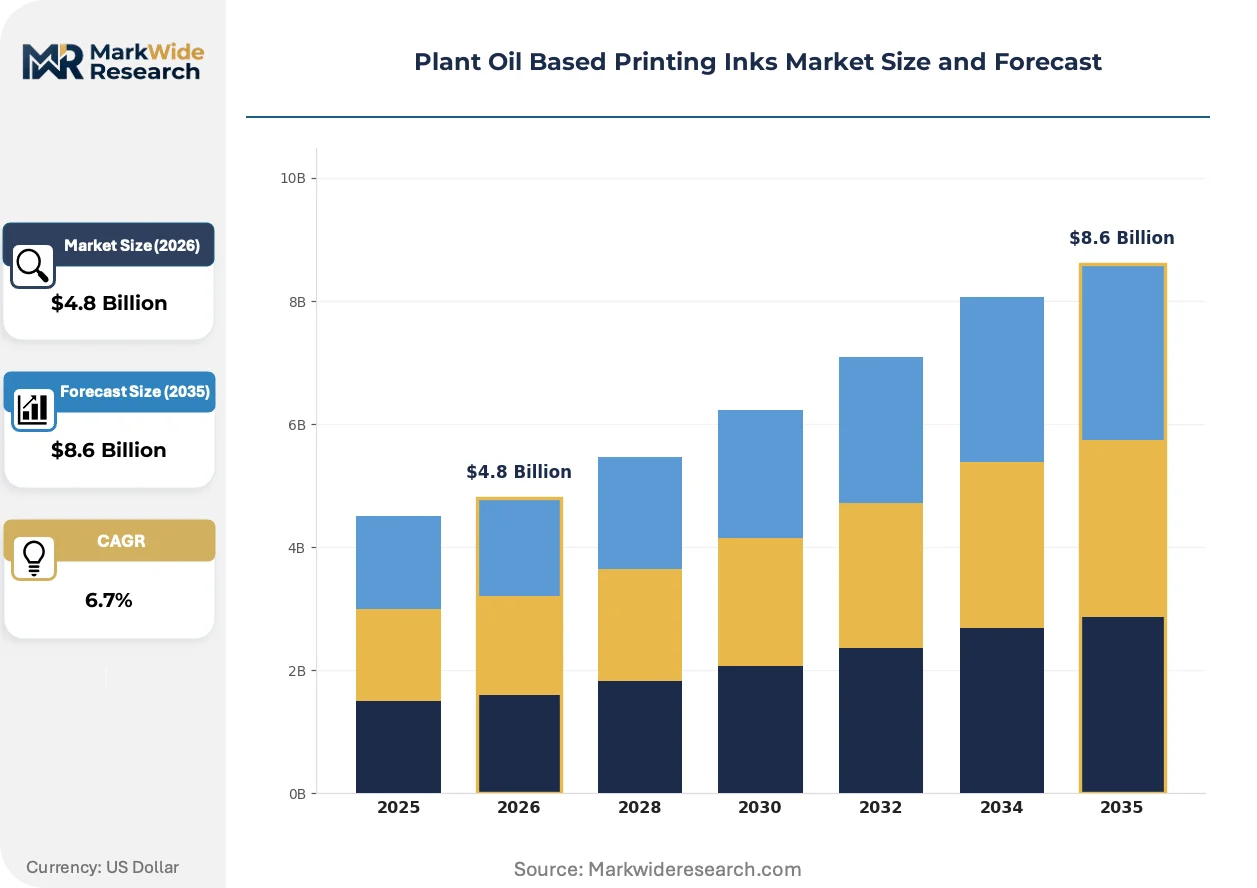
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexo Inks, Gravure Inks, Offset Inks, Digital Inks End User: Packaging Industry, Publishing Houses, Textile Industry, Commercial Printing Feature: Low VOC, Bio-Based, Fast Drying, High Pigment Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Sun Chemical, Siegwerk Druckfarben, INX International Ink Co., Flint Group, Nazdar Ink Technologies, Toyocolor Co. Ltd, DIC Corporation, Sakata INX, Wikoff Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Oil Based Printing Inks Market Evolving Landscape
Modular formulation architectures are fragmenting procurement patterns as mid-sized commercial printers abandon finished ink SKUs for base vehicle and additive packages mixed on-press.
Water-based flexo emulsions incorporating modified soy oil alkyd vehicles are absorbing volume from solvent-based nitrocellulose systems in corrugated post-print applications. Folding carton converters in the Netherlands and Belgium are adopting these hybrids fastest, driven by retailer packaging scorecards that penalize aromatic solvent content. The technology is absorbing market share previously held by UV-cured alternatives where energy costs and mercury lamp disposal burdens weigh against capital-constrained operations.
EPA 40 CFR 59 Subpart E tightened VOC content limits for publication rotogravure to 25% by weight, forcing US newspaper printers to reformulate heatset web inks around linseed oil vehicles. The rule compresses compliance timelines to 18 months for facilities above 100 tons annual solvent consumption. Mid-Atlantic commercial printing clusters are responding by consolidating purchasing through distributors with technical service capacity for fountain solution rebalancing.
Buyers are unbundling after-sales technical service from ink supply contracts, treating color management and press optimization as separate procurement categories. Commercial printers in France and Italy now engage independent color consultants rather than relying on supplier field technicians. This shift is most visible among mid-sized sheet-fed operations running 5-8 presses where in-house technical staff coverage gaps create demand for third-party expertise.
Plant Oil Based Printing Inks Market Segmentation
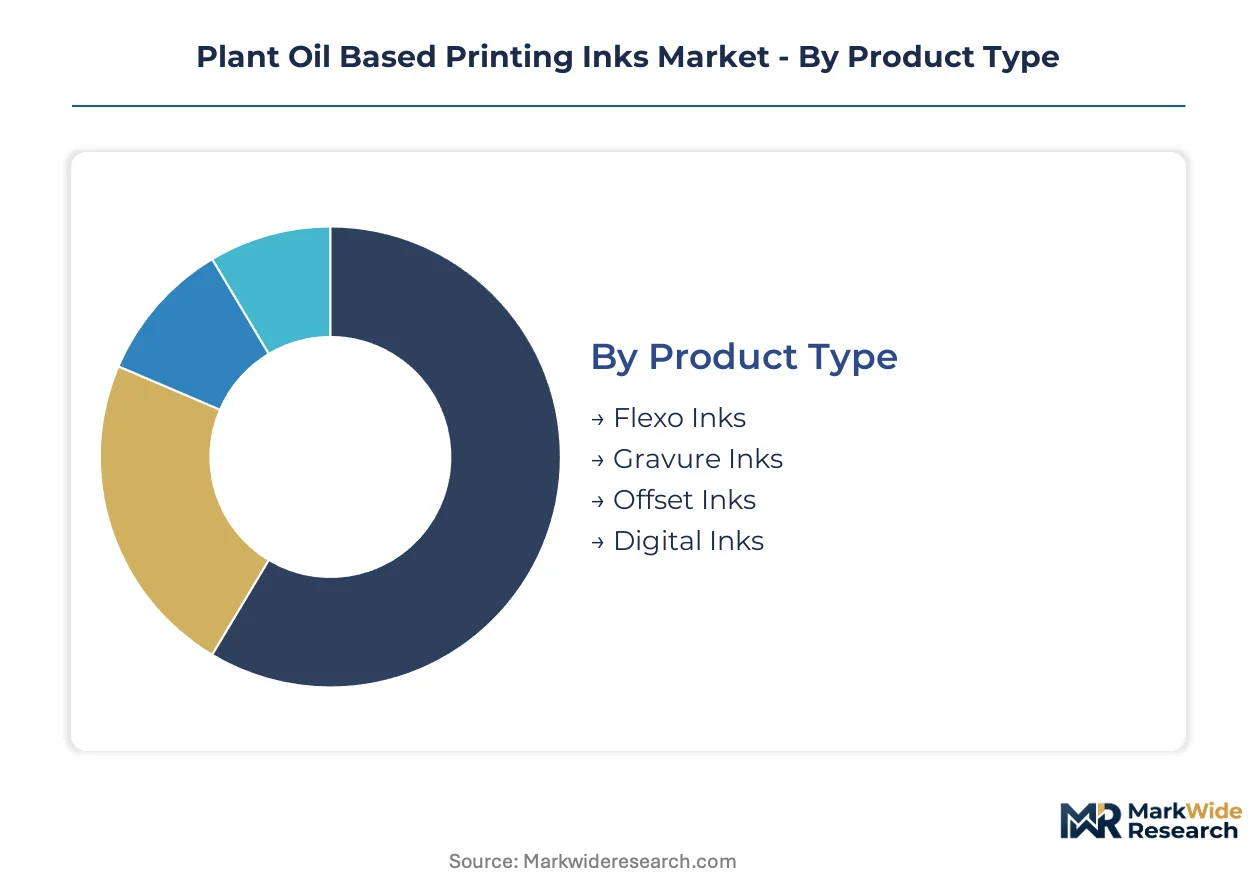
Segment boundaries in plant oil based printing inks reflect divergent regulatory burdens across end-use applications. FDA food contact notifications, REACH substance restrictions, and retailer sustainability scorecards each impose distinct compliance architectures that reshape formulation priorities and channel economics.
Product Type:
Certification intensity varies sharply by print process, with food contact flexo and gravure formulations requiring the most extensive documentation trails while commercial offset operates under lighter notification thresholds.
- Offset Inks:Lithographic vehicles rely on soy and linseed oil alkyds with oxidative drying kinetics tuned for coated paper stocks. Newspaper and sheet-fed commercial printers in Germany and the US dominate offtake as heatset web infrastructure amortizes reformulation costs across high-volume runs.
- Flexo Inks:Water-based emulsions incorporating modified triglyceride esters are displacing solvent-based nitrocellulose in corrugated post-print and flexible food packaging. REACH Annex XVII aromatic restrictions and retailer scorecards in France and the Netherlands accelerate specification switches.
- Gravure Inks:Publication rotogravure faces EPA 40 CFR 59 Subpart E VOC limits at 25% by weight, forcing linseed oil vehicle adoption in US newspaper printing above 100 tons annual solvent consumption.
- Digital Inks:UV-curable and aqueous inkjet formulations with bio-based reactive diluents serve short-run commercial and industrial decoration segments where press flexibility outweighs unit cost premiums.
Offset inks sit at the top of the volume ranking, with flexo inks climbing the fastest as corrugated and flexible packaging converters face compounding sustainability mandates.
End User:
Customer procurement sophistication spans from multinational packaging groups with dedicated regulatory affairs teams to fragmented commercial printers outsourcing compliance documentation.
- Packaging Industry:Folding carton and flexible film converters serving grocery retail chains in Germany and France must document bio-based content for supplier scorecards. FSSAI alignment discussions in India signal future compliance expansion.
- Commercial Printing:Mid-sized sheet-fed operations running 5-8 presses mix base vehicles with additive packages on-press, fragmenting traditional finished ink procurement.
- Publishing Houses:Newspaper printers under EPA heatset web rules consolidate purchasing through distributors with technical service capacity for fountain solution rebalancing.
- Textile Industry:Rotary screen and inkjet applications for natural fiber printing utilize linseed oil carriers where hand-feel and washfastness specifications permit slower oxidative cure profiles.
Packaging applications command the steepest expansion trajectory, with commercial print retaining the largest installed base of legacy press infrastructure.
Feature:
Performance attributes map directly to price tier positioning, with regulatory-driven characteristics carrying margin premiums over purely functional specifications.
- Low VOC:Formulations achieving volatile organic compound reductions below 5% by weight command qualification cost premiums in North American food contact applications where EPA and FDA documentation barriers filter mid-tier suppliers.
- Bio-Based:Certified renewable content verification enables EU Green Deal procurement compliance for public sector print contracts above EUR 200,000.
- Fast Drying:Oxidative catalyst packages accelerate triglyceride polymerization for high-speed heatset web presses, though plant oil rates lag petroleum vehicles above 15,000 impressions per hour.
- High Pigment:Concentrated colorant loadings reduce ink consumption per thousand impressions, appealing to cost-focused commercial printers in Italy and Spain.
Low VOC formulations anchor premium pricing tiers, with bio-based certification gaining share fastest as institutional procurement mandates proliferate.
Distribution Channel:
Channel selection reflects technical service requirements, with complex formulation transitions favoring intermediaries over direct supply relationships.
- Distributors:Regional ink distributors with application laboratories and field technical staff capture reformulation-driven purchasing consolidation among mid-Atlantic US commercial printers and Benelux folding carton converters.
- Direct Sales:Multinational packaging groups with centralized procurement and in-house color management capabilities negotiate direct supply agreements for volume flexo and gravure contracts.
- Online Retail:Standardized offset ink SKUs and color-matched replacement formulations move through digital channels serving small commercial printers with limited technical staff.
- Resellers:Equipment dealers and maintenance providers bundle ink supply with press service contracts, particularly among 1990s-era Heidelberg and Komori installations requiring fountain solution recalibration.
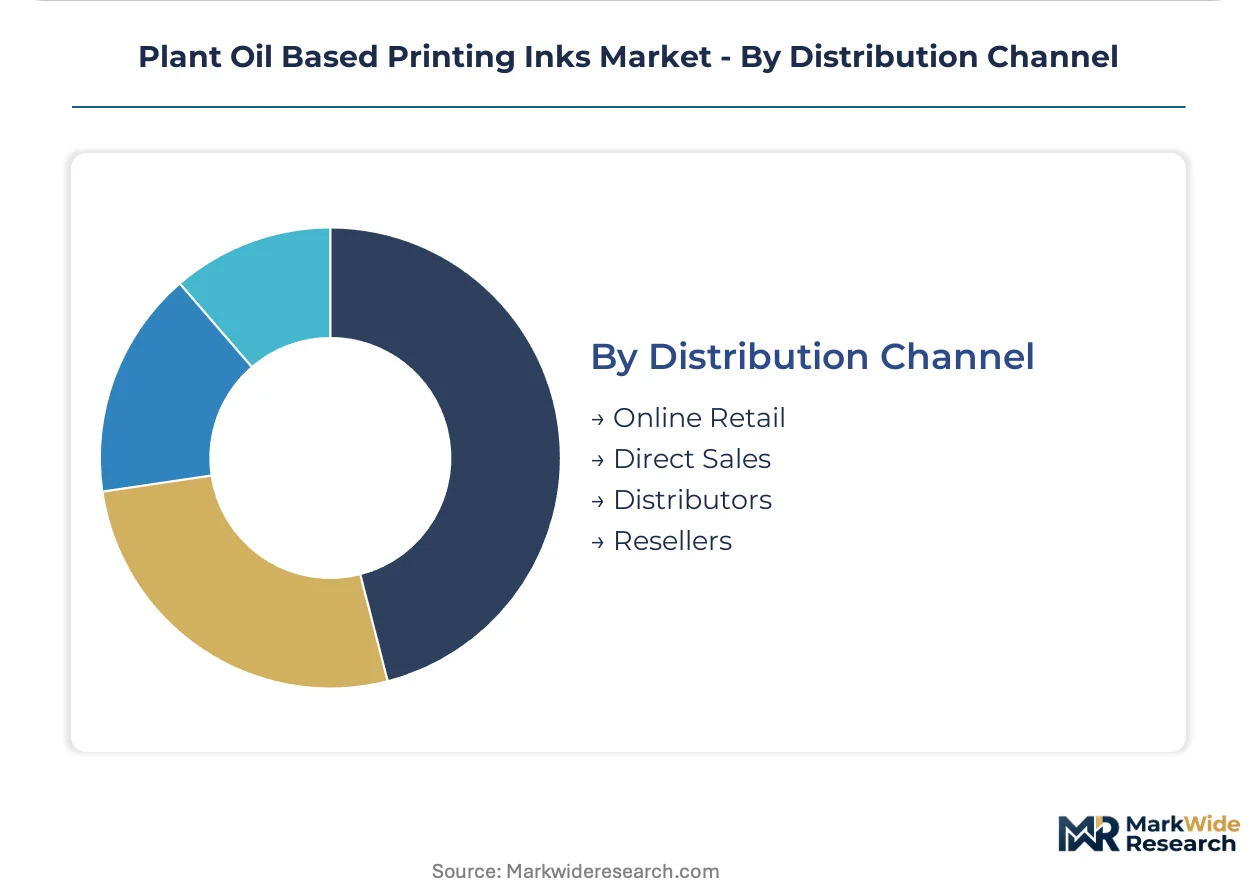
Distributor relationships concentrate the highest-value technical service contracts, with direct sales expanding most quickly among consolidated packaging groups internalizing color management capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plant oil based printing inks industry traces its commercial origins to German alkyd chemistry laboratories in the 1980s, where linseed oil esterification first achieved lithographic performance parity with petroleum vehicles. This technical foundation established enduring production concentration in Central Europe that persists through contemporary sustainability-driven reformulation cycles.
Germany
Cologne anchors European formulation capacity through technical centers serving EU-wide sustainable packaging mandates. REACH Annex XVII aromatic solvent restrictions force folding carton converters to eliminate mineral oil vehicles by 2025. The North Rhine-Westphalia chemical corridor concentrates alkyd resin synthesis for lithographic applications.
United States
Mid-Atlantic commercial printing clusters consolidate purchasing through distributors with technical service capacity for fountain solution rebalancing. EPA 40 CFR 59 Subpart E tightened VOC content limits for publication rotogravure to 25% by weight. Soybean oil feedstock availability from Illinois and Iowa processing infrastructure supports regional formulation houses.
France
Retailer sustainability scorecards from major grocery chains mandate bio-based ink documentation for corrugated secondary packaging. EU Green Deal procurement mandates now require bio-based content verification for public sector print contracts above EUR 200,000. The Île-de-France packaging converter base leads specification adoption for flexible food contact applications.
India
BIS standards for food contact inks remain permissive on mineral oil content, positioning early movers before anticipated FSSAI alignment with EU norms. Maharashtra and Gujarat host emerging flexible packaging converter clusters serving domestic FMCG brands. The country's vegetable oil processing infrastructure from soybean and rapeseed crush facilities offers feedstock cost advantages.
Japan
Integrated pigment manufacturing capabilities reduce third-party dependency for ink houses serving precision electronics and decorative packaging segments. METI industrial standards encourage bio-based content verification in public procurement. The Kanto region maintains formulation expertise in oxidative drying kinetics for high-speed commercial applications.
Plant Oil Based Printing Inks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory affairs capacity and captive resin synthesis capabilities. The vendor base stratifies into three tiers: multinational chemical conglomerates with integrated pigment operations, specialized ink houses with regional formulation expertise, and distributors with technical service laboratories. Consolidation pressure concentrates among mid-tier suppliers lacking FDA food contact notification capacity. Dominant competitive moves include backward integration into alkyd resin production and geographic expansion through distributor network acquisition.
Within the integrated chemical conglomerate tier, Sun Chemical exemplifies captive resin synthesis strategies that control raw material quality across flexo and gravure portfolios. Siegwerk Druckfarben anchors European supply architecture through its Cologne technical center. DIC Corporation occupies a position representing Asia-Pacific integrated manufacturing approaches that reduce third-party dependency in pigment supply.
| Leading Market Players |
|---|
| Sun Chemical |
| Siegwerk Druckfarben |
| INX International Ink Co. |
| Flint Group |
| Nazdar Ink Technologies |
| Toyocolor Co. Ltd |
| DIC Corporation |
| Sakata INX |
| Wikoff Color Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned German alkyd resin specialists, consolidated through three decades of private-equity roll-ups, anchor pricing discipline by controlling linseed oil esterification capacity while passing crop-yield volatility through to formulation houses on quarterly adjustment clauses. Their ownership concentration in the North Rhine-Westphalia chemical corridor lets them enforce term-contract premiums against mid-sized ink houses lacking backward integration into triglyceride processing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant food contact formulations from commercial offset grades and commodity newspaper inks. Price differentiation rests on certification grade and volume scale, with REACH Annex XVII-compliant flexo inks commanding qualification premiums against standard sheet-fed products. Cost compression in the economy tier is intensifying because renewable diesel competition for soybean oil offtake compresses feedstock spreads faster than ink price mechanisms adjust. Small commercial printers in Italy and Spain exhibit the highest price sensitivity, while multinational packaging groups internalizing color management absorb premium tier increases with limited volume elasticity.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from regional distribution centers in Cologne, Chicago, and Mumbai to serve formulation houses with just-in-time alkyd resin deliveries. Geographic supply concentrates in Germany, the United States, and Japan, where captive resin synthesis capabilities reduce third-party dependency. Raw material flows draw from soybean crush facilities in Illinois and Iowa, linseed oil processors in Saskatchewan, and rapeseed refiners in Ukraine and Argentina. Single-source vulnerability in EU alkyd resin capacity for lithographic applications creates continental supply risk. Distribution runs through technical-service-equipped distributors rather than direct channels for mid-sized commercial printer accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Flexible food packaging converters in France and Germany now mandate bio-based ink documentation, shifting procurement toward premium-certified formulations with embedded margin protection.
For Market Incumbents: Hedge formulation chemist scarcity by acquiring retiring specialist expertise at legacy Japanese and German ink houses before competitive poaching accelerates. Deepen captive resin synthesis in North America to offset EU supply concentration risk. Defend margin position through FDA food contact notification capacity that freezes mid-tier competitor pipelines.
For New Entrants and Emerging Players: Capture the underpenetrated flexible packaging segment in India before FSSAI alignment with EU norms closes the regulatory window. Target Maharashtra and Gujarat converter clusters with hybrid plant oil emulsion systems priced below established flexo alternatives. Lead with distributor technical service partnerships rather than direct sales to overcome legacy press compatibility barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier resin suppliers lacking regulatory affairs capacity but holding regional formulation relationships. Long-term viability hinges on bio-based feedstock cost positioning against petroleum alkyd alternatives. Watch renewable diesel offtake spreads as the inflection signal for input cost structure shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkyd Resin Production | Sun Chemical's captive synthesis controls raw material quality across flexo and gravure portfolios. |
| Regulatory Affairs Capacity Buildout | FDA food contact notification expertise filters mid-tier competitors from North American food packaging. |
| Distributor Network Acquisition | Technical service laboratories in Benelux capture reformulation-driven purchasing consolidation. |
| Hybrid Emulsion System Launch | Water-based flexo products displace solvent-based nitrocellulose in corrugated post-print segments. |
| Geographic Expansion to India | Early positioning before FSSAI alignment with EU norms closes regulatory arbitrage windows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation chemists, procurement leads at folding carton converters, distributor technical service directors, and regulatory affairs managers at multinational ink houses with secondary validation. Customs data on vegetable oil trade flows, EPA 40 CFR 59 enforcement records, REACH Annex XVII substance restriction updates, and SEC filings from integrated chemical conglomerates anchored supply-side modeling. Bottom-up triangulation across print process segments and top-down cross-checks against regional packaging demand aggregates ensured consistency.
Segment-weighting approaches distributed value and volume across offset, flexo, gravure, and digital product types, further disaggregated by end-use industry, certification intensity, and distribution channel. CAGRs derived from fitted growth curves incorporating regulatory compliance timelines, feedstock price elasticity estimates, and press fleet turnover rates across the projection horizon. Industry-specific forecast inputs included renewable diesel capacity expansion schedules and retailer sustainability scorecard adoption curves.
Feedstock price volatility, regulatory timeline delays, and press fleet replacement rate variations are the dominant revision risks that could shift trajectory materially. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Ink Additives Market
Printing Inks
Food Grade Inks Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Lithography Inks Market
Printing Inks
North America Printing Inks Market
Printing Inks
Screen Printing Inks Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Functional Printing Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Molecular Ink Market
Printing Inks
Waterborne Ink Market
Printing Inks
Europe Specialty Printing Consumables Market