
 Nutrition Chemicals Market | 2026-2036
Nutrition Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Nutrition Chemicals Market Outlook
Ingredient customization revenue is rewriting profit distribution across the nutrition chemicals value chain. BASF SE leverages its integrated fermentation platforms to dominate specialty amino acid supply. Cargill Incorporated anchors its position through backward integration into agricultural feedstock sourcing. Evonik Industries AG differentiates via biotechnology-driven precision nutrition solutions.
Nutrition chemicals comprise biologically active compounds—amino acids, vitamins, minerals, and enzymes—synthesized through fermentation, chemical synthesis, or extraction processes to enhance nutritional value in food, feed, and pharmaceutical applications. These compounds typically achieve purity thresholds exceeding 98% for pharmaceutical-grade formulations and serve as essential inputs for metabolic function, growth optimization, and disease prevention across human and animal systems. Amino acids command the largest product-type margin pool due to their irreplaceable role in protein synthesis and sports nutrition formulations. Human nutrition applications absorb the fastest-growing demand share as personalized wellness and preventive health trends expand consumer willingness to pay for verified bioactive efficacy. Powder formulations retain volume leadership in industrial procurement, though liquid concentrates gain traction in beverage fortification for their dosing precision and dissolution speed.
FDA dietary supplement regulations and EFSA novel food assessments impose stringent safety substantiation requirements that filter out undercapitalized entrants and elevate compliance costs for market access. ISO 22000 and FSSC 22000 certification frameworks increasingly function as de facto procurement prerequisites for multinational food manufacturers screening supplier networks. Stakeholders must monitor evolving precision fermentation regulatory pathways, as these technologies promise to disrupt traditional extraction-dependent supply structures.
Market Dynamics
Precision fermentation is compressing traditional extraction-dependent supply structures, forcing incumbent chemical synthesis players to retool capacity or cede specialty amino acid margins to biotechnology-enabled entrants.
Growth Catalysts
- EFSA novel food assessments:Standardized safety substantiation pathways accelerate product registration timelines for fermentation-derived ingredients entering European dietary supplement formulations.
- Sports nutrition manufacturers:Clean-label protein fortification demand pulls pharmaceutical-grade amino acid volumes into functional beverage applications at premium purity thresholds.
- Personalized wellness platforms:Direct-to-consumer microbiome testing services create pull-through for condition-specific mineral and enzyme premix combinations.
Market Restraints
- Agricultural feedstock volatility:Corn and soybean price swings transmit directly into fermentation substrate costs, compressing margin stability for amino acid producers dependent on commodity crop supply.
- Specialty enzyme supply concentration:Three contract manufacturers control pharmaceutical-grade lipase and protease capacity, creating single-source vulnerability for infant formula fortification programs.
- Legacy chemical synthesis asset stranding:Sunk costs in solvent-based vitamin C production lines delay transition to two-step fermentation routes despite yield advantages.
Strategic Opportunities
- Indian preventive health expansion:FSSAI functional food category notifications open formulation pathways for clinically substantiated mineral chelates targeting diabetes and cardiovascular wellness segments.
- Cell-culture media crossover:Precision fermentation platforms originally built for food-grade amino acids pivot into pharmaceutical-grade growth factor production for biologics manufacturing.
- ISO 22000 certification arbitrage:Mid-tier Chinese producers invest in FSSC 22000 accreditation to bypass multinational food manufacturer supplier exclusion protocols.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates in legacy pharmaceutical hubs, forcing nutrition chemical producers to recruit from distant industrial biotech clusters.
- Dual certification timeline compression:Simultaneous FDA NDI notification and EFSA novel food dossier preparation strains regulatory affairs capacity without guaranteed market access outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutrition Chemicals Market |
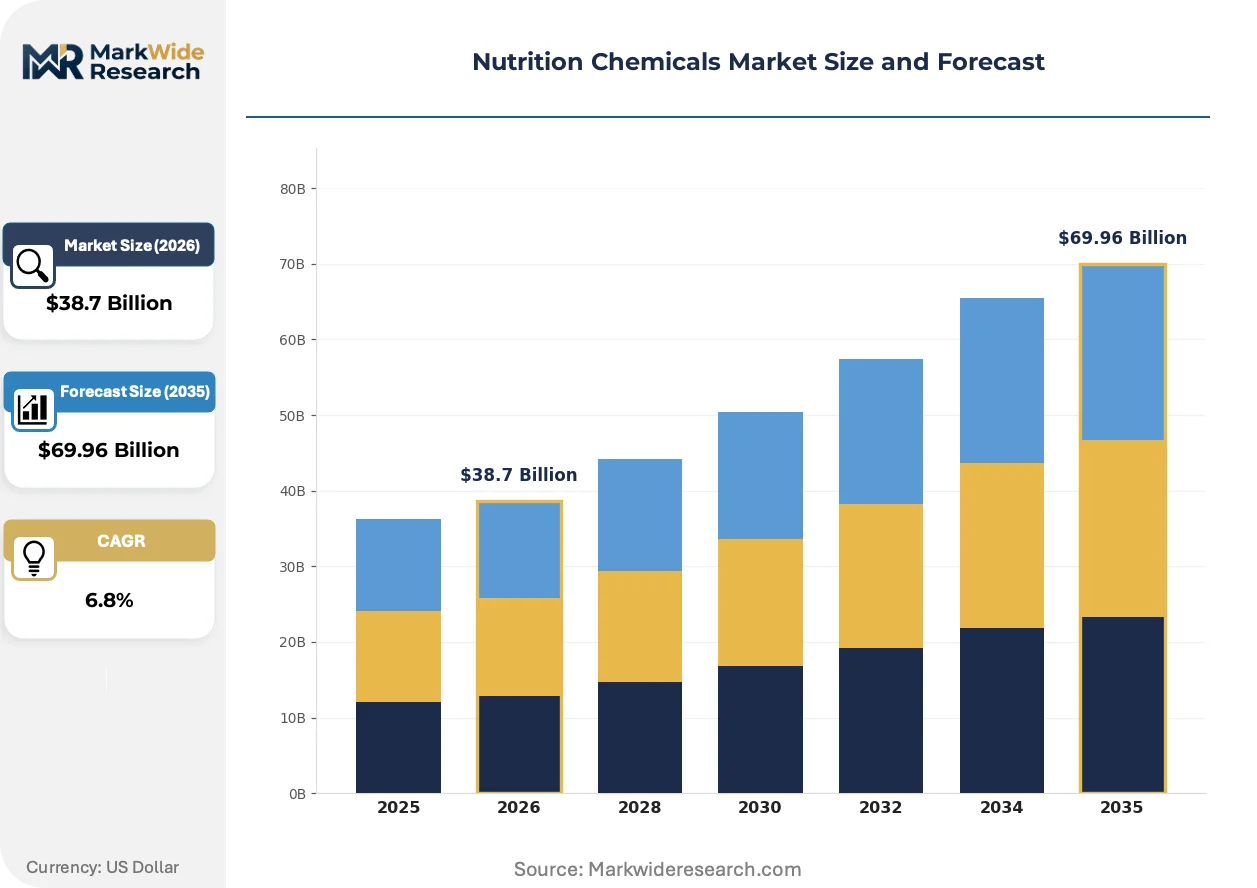
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Minerals, Enzymes Application: Human Nutrition, Animal Nutrition, Pharmaceuticals, Food Fortification Form: Powder, Liquid, Granule, Tablet End User: Food Industry, Dietary Supplements, Pharmaceutical Companies, Livestock |
| Companies Covered | BASF SE, Cargill Incorporated, Evonik Industries AG, International Flavors & Fragrances Inc., Lonza, Tata Chemicals Limited, FMC Corporation, Glanbia PLC, Balchem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutrition Chemicals Market Strategic Shifts
Biotechnology convergence with digital process control is collapsing development cycles for bioactive ingredients, while regulatory fragmentation across fermentation-derived categories forces parallel compliance investments.
Precision fermentation is hybridizing strain engineering with continuous bioprocessing to produce rare amino acids at ton-scale. Contract manufacturers serving sports nutrition brands adopt single-use bioreactor trains to compress campaign changeover downtime. This technology convergence is enabling geographic redistribution of specialty amino acid production away from traditional chemical synthesis clusters.
REACH registration requirements for enzymatic processing aids are tightening purity documentation obligations for imported premixes entering European compound feed operations. Feed manufacturers now demand full substance identity disclosure that legacy paper-based certification systems cannot deliver. Vitamin and mineral premix suppliers with ECHA-registered dossiers capture preferential procurement status from pan-European integrators.
Direct sourcing contracts between ingredient suppliers and finished goods brands are disintermediating traditional distribution layers in human nutrition channels. Sports nutrition and personalized wellness startups negotiate volume commitments directly with fermentation specialists, bypassing regional chemical distributors. This channel compression is most visible in United States direct-to-consumer subscription models where formulation transparency commands price premiums.
Nutrition Chemicals Market Segmentation
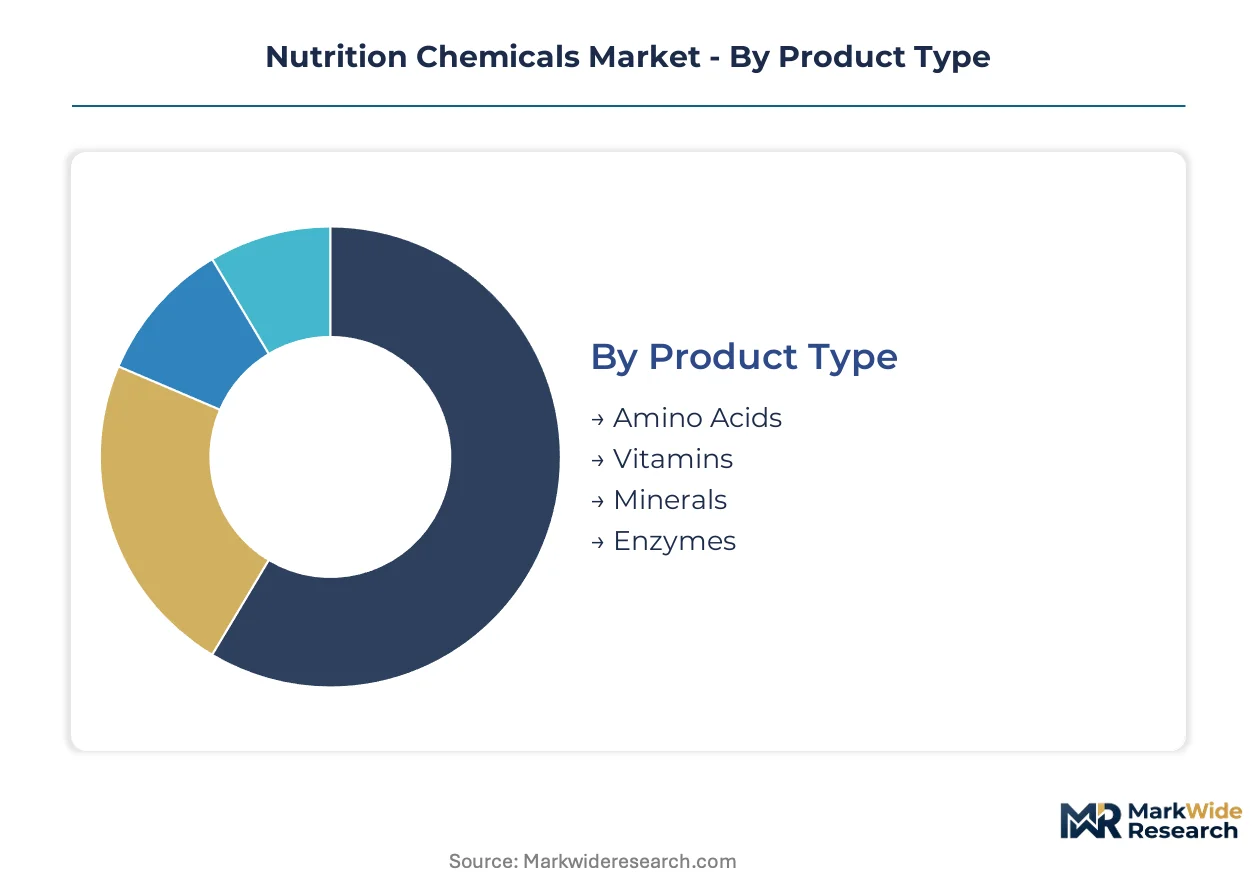
Segmentation in nutrition chemicals separates commodity-grade inputs from premium bioactives commanding formulation premiums. Distinct purity thresholds, regulatory pathways, and end-use specifications create parallel value chains within each category.
Product Type:
Mature chemical synthesis routes dominate commodity vitamins and bulk minerals, while biotechnology-enabled fermentation unlocks specialty amino acids and enzymes at premium positioning.
- Amino Acids:Pharmaceutical-grade purity exceeding 98% enables protein synthesis applications across sports nutrition and clinical enteral feeding. Fermentation-derived L-leucine and L-glutamine concentrate in United States clean-label formulations where FDA NDI notifications substantiate structure-function claims.
- Enzymes:Lipase, protease, and carbohydrase preparations catalyze nutrient bioavailability enhancement in infant formula and digestive health supplements. Supply concentrates among three contract manufacturers serving pharmaceutical-grade specifications, creating single-source vulnerability for formula fortification programs.
- Vitamins:Chemical synthesis remains cost-competitive for ascorbic acid and B-complex compounds, though two-step fermentation routes gain yield advantages.
- Minerals:Chelated forms using glycinate and citrate ligands improve absorption kinetics in personalized wellness applications.
Amino Acids retains volume leadership; Enzymes holds the steepest expansion curve.
Application:
Customer willingness-to-pay gradients separate preventive health positioning from cost-optimized feed supplementation.
- Human Nutrition:Direct-to-consumer microbiome testing platforms pull through condition-specific mineral and enzyme premix combinations. Personalized wellness subscriptions in the United States bypass traditional distribution layers through supplier-brand direct contracts.
- Animal Nutrition:Compound feed operations absorb bulk amino acid volumes where EFSA novel food assessments and REACH-registered enzymatic processing aids determine procurement eligibility for European integrators.
- Pharmaceuticals:Parenteral nutrition formulations demand injectable-grade raw materials with full substance identity documentation.
- Food Fortification:Mandatory flour enrichment programs and voluntary beverage fortification split between regulatory compliance and premium positioning strategies.
Human Nutrition commands the highest purity premiums; Animal Nutrition anchors absolute volume throughput.
Form:
Industrial procurement preferences favor handling efficiency, while finished product integration demands dictate dissolution and dosing characteristics.
- Powder:Free-flowing crystalline forms dominate bulk amino acid and vitamin procurement for premix manufacturing, with hygroscopicity control determining storage stability.
- Liquid:Concentrates enable precise dosing in beverage fortification applications where dissolution speed and homogeneity reduce processing downtime.
- Granule:Agglomerated particles improve flow properties for high-speed tablet compression and reduced dust generation in handling.
- Tablet:Direct-compression ready blends serve finished dietary supplement manufacturers seeking to bypass in-house granulation investment.
Powder retains volume leadership; Liquid is climbing the fastest on beverage fortification demand.
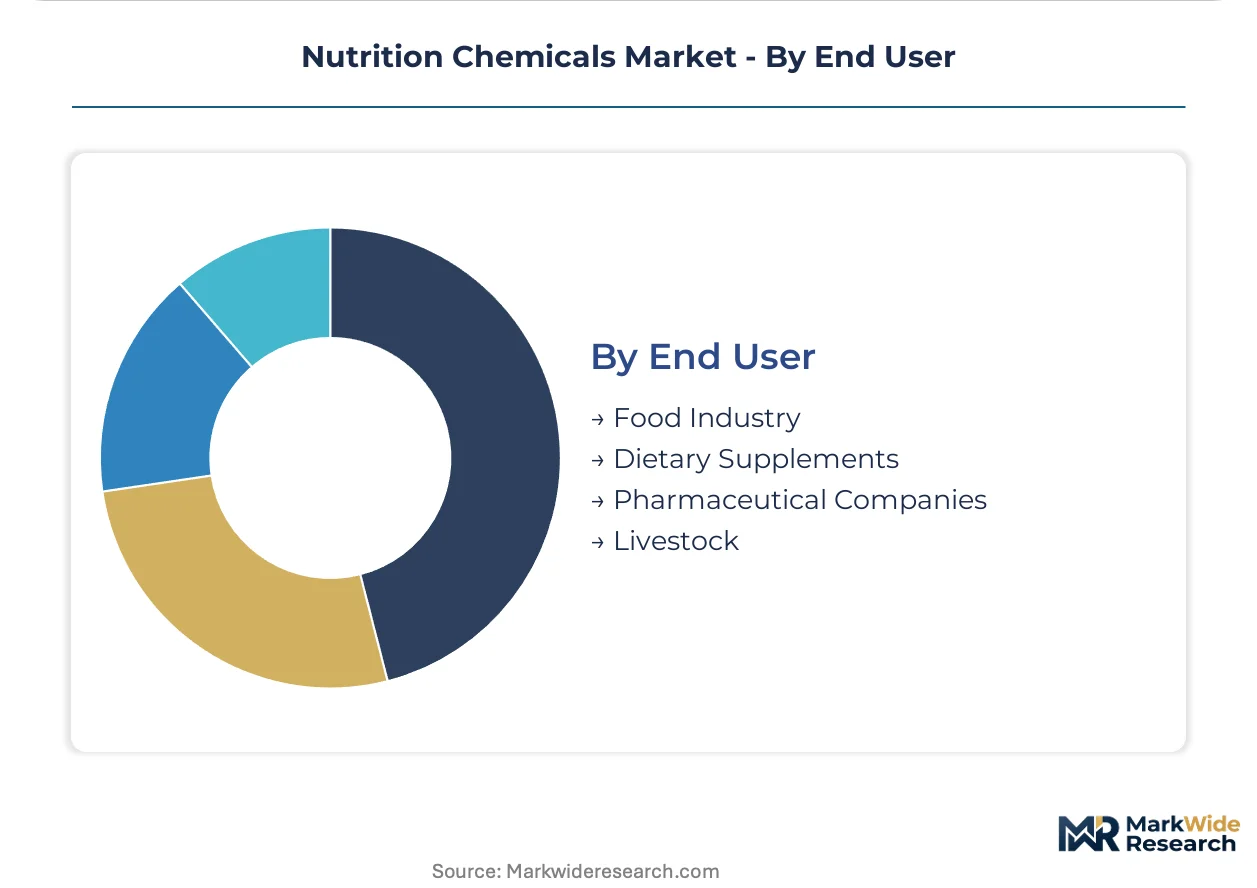
End User:
Certification requirements and formulation transparency standards fragment procurement behavior across customer types.
- Dietary Supplements:Clean-label formulation trends pull pharmaceutical-grade amino acids into sports nutrition applications at purity thresholds previously reserved for pharmaceutical use.
- Food Industry:Multinational manufacturers enforce ISO 22000 and FSSC 22000 as de facto supplier screening protocols, excluding uncertified mid-tier producers from approved vendor lists.
- Pharmaceutical Companies:Injectable and enteral nutrition specifications require drug master file documentation and audit-ready manufacturing sites.
- Livestock:Integrators prioritize cost-per-unit-protein metrics in amino acid procurement, with volatility in corn and soybean feedstock costs transmitting directly into margin pressure.
Dietary Supplements captures the fastest value expansion; Food Industry maintains the broadest supplier certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in livestock feed operations exhibit acute price sensitivity to corn and soybean feedstock swings, while United States sports nutrition brands absorb pharmaceutical-grade amino acid premiums with minimal elasticity. This demand-elasticity contrast shapes regional investment patterns across fermentation capacity and distribution infrastructure.
United States
Sports nutrition manufacturers pull pharmaceutical-grade amino acids into clean-label protein fortification at purity thresholds exceeding 98%. FDA NDI notification requirements filter undercapitalized entrants from structure-function claim substantiation. Chicago and New Jersey corridor fermentation specialists serve direct-to-consumer subscription brands through supplier-brand direct contracts.
Germany
EFSA novel food assessments accelerate fermentation-derived ingredient registration for European dietary supplement formulations. REACH registration requirements tighten purity documentation for enzymatic processing aids entering compound feed operations. Bavaria-based biotechnology clusters retool precision fermentation platforms toward pharmaceutical-grade growth factor production.
China
Mid-tier producers invest in FSSC 22000 accreditation to bypass multinational food manufacturer supplier exclusion protocols. SAMR functional food category oversight shapes mineral chelate formulation pathways for preventive health positioning. Yangtze River Delta fermentation capacity expands single-use bioreactor adoption for campaign changeover compression.
India
FSSAI functional food category notifications open formulation pathways for clinically substantiated mineral chelates targeting diabetes and cardiovascular wellness segments. CDSCO pharmaceutical-grade specifications govern parenteral nutrition raw material procurement. Maharashtra and Gujarat chemical synthesis corridors face margin pressure from agricultural feedstock volatility transmitting through fermentation substrate costs.
Brazil
Livestock integrators prioritize cost-per-unit-protein metrics in bulk amino acid procurement for compound feed operations. ANVISA dietary supplement regulations elevate compliance costs for imported premix market access. São Paulo state distribution networks concentrate backward integration into agricultural feedstock sourcing for margin stability.
Nutrition Chemicals Market Competitive Environment
Diversified chemical conglomerates and specialized biotechnology platforms split the market between commodity-scale efficiency and precision-enabled premium positioning. The vendor base concentrates around three strategic archetypes: integrated fermentation specialists leveraging captive agricultural feedstock, precision biotechnology players commanding rare amino acid margins, and diversified nutrition ingredient suppliers spanning human and animal applications. Dominant competitive moves include backward integration into substrate sourcing and certification arbitrage through ISO 22000 and FSSC 22000 accreditation investments.
Within the integrated fermentation tier, BASF SE and Cargill Incorporated exemplify divergent pathways to supply security. The Ludwigshafen-based chemical conglomerate anchors specialty amino acid positioning through biotechnology-enabled precision nutrition platforms. The Minneapolis-anchored agricultural processor occupies a position defined by upstream control over corn and soybean feedstock supply chains. Evonik Industries AG represents the precision biotechnology archetype, with its German corporate structure signaling rare amino acid specialization.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Evonik Industries AG |
| International Flavors & Fragrances Inc. |
| Lonza |
| Tata Chemicals Limited |
| FMC Corporation |
| Glanbia PLC |
| Balchem Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese fermentation amino acid facilities compresses supplier margins and forces aggressive spot-market pricing to maintain utilization rates. BASF SE and Cargill Incorporated respond with contract-based offtake structures that lock in pharmaceutical-grade premiums while insulating against agricultural feedstock volatility.
Pricing Analysis
After-sales technical service contracts drive lifetime value for precision fermentation platforms, with BASF SE bundling strain optimization support into multi-year amino acid supply agreements. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade purity levels separates sports nutrition brands from livestock integrators. Cost compression in commodity vitamin synthesis is intensifying because Chinese producers flood spot markets with solvent-based ascorbic acid output. Livestock integrators exhibit acute price sensitivity to corn and soybean substrate swings, while United States dietary supplement brands absorb pharmaceutical-grade premiums with minimal elasticity.
Supply Chain Analysis
Export control restrictions on precision fermentation bioreactor technology limit flow of single-use systems from United States and German suppliers to Chinese mid-tier producers. Manufacturing gravity centers on China, Germany, and the United States, with Yangtze River Delta fermentation clusters feeding bulk amino acid volumes into global compound feed operations. Supply chains draw from corn and soybean agricultural feedstocks, pharmaceutical-grade enzyme preparations, and chelated mineral ligands. Single-source vulnerability concentrates in lipase and protease contract manufacturing for infant formula fortification. Distribution runs through direct supplier-brand contracts in human nutrition channels and regional chemical distributors in animal feed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology penetration sits at early-cycle expansion, with personalized wellness platforms pulling condition-specific mineral and enzyme combinations into direct-to-consumer channels.
For Market Incumbents: Harden fermentation platform differentiation through captive strain engineering capabilities that biotechnology-enabled entrants cannot replicate overnight. Expand backward integration into agricultural feedstock sourcing to neutralize corn and soybean price volatility transmitting into margin pressure. Prioritize FSSC 22000 certification investments that multinational food manufacturers enforce as de facto procurement gates. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian preventive health segments where FSSAI functional food notifications open formulation pathways for clinically substantiated mineral chelates. Target diabetes and cardiovascular wellness applications with direct-to-consumer microbiome testing partnerships that bypass traditional distribution layers. Lead with ISO 22000 accreditation as a market entry credential to overcome multinational supplier exclusion protocols. For Investors and Strategic Acquirers: Capital is best deployed toward precision biotechnology platforms with demonstrated pharmaceutical-grade growth factor pivot capacity from food-grade amino acid foundations. Long-term viability over the next decade hinges on regulatory affairs bandwidth for simultaneous FDA NDI notification and EFSA novel food dossier preparation. Watch for inflection signals in precision fermentation regulatory pathway clarity across European and North American jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstock | Cargill Incorporated anchors margin stability through captive corn and soybean supply chains. |
| Precision Fermentation Platform Scale-Up | BASF SE leverages Ludwigshafen biotechnology clusters for rare amino acid ton-scale production. |
| FSSC 22000 Certification Investment | Mid-tier Chinese producers bypass multinational food manufacturer supplier exclusion protocols. |
| Direct Supplier-Brand Contracting | Sports nutrition startups in the United States negotiate volume commitments with fermentation specialists. |
| Pharmaceutical-Grade Growth Factor Pivot | Bavaria-based biotechnology clusters retool food-grade platforms for biologics manufacturing inputs. |
Study Parameters
A spread of perspectives from fermentation plant managers, procurement leads at dietary supplement manufacturers, distribution channel partners, and regulatory affairs directors converged on the working assumptions. Primary interview insights combined with secondary validation from FDA NDI notification databases, EFSA novel food assessment records, SEC 10-K filings, and customs/trade data. Bottom-up amino acid volume estimates triangulated against top-down nutrition chemicals market sizing.
Demand-supply balance modeling tracked fermentation capacity utilization against sports nutrition and personalized wellness pull-through across the analysis window. Segmentation dimensions included product type purity tiers, human versus animal nutrition applications, powder versus liquid formulation formats, and dietary supplement versus food industry end users. CAGRs derived from historical volume trajectories and penetration rate assumptions for precision fermentation technologies. Forecast inputs incorporated agricultural feedstock price elasticity and regulatory approval timeline distributions.
Sensitivities concentrate around precision fermentation regulatory pathway evolution and agricultural commodity price volatility. Forecasts reflect documented assumptions on technology adoption curves and certification requirement timelines. Material shifts in FDA or EFSA novel food assessment procedures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Iodoacetonitrile Market