
 Global Wood Pulp Market | 2026-2036
Global Wood Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Pulp Market Foresight
Elemental chlorine-free bleached softwood kraft is collapsing the price premium against standard grades as tissue and hygiene makers tighten furnish specifications. Suzano S.A. leverages its eucalyptus plantation base to anchor cost leadership across Latin American export flows. Stora Enso Oyj differentiates through integrated Nordic softwood sourcing and specialty pulp lines. Metsä Group controls a vertically linked chain from Finnish forest holdings to bioproduct mill complexes.
Wood pulp denotes fibrous material derived from lignocellulosic biomass via mechanical, chemical, or hybrid separation processes, typically yielding cellulose contents of 90-98 percent for bleached chemical grades used in paper, board, and regenerated fiber applications. Sulfate pulp dominates commercial volumes due to its strength properties and compatibility with diverse tree species, while mechanical pulp retains cost advantages in newsprint and magazine paper despite lower brightness stability. Specialty paper applications command the fastest expansion as thermal, filter, and medical-grade pulps attract formulation-specific premiums. Recycled pulp faces structural constraints from fiber shortening through repeated cycling, limiting its penetration into high-tensile packaging segments.
The EU Deforestation Regulation and REACH chemical compliance frameworks are tightening traceability and bleaching chemistry requirements for pulp entering European conversion facilities. China's GB standards and dual carbon goals from MEE are pushing import substitution toward domestic hardwood plantation programs. Brazil's environmental licensing under IBAMA and Finland's forest certification mandates through PEFC channels shape competitive access for sustainable fiber claims. Stakeholders must monitor how regulatory stringency on carbon intensity and deforestation linkage evolves across these jurisdictions to calibrate sourcing and certification investments.
Market Dynamics
The EU Deforestation Regulation is forcing a wholesale restructuring of fiber traceability systems, compelling mills to deploy satellite-verified chain-of-custody documentation and exclude non-compliant plantation sources from European supply chains.
Growth Catalysts
- Bleached hardwood kraft specialty grades:Consumer goods brands are expanding specification of these pulps for premium packaging applications requiring superior printability and structural integrity.
- REACH chemical compliance frameworks:European conversion facilities are accelerating adoption of elemental chlorine-free bleaching sequences to satisfy tightened discharge limits and product safety dossier requirements.
- Brazilian eucalyptus plantation economics:Favorable rotation cycles and scale efficiencies in Mato Grosso do Sul and Bahia are attracting incremental greenfield mill investment from export-oriented producers.
Market Restraints
- Energy cost volatility:Kraft pulping's thermal intensity exposes margins to natural gas and electricity price swings, particularly in Nordic markets dependent on spot power markets.
- Single-origin supply concentration:Latin American hardwood pulp exports flow through a narrow set of port terminals, creating chokepoint vulnerability during weather disruptions or labor actions.
- Recycled fiber length degradation:Mechanical recycling shortens cellulose chains below thresholds required for high-tensile packaging, structurally capping recycled pulp penetration in containerboard grades.
Strategic Opportunities
- Underpenetrated Indian tissue markets:Per-capita consumption remains below Southeast Asian benchmarks, creating expansion room for virgin softwood furnish as hygiene awareness rises.
- China's dual carbon goals from MEE:Domestic hardwood plantation subsidies and carbon-intensity benchmarks are redirecting import demand toward certified lower-carbon intensity supply sources.
- Digital textile fiber applications:Lyocell and viscose producers are sourcing dissolving-grade pulp for regenerated cellulose feedstock in fast-fashion supply chains.
Industry Challenges
- PEFC and FSC certification timeline compression:Mill auditors face backlogs extending field verification schedules, delaying market access for newly commissioned plantation assets.
- Bioproduct mill integration complexity:Pulp producers diversifying into lignin, tall oil, and bioenergy derivatives encounter process engineering bottlenecks at commercial scale-up.
- Specialty pulp formulation expertise scarcity:Thermal paper and medical-grade segments require polymer chemistry skillsets absent from conventional papermaking labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Pulp Market |
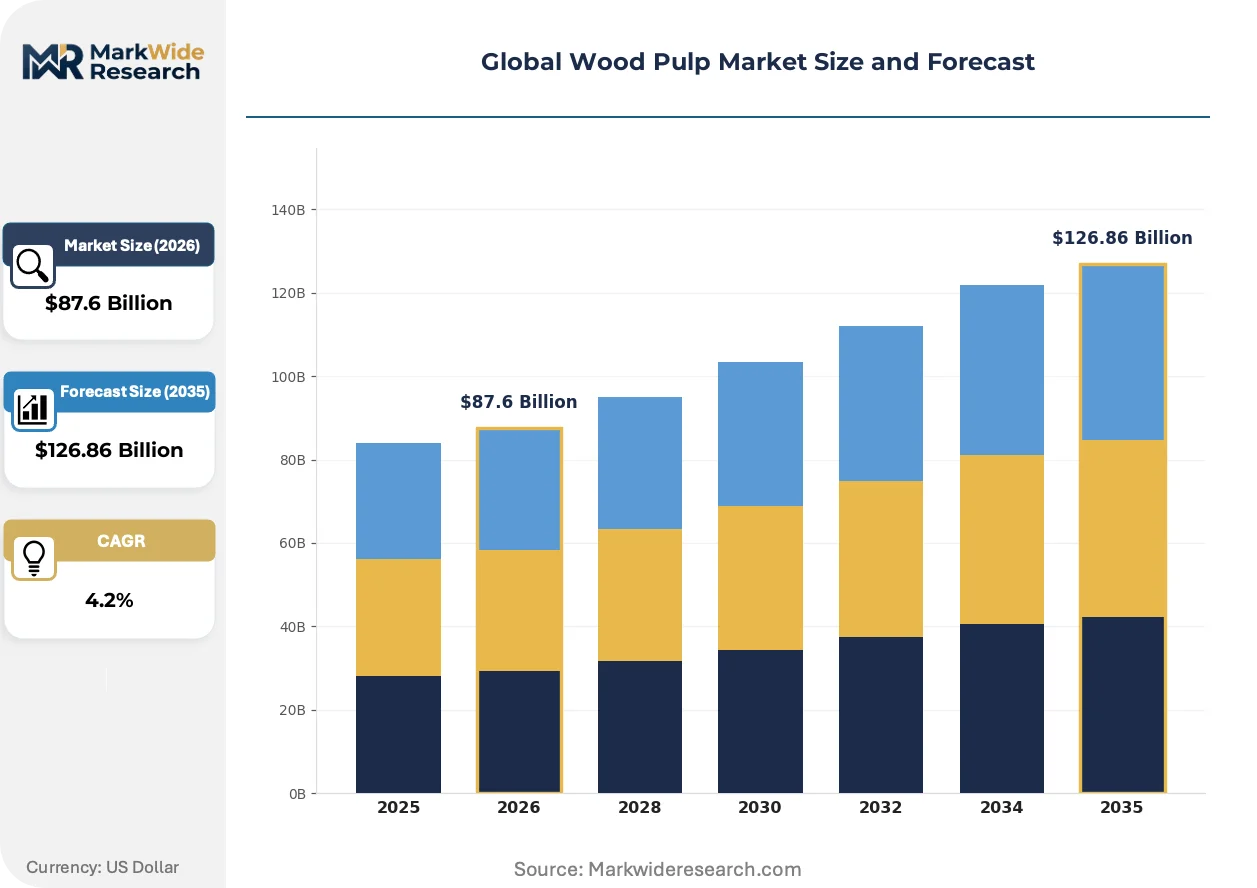
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $126.86 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfate Pulp, Sulfite Pulp, Mechanical Pulp, Chemi-Mechanical Pulp, Recycled Pulp Source Material: Hardwood, Softwood, Agro-based Fibers, Bamboo, Recovered Fibers Application: Packaging, Tissue Paper, Printing Paper, Absorbent Products, Speciality Paper End User: Pulp & Paper Mills, Textile Manufacturers, Construction Firms, Hygiene Product Makers, Chemical Industries |
| Companies Covered | International Paper Company, Suzano S.A., Stora Enso Oyj, UPM-Kymmene Corporation, Sappi Limited, Domtar Corporation, WestRock Company, Oji Holdings Corporation, Metsä Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Pulp Market Shifts & Advancements
Mechanical pulping technology is fragmenting traditional process boundaries as hybrid chemithermomechanical systems erode the cost-performance gap with full chemical routes.
Next-generation chemi-thermomechanical pulping is fragmenting the historical divide between mechanical and chemical yield economics. Tissue and toweling producers in North America are piloting these systems for furnish flexibility. The technology is fragmenting capital allocation patterns as mills defer full kraft rebuilds in favor of hybrid line retrofits.
REACH authorization requirements for persistent organic pollutants are tightening discharge monitoring obligations for pulp bleaching sequences across European mill networks. Integrated producers are deploying closed-loop oxygen delignification stages to reduce adsorbable organic halogen formation. Specialty hygiene paper grades face the steepest compliance cost escalation as brand owners demand third-party verified AOX documentation.
Brand-led sustainable packaging mandates are compressing supplier qualification cycles as consumer goods companies consolidate approved vendor lists around certified low-carbon furnish sources. Major tissue converters are shifting from spot procurement to multi-year offtake agreements with traceability guarantees. This pattern is most pronounced in German and French retail supply chains where private-label sustainability scorecards govern sourcing decisions.
Global Wood Pulp Market Segmentation
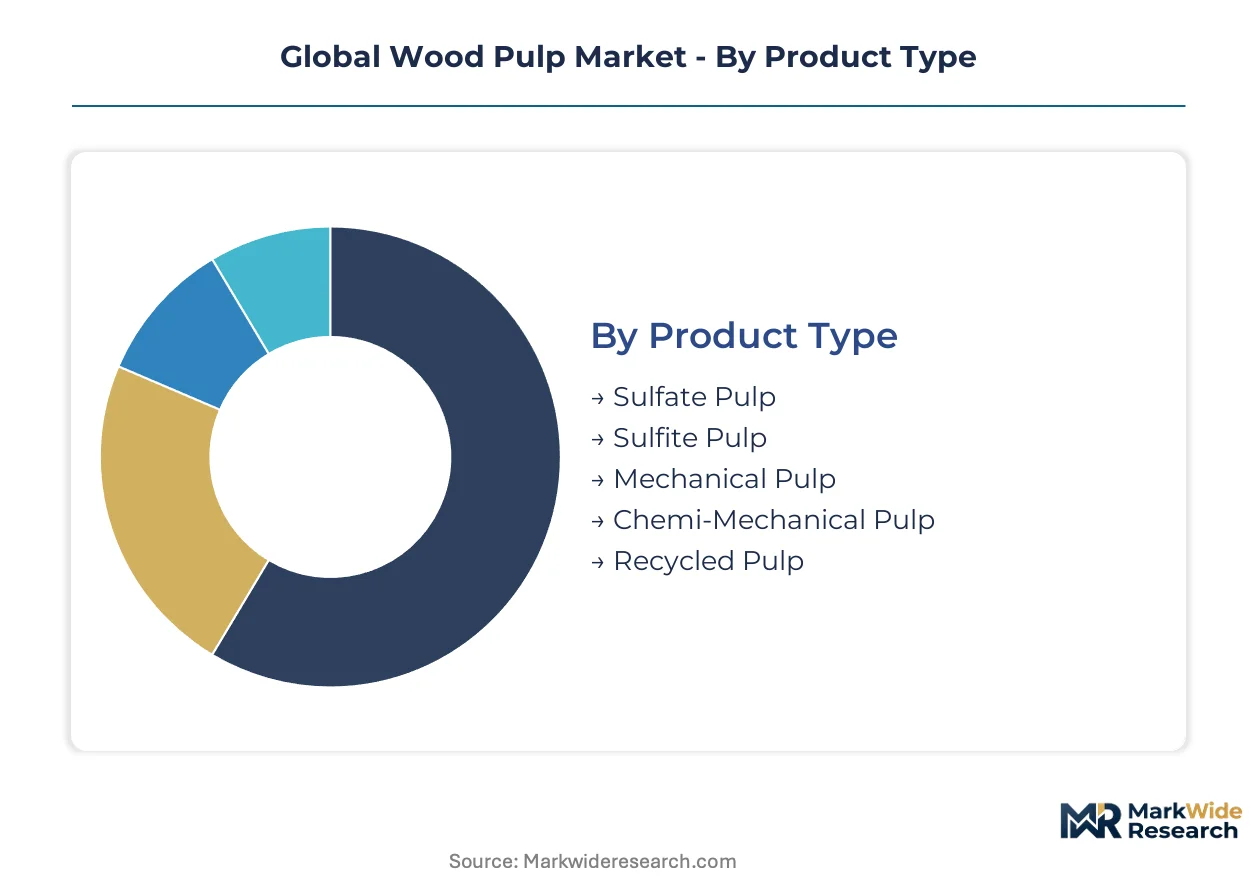
Wood pulp segmentation reveals divergent margin structures across furnish types and end-use specifications. Geographic concentration of demand and regulatory compliance requirements reshape competitive positioning within each category. Understanding these fault lines enables targeted capacity investment and certification prioritization.
Product Type:
Sulfate pulp dominates export flows from Nordic and Latin American mills, while mechanical pulp serves largely domestic graphic paper markets. Sulfite and chemi-mechanical grades occupy intermediate positions with regional supply concentration.
- Sulfate Pulp:Chemical kraft process yields cellulose fibers with superior tensile strength and bleachability for premium packaging and tissue applications. Brazilian eucalyptus plantations and Finnish softwood forests anchor the dominant supply bases for Asian and European converters respectively.
- Mechanical Pulp:Stone groundwood and thermomechanical processes retain lignin content for opacity and bulk in newsprint and magazine paper. Demand concentrates in domestic North American and European publication markets facing secular decline from digital substitution.
- Sulfite Pulp:Acid bisulfite cooking produces dissolving-grade cellulose for textile viscose and specialty chemical derivatives. European and South African mills control commercial volumes.
- Chemi-Mechanical Pulp:Hybrid chemithermomechanical systems bridge yield and quality gaps for packaging board furnish. Canadian and Scandinavian mills lead technology deployment.
- Recycled Pulp:De-inked and repulped post-consumer fiber faces fiber-length degradation limits in high-performance packaging. Collection infrastructure concentration in Germany, Japan, and the US shapes regional availability.
Sulfate pulp commands the established base. The steepest expansion runs through chemi-mechanical hybrid systems as mills defer full kraft rebuilds.
Source Material:
Cost structures stratify sharply between plantation-grown hardwoods and natural forest softwoods, with emerging agro-fiber alternatives pressing from below.
- Hardwood:Eucalyptus and acacia plantations in Brazil, Indonesia, and South Africa deliver short-fiber pulps for tissue and coated paper. Rotation cycles under 10 years compress capital recovery timelines versus temperate softwood alternatives.
- Softwood:Long-fiber pine and spruce from Nordic, Canadian, and Russian boreal forests provide tear strength for packaging and reinforcement pulp. REACH and EU Deforestation Regulation compliance costs escalate for Russian-origin supply.
- Agro-based Fibers:Wheat straw, bagasse, and hemp residues offer annual cropping without forest conversion risks. Chinese and Indian mills pilot commercial-scale integration.
- Bamboo:Fast-renewing grass species native to China and India yield pulp for tissue and textile applications. Processing chemistry challenges limit scale.
- Recovered Fibers:Post-consumer collection and sorting infrastructure determines regional competitiveness. Quality variance constrains penetration into premium grades.
Softwood maintains premium positioning in strength-critical applications. Hardwood plantation economics drive volume expansion in Asian and Latin American markets.
Application:
Packaging and tissue applications pull divergent fiber specifications, with specialty grades commanding formulation-specific premiums.
- Packaging:Containerboard and cartonboard demand bleached and unbleached kraft for structural integrity and printability. E-commerce fulfillment growth in China, the US, and Germany concentrates demand for virgin fiber reinforcement.
- Tissue Paper:Consumer and away-from-home segments require softwood-long-fiber blends for absorbency and hardwood for bulk. Per-capita consumption gaps in India and Southeast Asia signal expansion headroom.
- Printing Paper:Uncoated woodfree and coated mechanical grades face secular pressure from digital media. European and Japanese markets exhibit steepest volume contraction.
- Absorbent Products:Fluff pulp from southern US pine serves diapers and feminine hygiene markets. Procter & Gamble and Kimberly-Clark offtake agreements dominate procurement patterns.
- Speciality Paper:Thermal, filter, and medical grades require purified cellulose with controlled extractives. Lenzing and specialty chemical producers anchor dissolving pulp demand.
Packaging absorbs the largest volume flows. Speciality paper climbs the fastest on premium pricing and technical barriers.
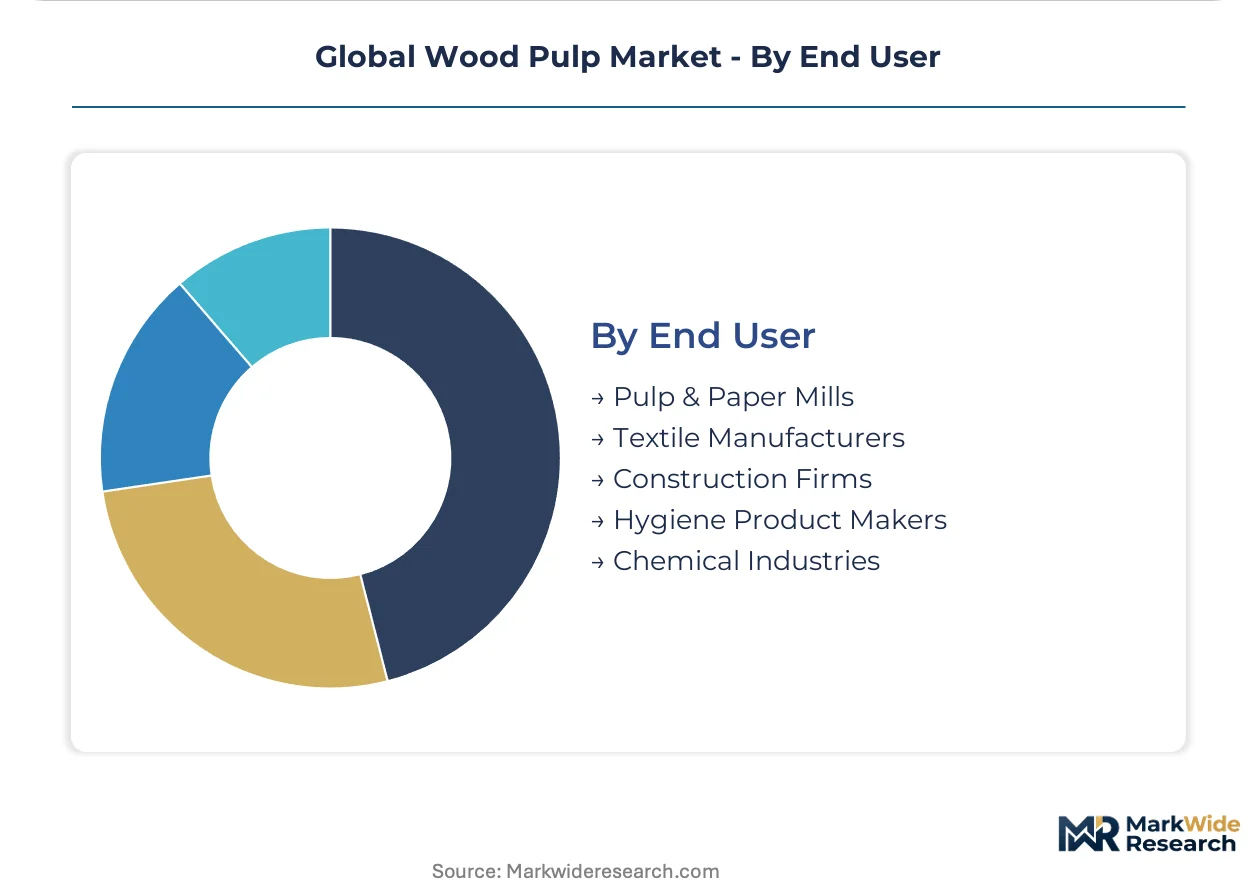
End User:
Pulp and paper mills consolidate procurement through long-term offtake structures, while chemical and textile verticals impose exacting purity specifications.
- Pulp & Paper Mills:Integrated and market pulp consumers blend furnish for paper and board machines. Brazilian and Indonesian mills increasingly supply Asian converters directly.
- Textile Manufacturers:Viscose staple fiber and lyocell producers source dissolving-grade pulp with alpha-cellulose content above 90 percent. Austrian, Indian, and Chinese textile chemical plants dominate offtake.
- Hygiene Product Makers:Diaper and sanitary product converters specify fluff pulp with defined absorbency and fiberization performance. US Gulf Coast and Scandinavian mills serve this concentrated customer base.
- Construction Firms:Cellulose ether and fiber cement applications consume specialty-grade pulp for mortar and board additives. European building chemical formulators drive specification.
- Chemical Industries:CMC, rayon, and nitrocellulose derivatives require high-purity dissolving pulp. Pharmaceutical and food-grade certifications filter supplier eligibility.
Pulp and paper mills anchor the demand base. Textile manufacturers expand most quickly on regenerated fiber substitution for polyester.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mills in Brazil and Finland anchor export supply chains, while Chinese converters drive incremental demand for bleached hardwood grades. Regulatory divergence between EU deforestation rules and Chinese carbon benchmarks is fragmenting certification requirements across trade corridors.
Brazil
Eucalyptus plantation operators in Mato Grosso do Sul and Bahia attract greenfield mill investment from export-oriented producers. IBAMA environmental licensing protocols govern plantation expansion and mill commissioning timelines. São Paulo-based logistics clusters coordinate Latin American hardwood pulp flows to Asian ports.
China
Domestic tissue and packaging converters source imported bleached kraft for reinforcement pulp in containerboard grades. MEE dual carbon goals and GB standards redirect procurement toward certified lower-carbon intensity supply sources. Yangtze River Delta mill complexes blend imported hardwood with domestic plantation fiber.
Finland
Integrated Nordic softwood sourcing supports specialty pulp lines serving European and Asian converters. PEFC forest certification mandates and REACH chemical compliance frameworks govern chain-of-custody documentation. Bioproduct mill complexes in Äänekoski and Kemi anchor vertically linked production from forest holdings to derivative outputs.
Germany
Conversion facilities in the Rhine-Ruhr corridor process imported sulfate pulp for premium packaging and hygiene applications. EU Deforestation Regulation traceability requirements compel satellite-verified documentation from non-EU suppliers. Hamburg and Bremen port terminals handle Nordic and Latin American fiber imports.
United States
Southern pine fluff pulp serves concentrated diaper and feminine hygiene markets through long-term offtake structures. EPA discharge monitoring shapes bleaching sequence investments across southeastern mill networks. Georgia and Alabama chemical pulp complexes supply absorbent product makers with defined fiberization performance grades.
Global Wood Pulp Market Competitive Landscape
Concentration sits with integrated plantation-to-mill operators and Nordic forest-holding conglomerates. Brazilian eucalyptus-based producers and Finnish softwood-integrated groups anchor the tiered competitive structure. Strategic moves center on bioproduct mill diversification into lignin and tall oil derivatives, plus multi-year offtake agreements with traceability guarantees for European retail supply chains.
Among Latin American plantation-anchored producers, Suzano S.A. exemplifies cost leadership through eucalyptus rotation economics. Within the Nordic integrated tier, Stora Enso Oyj and Metsä Group occupy positions linking forest certification to specialty pulp premiums. UPM-Kymmene Corporation represents the diversified forest industry model spanning pulp, paper, and bioproduct outputs.
| Leading Market Players |
|---|
| International Paper Company |
| Suzano S.A. |
| Stora Enso Oyj |
| UPM-Kymmene Corporation |
| Sappi Limited |
| Domtar Corporation |
| WestRock Company |
| Oji Holdings Corporation |
| Metsä Group |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with traceability guarantees lock in Brazilian hardwood pulp supply for European packaging converters while capping price volatility exposure against spot market swings. REACH compliance costs and EU Deforestation Regulation documentation requirements embed premium tiers for certified furnish, separating contract-bound buyers from spot purchasers facing qualification delays.
Pricing Analysis
EU Deforestation Regulation dictates the pricing tier structure by forcing satellite-verified chain-of-custody documentation as a mandatory qualifier for European market access. Three-tier pricing structure across premium, standard, and economy levels separates elemental chlorine-free certified grades from conventional bleached kraft and spot-traded mechanical pulp. Cost compression in standard kraft grades is intensifying because tissue makers are tightening furnish specifications and collapsing former quality premiums. Hygiene product makers exhibit the lowest price sensitivity due to fluff pulp's irreplaceable absorbency performance, while printing paper converters face acute margin pressure from digital substitution.
Supply Chain Analysis
Santos port terminal congestion in São Paulo state underwrites Latin American hardwood pulp export vulnerability during weather disruptions or labor actions. Brazilian eucalyptus plantations, Finnish boreal softwood forests, and Indonesian acacia estates anchor global sulfate pulp supply. Kraft pulping draws from natural gas, electricity, and chemical inputs including sodium hydroxide and sulfur. Single-origin concentration through narrow port chokepoints creates structural vulnerability. Distribution runs through integrated mill-to-converter direct shipments and merchant pulp traders serving smaller paper machines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty pulp formulation expertise scarcity constrains expansion into thermal paper and medical-grade segments where polymer chemistry skillsets command premium margins. Mills lacking in-house R&D capabilities face disqualification from brand-led sustainable packaging vendor consolidation.
For Market Incumbents: Shield core eucalyptus plantation positions by accelerating PEFC and FSC certification field verification to preempt EU Deforestation Regulation access barriers. Secure backward integration into lignin and tall oil bioproduct derivatives to offset kraft pulp margin compression from energy cost volatility. Prioritize multi-year offtake structures with German and French retail supply chains where private-label sustainability scorecards govern procurement decisions. For New Entrants and Emerging Players: Dissolving-grade pulp supply gaps for Indian and Southeast Asian viscose staple fiber producers represent the most penetrable white-space target, as Austrian and Chinese textile chemical plants face carbon-intensity benchmark pressure under MEE dual carbon goals. Entry through certified lower-carbon intensity supply positioning captures redirecting Chinese import demand. Go-to-market leverage rests on direct mill relationships with Yangtze River Delta converters blending imported hardwood with domestic plantation fiber. For Investors and Strategic Acquirers: Plantation-anchored mid-cap producers with approved IBAMA environmental licensing and unencumbered port terminal access present acquisition targets with embedded supply security. Long-term viability centers on rotation economics under 10 years compressing capital recovery timelines versus temperate softwood alternatives. Watch for MEE carbon-intensity benchmark enforcement tightening as the inflection signal redirecting procurement toward certified supply sources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive eucalyptus supply in Mato Grosso do Sul insulates against fiber cost volatility and IBAMA licensing delays. |
| Bioproduct Mill Diversification | Lignin and tall oil derivative output at Äänekoski and Kemi complexes spreads capital recovery across pulp and biochemical revenue streams. |
| Multi-Year Offtake Agreement Structuring | Traceability guarantees embedded in German retail supply chain contracts preempt EU Deforestation Regulation compliance disqualification. |
| Specialty Pulp Line Commissioning | Thermal and medical-grade purified cellulose production captures formulation-specific premiums from Lenzing and hygiene chemical producers. |
| Hybrid Chemithermomechanical Retrofit | Canadian and Scandinavian mills defer full kraft rebuild capital while bridging yield-quality gaps for packaging board furnish flexibility. |
Research Methodology
A standing panel of pulp mill operations directors, European packaging converter procurement leads, textile fiber R&D heads, and forest certification auditors provided ongoing calibration against trade flow data and mill capacity announcements. Primary interviews with IBAMA licensing officers and MEE carbon policy specialists cross-checked regulatory timeline assumptions. Secondary validation drew from customs export records, PEFC chain-of-custody databases, FAO forest product statistics, and SEC pulp segment disclosures. Bottom-up mill capacity modeling triangulated against top-down end-use demand aggregation across tissue, packaging, and dissolving pulp applications.
Consistency checks against external benchmarks validated volume and value outputs against FAO trade statistics and regional production association reports across the analysis window. Segmentation modeling incorporated furnish type, source material, end-use application, and geographic regulatory cluster dimensions. CAGRs were derived from weighted capacity expansion schedules and per-capita consumption convergence assumptions. Industry-specific forecast inputs included eucalyptus rotation cycle economics, REACH discharge limit enforcement trajectories, and Chinese domestic hardwood plantation subsidy uptake rates.
Forecasts assume regulatory continuity in EU Deforestation Regulation implementation, REACH authorization timelines, and MEE dual carbon goal enforcement; material policy shifts would require re-modeling supply qualification costs and import substitution patterns. Scenario readiness demands monitoring IBAMA environmental licensing backlog resolution, Nordic spot power market price volatility, and certification auditor field verification capacity constraints as conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Base Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Global Direct Thermal Ticket Paper Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
Pharma Grade Paper Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
Thin Printing Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Filtration Paper Market
Paper Products
Paper Coating Materials Market
Paper Products
North America Medium-Density Fiberboard Market
Paper Products
Paper Machine Systems Market
Paper Products
Global Cellulose Sponge Market