
 Duplex Paper and Board Market | 2026-2036
Duplex Paper and Board Market Size, Share, and Industry Trends Forecast 2026-2036
Duplex Paper and Board Market Foresight
Aftermarket service revenue from packaging line optimization and print-finishing support is tilting margin pools away from commodity board sales. Mondi Group leverages integrated pulp-to-board operations across Central Europe to sustain cost discipline. Stora Enso anchors its Nordic position through certified virgin fiber streams for premium folding boxboard grades. Nine Dragons competes aggressively on recycled fiber throughput in coastal Chinese manufacturing clusters.
Duplex paper and board denotes a multi-ply paperboard with a white printable topside and grey or brown reverse, typically constructed from 250–450 gsm layered fiber webs for rigidity and printability. Its primary purpose centers on consumer-facing packaging, point-of-sale displays, and book covers where surface quality and structural integrity must coexist. Coated duplex commands the widest margin pool among product types due to its suitability for high-resolution lithographic printing in cosmetics and electronics packaging. Recycled fiber grades under the grade dimension are gaining fastest traction as brand owners enforce post-consumer content minimums across European and North American supply chains.
The EU Green Deal's packaging waste reduction targets and REACH chemical compliance frameworks reshape material specifications and recyclability claims across European supply chains. China's MEE enforces wastewater discharge limits that elevate capital requirements for mills running high-volume recycled fiber lines. India's BIS mandates local testing for imported board lots, creating procedural friction for foreign suppliers. Stakeholders must monitor how divergent national recycling infrastructure investments determine which fiber grades achieve cost-competitive circularity at scale.
Market Dynamics
The EU Green Deal's packaging waste reduction targets and China's dual carbon goals are compressing virgin fiber margins while elevating certified recycled grades across multi-ply board supply chains.
Growth Catalysts
- E-commerce fulfillment packaging:Third-party logistics providers in India and Southeast Asia are standardizing on 300–400 gsm duplex board for protective secondary packaging. BIS certification requirements under the PLI scheme for packaging materials are accelerating domestic mill capacity additions.
- REACH chemical compliance:European brand owners are mandating post-consumer recycled content minimums in folding boxboard specifications. This regulatory pull is expanding deinking capacity and closed-loop fiber collection infrastructure across Germany and the Netherlands.
- Dual carbon goals:China's MEE wastewater discharge limits are forcing coastal mills to upgrade recycled fiber processing lines. Mills achieving compliance are capturing preferential supply contracts from export-oriented electronics packaging buyers.
Market Restraints
- Recycled fiber input volatility:Old corrugated container prices fluctuate with Chinese import quota adjustments and Indian monsoon-season collection disruptions. Mills without captive pulp supply face margin compression during price spikes.
- Supply concentration in Nordic virgin fiber:Premium folding boxboard grades depend on certified boreal softwood pulp from a limited number of Finnish and Swedish integrated producers. Any disruption to these fiber streams propagates through European cosmetics and electronics packaging supply chains.
- Substitute board technologies:Molded fiber and thermoformed plastic alternatives are capturing share in lightweight electronics and foodservice applications where print surface quality is secondary to cushioning performance.
Strategic Opportunities
- Underpenetrated Indian premium segment:Domestic capacity for coated duplex above 350 gsm remains insufficient for pharmaceutical and luxury cosmetics packaging. Mills investing in multi-ply formers with online coating stations can capture import substitution margins.
- EU AI Act supply chain traceability:Packaging converters deploying digital watermarking and blockchain-verified fiber provenance systems will qualify for premium tier pricing from brand owners facing CSRD disclosure requirements.
- Digital print-finishing convergence:Integration of inkjet personalization with traditional lithographic base printing is enabling short-run versioning for regional promotional campaigns. This hybrid workflow is virtualizing inventory models for seasonal consumer goods.
Industry Challenges
- Deinking chemistry expertise scarcity:Mills scaling recycled fiber lines require process engineers fluent in enzymatic ink removal and stickies control. European and North American technical training programs are not producing sufficient talent pipelines.
- BIS certification timeline friction:Foreign suppliers to India face 90–120 day testing cycles for imported board lots. This procedural delay complicates just-in-time supply relationships with Mumbai and Delhi-based converters.
- Capex intensity for emissions compliance:China's MEE standards require anaerobic wastewater treatment and biogas capture systems representing 15–20% of mill replacement value. Smaller coastal operators lack balance sheet capacity for these investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duplex Paper and Board Market |
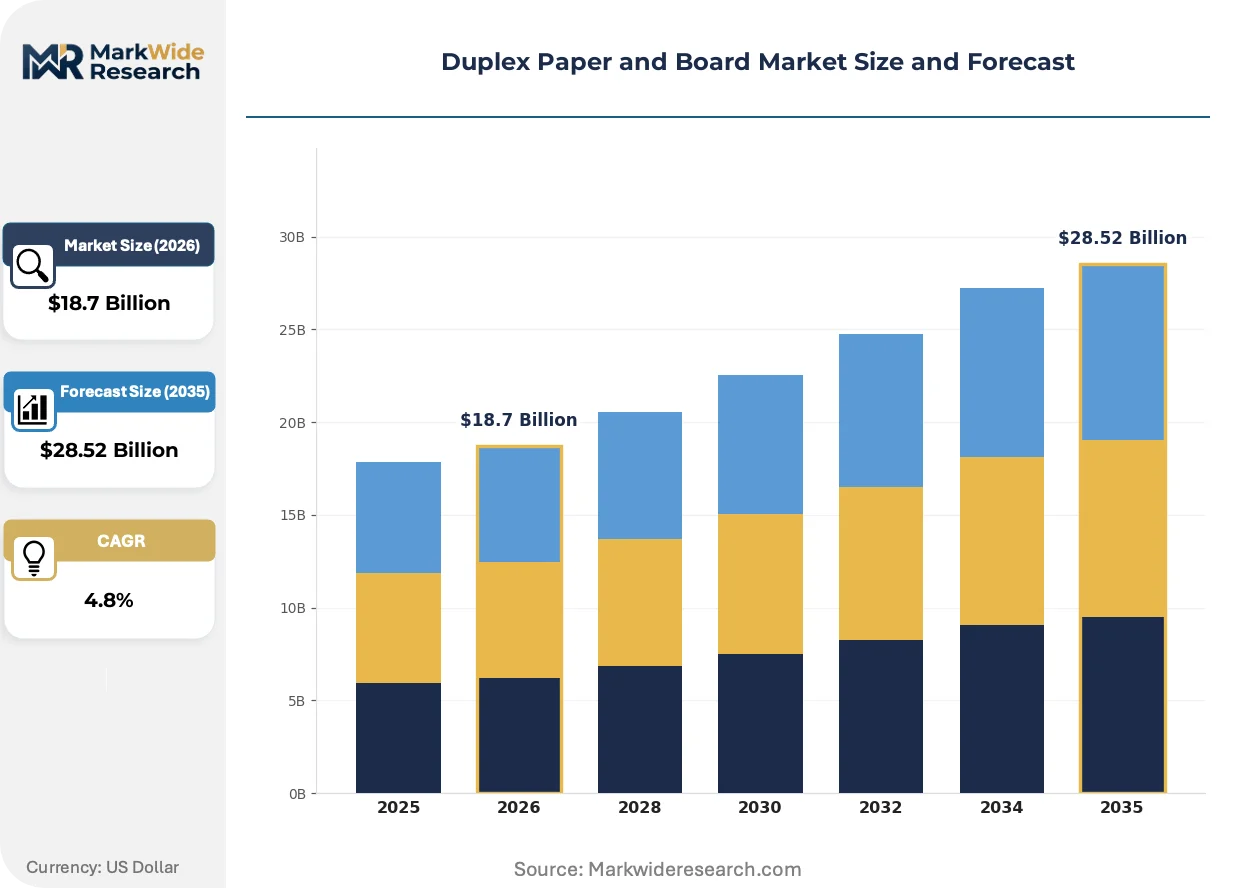
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uncoated Duplex, Coated Duplex, Linerboard, Folding Boxboard End Use Industry: Food Packaging, Consumer Goods, Pharmaceuticals, Stationery Grade: Virgin Fiber, Recycled Fiber, Bending Strength, Brightness Application: Printing, Packaging, Corrugated Boxes, Graphic Design |
| Companies Covered | Mondi Group, Sappi, International Paper, Oji Holdings Corporation, Nippon Paper Industries, WestRock, Stora Enso, Nine Dragons, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duplex Paper and Board Market Shifts & Advancements
Digital production workflows and regulatory traceability mandates are compressing traditional print runs while fragmenting fiber certification requirements across buyer segments.
Digital inkjet personalization technology is virtualizing the economics of short-run packaging production. Beauty and electronics brands in Germany and France are adopting versioned carton designs with regional language and promotional customization. This capability is collapsing minimum order quantities from 50,000 units toward 5,000 units, enabling test-market packaging without lithographic plate costs.
REACH chemical compliance frameworks are restricting coating chemistries and adhesive formulations used in food-contact board grades. European converters are reformulating barrier coatings to eliminate per- and polyfluoroalkyl substances ahead of 2025 restriction deadlines. Premium folding boxboard producers with verified fluorine-free barriers are capturing shelf space from competitors facing reformulation delays.
Consolidated buying desks at multinational consumer goods companies are compressing supplier panels and demanding outcome-based packaging performance guarantees. Unilever and L'Oréal procurement teams in Western Europe now specify recyclability rates and carbon intensity per thousand units rather than board gsm and brightness metrics. This shift is forcing mills to invest in lifecycle assessment capabilities and third-party certification to retain preferred supplier status.
Duplex Paper and Board Market Segmentation
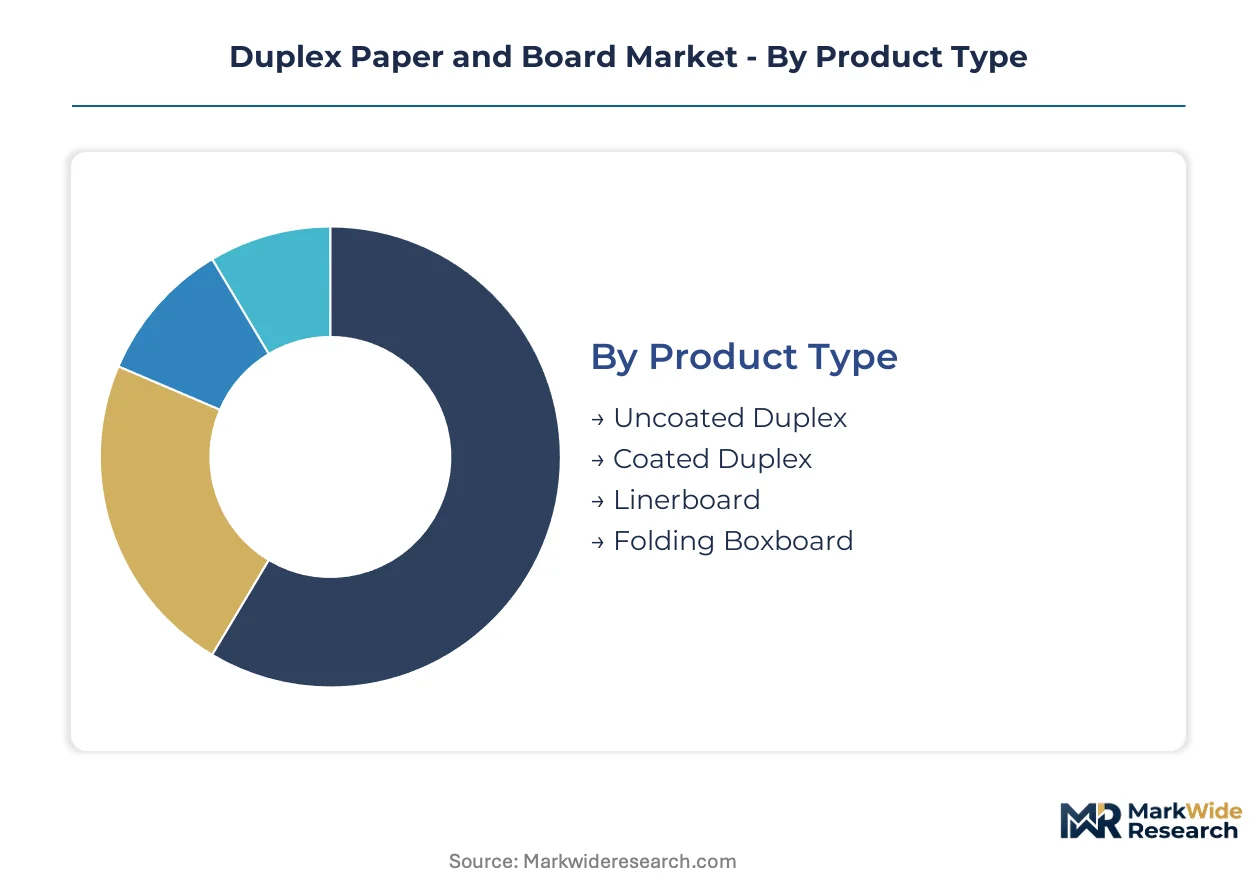
Duplex paper and board segmentation reflects divergent fiber sourcing strategies and print performance requirements across consumer-facing industries. Product type and grade distinctions determine margin capture, while end-use concentration in e-commerce and pharmaceuticals reshapes volume allocation across manufacturing clusters.
Product Type:
Mature lithographic grades dominate volume, yet emerging digital-print-compatible surfaces are capturing premium positioning in short-run versioning applications.
- Coated Duplex:Clay-coated white topside over grey back delivers high-resolution print receptivity for cosmetics and electronics packaging. European brand owners specify this grade for shelf-facing cartons in Germany and France where surface gloss and color fidelity command supplier premiums.
- Uncoated Duplex:Unfinished white or mottled surface suits cost-sensitive secondary packaging and book cover applications. Indian third-party logistics providers standardize on 300–400 gsm uncoated grades for e-commerce protective inserts under BIS certification mandates.
- Linerboard:Outer facing layer for corrugated construction, typically 150–200 gsm, provides printability on box exteriors. Demand concentrates in Chinese coastal manufacturing clusters serving export electronics fulfillment.
- Folding Boxboard:Multi-ply solid bleached or unbleached board for premium carton conversion. Nordic integrated producers anchor supply through certified virgin fiber streams for pharmaceutical and luxury goods applications.
Coated duplex handles the majority of throughput; recycled-content folding boxboard is expanding most quickly on share as REACH compliance tightens across European supply chains.
End Use Industry:
Cost tier stratification separates commodity protective packaging from performance-specified pharmaceutical and cosmetics applications requiring batch-level traceability.
- Food Packaging:Barrier-coated grades for dry goods and frozen products must satisfy EFSA migration limits and fluorine-free coating mandates. European converters are reformulating barriers ahead of 2025 restriction deadlines.
- Consumer Goods:Electronics and personal care brands in India and Southeast Asia drive 300–400 gsm duplex consumption for protective secondary cartons. PLI scheme incentives are accelerating domestic mill capacity additions to serve this segment.
- Pharmaceuticals:Folding boxboard with verified fiber provenance and serialization compatibility for regulatory compliance. Unilever and L'Oréal procurement teams now specify carbon intensity per thousand units rather than traditional brightness metrics.
- Stationery:Book covers and rigid presentation materials requiring lay-flat rigidity and surface durability. This segment maintains steady demand through educational and corporate procurement channels.
Consumer goods absorbs the largest volume share; pharmaceutical specifications are climbing the fastest as CSRD disclosure requirements harden.
Grade:
Customer type bifurcation separates brand owners with post-consumer content mandates from cost-optimized buyers prioritizing bending performance over fiber provenance.
- Recycled Fiber:Post-consumer reclaimed pulp construction with controlled contaminant levels for closed-loop circularity claims. REACH chemical compliance frameworks are expanding deinking capacity across Germany and the Netherlands.
- Virgin Fiber:Certified boreal softwood pulp from Finnish and Swedish integrated producers for premium folding boxboard. Any disruption to these fiber streams propagates through European cosmetics packaging supply chains.
- Bending Strength:Structural specification grade measured in Taber units for rigid box and display applications. Electronics packaging buyers in coastal China prioritize this metric for protective performance.
- Brightness:ISO or TAPPI reflectance measurement determining print color reproduction fidelity. High-brightness grades command tiered pricing premiums in cosmetics and luxury goods segments.
Recycled fiber now handles the majority of new capacity investment; virgin fiber grades retain steepest margin expansion where certified supply remains concentrated.
Application:
Supply concentration in corrugated converting clusters shapes regional demand patterns, while graphic design applications fragment across digital and traditional print workflows.
- Packaging:Primary and secondary carton construction for product protection and shelf presentation. This application anchors volume throughput across all geographic markets.
- Corrugated Boxes:Combined board construction using duplex as outer liner for strength and printability. Chinese MEE wastewater discharge limits are forcing mill upgrades on recycled fiber lines serving this segment.
- Printing:Lithographic, flexographic, and digital inkjet surface preparation for branded communications. Digital inkjet personalization is collapsing minimum order quantities from 50,000 units toward 5,000 units in German and French markets.
- Graphic Design:Presentation folders, point-of-sale displays, and promotional materials requiring structural integrity and surface quality. Short-run versioning capabilities are virtualizing inventory models for seasonal campaigns.
Packaging commands the dominant throughput position; digital-print-enabled graphic design is gaining share fastest as hybrid workflows proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian third-party logistics providers exhibit acute price sensitivity on 300–400 gsm uncoated grades, while German cosmetics brands absorb steep premiums for certified high-brightness folding boxboard with verified fiber provenance.
India
E-commerce fulfillment packaging and pharmaceutical secondary cartons drive duplex consumption across Mumbai and Delhi-NCR logistics corridors. BIS certification mandates under the PLI scheme for packaging materials are accelerating domestic mill capacity additions. Gujarat-based manufacturing clusters are expanding multi-ply former investments to capture import substitution margins in coated grades above 350 gsm.
China
Export-oriented electronics packaging buyers in coastal provinces are consolidating supply contracts around MEE-compliant recycled fiber mills. Dual carbon goals are forcing wastewater treatment upgrades representing substantial capital commitments for smaller operators. Pearl River Delta manufacturing hubs are prioritizing deinking line expansions to serve brand owner post-consumer content requirements.
Germany
REACH chemical compliance frameworks and CSRD disclosure requirements are hardening specifications for fluorine-free barrier coatings in food-contact applications. Rhineland converting clusters are deploying digital watermarking systems to qualify for premium tier pricing from multinational consumer goods procurement desks. ECHA reformulation deadlines are compressing supplier panels toward certified lifecycle assessment capabilities.
United States
Consolidated buying desks at consumer goods companies are demanding outcome-based performance guarantees rather than traditional brightness metrics. Midwest corrugated converting corridors are integrating inkjet personalization capabilities for short-run versioning in seasonal promotional campaigns. EPA wastewater discharge frameworks are elevating capital requirements for mills scaling recycled fiber throughput.
Sweden
Certified boreal softwood pulp streams anchor premium folding boxboard supply for pharmaceutical and luxury cosmetics packaging. Integrated producers across Nordic fiber basins are capturing margin expansion where virgin grade concentration limits competitive entry. Stockholm-Uppsala logistics corridors are optimizing closed-loop collection infrastructure to support circularity claims under EU Green Deal packaging waste reduction targets.
Duplex Paper and Board Market Competitive Landscape
Integrated pulp-to-board operators and recycled fiber specialists split the market between margin-rich virgin grades and high-volume circular production. Nordic and Central European producers dominate premium folding boxboard through certified fiber streams, while Chinese coastal mills compete on recycled fiber throughput and emissions compliance speed. Three archetypes define competitive positioning: integrated virgin fiber producers with captive pulp supply, deinking-scale recycled fiber operators, and regional converters with hybrid sourcing flexibility. Capacity expansion and strategic partnerships represent the dominant competitive moves as mills respond to divergent national recycling infrastructure investments.
Within the integrated producer tier, Mondi Group exemplifies cost discipline through Central European pulp-to-board operations, while Stora Enso anchors Nordic premium positioning through certified virgin fiber concentration. Among recycled fiber specialists, Nine Dragons occupies a scale-driven position in coastal Chinese manufacturing clusters. Smurfit Kappa represents the converter-fabricator archetype with hybrid sourcing flexibility across European corrugated networks.
| Leading Market Players |
|---|
| Mondi Group |
| Sappi |
| International Paper |
| Oji Holdings Corporation |
| Nippon Paper Industries |
| WestRock |
| Stora Enso |
| Nine Dragons |
| Smurfit Kappa |
| Others |
Supply & Pricing Matrix
Pearl River Delta manufacturing clusters anchor global recycled fiber throughput, and their MEE compliance investments are transmitting cost pressure downstream to export-oriented electronics packaging buyers. Nordic integrated producers capture divergent pricing power through certified virgin fiber scarcity, while Indian domestic mills exploit BIS certification friction to command import substitution premiums.
Pricing Analysis
Aftermarket service revenue from packaging line optimization and print-finishing support drives lifetime value beyond commodity board transactions. Three-tier pricing structure across premium, standard, and economy levels separates certified folding boxboard with verified fiber provenance from uncoated grades serving e-commerce fulfillment. Cost compression in standard recycled grades is intensifying because Chinese coastal mills face wastewater treatment capital requirements. Third-party logistics providers in India exhibit acute price sensitivity on 300–400 gsm uncoated grades, while German cosmetics brands absorb minimal price pressure for high-brightness certified grades.
Supply Chain Analysis
Export-control regime angles around REACH chemical compliance and BIS certification mandates are restricting raw material flows and reshaping procurement geography. Supply concentrates in China, Finland, and India, with fiber sourcing drawing from old corrugated container streams, certified boreal softwood pulp, and agricultural residue respectively. Single-source vulnerability pervades premium folding boxboard grades tethered to Nordic integrated producers. Distribution runs through corrugated converting clusters in coastal Chinese manufacturing hubs and Mumbai-Delhi logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as digital print-finishing convergence and regulatory traceability mandates splinter buyer requirements into versioned niches. The collapse of minimum order quantities from lithographic plate economics toward inkjet-enabled short runs creates specialized supplier openings.
For Market Incumbents: Entrench defensive positioning through backward integration into captive pulp supply and deinking capacity expansion ahead of REACH reformulation deadlines. Mondi Group's Central European pulp-to-board model exemplifies cost discipline that insulates against recycled fiber input volatility. Certification investment in fluorine-free barrier coatings captures shelf space from competitors facing ECHA compliance delays. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated coated duplex segment above 350 gsm for pharmaceutical and luxury cosmetics packaging. Gujarat-based multi-ply former investments with online coating stations capture import substitution margins currently flowing to Nordic suppliers. A go-to-market angle anchored in BIS certification speed—compressing 90–120 day testing cycles through local laboratory partnerships—differentiates against procedural friction faced by foreign competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors deinking-scale recycled fiber operators with MEE compliance already achieved. Long-term viability across the analysis window rests on circularity infrastructure investments rather than virgin fiber concentration. Acquisition target archetype: coastal Chinese mills with upgraded wastewater treatment and biogas capture systems securing preferential supply contracts from export electronics buyers. The signal to watch as inflection indicator is consolidation velocity among smaller operators lacking balance sheet capacity for emissions compliance capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Deinking Capacity Expansion | REACH compliance timelines in Germany and the Netherlands accelerate closed-loop fiber collection infrastructure deployment. |
| Multi-Ply Former Investment | Gujarat manufacturing clusters capture pharmaceutical packaging margins above 350 gsm currently served by imports. |
| Digital Watermarking Integration | Rhineland converters qualify for premium tier pricing under EU AI Act supply chain traceability mandates. |
| Fluorine-Free Barrier Reformulation | EFSA migration limit compliance ahead of 2025 deadlines secures food-contact grade shelf positioning. |
| Closed-Loop Collection Infrastructure | Stockholm-Uppsala logistics corridors optimize circularity claims under EU Green Deal packaging waste targets. |
Research Methodology
Operator-level perspectives from mill operations directors, packaging converter procurement leads, brand owner sustainability officers, and third-party logistics category managers anchored the qualitative base. Primary interviews triangulated with customs and trade data, SEC filings from integrated producers, BIS certification registry records, and ECHA pre-registration databases. Bottom-up capacity assessments across Chinese coastal manufacturing clusters and Nordic fiber basins validated top-down demand modeling from e-commerce fulfillment and pharmaceutical packaging end-uses.
Scenario-bracketing around MEE compliance investment trajectories, REACH reformulation deadlines, and PLI scheme incentive capture framed the analytical envelope across the projection horizon. Segmentation dimensions modeled include product type tier, fiber grade certification level, end-use industry concentration, and regional regulatory cluster. CAGRs derived from fiber throughput elasticity to e-commerce parcel volume growth and pharmaceutical serialization compliance ramp rates.
Stress conditions across old corrugated container price volatility, BIS certification timeline extension, and Nordic fiber stream disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding circularity infrastructure investment pacing and brand owner post-consumer content mandate adoption. Material shifts in EU Green Deal packaging waste reduction target enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
North America Thermal Paper Market
Paper Products
Paper Pigment Market
Paper Products
Paper Based Laminates Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Household Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Organic Tissue Paper Market
Paper Products
Paper Doilies Market
Paper Products
Tissue Paper Market
Paper Products
Paper Products Market
Paper Products
Fluff Pulp Market
Paper Products
Heat Transfer Paper Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Compressed Fiberboard Market
Paper Products
Paper Machine Systems Market