
 Digital Light Processing Technology Market | 2026-2036
Digital Light Processing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Light Processing Technology Market Insights
4K resolution specification is reorganizing procurement priorities across commercial and consumer channels. Texas Instruments Incorporated leverages its semiconductor foundry depth to sustain DMD chip supply continuity for premium cinema installations. Barco anchors large-venue digital cinema through direct control over projector calibration and service networks. BenQ Corporation competes aggressively in home theater segments where price-performance positioning determines shelf placement.
Digital Light Processing Technology employs an array of microscopic mirrors mounted on a semiconductor chip to modulate light pixels, with mirror tilt angles typically switching thousands of times per second to create grayscale and color images through sequential color filtering or multi-chip architectures. Its primary commercial purpose centers on delivering high-brightness, high-contrast projection for environments where ambient light would degrade liquid crystal or liquid crystal on silicon alternatives. Three Chip technology dominates professional cinema and simulation installations where color fidelity requirements exclude single-chip cost compromises. Light Emitting Diode illumination represents the fastest-expanding technology segment as solid-state light sources displace lamp-based systems in education and corporate presentation verticals. Microprojectors occupy a mature volume tier with margin pools compressed by smartphone-integrated pico-projection alternatives.
FCC equipment authorization rules govern radio-frequency emissions from connected projection systems in the US market, while RoHS and REACH frameworks in Europe restrict hazardous substance content in semiconductor and optical component manufacturing. China's GB standards for display energy consumption, administered by SAMR, directly shape product qualification for public procurement tenders. India's BIS certification mandates for electronic goods create compliance gates for imported professional display equipment. Stakeholders must monitor divergence between regional efficiency mandates and the capital requirements for multi-standard product platform development.
Market Dynamics
LED illumination architectures are compressing lamp replacement revenue streams while MIIT's tightened GB standards force simultaneous efficiency and performance upgrades across commercial display portfolios.
Growth Catalysts
- Multiplex infrastructure mandates:India's cinema exhibition expansion corridor requires digital projection compliance for new screen licenses, pulling three-chip DLP installations into tier-2 and tier-3 cities.
- REACH substance restrictions:European RoHS and REACH frameworks on hazardous materials in semiconductor manufacturing are accelerating mercury-free solid-state illumination transitions in education and corporate verticals.
- Simulation fidelity requirements:Defense and aviation training centers specify color-accurate, high-refresh projection for immersive environments, locking in DLP's contrast advantages over liquid crystal alternatives.
Market Restraints
- DMD chip supply concentration:Foundry capacity for micro-mirror arrays remains concentrated among specialized semiconductor fabricators, creating vulnerability to geopolitical trade restrictions.
- Lamp aftermarket collapse:Solid-state illumination eliminates recurring consumable revenue, forcing projector OEMs to absorb service-margin compression or raise upfront hardware pricing.
- Smartphone-integrated pico-projection:MEMS-based laser scanning modules in mobile devices substitute for dedicated microprojector purchases in consumer and light commercial use cases.
Strategic Opportunities
- India's education technology procurement zones:State-level digital classroom initiatives specify interactive projection, creating volume demand for mid-brightness DLP configurations in government tenders.
- Laser phosphor convergence:Combining laser excitation with phosphor wheel architectures enables 20,000+ hour maintenance-free operation, opening museum and retail signage applications previously served by LCD video walls.
- China's dual carbon policy alignment:SAMR-administered energy-efficiency certifications for public procurement favor solid-state illuminated projectors with verified power consumption metrics.
Industry Challenges
- Calibration technician scarcity:Multi-chip alignment and color-matching protocols require specialized field engineers, with training pipelines failing to match installation growth in Asia-Pacific expansion markets.
- Legacy cinema server integration:New DLP cinema projectors must maintain backward compatibility with existing content distribution networks and key management infrastructure, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Light Processing Technology Market |
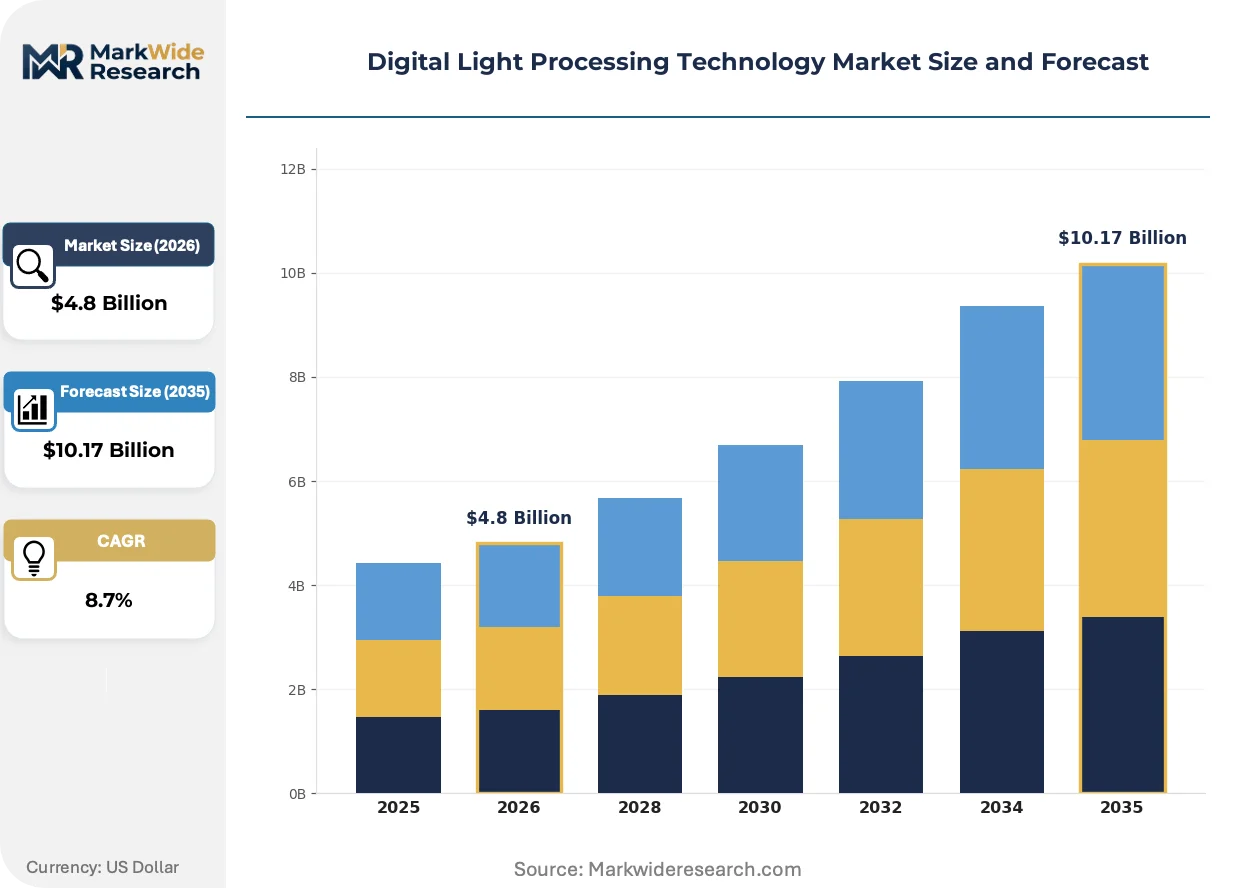
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprojectors, Digital Cinema, Home Theater, Professional Displays Application: Education, Entertainment, Corporate Presentation, Simulation End User: Broadcasting, Retail, Aerospace, Automotive Technology: Single Chip, Three Chip, Light Emitting Diode, Laser |
| Companies Covered | Texas Instruments Incorporated, Christie Digital Systems USA, Inc, Barco, BenQ Corporation, OSRAM Opto Semiconductors GmbH, Digital Projection, Optoma Corporation, ViewSonic Corporation, 3D Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Light Processing Technology Market Trends and Innovations
Illumination source diversification and procurement model restructuring are simultaneously compressing hardware margins and expanding addressable application spaces for projection technology vendors.
Laser phosphor architectures are fragmenting the traditional lamp-versus-LED binary in commercial projection. Museum and exhibition designers specify these hybrid sources for 30,000-hour lifespans without color degradation. The technology is fragmenting after-sales service revenue models by eliminating scheduled lamp replacement contracts.
China's MIIT has tightened GB standards for display energy consumption in commercial equipment. The regulations disqualify high-wattage lamp-based systems from public procurement tenders. Education and government verticals are responding with accelerated LED and laser phosphor refresh cycles to maintain bidding eligibility.
Buyers are unbundling installation and calibration services from hardware procurement. Corporate and education customers now source projectors through IT distributors while contracting independent AV integrators for deployment. This pattern is most visible in India's multiplex and digital classroom corridors where procurement authority has shifted from facilities management to technology procurement officers.
Digital Light Processing Technology Market Segmentation
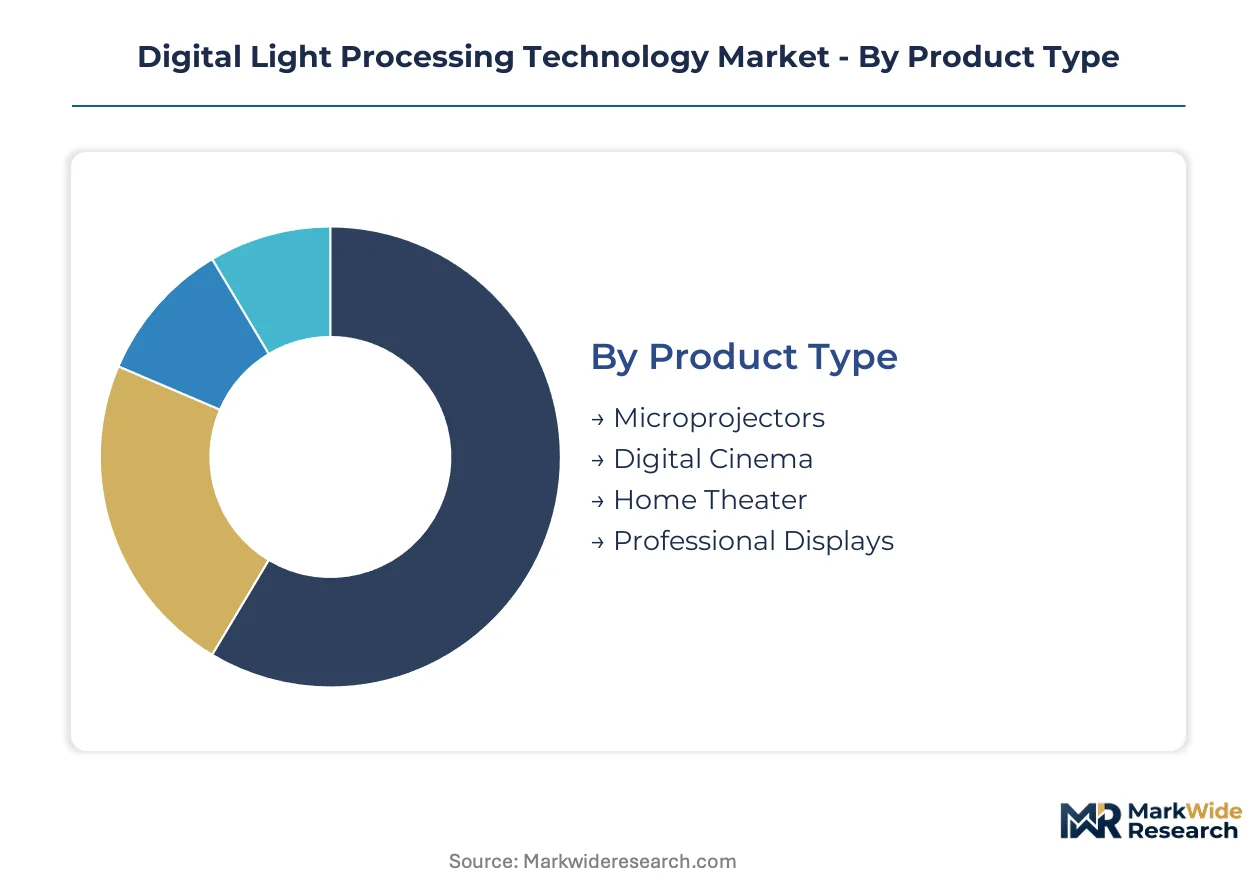
DLP technology fragments across distinct hardware configurations and use environments, with each segment demanding specialized mirror array architectures and illumination systems. Channel strategies diverge sharply between volume-driven education tenders and precision-calibrated cinema installations.
Product Type:
Microprojectors and home theater units flow through consumer electronics distributors, while digital cinema and professional displays route through specialized AV integrators with calibration capabilities.
- Microprojectors:Compact single-chip designs with LED illumination target mobile professionals and classroom portability requirements. Demand concentrates in India's state-level digital classroom procurement zones where interactive whiteboard integration is mandatory.
- Digital Cinema:Three-chip architectures with xenon or laser phosphor illumination deliver the color accuracy and brightness uniformity required for multiplex certification. China's cinema infrastructure upgrade wave and India's screen expansion corridor are pulling premium installations into tier-2 and tier-3 cities.
- Home Theater:Single-chip configurations with LED or laser light sources compete on lumen-per-dollar metrics in retail channels. BenQ and Optima dominate shelf placement through aggressive price-performance positioning.
- Professional Displays:High-brightness three-chip systems serve museum, control room, and large-venue applications where ambient light rejection is critical. Laser phosphor variants are displacing lamp-based units in European exhibition spaces under REACH substance restrictions.
By volume, microprojectors lead. By growth pace, digital cinema is ahead.
Application:
Cost tier stratification separates commodity education procurement from premium simulation contracts, with entertainment and corporate presentation occupying intermediate margin bands.
- Education:Mid-brightness single-chip projectors with 3,000-5,000 lumen output dominate government tender specifications. India's state digital classroom initiatives and China's GB energy-efficiency compliance requirements are accelerating LED refresh cycles.
- Entertainment:Cinema exhibition and live event projection demand the highest mirror array densities and thermal management precision. Asia-Pacific multiplex operators are upgrading projection infrastructure at accelerating rates to meet 4K resolution mandates.
- Corporate Presentation:Portable and installed conference room systems prioritize quick startup and network connectivity over color gamut breadth. Laser illumination is displacing lamp-based systems as total cost of ownership calculations favor solid-state maintenance profiles.
- Simulation:Defense and aviation training centers specify high-refresh-rate three-chip architectures with edge-blending capabilities for immersive dome environments. Color accuracy requirements lock in DLP's contrast advantages over liquid crystal alternatives.
Education commands unit volume. Simulation delivers margin concentration.
End User:
Customer type determines procurement authority structure, with broadcasting and aerospace demanding specification compliance while retail prioritizes total cost of ownership.
- Broadcasting:Reference-grade monitors and projection systems for color grading suites require calibrated D65 white point and extended color gamut coverage. Professional displays in this vertical route through broadcast equipment specialists rather than general IT distributors.
- Retail:Digital signage and window projection applications favor laser phosphor architectures for 20,000-hour maintenance-free operation. Museum and luxury retail designers in Europe specify these hybrid sources under RoHS mercury restrictions.
- Aerospace:Flight simulators and maintenance training systems demand high-refresh projection with motion platform synchronization. Defense procurement channels in the US specify ITAR-compliant supply chains for DMD chip sourcing.
- Automotive:Head-up display development and design studio applications utilize compact DLP modules for windshield projection and clay model visualization. OEM engineering centers specify units with automotive-grade thermal cycling tolerance.
Retail generates installation breadth. Aerospace commands specification stringency.
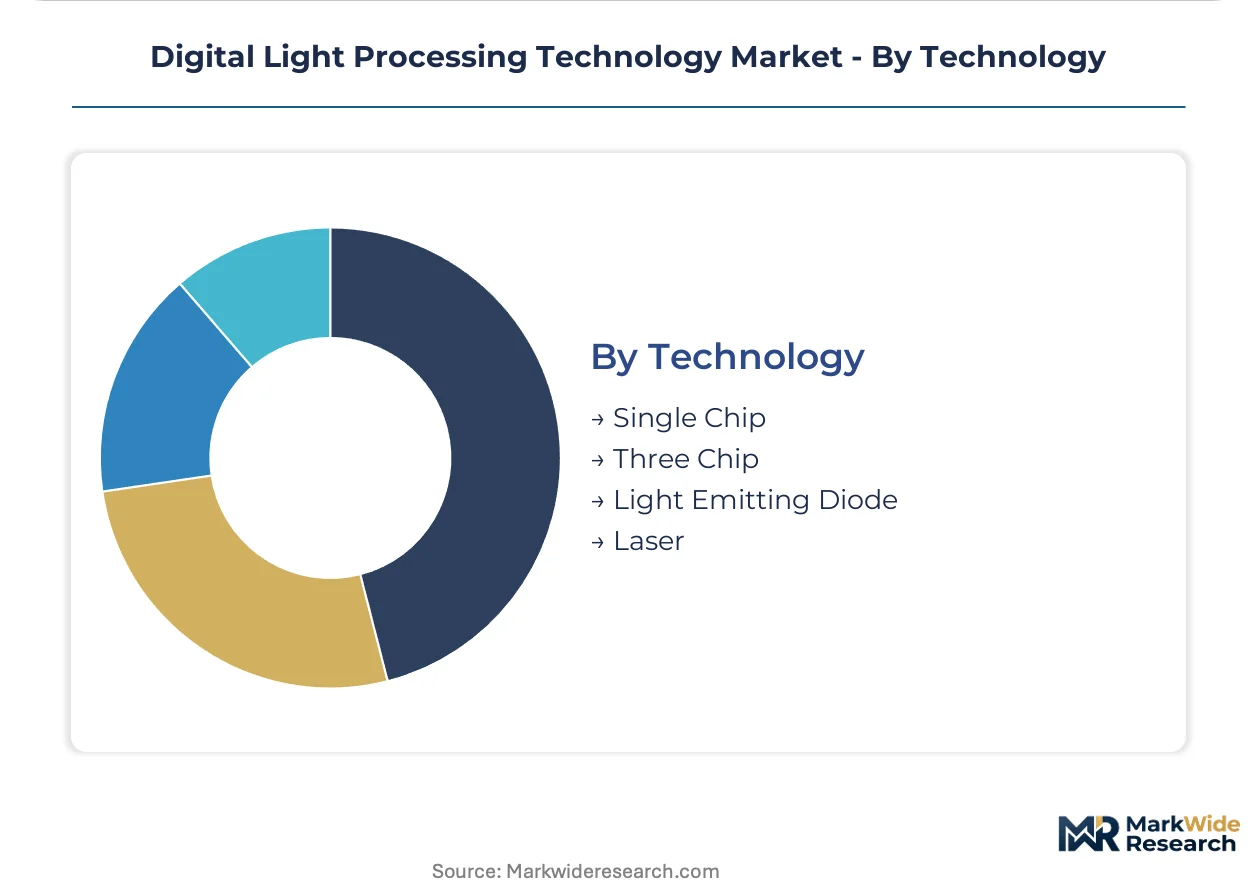
Technology:
Supply concentration for micro-mirror arrays and illumination subsystems creates divergent margin structures across chip architectures and light source categories.
- Single Chip:One DMD device with sequential color wheel or solid-state color sequencing delivers cost-optimized projection for price-sensitive volume markets. Education and home theater procurement favors this architecture for its hardware simplicity.
- Three Chip:Separate DMD arrays for red, green, and blue channels eliminate sequential color artifacts and deliver the color fidelity required for cinema and simulation. Foundry capacity for matched mirror arrays remains concentrated among specialized semiconductor fabricators.
- Light Emitting Diode:Solid-state illumination with 20,000-hour lifespans is displacing lamp-based systems in education and corporate verticals. China's MIIT tightened GB standards disqualify high-wattage lamp systems from public procurement tenders.
- Laser:Laser phosphor and direct RGB laser architectures enable 30,000-hour operation with sustained brightness and color stability. Museum and exhibition designers specify these sources for applications previously served by LCD video walls.
Single chip dominates unit economics. Laser illumination is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Instruments Incorporated's foundry network in the United States supplies DMD chips to projection OEMs worldwide, yet demand generation clusters in Asia-Pacific cinema corridors and European education procurement zones. Regulatory divergence across energy-efficiency mandates and substance restrictions is fragmenting product qualification requirements by geography.
China
MIIT's tightened GB standards for display energy consumption disqualify high-wattage lamp-based projectors from public procurement tenders. SAMR-administered certifications now favor solid-state illuminated units with verified power metrics. The Yangtze River Delta concentration of cinema exhibitors is upgrading projection infrastructure to meet 4K resolution mandates ahead of regulatory deadlines.
India
State-level digital classroom initiatives in Maharashtra and Karnataka specify interactive projection, creating volume demand for mid-brightness DLP configurations. BIS certification mandates for electronic goods create compliance gates for imported professional display equipment. The multiplex expansion corridor in tier-2 and tier-3 cities pulls three-chip installations beyond metropolitan centers.
United States
FCC equipment authorization rules govern radio-frequency emissions from connected projection systems in commercial and residential channels. Defense procurement channels specify ITAR-compliant supply chains for DMD chip sourcing in simulation applications. The Greater Boston cluster of defense and aviation training centers sustains demand for high-refresh-rate three-chip architectures.
Germany
ECHA REACH frameworks restrict hazardous substance content in semiconductor and optical component manufacturing, accelerating mercury-free solid-state illumination transitions. The Bavaria concentration of museum and exhibition designers specifies laser phosphor sources for 30,000-hour maintenance-free operation. German cinema operators face parallel pressure from EU energy-efficiency directives and RoHS substance restrictions.
Japan
METI standards for commercial display equipment efficiency shape product development priorities for domestic and export markets. The Kanto region's concentration of broadcast equipment specialists routes reference-grade projection systems through specialized channels rather than general IT distributors. Japanese automotive OEM engineering centers specify compact DLP modules with automotive-grade thermal cycling tolerance for head-up display development.
Digital Light Processing Technology Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the DLP projection value chain. The market structure concentrates around semiconductor foundry control of DMD arrays at the upstream tier, with downstream projector OEMs competing on illumination architecture selection and calibration service capabilities. Two strategic archetypes dominate: foundry-integrated chip suppliers with captive mirror array production, and brand-anchored system integrators with direct control over service networks. Competitive moves center on solid-state illumination portfolio transitions and geographic expansion into Asia-Pacific procurement corridors.
Within the foundry-integrated tier, Texas Instruments Incorporated anchors upstream supply continuity for premium cinema installations. Among European-headquartered system specialists, Barco occupies a position in large-venue digital cinema through direct control over projector calibration networks. BenQ Corporation exemplifies aggressive price-performance positioning in home theater segments where retail shelf placement determines volume capture. These three players represent divergent strategic vectors: upstream technology control, vertical service integration, and consumer channel scale.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Christie Digital Systems USA, Inc |
| Barco |
| BenQ Corporation |
| OSRAM Opto Semiconductors GmbH |
| Digital Projection |
| Optoma Corporation |
| ViewSonic Corporation |
| 3D Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Foundry-scale economies for micro-mirror arrays concentrate pricing power among specialized semiconductor fabricators, compressing margins for downstream projector OEMs while establishing hard price floors for three-chip cinema configurations. This upstream concentration interacts with solid-state illumination transitions to eliminate recurring lamp revenue streams, forcing hardware pricing adjustments across education and corporate verticals.
Pricing Analysis
China's MIIT tightened GB standards dictate the pricing tier structure across commercial projection segments. Three-tier pricing structure across premium cinema, standard education, and economy home theater levels separates installations by certification grade and after-sales bundling intensity. Price compression runs through mid-brightness education procurement as LED refresh cycles accelerate under energy-efficiency mandates. Government tender specifications in India demonstrate highest price sensitivity, while defense simulation contracts in the United States show lowest elasticity due to ITAR compliance requirements.
Supply Chain Analysis
Container availability fluctuations on the Asia-Pacific to North America trade lane create inbound logistics volatility for DMD chip shipments. Taiwan, South Korea, and the United States anchor micro-mirror array fabrication, while China and Japan concentrate LED and laser phosphor illumination subsystem production. The supply chain draws from rare-earth phosphor materials, precision optical glass, and semiconductor-grade silicon wafers. Single-source vulnerability for matched three-chip DMD arrays from Texas Instruments' foundry network concentrates geopolitical exposure. Distribution runs through specialized AV integrators for cinema and simulation segments, with IT distributors handling education and corporate volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as unbundled procurement patterns separate hardware purchasing from installation services, creating niche positions for independent calibration specialists and regional integrators across Asia-Pacific expansion corridors.
For Market Incumbents: Secure captive supply continuity for DMD arrays through foundry partnership extensions or backward integration into semiconductor fabrication capacity. Lock in service network density across India's tier-2 and tier-3 multiplex expansion corridor before independent AV integrators consolidate local relationships. Prioritize laser phosphor portfolio breadth to offset lamp aftermarket revenue collapse.
For New Entrants and Emerging Players: Anchor in India's state-level digital classroom procurement zones where BIS certification gates filter established import channels but local assembly partnerships unlock tender eligibility. Target mid-brightness single-chip configurations with interactive whiteboard integration as the most penetrable specification tier. Pursue government contractor status through regional manufacturing joint ventures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors illumination subsystem specialists with laser phosphor intellectual property portfolios over commoditized projector assembly operations. Long-term viability rests on solid-state transition completion and service revenue model reconstruction. Acquisition target archetype: regional AV integrators with calibration technician training pipelines in Asia-Pacific growth markets. Signal to watch: divergence between regional energy-efficiency mandate timelines and multi-standard product platform capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Phosphor Portfolio Transition | Eliminates mercury content for REACH compliance while extending maintenance intervals beyond 20,000 hours. |
| Regional Foundry Partnership | Diversifies DMD chip sourcing beyond single-supplier concentration for geopolitical risk mitigation. |
| Calibration Service Network Expansion | Captures recurring revenue as hardware margins compress under solid-state illumination transitions. |
| Public Procurement Certification Investment | Unlocks India's state digital classroom tenders and China's SAMR-administered energy-efficiency bids. |
| Backward Integration into LED Subsystems | Reduces illumination component cost exposure while securing supply continuity for high-volume education contracts. |
Research Methodology
Operator-level perspectives from cinema exhibition procurement officers, AV integration technical directors, semiconductor foundry operations managers, and education technology procurement coordinators anchored the qualitative base. Primary interview data combined with secondary validation from SEC 10-K filings, MIIT GB standard publications, BIS certification registries, and ECHA REACH substance restriction databases. Bottom-up volume triangulation across product type and application segments converged with top-down market sizing from illumination subsystem shipment data.
Sensitivity analysis frameworks tested projection demand elasticity against regulatory timeline acceleration and solid-state illumination cost curves across the analysis window. Segmentation dimensions modeled include chip architecture category, illumination source type, end-use vertical, and regional procurement authority structure. CAGRs derived from installed base replacement cycles and new infrastructure mandates in cinema and education corridors. Industry-specific forecast inputs incorporated multiplex screen licensing requirements and state-level digital classroom budget allocations.
Material uncertainties — geopolitical trade restriction expansion, foundry capacity allocation shifts, and divergence between regional energy-efficiency enforcement timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions about solid-state illumination adoption velocity and technician training pipeline scaling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Softbox Lighting Kit Market
Lighting
Vintage Bulb Market
Lighting
Directional Luminaire Market
Lighting
COB Photo Light Market
Lighting
Solar Column Headlight Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Global Stadium Lighting Market
Lighting
Xenon Headlights Market
Lighting
Tritium Light Source Market
Lighting
Smart Lights Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
Programmable Stage Lighting Market
Lighting
Plasma Lighting Market
Lighting
Germany Indoor LED Lighting Market
Lighting
UAE Smart Lighting Market