
 Smart Meters Chipset Market | 2026-2036
Smart Meters Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Meters Chipset Market Insights
The capital-intensity divergence between foundry-dependent fabless designers and integrated device manufacturers is collapsing as wafer costs normalize and foundry capacity expands. Landis+Gyr Group AG leverages its vertically integrated European manufacturing to control chipset quality for advanced metering infrastructure. Itron Inc. sustains R&D intensity across communication module architectures, while Siemens AG anchors its position through dominance in industrial-grade power management ICs for utility-scale deployments.
A smart meters chipset comprises integrated circuits including microcontrollers, power management ICs, communication modules, and sensor chips engineered to measure, process, and transmit consumption data across electricity, water, and gas infrastructure. These chipsets typically operate within sub-1 GHz to 2.4 GHz frequency bands with power budgets under 500 milliwatts to ensure decade-long battery life in remote meter nodes. Communication modules represent the fastest-expanding segment as utilities migrate from proprietary RF mesh to standardized NB-IoT and LoRa protocols for wide-area coverage. Microcontrollers retain the deepest margin pools due to firmware customization requirements and long-term supply contracts with meter OEMs.
The EU Green Deal and F-Gas Regulation shape European demand by mandating interoperable, low-carbon metering systems, while the FCC in the United States governs spectrum allocation for unlicensed Zigbee and LoRa deployments in residential AMI networks. India's CEA and BIS enforce local content and testing standards that condition market access for imported chipsets. Stakeholders must monitor evolving cybersecurity certification requirements across jurisdictions as grid-edge connectivity expands attack surfaces for critical infrastructure.
Market Dynamics
NB-IoT and LoRa protocol standardization is collapsing the installed base of proprietary RF mesh systems, forcing chipset vendors to re-architect communication modules around licensed and unlicensed wide-area specifications. This protocol migration redistributes margin pools from meter OEMs with captive RF stacks to semiconductor firms with cellular-certified silicon portfolios.
Growth Catalysts
- EU Green Deal mandates:The F-Gas Regulation and energy efficiency directives compel utilities across Germany, France, and Italy to replace legacy electromechanical meters with interoperable smart systems requiring certified chipsets.
- India's AMI scale-up:The CEA's metering standards and BIS certification requirements create captive demand for locally tested power management ICs and microcontrollers in state-led distribution company tenders.
- China's dual carbon goals:Grid modernization investments under MIIT guidance accelerate deployment of integrated metering chipsets with embedded powerline communication for residential and industrial monitoring nodes.
Market Restraints
- Wafer cost volatility:Foundry capacity constraints for 40nm and 28nm process nodes create input cost instability for fabless chipset designers serving utility procurement cycles.
- Supply concentration in East Asian packaging:Advanced flip-chip and system-in-package capabilities cluster in Taiwan and South Korea, exposing meter OEMs to single-source risks for industrial-grade communication modules.
- Certification timeline friction:Multi-jurisdictional cybersecurity certifications under IEC 62056 and national grid codes extend product qualification periods beyond typical semiconductor release cycles.
Strategic Opportunities
- Water and gas metering expansion:Battery-operated ultrasonic flow sensors with sub-1 GHz connectivity open addressable markets beyond electricity AMI in Japan and South Korea.
- Edge AI integration:Convergence of low-power neural accelerators with metering microcontrollers enables on-device anomaly detection for theft prevention and predictive maintenance.
- India's PLI scheme:Production-linked incentives for electronics manufacturing attract captive semiconductor testing and packaging investments to serve domestic meter OEMs.
Industry Challenges
- Firmware security engineering gap:Shortage of embedded systems specialists with grid-edge cybersecurity expertise delays secure boot and over-the-air update implementations.
- Legacy AMI integration complexity:Backward compatibility requirements with 15-20 year installed bases of proprietary RF mesh systems fragment R&D roadmaps for communication module vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Meters Chipset Market |
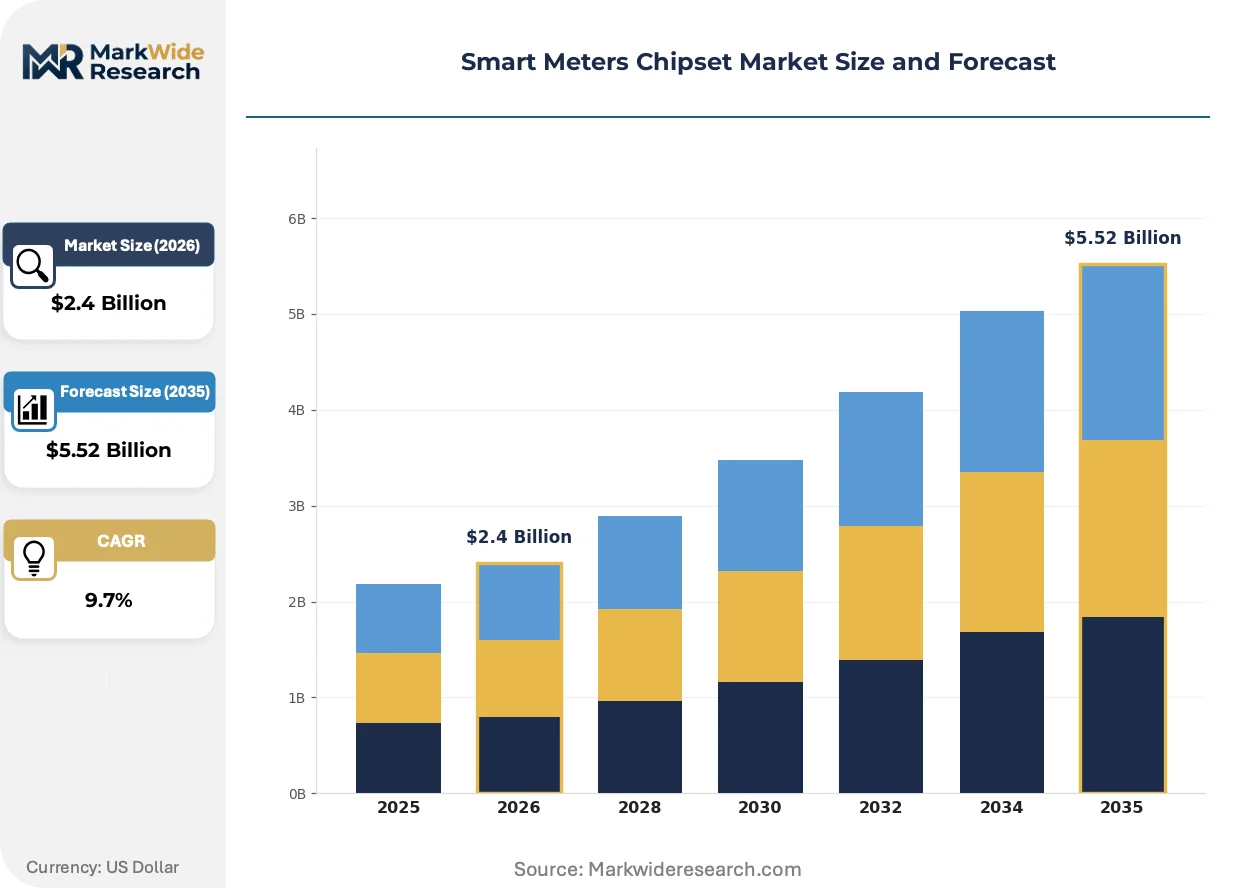
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Microcontrollers, Power Management ICs, Communication Modules, Sensor Chips Technology Type: Zigbee, LoRa, NB-IoT, Cellular End User Type: Utilities, Residential Consumers, Commercial Establishments, Industrial Users Application Type: Energy Monitoring, Water Management, Gas Consumption, Smart Grid |
| Companies Covered | Landis+Gyr Group AG, Itron Inc., Sagemcom, OSAKI ELECTRIC CO., LTD. (EDMI), Siemens AG, Honeywell International Inc., Schneider Electric, Xylem Inc., ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Meters Chipset Market Trends and Innovations
Silicon architectures are converging around system-on-chip designs that collapse metering, communication, and power management functions into single-die solutions. This integration pressure favors IDMs with captive analog expertise over pure-play digital designers.
Dual-band RF transceivers supporting both sub-1 GHz mesh and 2.4 GHz star topologies are displacing single-protocol chipsets in next-generation meter designs. European utilities in Denmark and the Netherlands specify these flexible architectures to hedge against protocol obsolescence. The displacement compresses SKU diversity for chipset vendors while raising firmware customization requirements.
The EU AI Act and accompanying cybersecurity certification frameworks under EN 303 645 impose mandatory risk management systems on connected metering infrastructure. Chipset vendors must embed hardware security modules and attestation capabilities at the silicon level. Industrial-grade deployments in Germany and Austria face the steepest compliance ramps, with TÜV and DEKRA certification timelines extending 18-24 months.
Aggregated procurement consortia among municipal utilities are consolidating vendor selection power and unbundling after-sales service from hardware supply contracts. French and Spanish distribution cooperatives now source chipsets through centralized technical specifications rather than OEM-mediated channels. This disintermediation exposes semiconductor margins to direct price negotiation with buying committees.
Smart Meters Chipset Market Segmentation
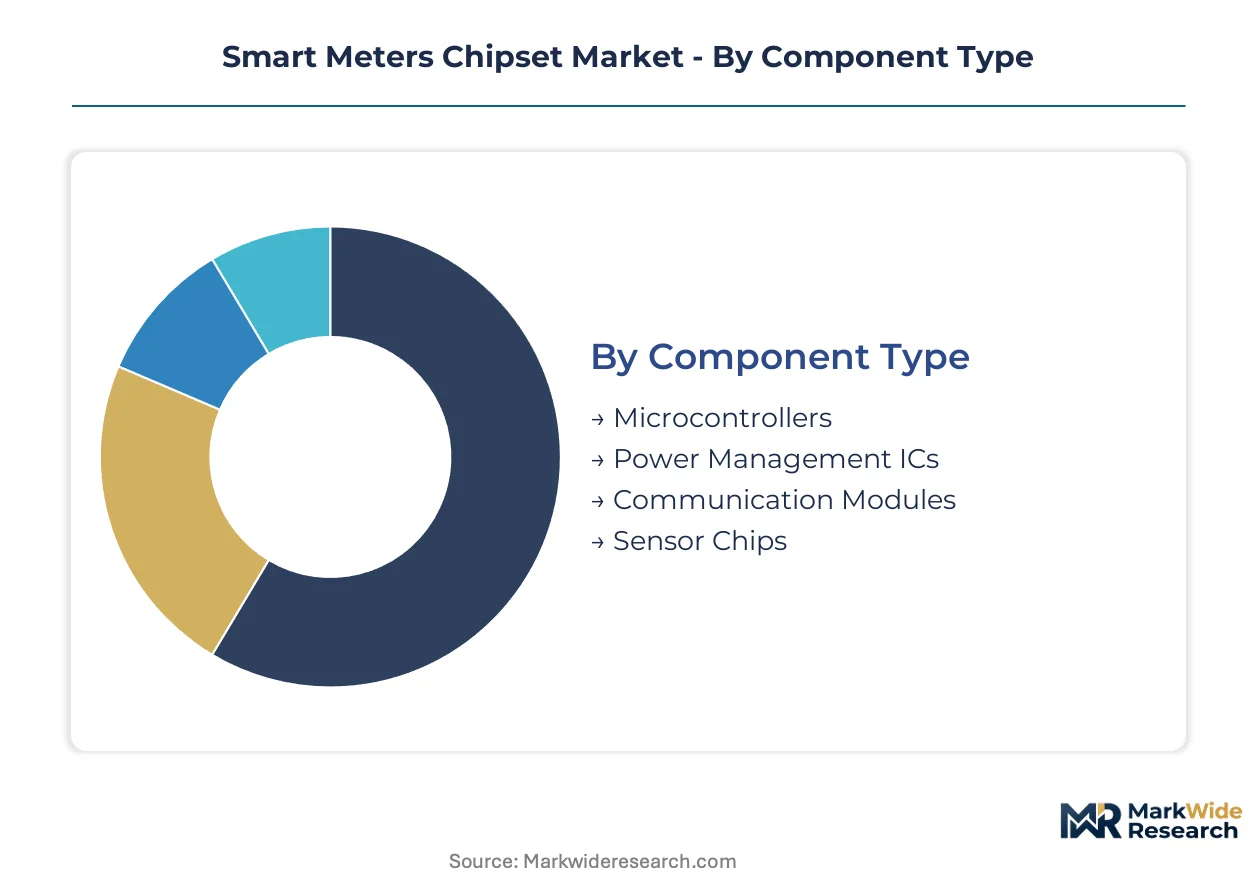
Smart meters chipset procurement patterns fragment across four distinct axes. Component specialization determines foundry relationships and margin capture. Technology choices lock utilities into decade-long protocol commitments with diverging upgrade economics.
Component Type:
Microcontrollers command the deepest margin pools due to firmware customization requirements and long-term supply contracts with meter OEMs.
- Microcontrollers:These integrated circuits execute metering algorithms, protocol stacks, and security functions within sub-500 milliwatt power envelopes. German and Austrian utilities specify IEC 62056-compliant microcontrollers with hardware security modules, extending TÜV certification timelines to 24 months.
- Communication Modules:RF transceivers and baseband processors enable data transmission across sub-1 GHz mesh and 2.4 GHz star topologies. China's MIIT-guided grid modernization accelerates demand for integrated powerline communication chipsets in residential and industrial monitoring nodes.
- Power Management ICs:Voltage regulators and energy harvesting circuits ensure decade-long battery life in remote gas and water meters.
- Sensor Chips:Analog front-ends convert physical consumption measurements into digital signals for processing.
Microcontrollers hold installed capacity. Communication modules are rotating up the share rankings.
Technology Type:
Protocol migration from proprietary RF mesh to standardized wide-area specifications is redistributing margin pools toward cellular-certified silicon portfolios.
- NB-IoT:Licensed narrowband cellular technology delivers deep indoor penetration and operator-managed quality of service. India's CEA metering standards and BIS certification requirements create captive demand for NB-IoT chipsets in state-led distribution company tenders.
- LoRa:Unlicensed chirp spread spectrum protocol enables utility-owned network deployments with lower recurring costs. French and Spanish distribution cooperatives specify LoRa chipsets through centralized technical specifications rather than OEM-mediated channels.
- Zigbee:Mesh networking standard dominates legacy residential AMI deployments in the United States under FCC spectrum allocations.
- Cellular:4G LTE and emerging 5G RedCap chipsets address high-bandwidth industrial metering and real-time grid control applications.
LoRa and NB-IoT are climbing the fastest as utilities abandon proprietary RF mesh systems. Zigbee retains legacy footprint.
End User Type:
Procurement authority concentrates with utilities, though commercial and industrial segments demand higher-performance chipsets with extended temperature ranges.
- Utilities:State-owned and municipal distribution companies drive volume procurement through multi-year AMI tenders. Aggregated procurement consortia in France and Spain now unbundle after-sales service from hardware supply contracts, exposing semiconductor margins to direct price negotiation.
- Industrial Users:Manufacturing facilities and data centers require chipsets with sub-second latency for demand response integration.
- Commercial Establishments:Office buildings and retail chains deploy sub-metering chipsets for tenant billing and energy management.
- Residential Consumers:Individual homeowners represent minimal direct chipset demand, accessing smart metering through utility-managed deployments.
Utilities dominate volume procurement. Industrial users are rotating up the share rankings on performance premium capture.
Application Type:
Water and gas metering applications are opening addressable markets beyond electricity AMI with distinct battery life and environmental sealing requirements.
- Energy Monitoring:Electricity metering chipsets integrate power measurement, theft detection, and tariff management functions. EU Green Deal mandates and F-Gas Regulation compel German, French, and Italian utilities to replace legacy electromechanical meters with interoperable smart systems requiring certified chipsets.
- Water Management:Battery-operated ultrasonic flow sensors with sub-1 GHz connectivity address non-revenue water reduction in Japan and South Korea.
- Gas Consumption:Intrinsically safe chipsets operate in explosive atmospheres with strict ATEX and IECEx certification requirements.
- Smart Grid:Distribution automation and grid-edge control demand chipsets with deterministic latency and cybersecurity hardening.
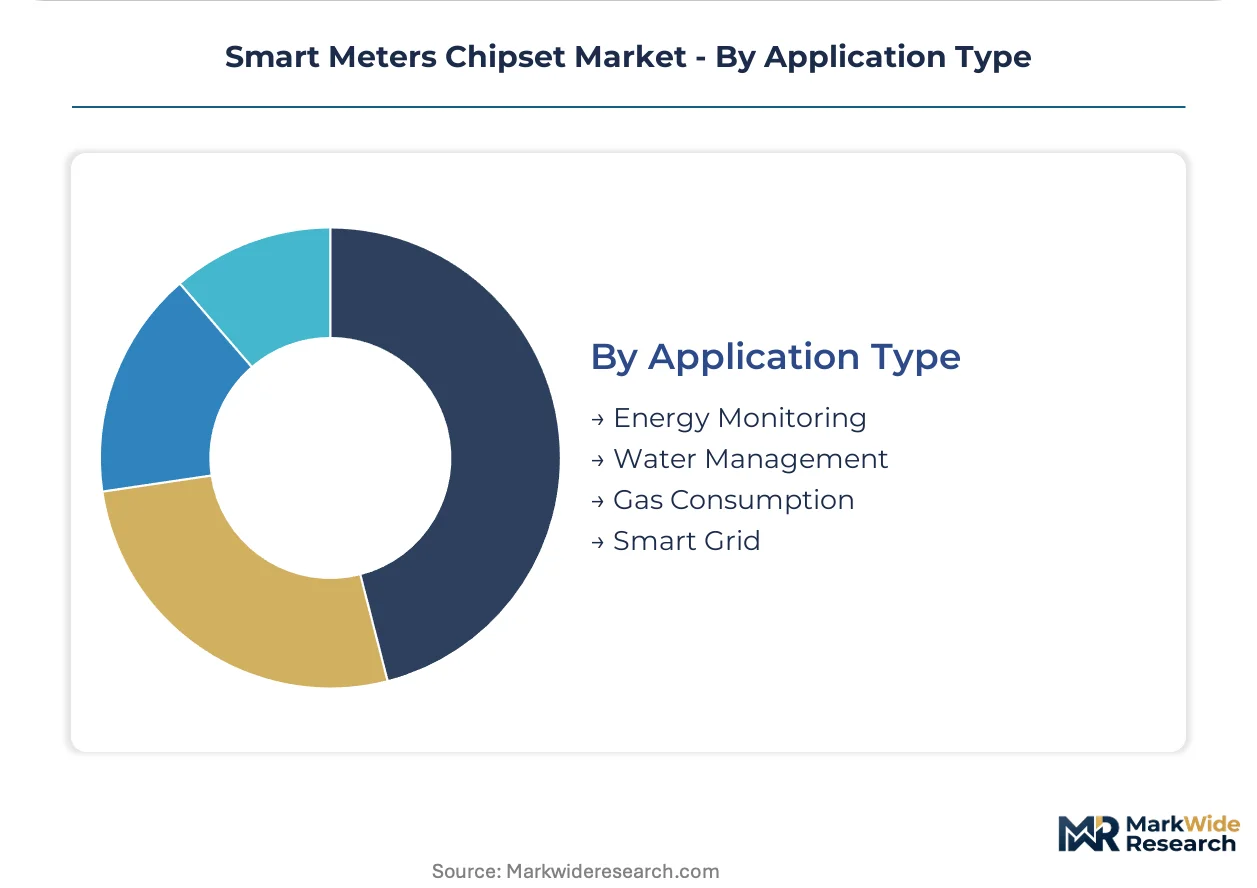
Energy monitoring holds installed capacity. Water management is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through state-coordinated procurement volumes, while European utilities absorb premium certification costs for cybersecurity-hardened chipsets. This asymmetry fragments margin capture across geographies.
China
MIIT-guided grid modernization accelerates deployment of integrated metering chipsets with embedded powerline communication. The dual carbon goals mandate residential and industrial monitoring node expansion. Yangtze River Delta clusters in Shanghai and Jiangsu province concentrate domestic chipset design houses serving state-owned distribution companies.
India
State-led distribution company tenders create captive demand for NB-IoT chipsets and locally tested power management ICs. CEA metering standards and BIS certification requirements condition market access for imported semiconductors. Manufacturing investments under the PLI scheme cluster in Gujarat and Karnataka to serve domestic meter OEMs.
Germany
EU Green Deal mandates and F-Gas Regulation compel utilities to replace legacy electromechanical meters with interoperable smart systems. TÜV and DEKRA certification timelines extend 18-24 months for industrial-grade deployments. Bavaria and North Rhine-Westphalia anchor European demand through municipal utility consortia specifying hardware security modules.
United States
FCC spectrum allocation governs unlicensed Zigbee and LoRa deployments in residential AMI networks. Utility procurement concentrates with investor-owned distribution companies in Texas and California. Greater Boston and Silicon Valley clusters host communication module vendors serving North American meter OEMs.
Japan
METI efficiency standards drive battery-operated ultrasonic flow sensor deployment for non-revenue water reduction. Sub-1 GHz connectivity chipsets address gas and water metering applications with decade-long battery life requirements. Kansai region manufacturers in Osaka prefecture specialize in industrial-grade sensor chip packaging.
Smart Meters Chipset Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated device manufacturers controlling analog expertise while fabless designers compete on protocol flexibility. The vendor base organizes into three tiers: vertically integrated European industrial conglomerates, communication-focused technology specialists, and Asian component-scale suppliers. Dominant competitive moves include strategic partnerships for cellular certification and geographic expansion through local content compliance in India and China.
Within the integrated industrial tier, Landis+Gyr Group AG and Siemens AG exemplify archetypes combining captive manufacturing with utility-scale deployment experience. Itron Inc. occupies a position representing communication module specialization. These three anchors illustrate how European-origin players leverage certification depth against Asian competitors competing on volume scale.
| Leading Market Players |
|---|
| Landis+Gyr Group AG |
| Itron Inc. |
| Sagemcom |
| OSAKI ELECTRIC CO., LTD. (EDMI) |
| Siemens AG |
| Honeywell International Inc. |
| Schneider Electric |
| Xylem Inc. |
| ABB |
| Others |
Pricing and Supply Chain Analysis
Wafer-scale economies at 40nm and 28nm process nodes concentrate margin capture among integrated device manufacturers with captive analog expertise, compressing price floors for fabless competitors while amplifying procurement leverage for utility-scale buyers. This scale asymmetry redistributes value toward foundry-integrated players capable of decade-long supply commitments.
Pricing Analysis
The customization-premium spread between configured-to-order firmware and standard-catalog microcontrollers spans three performance tiers: IEC 62056-certified industrial grade, utility-standard commercial grade, and price-sensitive residential grade. Certification depth under TÜV and DEKRA protocols drives differentiation, with hardware security module integration commanding substantial premiums. Pricing pressure stems from aggregated procurement consortia in France and Spain unbundling after-sales service from hardware contracts. State-owned utilities in China and India exhibit highest price sensitivity, while German municipal consortia absorb premium certification costs.
Supply Chain Analysis
Inventory buffers for communication modules stretch 18-24 months due to multi-jurisdictional cybersecurity certification timelines under IEC 62056 and national grid codes. Taiwan and South Korea anchor advanced flip-chip and system-in-package capabilities, while China concentrates powerline communication chipset production. Silicon feedstock and rare-earth magnet materials for sensor calibration draw from concentrated extraction bases. Single-source vulnerability in East Asian packaging exposes meter OEMs to disruption. Distribution runs through OEM-mediated channels, though French and Spanish cooperatives increasingly source direct.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of embedded systems engineers with grid-edge cybersecurity expertise constrains firmware development velocity, creating defensive moats for incumbents with established secure-boot implementations while raising barriers for new entrants lacking certification track records.
For Market Incumbents: Shield market position by deepening backward integration into power management IC design and expanding captive testing capacity in India under PLI scheme incentives. Prioritize hardware security module pre-certification with TÜV and DEKRA to compress 24-month qualification windows. Consolidate protocol flexibility through dual-band RF transceiver architectures that hedge against LoRa and NB-IoT standard shifts. For New Entrants and Emerging Players: Firmware security engineering services represent the most exploitable service-layer gap, as incumbent IDMs under-invest in customer-specific secure boot customization. Target water and gas metering segments in Japan and South Korea where ultrasonic flow sensor integration demands outstrip established supply. Pursue white-label communication module partnerships with Indian meter OEMs facing CEA localization mandates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among communication module specialists with cellular-certified silicon portfolios and long-term utility supply contracts. Long-term viability centers on protocol-agnostic RF architectures capable of spanning 15-20 year AMI upgrade cycles. Acquisition focus should target fabless designers with NB-IoT certification depth and established BIS testing relationships in India. Monitor India's PLI scheme disbursement velocity as inflection signal for domestic manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Cellular Certification Investment | NB-IoT and 5G RedCap certification with DEKRA accelerates utility procurement timelines in Germany. |
| Backward Integration into Analog Design | In-house power management IC development captures margin pools from external foundry arrangements. |
| Edge AI Accelerator Integration | Low-power neural engine embedding enables on-device theft detection for predictive maintenance revenue. |
| Geographic Expansion via Local Content | PLI-compliant testing investments in Gujarat secure access to India's state-led distribution tenders. |
| Protocol Flexibility Architecture | Dual-band sub-1 GHz and 2.4 GHz transceivers hedge against LoRa and NB-IoT obsolescence risk. |
Research Methodology
Cross-validation between primary interviews with utility procurement officers, semiconductor R&D directors, and meter OEM supply chain managers and secondary sources including MIIT grid modernization disclosures, CEA metering standards filings, and EU Green Deal implementation reports anchors the qualitative findings. SEC 10-K filings from listed industrial conglomerates and customs trade data for semiconductor imports into India and China provide volume triangulation. Bottom-up segment sizing and top-down macro validation converge on market estimates.
Sensitivity analysis across wafer cost assumptions, certification timeline scenarios, and protocol adoption curves shapes the analytical framework over the projection horizon. Component type, technology protocol, end user procurement authority, and application segment constitute the segmentation dimensions modeled. CAGRs derive from utility AMI deployment schedules, regulatory mandate enforcement intensity, and semiconductor foundry capacity expansion plans. Grid-edge connectivity penetration and cybersecurity certification backlog serve as industry-specific demand drivers.
Forecasts assume regulatory continuity in EU Green Deal implementation, India's PLI scheme structure, and China's dual carbon goal enforcement; material policy shifts would require re-modeling. Supply concentration risk in Taiwan packaging and rare-earth magnet sourcing could revise volume assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Microserver Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
IoT Processor Market