
 Global Smartcard MCU Market | 2026-2036
Global Smartcard MCU Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smartcard MCU Market Foresight
EAL5+ and Common Criteria certification tiers is redrawing procurement standards across the Global Smartcard MCU Market. Infineon Technologies leverages captive fabrication capacity in Germany to sustain high-assurance chip output. NXP Semiconductors dominates near-field communication integration for transit credentialing. STMicroelectronics specializes in dual-interface architectures that bridge legacy contact infrastructure with contactless upgrades.
A smartcard MCU integrates a secure processor core, cryptographic accelerators, tamper-resistant memory, and RF analog front-ends within a single die to execute authenticated transactions and protected data storage. These devices operate at clock speeds from 1 MHz to 50 MHz with embedded flash densities reaching 1 MB, purpose-built for EMV payment protocols, government e-ID frameworks, and transit fare collection. Contactless device types are capturing the fastest expansion as tap-to-pay displaces magnetic-stripe and contact-dip methods across retail point-of-sale terminals. Thirty-two-bit architecture segments are pulling margin pools upward as biometric payment cards and digital identity wallets demand greater computational throughput. Banking applications retain the largest revenue footprint, though transportation credentials are narrowing the gap through city-scale automated fare collection deployments.
Common Criteria certification administered by BSI in Germany and ANSSI in France gates market access for government-issued e-ID and payment products. ETSI standards harmonized under EU regulatory frameworks mandate interoperability thresholds that constrain non-compliant suppliers. EMVCo specifications maintained by Visa, Mastercard, JCB, and American Express dictate physical and electrical interface requirements that shape R&D allocation across the value chain. Stakeholders must monitor how post-quantum cryptography migration timelines will force silicon redesign cycles and foundry qualification schedules.
Market Dynamics
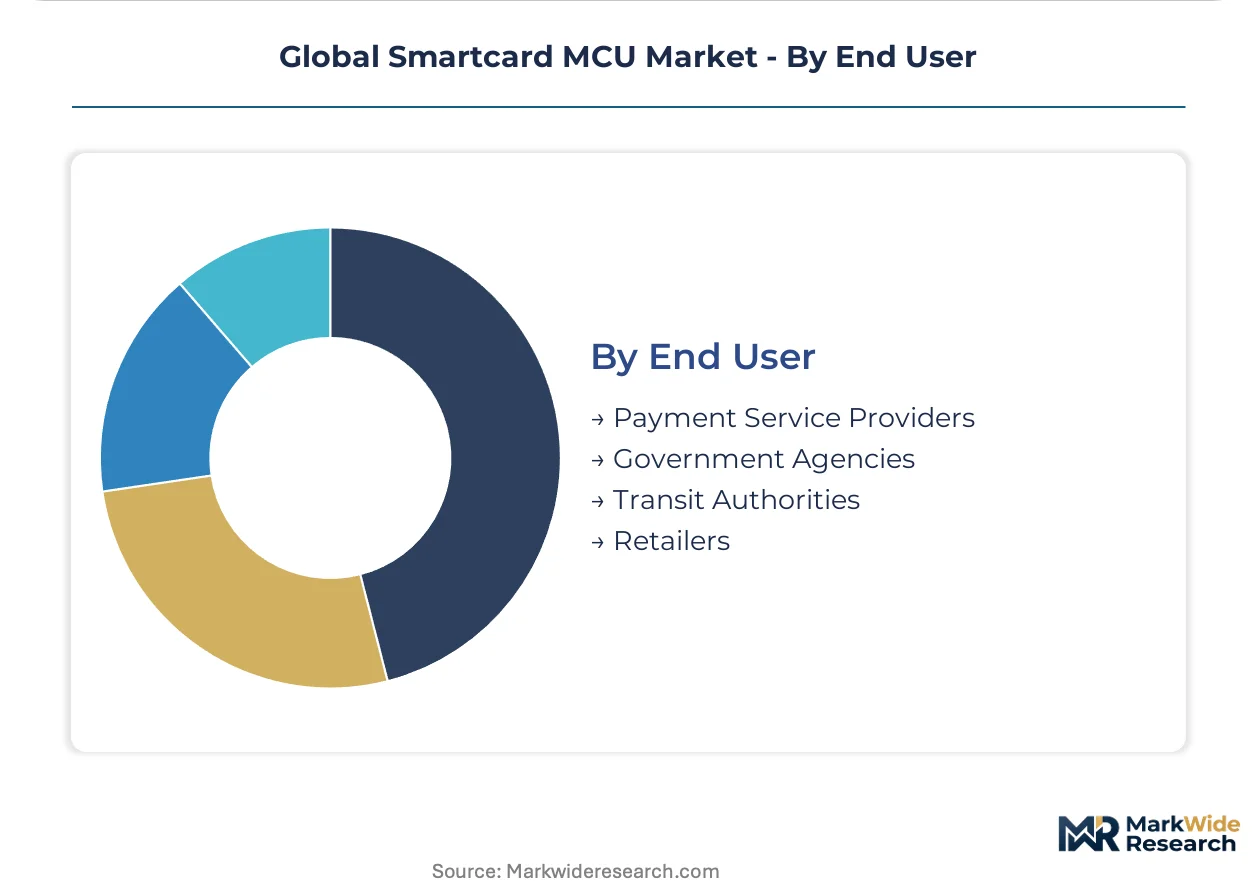
Post-quantum cryptography migration timelines are compressing silicon redesign cycles across the Global Smartcard MCU Market, forcing foundry requalification schedules and accelerating R&D allocation toward quantum-resistant cryptographic accelerators.
Growth Catalysts
- EMVCo specification expansion:Visa, Mastercard, JCB, and American Express interface mandates are driving contactless terminal infrastructure buildouts across retail banking networks, pulling secure element demand upward.
- China UnionPay domestic scaling:Secure element deployment across China's payment rails is concentrating volume demand for dual-interface architectures.
- Biometric payment card emergence:Fingerprint sensor integration into payment credentials is expanding 32-bit MCU computational requirements and memory density specifications.
Market Restraints
- Foundry concentration risk:High-assurance fabrication capacity concentrates in Germany and France, constraining supply elasticity for EAL5+ certified devices.
- Common Criteria certification friction:BSI and ANSSI evaluation timelines extend 12-18 months, gating market entry for new government e-ID suppliers.
- Silicon input cost volatility:300mm wafer supply constraints and specialty packaging material shortages are pressuring gross margins at the die level.
Strategic Opportunities
- India digital identity expansion:Aadhaar-linked payment credentialing and the RBI's tokenization mandates are opening volume deployment channels for domestic and foreign MCU suppliers.
- Transit credentialing convergence:City-scale automated fare collection in São Paulo, London, and Singapore is narrowing the revenue gap with banking applications.
- Post-quantum algorithm standardization:NIST's finalization of lattice-based cryptography standards is creating first-mover advantage windows for quantum-resistant secure element redesigns.
Industry Challenges
- Cryptographic engineering talent scarcity:Side-channel attack resistance design and formal verification expertise pools concentrate at a handful of European and East Asian institutions.
- Dual-interface integration complexity:Bridging legacy contact infrastructure with contactless RF front-ends requires analog-digital co-design capabilities that strain mid-tier engineering teams.
- EMVCo compliance timeline compression:Specification revision cycles are accelerating faster than typical 24-month product qualification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smartcard MCU Market |
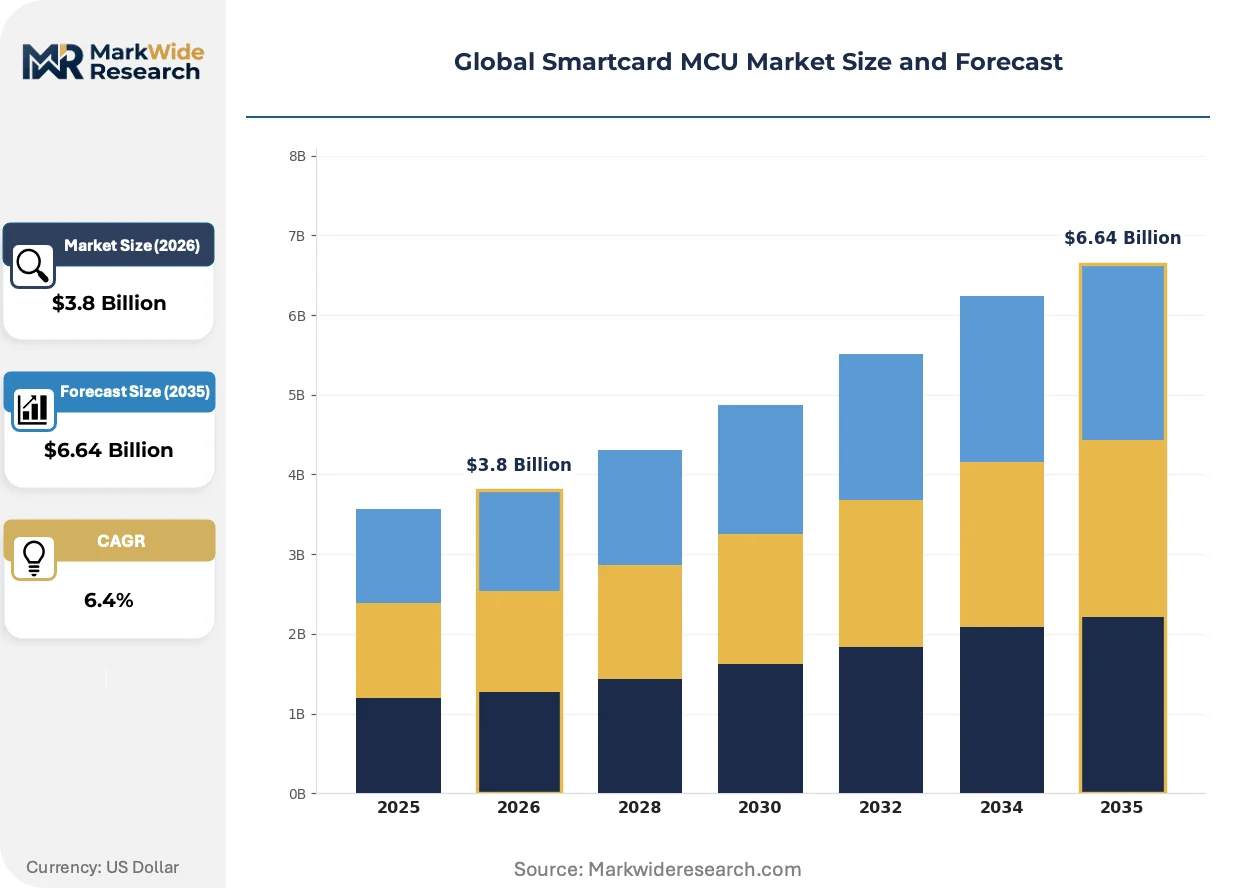
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Contact, Contactless, Dual Interface, Secure Element Embedded Application: Banking, Identification, Transportation, Loyalty Programs, Access Control Technology: 8-bit Architecture, 16-bit Architecture, 32-bit Architecture, Near Field Communication End User: Payment Service Providers, Government Agencies, Transit Authorities, Retailers |
| Companies Covered | NXP Semiconductors, Infineon Technologies, STMicroelectronics, Renesas Electronics Corporation, Microchip Technology, Samsung Electronics, Giesecke+Devrient, IDEMIA, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smartcard MCU Market Shifts & Advancements
Secure element architectures are fragmenting into discrete functional blocks as biometric authentication, quantum-resistant cryptography, and multi-application hosting demands diverge from legacy monolithic designs.
Hardware security modules are decomposing into discrete cryptographic accelerators, tamper-resistant memory controllers, and RF analog front-ends that vendors can mix across process nodes. Transit authorities in Singapore and London are adopting this modular approach to upgrade contactless interfaces without full silicon respins. The decomposition is compressing product development cycles from 36 months toward 18-month refresh intervals.
France's ANSSI and Germany's BSI are tightening Common Criteria evaluation depth for biometric payment cards, extending certification timelines and raising documentation burdens. This regulatory stringency is favoring incumbent suppliers with established evaluation track records. Government e-ID frameworks in the EU are responding by consolidating procurement around pre-certified platform architectures.
Banking credential procurement is fragmenting between chip-issuing banks, payment network operators, and fintech wallet providers, each demanding customized secure element configurations. Tier-1 issuers in the United States and United Kingdom are unbundling hardware procurement from personalization services, compressing supplier margins. This disintermediation is most visible in North American markets where digital wallet tokenization is displacing physical card-centric sourcing models.
Global Smartcard MCU Market Segmentation
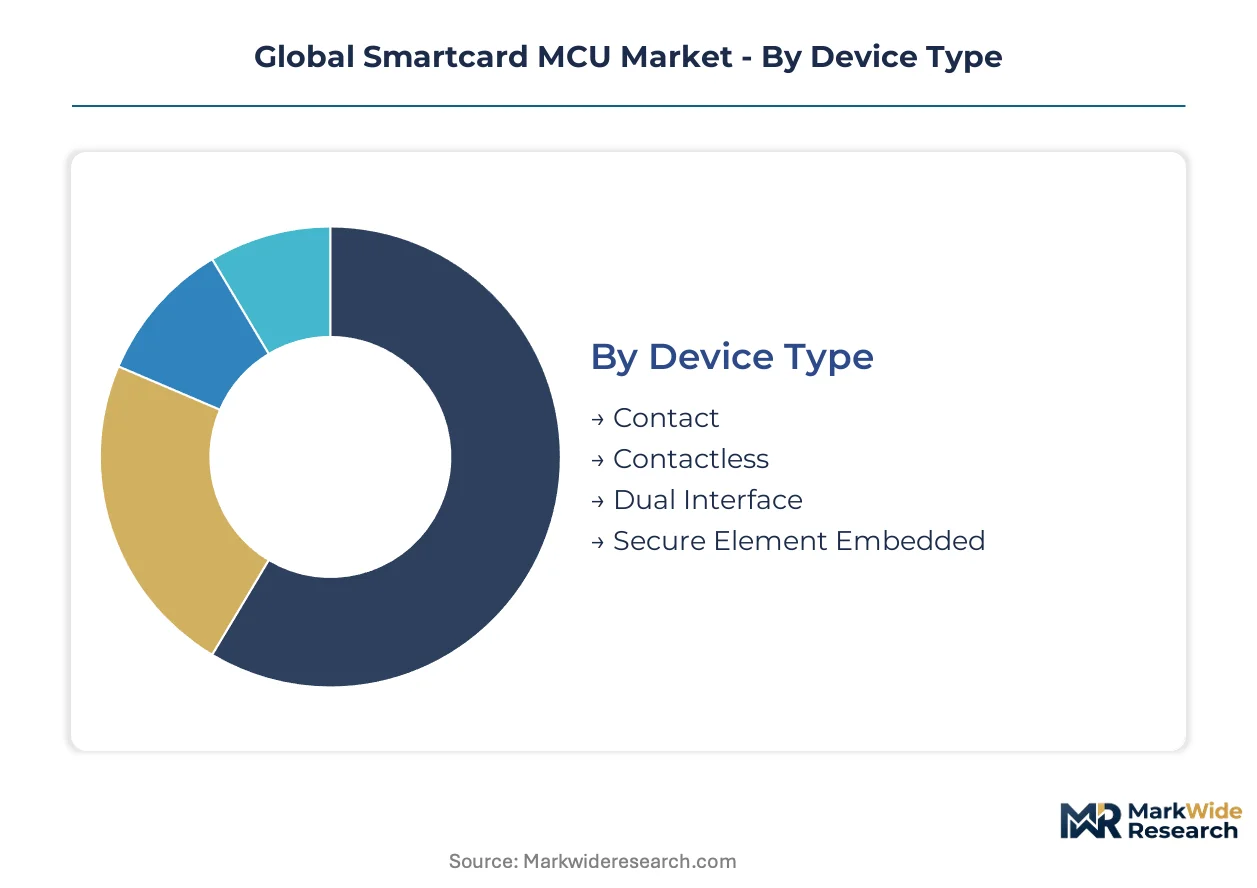
Smartcard MCU segmentation reveals divergent margin structures across interface technologies, with certification tiers and computational density determining profitability. Application-specific requirements from payment networks, transit operators, and government issuers fragment procurement specifications across the value chain.
Device Type:
Dual Interface and Secure Element Embedded variants command premium pricing due to EAL5+ certification overhead and multi-protocol complexity.
- Contact:Legacy dip-card interface using ISO 7816 electrical specifications with 1-5 MHz clock operation. Banking EMV compliance in France and Germany sustains residual demand despite terminal infrastructure aging.
- Contactless:RF-powered 13.56 MHz operation enabling tap-to-pay transactions without physical insertion. Transit fare collection in London, São Paulo, and Singapore is displacing magnetic-stripe systems fastest.
- Dual Interface:Hybrid architectures bridging contact legacy infrastructure with contactless RF front-ends through single-die integration.
- Secure Element Embedded:Tamper-resistant silicon integrated directly into smartphone chipsets or wearable devices, bypassing discrete card form factors.
Contactless holds installed capacity. Dual Interface is rotating up the share rankings.
Application:
Banking credentials generate volume concentration, while transportation and digital identity applications are climbing the fastest.
- Banking:EMV payment card deployment across Visa, Mastercard, and China UnionPay networks. EMVCo specification mandates in the United States and United Kingdom sustain replacement cycles for expired card stock.
- Identification:Government e-ID and biometric passport chips requiring Common Criteria EAL4+ to EAL6 evaluation depth. ANSSI and BSI certification gates in France and Germany constrain supplier participation.
- Transportation:City-scale automated fare collection with MIFARE DESFire and Calypso protocol support.
- Loyalty Programs:Closed-loop retail credentialing with lower security tiers and minimal cryptographic acceleration.
- Access Control:Physical security credentialing for enterprise campuses and government facilities.
Banking retains volume leadership. Transportation is gaining share fastest through metro system digitization.
Technology:
Thirty-two-bit architectures pull margin pools upward as biometric authentication and multi-application hosting demand computational headroom.
- 32-bit Architecture:ARM Cortex-M series cores operating at 25-50 MHz with embedded flash densities to 1 MB. Fingerprint sensor integration in payment cards from issuers in China and South Korea is expanding memory and throughput specifications.
- Near Field Communication:Integrated RF analog front-ends with ISO 14443 Type A/B protocol stacks. Transit authorities in Singapore and London specify NFC-A for interoperability with existing reader infrastructure.
- 8-bit Architecture:Legacy 8051-derived cores for cost-sensitive loyalty and low-security access applications.
- 16-bit Architecture:Intermediate computational tier for mid-range payment credentials without biometric requirements.
32-bit Architecture holds technology roadmap priority. Near Field Communication is rotating up the share rankings through transit convergence.
End User:
Government Agencies and Transit Authorities concentrate procurement around certified platform architectures, while Payment Service Providers fragment sourcing across multiple qualification tiers.
- Government Agencies:National e-ID and passport programs requiring BSI or ANSSI Common Criteria evaluation with 12-18 month certification timelines.
- Transit Authorities:City and regional operators in São Paulo, London, and Singapore specifying open-loop payment interoperability.
- Payment Service Providers:Chip-issuing banks and payment network operators unbundling hardware procurement from personalization services.
- Retailers:Closed-loop loyalty and private-label payment programs with reduced security certification burdens.
Government Agencies anchor certification requirements. Transit Authorities are rotating up the share rankings through infrastructure modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabrication facilities export EAL5+ certified secure elements to payment network operators across France, the United Kingdom, and Singapore. This trade corridor channels high-assurance silicon through Common Criteria evaluation pipelines into retail banking and transit credentialing deployments.
Germany
BSI-administered Common Criteria evaluations gate government e-ID procurement for domestic chip suppliers. The country's national cybersecurity regulator maintains EAL5+ certification depth for biometric passport and payment applications. Munich and Dresden host captive fabrication clusters where high-assurance foundry output feeds into European payment network supply chains.
China
China UnionPay domestic scaling concentrates volume demand for dual-interface secure elements across state-owned banking networks. The central bank's tokenization mandates and digital yuan pilot programs accelerate secure element deployment. Shanghai and Shenzhen manufacturing corridors supply payment terminals and chipsets for domestic transit modernization in Beijing and Guangzhou metro systems.
France
ANSSI certification timelines extend 12-18 months for biometric payment card suppliers seeking government credentialing contracts. The national cybersecurity agency tightens evaluation depth alongside ETSI interoperability mandates. Paris and Grenoble engineering clusters specialize in side-channel attack resistance design for banking and e-ID applications.
Singapore
Land Transport Authority open-loop fare collection specifications drive NFC-A secure element demand for transit credentialing convergence. The country's standards body mandates ISO 14443 Type A/B protocol interoperability with existing reader infrastructure. Jurong and One-North technology corridors host system integrators bridging contactless payment rails with automated fare collection networks.
India
Aadhaar-linked payment credentialing and RBI tokenization mandates open volume deployment channels for domestic and foreign MCU suppliers. The central bank's regulatory framework pushes secure element integration into unified payment interface architectures. Bengaluru and Hyderabad semiconductor design clusters localize firmware development for government digital identity programs.
Global Smartcard MCU Market Competitive Landscape
Listed leaders compete with private specialists across certification tier depth and foundry capacity allocation. The vendor base concentrates around three to four integrated fabricators with captive high-assurance production, while mid-tier specialists compete on modular architecture flexibility. Strategic archetypes include EAL5+ certified integrated device manufacturers, fabless secure element designers, and government-focused credentialing specialists. Competitive moves center on foundry capacity expansion in Germany and France alongside post-quantum cryptography accelerator licensing partnerships.
Within the integrated fabrication tier, Infineon Technologies and NXP Semiconductors exemplify European high-assurance production archetypes with German and Dutch origins respectively. STMicroelectronics anchors the dual-interface specialization vector through French and Italian engineering heritage. These three listed entities occupy positions that bridge Common Criteria certification pipelines with EMVCo specification compliance for payment network procurement.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Infineon Technologies |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Microchip Technology |
| Samsung Electronics |
| Giesecke+Devrient |
| IDEMIA |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
Captive high-assurance fabrication capacity in Germany and France creates scale economies that simultaneously concentrate supply-side power and establish rigid price floors for EAL5+ certified devices. Foundry utilization rates above 85% at BSI-qualified facilities translate directly into premium pricing tiers that resist downward negotiation from payment network operators and government procurement agencies.
Pricing Analysis
Technology-generation pricing gaps separate 32-bit biometric-enabled secure elements from legacy 8-bit contact-only architectures and emerging post-quantum cryptography designs. Three-tier pricing structure across premium, standard, and economy levels stratifies by Common Criteria certification depth, with EAL5+ devices commanding 40-60% premiums over EAL4+ equivalents. Cost compression in 8-bit legacy tiers is intensifying because terminal infrastructure aging in France and Germany sustains residual demand without pricing power. Payment Service Providers exhibit highest price sensitivity through unbundled hardware procurement, while Government Agencies accept premium pricing for pre-certified platform architectures with documented evaluation track records.
Supply Chain Analysis
Inventory lead times for 300mm wafers and specialty packaging materials currently stretch 26-32 weeks at German high-assurance foundries, constraining order fulfillment flexibility for urgent transit credentialing deployments. Supply concentrates in Germany, France, and China, with Dresden and Munich clusters feeding European payment networks while Shanghai manufacturing corridors serve domestic China UnionPay scaling. Raw material dependencies center on 300mm silicon wafers, gold wire bonding supplies, and epoxy molding compounds qualified for tamper-resistance specifications. Single-source vulnerability at BSI-accredited packaging facilities in Bavaria poses structural risk for government e-ID procurement timelines. Distribution runs through direct foundry-to-module-maker contracts, bypassing traditional semiconductor distributor channels to preserve chain-of-custody documentation for certification compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated payment network operators and transit authorities, fragmenting procurement across chip-issuing banks, fintech wallet providers, and government credentialing agencies that now unbundle hardware from personalization services.
For Market Incumbents: Shield certification-track record advantages by accelerating post-quantum cryptography accelerator tape-outs before NIST standardization finalizes, denying new entrants first-mover positioning. Deepen backward integration into 300mm wafer supply through long-term offtake agreements with German foundry partners, insulating against specialty packaging material shortages that threaten margin stability. Prioritize BSI and ANSSI evaluation pipeline investment to extend certification timeline barriers against mid-tier modular architecture competitors. For New Entrants and Emerging Players: Anchor in India's Aadhaar-linked payment credentialing expansion, where RBI tokenization mandates create volume deployment channels without entrenched incumbent relationships. Target transportation credentialing convergence in São Paulo and Singapore metro systems, where open-loop fare collection specifications favor NFC-A interoperability expertise over deep Common Criteria track records. Pursue modular secure element architecture licensing to transit system integrators seeking 18-month refresh cycles without full silicon respins. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fabless secure element designers with post-quantum cryptography IP portfolios and established EMVCo specification compliance engineering teams. Long-term viability over the next decade hinges on foundry qualification timelines and regulatory evaluation depth rather than pure manufacturing scale. Acquisition target archetype: specialized biometric payment card designers with ANSSI evaluation-in-progress status and side-channel attack resistance design capabilities. Watch NIST lattice-based cryptography standardization announcements as inflection indicator for quantum-resistant secure element redesign cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Accelerator Development | NIST standardization timelines are compressing silicon redesign cycles for quantum-resistant secure elements. |
| Common Criteria Certification Pipeline Expansion | BSI and ANSSI evaluation depth requirements favor incumbents with 12-18 month track record documentation. |
| Modular Secure Element Architecture Licensing | Transit authorities in Singapore and London demand 18-month refresh intervals without full respins. |
| India Market Localization Partnership | RBI tokenization mandates and Aadhaar-linked credentialing open volume channels for domestic integration. |
| 300mm Wafer Supply Agreement Structuring | Foundry concentration in Germany and France constrains supply elasticity for EAL5+ certified device procurement. |
Research Methodology
Operator-level perspectives from secure element procurement managers at payment network operators, transit authority technical specifications leads, government e-ID program directors, and foundry capacity planners anchored the qualitative base for this study. Primary interview intelligence combined with secondary validation from EMVCo specification documentation, BSI Common Criteria evaluation registers, ANSSI certification timelines, and semiconductor customs trade data. Bottom-up secure element shipment estimates by device type and application triangulated against top-down payment card issuance forecasts and transit system deployment announcements.
Sensitivity analysis across post-quantum cryptography migration timelines, foundry capacity utilization scenarios, and certification evaluation duration variations shaped the analytical framework. Segmentation dimensions modeled include interface technology, application vertical, architecture bit-width, and end-user procurement archetype across the projection horizon. CAGRs derived from fitted growth curves against historical secure element deployment patterns in banking and transit credentialing, with EMVCo specification revision cycles and China UnionPay domestic scaling curves as primary industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EMVCo contactless terminal buildout momentum and stable BSI/ANSSI evaluation capacity; material deviation in post-quantum standardization timelines or foundry qualification schedules would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Indonesia Data Center Processor Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
Europe MPU Market