
 Laser-Based Gas Analyzers Market | 2026-2036
Laser-Based Gas Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Laser-Based Gas Analyzers Market Foresight
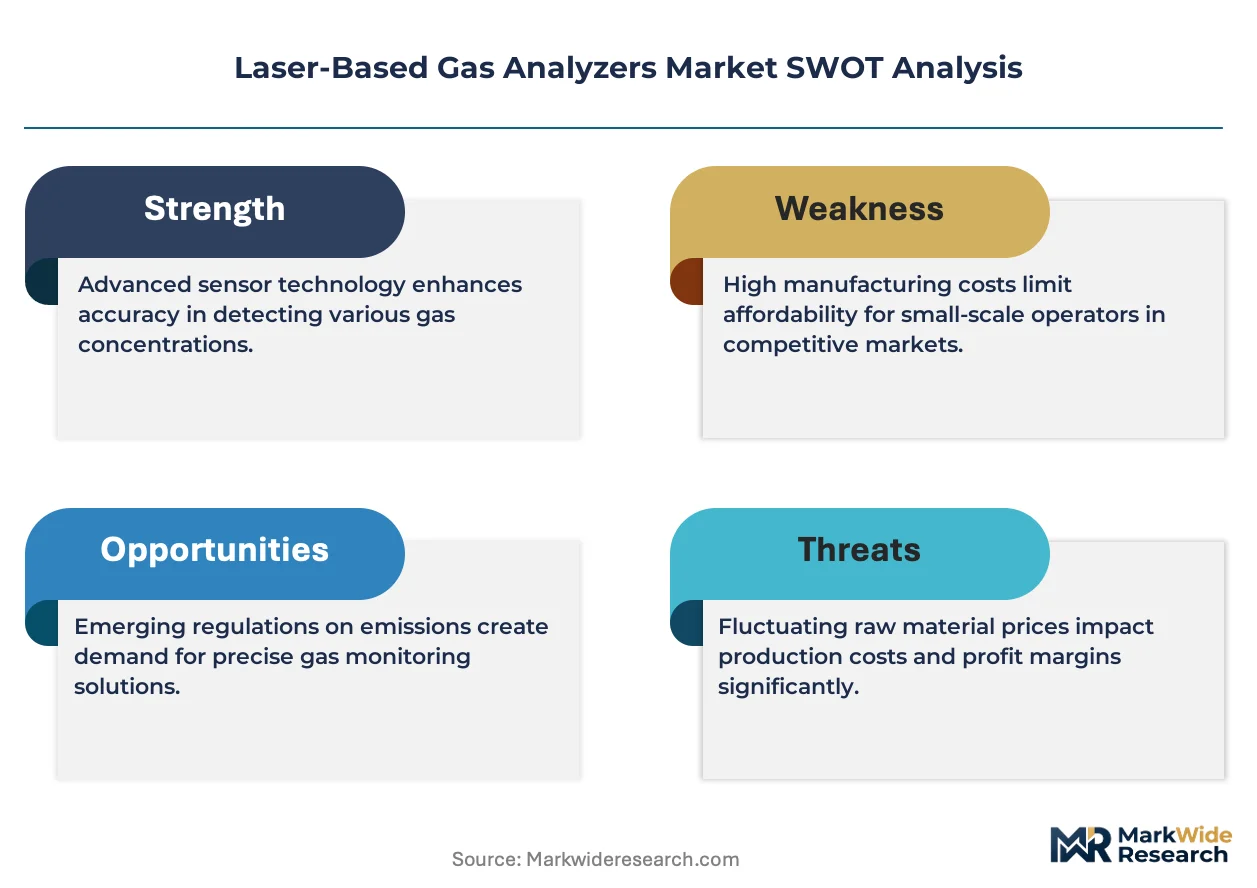
Process control buyers are gaining share as environmental monitoring procurement is unwinding from its prior dominance in laser-based gas analyzer deployment. ABB Ltd leverages its integrated automation portfolio to anchor large refinery contracts across European chemical corridors. Yokogawa Electric Corporation competes through specialized tunable diode laser architectures optimized for petrochemical stack monitoring. Honeywell International Inc. sustains its position via backward integration into sensor fabrication and embedded software control layers.
Laser-based gas analyzers are optical instruments that exploit absorption spectroscopy principles, typically operating at wavelengths from near-infrared through mid-infrared, to quantify gas concentrations with detection limits reaching parts-per-billion in industrial process streams and ambient air matrices. Their primary purpose centers on real-time emission quantification, combustion optimization, and regulatory compliance verification across continuous manufacturing operations. Stationary analyzers dominate installed value due to permanent integration requirements at power generation and petrochemical facilities, while portable analyzers represent the fastest-expanding category as field inspection protocols multiply under tightened leak detection mandates. Quantum cascade laser technology leads the technology dimension with superior mid-infrared coverage for multi-species detection, though tunable diode lasers retain margin advantages in oxygen and carbon monoxide measurement niches.
The US EPA enforces methane performance standards under New Source Performance Standards rules that mandate optical gas imaging or equivalent laser-based monitoring at oil and gas production sites, directly expanding analyzer procurement cycles. EU REACH restrictions on hazardous substance releases and the Industrial Emissions Directive impose continuous monitoring obligations that favor laser methods over extractive sampling for stack and fence-line applications. China's MEE administers increasingly stringent emission permits for steel and cement sectors that specify continuous emission monitoring system certifications. Stakeholders must evaluate how divergent certification timelines across EPA, ECHA, and MEE jurisdictions will strain product development roadmaps and service localization investments.
Market Dynamics
The US EPA's updated methane performance standards are compressing compliance windows and forcing oil and gas operators to replace extractive sampling with optical monitoring systems at production, gathering, and processing sites.
Growth Catalysts
- Tunable Diode Laser Architectures:Petrochemical facilities in Germany's chemical clusters are deploying these systems for continuous stack monitoring under EU Industrial Emissions Directive obligations, replacing legacy extractive analyzers.
- Pipeline Integrity Mandates:Fugitive emissions protocols are multiplying across US shale basins, requiring real-time leak detection at compressor stations and storage facilities.
- China's MEE Emission Permits:Steel and cement sector certifications now specify continuous emission monitoring systems, opening procurement cycles for quantum cascade laser installations.
Market Restraints
- Detector Material Concentration:Indium antimonide and mercury cadmium telluride substrate supply concentrates among specialty semiconductor foundries in Japan and the United States, creating input cost volatility for mid-infrared instrument manufacturers.
- Calibration Gas Bottleneck:Certified reference material production for methane and ammonia spans fewer than twelve accredited laboratories globally, stretching lead times for analyzer commissioning.
- Extractive Sampling Incumbency:Fourier-transform infrared systems retain installed base advantages in refinery process control applications where multi-point averaging is acceptable.
Strategic Opportunities
- Biogas Upgrading Facilities:Anaerobic digestion plants in Denmark and the Netherlands require siloxane and hydrogen sulfide monitoring for grid injection compliance, a specification quantum cascade lasers address uniquely.
- EU F-Gas Regulation Phase-Down:Refrigerant leak detection mandates for commercial cooling systems are expanding addressable demand beyond industrial fence-line applications.
- Portable Analyzer Channel Development:Environmental consulting firms are building captive fleets for LDAR (Leak Detection and Repair) contracting, bypassing traditional distributor networks.
Industry Challenges
- Spectroscopy Specialist Scarcity:Installation and maintenance of tunable diode laser systems requires technicians trained in laser alignment and interferometry, a skill set concentrated among aging field service workforces at ABB and Yokogawa.
- Cross-Jurisdiction Certification Lag:Simultaneous EPA, ECHA, and MEE approval timelines strain product development roadmaps, particularly for multi-species analyzers targeting methane, ammonia, and nitrous oxide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser-Based Gas Analyzers Market |
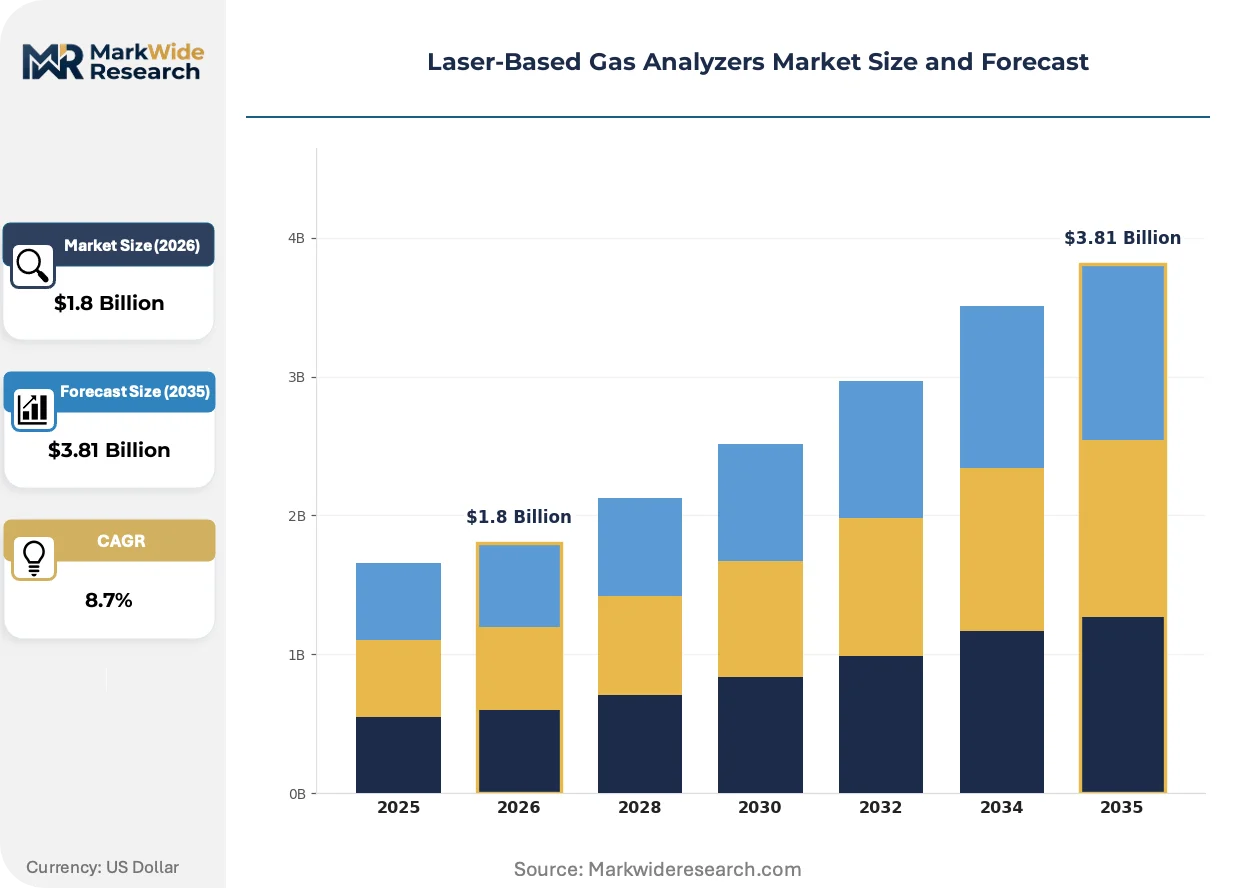
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Stationary Analyzers, User-Friendly Devices, High-Precision Systems Application: Environmental Monitoring, Industrial Emissions, Process Control, Research & Development End User: Aerospace, Automotive Manufacturers, Oil & Gas Companies, Laboratories Technology: Quantum Cascade Lasers, Tunable Diode Lasers, Frequency-Modulated Lasers, Others |
| Companies Covered | ABB Ltd, Emerson Electric Co., Yokogawa Electric Corporation, Siemens AG, Honeywell International Inc., HORIBA Ltd, Endress + Hauser AG, AMETEK Inc., Servomex Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser-Based Gas Analyzers Market Shifts & Advancements
Quantum cascade laser technology is fragmenting the competitive landscape as specialized mid-infrared coverage enables multi-species detection that tunable diode lasers cannot match, while portable form factors reshape field inspection economics.
Quantum cascade laser technology is fragmenting the stationary analyzer segment by delivering parts-per-billion detection limits for methane, ammonia, and nitrous oxide in a single optical path. Refinery operators in Rotterdam and Antwerp chemical clusters are specifying these systems for fence-line monitoring. The technology is compressing margins for single-species tunable diode laser architectures in process control applications.
REACH restrictions on hazardous substance releases are tightening continuous monitoring obligations for chemical manufacturing stack emissions across EU member states. The Industrial Emissions Directive now explicitly favors in-situ laser methods over extractive sampling for new permit applications. German chemical clusters in Ludwigshafen and Leverkusen are responding with accelerated replacement cycles for legacy analyzer infrastructure.
Environmental consulting firms are unbundling after-sales service from original equipment manufacturers and building captive calibration and maintenance capabilities. This channel shift is most visible in Texas and North Dakota shale basins where LDAR contractors operate analyzer fleets exceeding fifty units. Third-party service providers are compressing OEM service contract renewal rates by thirty to forty percent in these regions.
Laser-Based Gas Analyzers Market Segmentation
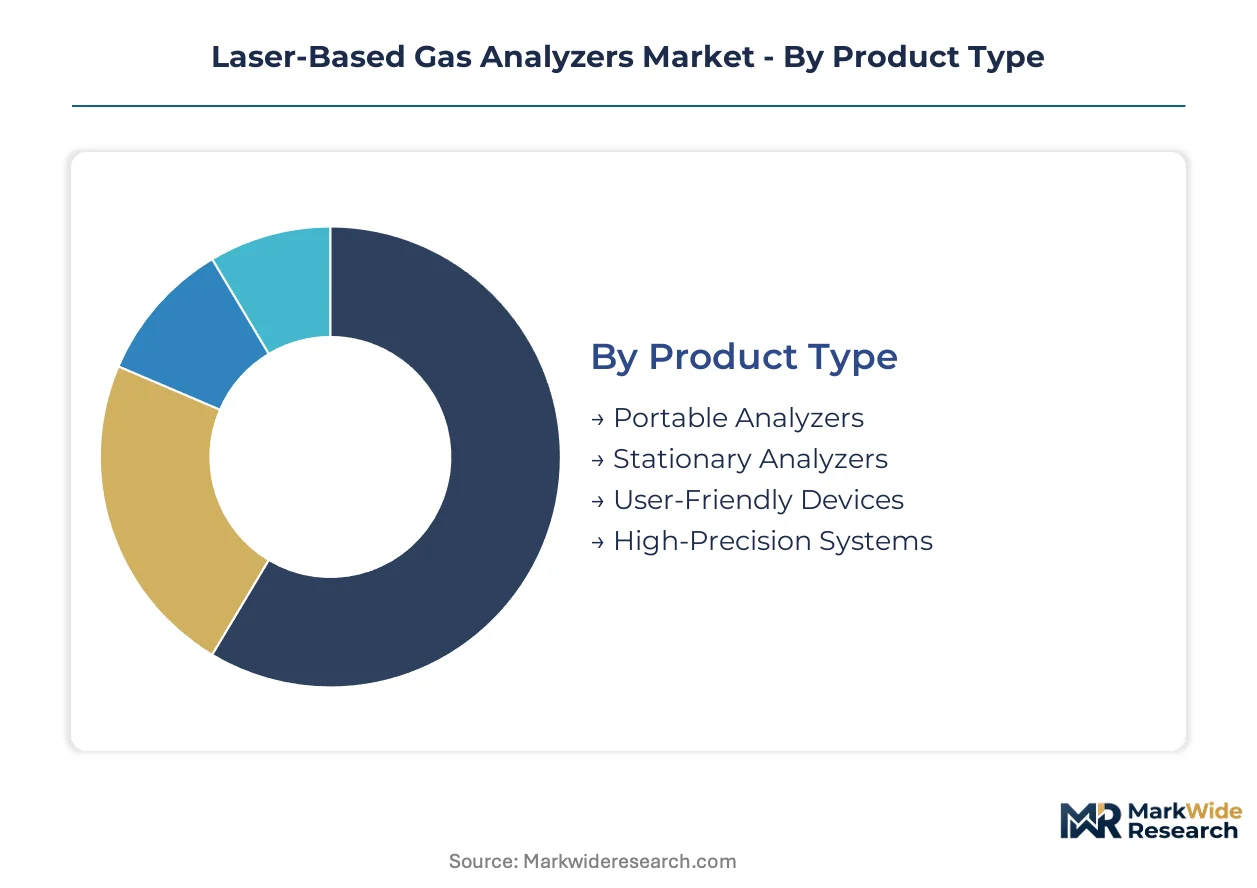
Laser-based gas analyzer procurement splits across stationary infrastructure investments and portable field deployment, with regulatory mandates dictating which configurations dominate specific compliance scenarios. Understanding these segment boundaries clarifies where technology suppliers must align product roadmaps with enforcement timelines.
Product Type:
EPA methane performance standards and EU Industrial Emissions Directive obligations create divergent form factor requirements between permanent stack installations and mobile leak detection protocols.
- Portable Analyzers:Handheld and transportable units integrate battery-powered laser sources with wireless data transmission for LDAR field crews. Demand concentrates in Texas and North Dakota shale basins where environmental consulting firms build captive fleets exceeding fifty units to serve oil and gas operator contracts. These configurations face calibration gas supply bottlenecks that stretch commissioning lead times.
- Stationary Analyzers:Permanently mounted systems with heated sample lines and automated zero-span checks anchor continuous emission monitoring at power generation and petrochemical facilities. German chemical clusters in Ludwigshafen and Leverkusen specify these for EU Industrial Emissions Directive compliance, replacing legacy extractive analyzers with in-situ laser methods.
- User-Friendly Devices:Simplified interfaces with automated diagnostic routines reduce technician training burdens for utility and small industrial operators.
- High-Precision Systems:Laboratory-grade stability specifications serve research institutions and reference method validation programs requiring parts-per-trillion detection thresholds.
Established volume favors Stationary Analyzers; emerging adoption favors Portable Analyzers.
Application:
Cost tier differentiation separates compliance-driven procurement from optimization-motivated spending, with environmental monitoring commanding premium pricing for certified reference performance.
- Environmental Monitoring:Ambient air quality networks and fence-line surveillance require multi-species detection with documented uncertainty budgets. Rotterdam and Antwerp refinery operators specify quantum cascade laser architectures for methane, ammonia, and nitrous oxide quantification under REACH hazardous substance release protocols.
- Process Control:Combustion optimization and reaction monitoring in chemical manufacturing prioritize response speed over absolute accuracy. Petrochemical facilities deploy tunable diode laser systems for oxygen and carbon monoxide measurement where margin advantages persist against quantum cascade alternatives.
- Industrial Emissions:Stack monitoring for regulatory reporting demands calibration traceability to national metrology institutes.
- Research & Development:Spectroscopy method development and sensor validation programs drive demand for configurable optical paths and custom wavelength selection.
Environmental Monitoring claims the steepest expansion trajectory as enforcement intensifies; Process Control retains the largest installed value base.
End User:
Customer type concentration shapes service model requirements, with oil and gas operators demanding 24-hour response capabilities while laboratory clients prioritize technical consultation.
- Oil and Gas Companies:Upstream, midstream, and downstream operations deploy analyzers for methane leak detection, flare monitoring, and processing unit optimization. US EPA New Source Performance Standards mandate optical gas imaging or equivalent laser-based monitoring at production, gathering, and processing sites, directly expanding procurement cycles.
- Laboratories:National metrology institutes and commercial testing facilities require analyzer stability for certified reference material production and instrument intercomparison studies.
- Aerospace:Propulsion test stands and fuel system qualification programs specify hydrogen and hydrocarbon detection for safety monitoring.
- Automotive Manufacturers:Engine test cells and catalytic converter development programs measure exhaust gas composition for emissions certification.
Oil and Gas Companies dominate current demand volume; Laboratories represent the most stable replacement cycle profile.
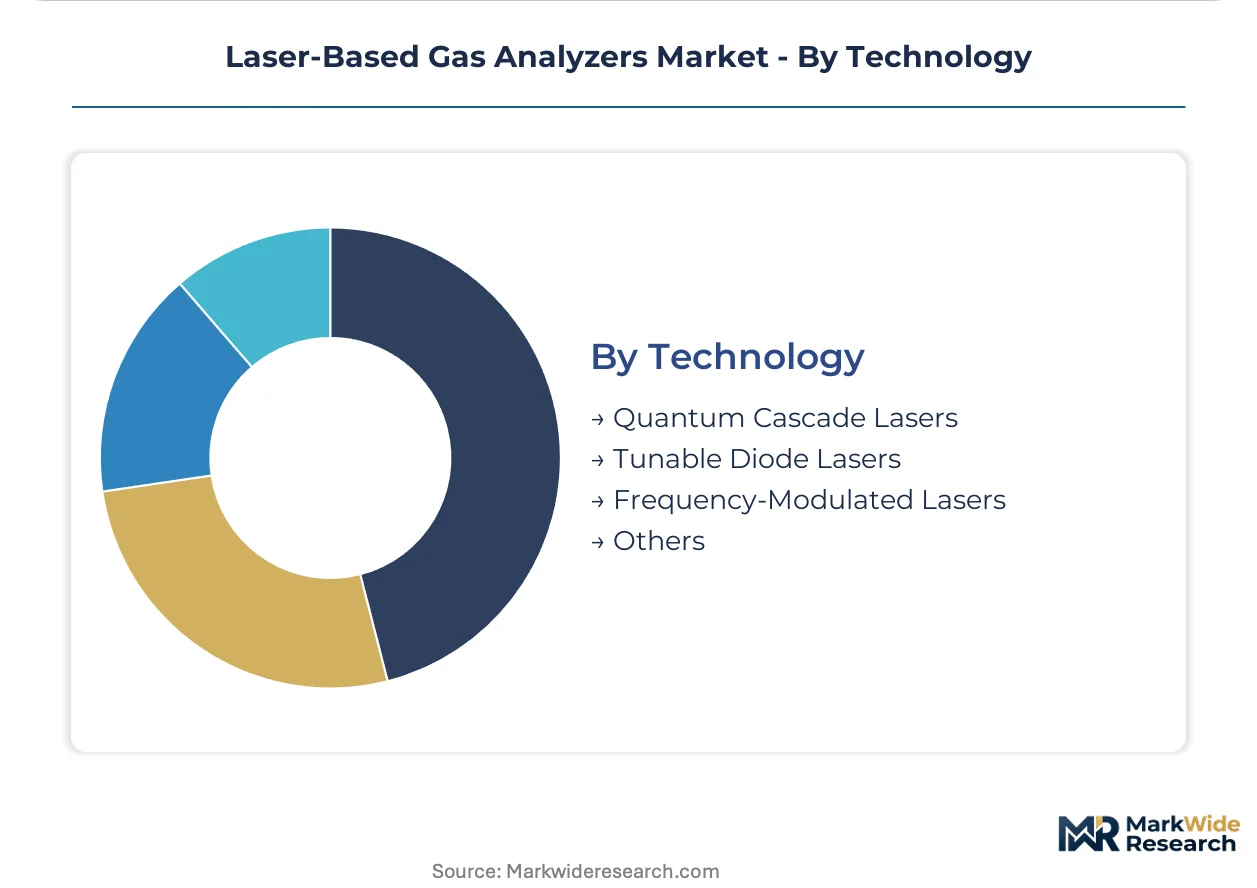
Technology:
Supply concentration in detector substrate manufacturing constrains cost trajectories for mid-infrared architectures, with indium antimonide and mercury cadmium telluride sourcing limited to specialty semiconductor foundries in Japan and the United States.
- Quantum Cascade Lasers:Semiconductor heterostructure designs emit across the mid-infrared with tunable wavelength coverage enabling simultaneous methane, ammonia, and nitrous oxide detection in a single optical path. China's MEE emission permits for steel and cement sectors now specify continuous emission monitoring system certifications that quantum cascade installations satisfy.
- Tunable Diode Lasers:Near-infrared distributed feedback lasers offer mature manufacturing economies and established supply chains for oxygen and carbon monoxide measurement niches. These architectures retain margin advantages where single-species detection suffices.
- Frequency-Modulated Lasers:Wavelength modulation spectroscopy techniques enhance signal-to-noise ratios for trace gas detection in interference-prone matrices.
- Others:Cavity ring-down and photoacoustic methods serve specialized applications requiring ultra-low detection limits or compact form factors.
Tunable Diode Lasers anchor the largest installed base; Quantum Cascade Lasers are gaining share fastest through multi-specification compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network underwrites North American demand concentration for fugitive emissions monitoring infrastructure. European chemical corridors depend on Rhine River barge terminals for analyzer component logistics. East Asian manufacturing clusters feed quantum cascade laser substrate supply chains through specialized semiconductor foundries.
United States
Shale basin compressor stations and storage facilities drive procurement for portable laser analyzers. EPA New Source Performance Standards mandate optical gas imaging or equivalent laser-based monitoring at production and gathering sites. Texas and North Dakota environmental consulting firms operate captive analyzer fleets exceeding fifty units for LDAR contracting.
Germany
Chemical manufacturing clusters in Ludwigshafen and Leverkusen require continuous stack monitoring under EU Industrial Emissions Directive obligations. REACH hazardous substance release protocols tighten continuous monitoring specifications for fence-line surveillance. Refinery operators in the Rhine-Ruhr industrial belt are accelerating replacement cycles for legacy extractive analyzers.
China
Steel and cement sector expansion creates demand for certified continuous emission monitoring systems. MEE emission permits now specify multi-species detection capabilities for methane, ammonia, and nitrous oxide quantification. Yangtze River Delta manufacturing hubs are integrating quantum cascade laser installations for regulatory compliance verification.
Netherlands
Rotterdam and Antwerp chemical corridor refineries specify quantum cascade laser architectures for fence-line monitoring applications. EU F-Gas Regulation phase-down mandates expand refrigerant leak detection requirements beyond industrial fence-line applications. Biogas upgrading facilities in Denmark and the Netherlands require siloxane monitoring for grid injection compliance.
Japan
Specialty semiconductor foundries concentrate indium antimonide and mercury cadmium telluride substrate production for mid-infrared detector manufacturing. METI industrial emission guidelines favor laser-based methods over extractive sampling for new facility permits. Osaka-Kobe manufacturing belt facilities supply detector materials to global instrument manufacturers.
Laser-Based Gas Analyzers Market Competitive Landscape
Concentration sits with diversified industrial automation conglomerates that anchor large refinery and chemical complex contracts through integrated control system portfolios. The vendor base spans three tiers: multinational automation platforms with captive sensor fabrication, specialized spectroscopy houses with tunable diode laser architectures, and emerging quantum cascade laser specialists. Competitive dynamics center on backward integration into detector substrate supply and geographic service localization for EPA, ECHA, and MEE certification timelines.
Among diversified automation conglomerates, ABB Ltd and Yokogawa Electric Corporation exemplify contrasting strategic positions. ABB leverages its integrated automation portfolio to anchor contracts across European chemical corridors. Yokogawa occupies a specialist position through focused spectroscopy architectures optimized for petrochemical stack monitoring. Honeywell International Inc. represents the backward integration archetype with in-house sensor fabrication and embedded software control layers.
| Leading Market Players |
|---|
| ABB Ltd |
| Emerson Electric Co. |
| Yokogawa Electric Corporation |
| Siemens AG |
| Honeywell International Inc. |
| HORIBA Ltd |
| Endress + Hauser AG |
| AMETEK Inc. |
| Servomex Group Limited |
| Others |
Supply & Pricing Matrix
EPA New Source Performance Standards certification gates both supply qualification and price differentiation simultaneously, separating vendors with multi-jurisdiction approval capabilities from those limited to single-market deployments. Buyers in oil and gas sectors pay premiums for analyzers pre-certified across EPA, ECHA, and MEE regimes, while utility operators accept economy-tier specifications where single-jurisdiction compliance suffices.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with oil and gas operators securing 15-25 unit fleet pricing against single-unit laboratory purchases. Price differentiation rests on certification breadth and detector substrate grade, with indium antimonide-based architectures commanding premiums over standard mercury cadmium telluride alternatives. Cost compression in the portable analyzer tier is intensifying because environmental consulting firms are consolidating captive fleets and bypassing traditional distributor markups. Small industrial operators exhibit highest price sensitivity, while national metrology institutes demonstrate lowest sensitivity due to stability requirements overriding procurement cost.
Supply Chain Analysis
Strategic stockpiling of detector substrates prevails over just-in-time approaches, with instrument manufacturers holding 6-9 month indium antimonide and mercury cadmium telluride inventories against foundry lead time volatility. Supply concentrates in Japan and the United States for these specialty semiconductor substrates, with Osaka-Kobe manufacturing belt facilities feeding global instrument production. Raw material dependencies extend to precision optical coatings, hermetic packaging ceramics, and certified reference gas mixtures. Single-source vulnerability in Japanese foundry capacity represents the dominant structural risk. Distribution runs through integrated automation conglomerates for large refinery contracts, while environmental consulting firms source directly through specialized spectroscopy houses for portable analyzer fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is approaching a platform-economics inflection where interoperability between analyzer hardware and third-party calibration service platforms will determine competitive survival. Ecosystem openness now shapes procurement decisions as environmental consulting firms unbundle after-sales service from original equipment manufacturers.
For Market Incumbents: Fortify backward integration into detector substrate supply and embedded software control layers against quantum cascade laser specialists eroding margin positions in multi-species detection niches. Prioritize EPA-ECHA-MEE simultaneous certification investment to defend large refinery contract renewals. Channel control through captive service networks in Texas and North Dakota shale basins remains essential as third-party providers compress OEM service contract renewal rates. For New Entrants and Emerging Players: Differentiate on portable form factor miniaturization and wireless data transmission integration for LDAR field crew applications. Biogas upgrading facilities in Denmark and the Netherlands represent the most penetrable segment, with siloxane and hydrogen sulfide monitoring specifications that quantum cascade lasers address uniquely. Direct sales to environmental consulting firms building captive fleets bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: EPA methane performance standards phase-down timelines reshape the acquisition landscape toward vendors with pre-positioned optical monitoring system portfolios. Long-term viability over a 5-10 year window favors specialists with quantum cascade laser architectures and multi-jurisdiction certification capabilities over single-technology tunable diode laser houses. Watch MEE emission permit enforcement intensity in Yangtze River Delta steel and cement sectors as the primary inflection indicator for East Asian procurement cycle expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Fabrication | Captive indium antimonide supply insulates margins against Japanese foundry price volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA-ECHA-MEE approval unlocks oil and gas operator premium procurement tiers. |
| Portable Analyzer Channel Development | Direct sales to LDAR contractors bypasses traditional distributor networks in Texas shale basins. |
| Third-Party Service Platform Partnership | Interoperability with environmental consulting firm calibration capabilities expands addressable aftermarket. |
| Quantum Cascade Laser Product Line Expansion | Multi-species detection coverage displaces tunable diode laser incumbency in fence-line monitoring. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings across the analysis. Conversations with plant engineers at German chemical clusters, environmental consulting firm operations directors, OEM procurement teams at oil and gas operators, and aftermarket service heads at integrated automation conglomerates informed demand-side dynamics. Secondary sources included EPA enforcement action databases, ECHA substance restriction notifications, MEE emission permit registries, and SEC 10-K filings from listed instrument manufacturers. Bottom-up unit deployment estimates triangulated against top-down addressable market calculations derived from regulatory mandate coverage expansion.
Sensitivity analysis around enforcement timeline acceleration and detector substrate cost trajectories shaped the analytical framework. Segmentation dimensions modeled include product type, application tier, end-user industry, and technology architecture across the projection horizon. CAGRs were derived from regression analysis against historical procurement cycles correlated with regulatory implementation phases. Industry-specific forecast inputs incorporated EU Industrial Emissions Directive permit renewal schedules and US shale basin compressor station buildout pipelines.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or stable semiconductor foundry capacity would require recalibration. Forecasts reflect assumptions regarding EPA methane rule implementation pace, REACH restriction expansion scope, and MEE certification timeline convergence. Revision becomes warranted when cross-jurisdiction approval lag exceeds 18 months or detector substrate supply concentration shifts beyond Japanese and US foundry dominance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
Metallurgical Microscope Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Gas Chromatography Systems Market
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market