
 Temperature Monitoring Devices Market | 2026-2036
Temperature Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Monitoring Devices Market Outlook
Wireless sensor integration with cloud-based analytics platforms is rewriting how temperature data is captured, transmitted, and acted upon across distributed supply chains. 3M Company leverages its materials science portfolio to sustain dominance in adhesive-backed sensor deployments for healthcare and industrial environments. Emerson Electric Co. anchors its position through deep specialization in industrial-grade thermocouple assemblies for process manufacturing. Honeywell International Inc. competes by extending its building automation expertise into HVAC-centric temperature monitoring ecosystems.
Temperature monitoring devices encompass instruments that measure, record, and transmit thermal data through thermoelectric, infrared, or semiconductor-based sensing elements, typically achieving accuracy within ±0.1°C to ±0.5°C depending on sensor class and calibration protocol. These instruments serve critical functions in preserving product integrity, ensuring regulatory compliance, and preventing thermal excursions that degrade pharmaceutical, food, or industrial outputs. Infrared thermometers command substantial volume in healthcare point-of-care settings where non-contact speed matters, while wireless sensors represent the fastest-expanding segment as Bluetooth and Wi-Fi protocols eliminate wiring constraints in mobile and remote deployments. Data loggers retain entrenched positions in pharmaceutical cold chain validation where auditable temperature histories remain mandatory for FDA and EMA submissions.
FDA oversight of biologics storage conditions, EMA's Good Distribution Practice requirements, and ISO 13485 quality management standards collectively elevate device accuracy, calibration traceability, and documentation burdens for manufacturers seeking market access. The EU MDR framework further tightens clinical evidence requirements for devices deployed in patient-facing diagnostic roles. Stakeholders must weigh interoperability investments against the fragmentation of proprietary cloud platforms that currently lock data into vendor-specific ecosystems.
Market Dynamics
Wireless sensor networks are compressing installation timelines and eliminating wiring infrastructure across pharmaceutical cold chains, forcing incumbent data logger manufacturers to retrofit cloud connectivity or surrender validation-heavy contracts to sensor-native competitors.
Growth Catalysts
- FDA's updated guidance on continuous temperature monitoring for biologics:Mandates for uninterrupted thermal tracking in vaccine distribution are expanding device deployment density across US pharmaceutical logistics networks.
- Bluetooth Low Energy protocols:Elimination of wiring constraints in mobile healthcare deployments is accelerating sensor adoption for bedside patient monitoring and remote clinical trials.
- Precision manufacturing clusters in Germany:Stringent pharmaceutical standards and advanced chemical processing are driving premium procurement of calibrated thermocouple assemblies for batch validation.
Market Restraints
- Proprietary cloud platform fragmentation:Vendor-specific data ecosystems lock customers into single-source dependencies, raising switching costs and interoperability barriers for multi-site pharmaceutical operators.
- Lithium battery supply concentration:Dependence on constrained cell production for wireless sensor power modules creates input volatility and extended lead times for remote deployment configurations.
- Thermocouple cold junction compensation limitations:Intrinsic accuracy constraints in extreme temperature ranges restrict industrial process applications below -200°C and above 1300°C without exotic material substitutions.
Strategic Opportunities
- EMA's Good Distribution Practice requirements:Regulatory tightening across European pharmaceutical logistics is creating compliance-driven replacement cycles for non-validated legacy monitoring equipment.
- Edge AI inference on sensor nodes:Localized anomaly detection without cloud transmission is opening real-time intervention capabilities for ultra-low-latency cold chain applications.
- Direct-to-patient pharmaceutical delivery:Last-mile temperature assurance for biologics shipped to home infusion patients is emerging as an unserved application requiring portable, disposable monitoring formats.
Industry Challenges
- Calibration technician scarcity:ISO 17025-accredited metrology expertise required for pharmaceutical-grade sensor validation is concentrated in limited geographic clusters, extending deployment timelines.
- Legacy SCADA integration complexity:Brownfield industrial facilities running proprietary communication protocols face substantial middleware development costs to incorporate wireless sensor feeds.
- EU MDR clinical evidence timelines:Patient-facing diagnostic temperature devices face extended certification cycles that compress commercialization windows before technology obsolescence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Monitoring Devices Market |
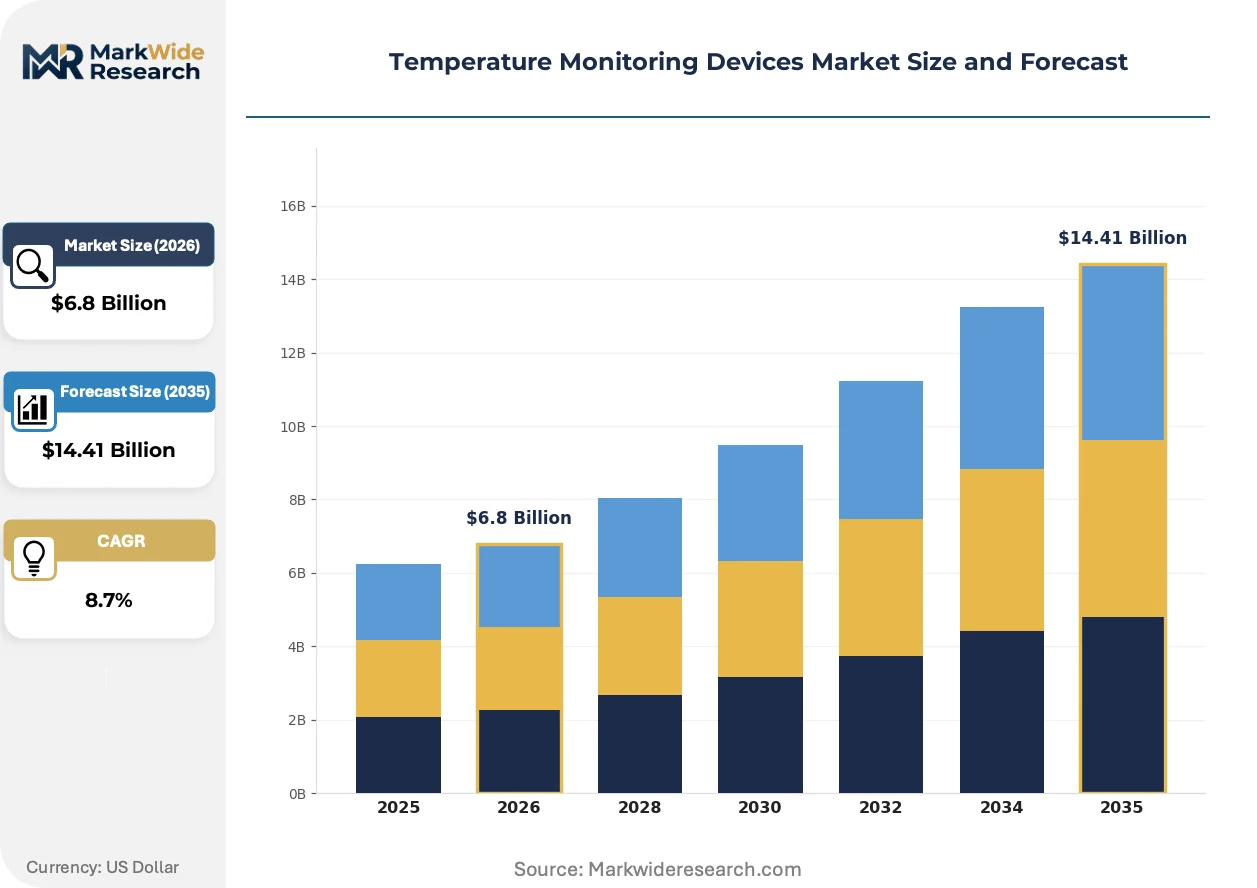
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Infrared Thermometers, Data Loggers, Wireless Sensors, Thermocouples Application: Healthcare, Food Safety, HVAC, Industrial Processes End User: Hospitals, Restaurants, Laboratories, Manufacturing Plants Technology: Bluetooth, Wi-Fi, Wired, Cloud-Based Solutions |
| Companies Covered | 3M Company, Omron Healthcare, Philips Healthcare, GE Healthcare, Medtronic, Honeywell International Inc., Emerson Electric Co., Abbott Laboratories, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Monitoring Devices Market Strategic Shifts
Sensor miniaturization and energy harvesting are collapsing the distinction between disposable shipping indicators and permanent installed monitors, creating hybrid device categories that challenge traditional segmentation logic.
Printed thermistor arrays on flexible substrates are rendering obsolete rigid probe assemblies in pharmaceutical packaging applications. Contract packaging organizations in North America and Western Europe are piloting roll-to-roll printed sensors at scale. The structural consequence is compressing unit economics for single-use temperature indicators from dollars to cents, threatening incumbent electrochemical indicator manufacturers.
REACH restrictions on mercury-containing thermometers are accelerating infrared and semiconductor-based alternatives across European healthcare procurement. The ban eliminates calibration-stable reference standards previously used for field verification of electronic devices. German hospital networks and French pharmaceutical distributors are most affected, responding with accelerated investments in NIST-traceable blackbody calibration sources.
Consolidated buying by pharmaceutical third-party logistics providers is compressing vendor counts and unbundling hardware from validation services. Large cold chain operators in the United States are negotiating enterprise sensor contracts with dedicated calibration and documentation support. The shift is most visible in biologics distribution, where temperature excursion liability has concentrated procurement authority with risk-bearing logistics specialists rather than end-manufacturers.
Temperature Monitoring Devices Market Segmentation
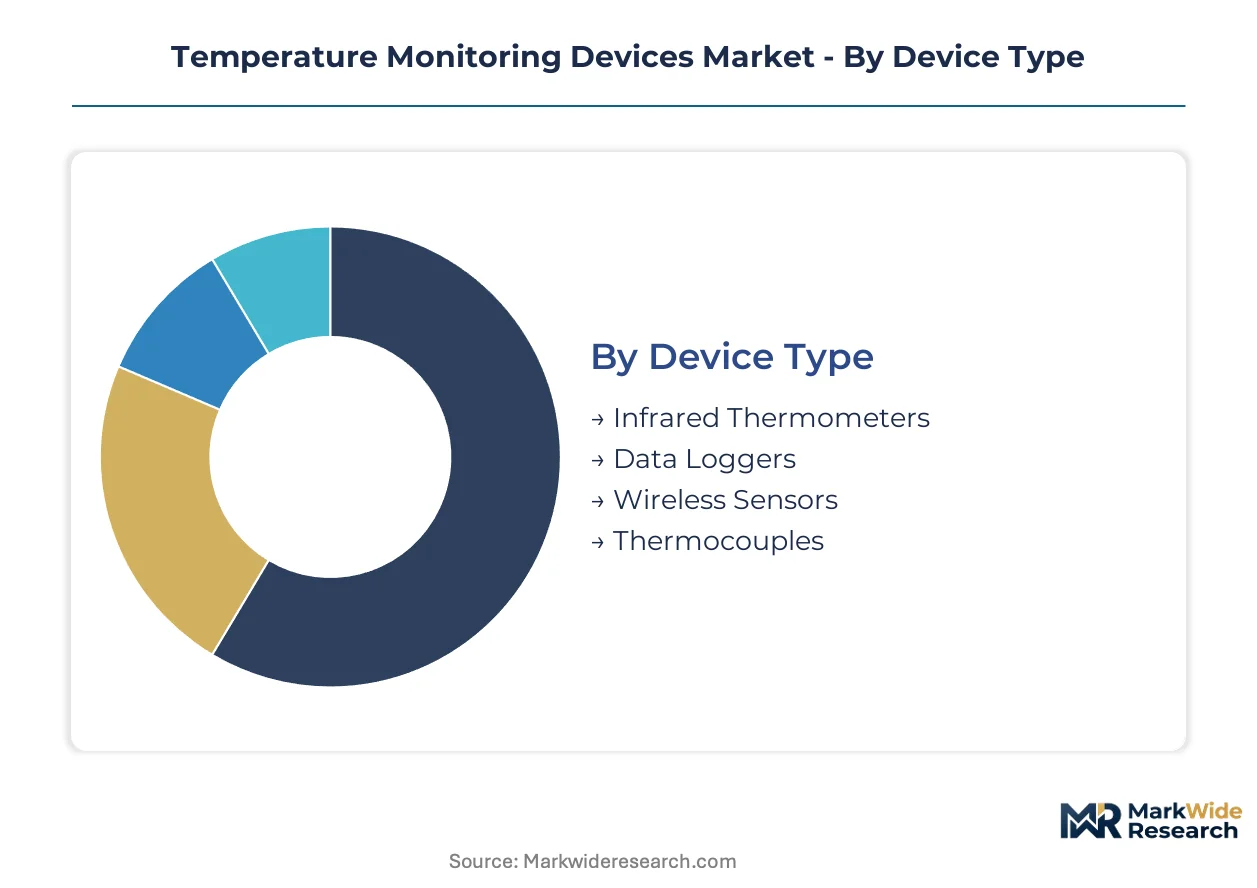
Temperature monitoring devices fragment across four distinct classification axes that determine procurement patterns, technical specifications, and compliance burdens. Device type and application category exert the strongest influence on pricing architecture and vendor selection criteria.
Device Type:
Mature electromechanical instruments coexist with emerging solid-state and wireless formats, creating a bifurcated landscape where legacy validation requirements slow adoption of connected alternatives.
- Wireless Sensors:Semiconductor-based transducers with integrated Bluetooth or Wi-Fi radios transmit thermal data to cloud analytics platforms without physical wiring infrastructure. Pharmaceutical cold chain operators in Germany and the United States are deploying these at scale to eliminate manual data retrieval in vaccine distribution networks, though FDA validation protocols for continuous monitoring applications extend deployment timelines.
- Data Loggers:Self-contained recording instruments with onboard memory store timestamped temperature histories for subsequent download and audit submission. These retain entrenched positions in pharmaceutical batch validation where EMA Good Distribution Practice mandates require auditable documentation trails that predate cloud-native architectures.
- Infrared Thermometers:Non-contact optical sensors measuring thermal radiation from surfaces enable rapid screening in healthcare point-of-care settings.
- Thermocouples:Junction-based sensors exploiting the Seebeck effect deliver wide-range measurement for industrial process control applications.
Data loggers retain volume leadership; wireless sensors hold the steepest expansion curve.
Application:
Regulatory intensity varies sharply across use cases, with life sciences applications commanding precision specifications and documentation rigor that food safety and HVAC deployments rarely match.
- Healthcare:Patient monitoring, diagnostic screening, and clinical trial temperature management require ISO 13485-compliant devices with calibration traceability to NIST or national metrology institutes. FDA oversight of biologics storage and the EU MDR framework for patient-facing diagnostics elevate accuracy requirements to ±0.1°C in critical care applications.
- Food Safety:HACCP-aligned temperature tracking across cold storage, transport, and service environments emphasizes ruggedness and cost efficiency over laboratory-grade precision. Quick-service restaurant chains and centralized kitchen operations drive volume procurement of disposable indicators and reusable probe systems.
- HVAC:Building automation systems integrate temperature sensors for climate control optimization and energy management compliance.
- Industrial Processes:Chemical manufacturing, metallurgy, and semiconductor fabrication deploy thermocouple and RTD assemblies for reactor monitoring and quality control.
Healthcare commands premium pricing; food safety generates the highest unit volumes.
End User:
Procurement sophistication diverges between regulated institutions with dedicated metrology departments and distributed operators lacking in-house calibration capabilities.
- Hospitals:Acute care facilities and integrated delivery networks purchase through group purchasing organizations, bundling temperature monitoring with broader medical device contracts. Infection control protocols and joint commission accreditation requirements mandate specific accuracy classes and documentation formats.
- Laboratories:Research institutions and clinical testing facilities prioritize calibration stability and interoperability with laboratory information management systems.
- Restaurants:Food service operators favor simple, durable devices with minimal training requirements and rapid response times.
- Manufacturing Plants:Process industries integrate sensors into SCADA and distributed control systems for real-time quality assurance.
Hospitals dominate value capture; laboratories exhibit the most demanding technical specifications.
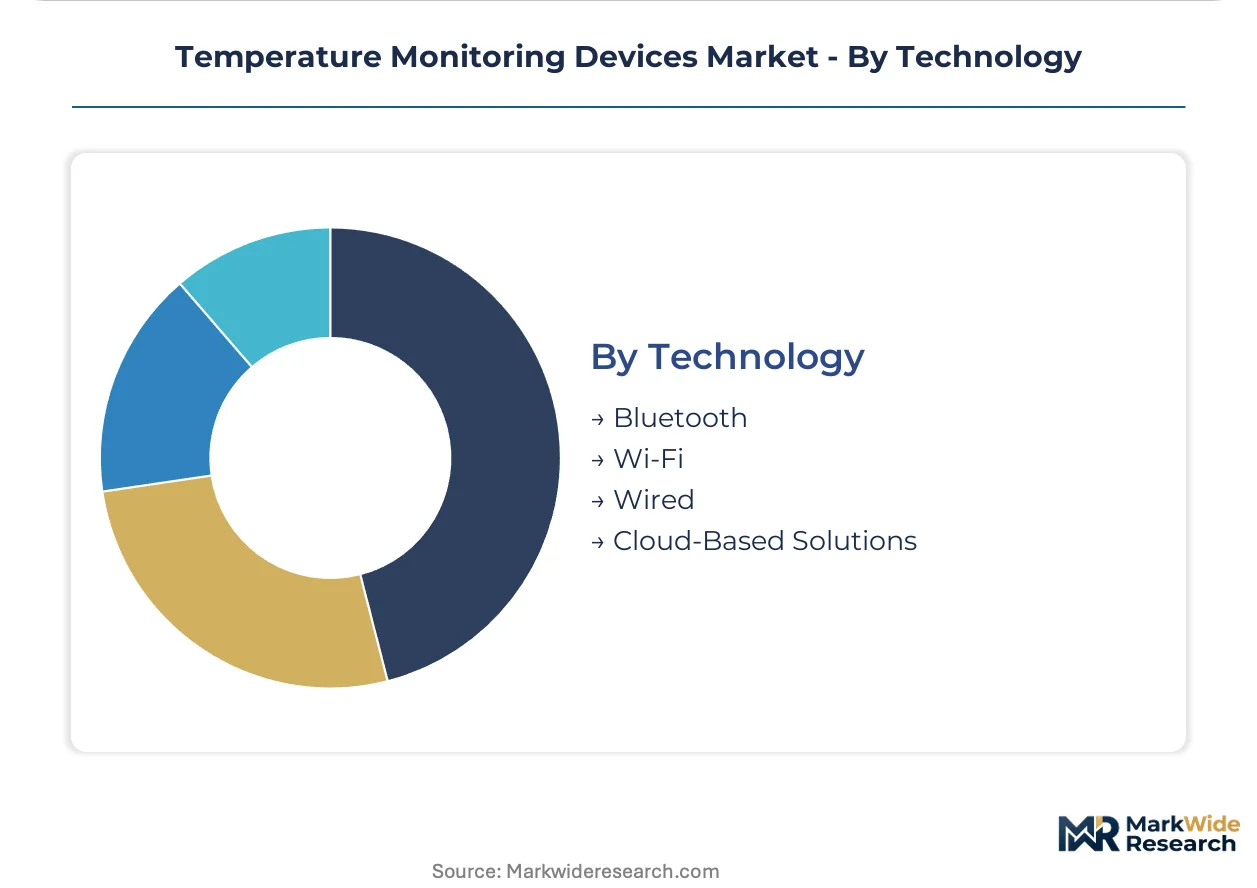
Technology:
Connectivity architecture determines installation economics, data accessibility, and cybersecurity exposure profiles across deployment scenarios.
- Bluetooth:Low-energy protocols eliminate pairing complexity and extend battery life for mobile healthcare applications including bedside patient monitoring and remote clinical trial participation. German hospital networks are standardizing on Bluetooth-enabled wearable formats for continuous core temperature tracking.
- Cloud-Based Solutions:Centralized data aggregation platforms with API accessibility enable enterprise-scale dashboarding and predictive analytics. Third-party logistics providers managing pharmaceutical cold chains are mandating cloud-native architectures to consolidate visibility across multi-site operations.
- Wi-Fi:Higher bandwidth connectivity supports streaming data applications in fixed infrastructure deployments.
- Wired:Hardwired sensor networks persist in industrial process control where electromagnetic interference immunity and deterministic latency outweigh installation flexibility.
Cloud-based solutions are gaining share fastest; wired installations retain dominance in heavy industrial settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical third-party logistics providers and precision manufacturing clusters concentrate procurement authority in Germany, the United States, and Japan, while cold chain infrastructure investments accelerate across India and Brazil.
United States
FDA mandates for continuous temperature monitoring in biologics distribution drive sensor deployment density across vaccine logistics networks. The agency's updated guidance tightens validation protocols for wireless monitoring systems. Third-party logistics hubs in Memphis, Tennessee and Louisville, Kentucky anchor pharmaceutical cold chain concentration.
Germany
Stringent pharmaceutical manufacturing standards and advanced chemical processing sustain premium demand for calibrated thermocouple assemblies. EMA Good Distribution Practice requirements accelerate compliance-driven replacement cycles for legacy monitoring equipment. Precision manufacturing clusters in Baden-Württemberg and Bavaria drive batch validation sensor procurement.
Japan
PMDA oversight of biologics storage conditions elevates device accuracy requirements for pharmaceutical distribution networks. METI industrial standards promote interoperability investments in building automation temperature sensors. Manufacturing concentration in the Kansai region around Osaka sustains demand for process control thermocouple assemblies.
India
CDSCO regulatory alignment with international cold chain standards expands validation requirements for pharmaceutical distribution. The country's national pharmaceutical regulator tightens documentation burdens for temperature monitoring device market access. Cold chain infrastructure investments in Maharashtra and Gujarat accelerate sensor adoption for generic drug exports.
Brazil
ANVISA pharmaceutical distribution regulations drive temperature assurance investments across vaccine and biologics logistics networks. National health surveillance requirements mandate auditable temperature documentation for imported pharmaceuticals. São Paulo-based pharmaceutical distributors concentrate procurement authority for regional cold chain monitoring systems.
Temperature Monitoring Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated structure where consolidated logistics providers negotiate enterprise contracts while mid-tier device manufacturers serve fragmented end-user segments. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with materials science portfolios, automation specialists with building control expertise, and healthcare-focused device manufacturers with regulatory certification depth. Dominant competitive moves include backward integration into sensor manufacturing to secure supply chain control and strategic partnerships with cloud platform providers to bypass proprietary data ecosystem fragmentation.
Among diversified industrial conglomerates, 3M Company and Emerson Electric Co. exemplify scale-driven positioning anchored in materials science and process automation expertise respectively. Honeywell International Inc. occupies a position bridging building automation heritage with healthcare-adjacent temperature monitoring applications. These three entities represent contrasting strategic postures: adhesive-backed sensor deployment specialization, industrial-grade thermocouple assembly dominance, and HVAC-centric ecosystem extension.
| Leading Market Players |
|---|
| 3M Company |
| Omron Healthcare |
| Philips Healthcare |
| GE Healthcare |
| Medtronic |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Abbott Laboratories |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in lithium battery cell production for wireless sensor power modules is compressing supplier margins while amplifying pricing power for qualified vendors serving FDA-validated pharmaceutical cold chain contracts.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate long-term supply agreements for wireless sensor manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated devices with ISO 17025 calibration from uncertified alternatives. Price differentiation rests on certification grade and after-sales validation support. Cost compression in economy-tier food safety indicators is intensifying because printed thermistor arrays are collapsing unit economics. Quick-service restaurant chains exhibit highest price sensitivity; German precision manufacturing clusters show lowest.
Supply Chain Analysis
Upstream feedstock concentration in semiconductor wafer fabrication centers on Taiwan, South Korea, and the United States. Sensor manufacturing draws from lithium-ion cells, MEMS thermopile substrates, and Bluetooth radio modules. Single-source vulnerability in rare-earth magnet supply for thermocouple cold junction compensation creates chokepoint exposure. Distribution runs through pharmaceutical third-party logistics providers consolidating enterprise procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as proprietary cloud fragmentation gives way to API-standardized interoperability, with EMA-mandated data portability accelerating ecosystem openness.
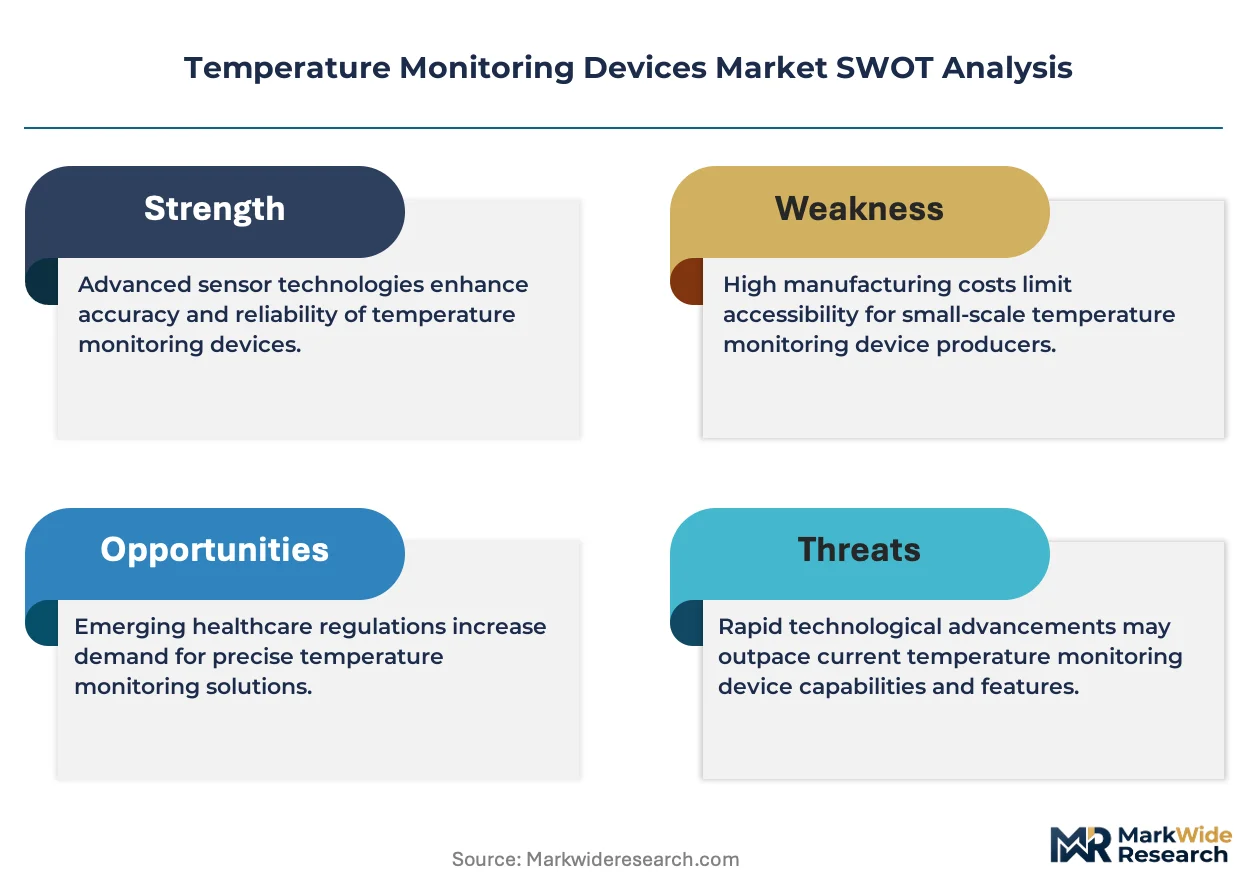
For Market Incumbents: Harden cloud platform moats through backward integration into sensor silicon and exclusive calibration service bundling. Incumbent data logger manufacturers face displacement by sensor-native competitors; vertical integration into lithium battery cell supply secures allocation priority during input scarcity. For New Entrants and Emerging Players: Direct-to-patient pharmaceutical delivery for home infusion biologics represents the most penetrable entry point, with disposable printed sensor formats bypassing incumbent validation overhead. Southeast Asian cold chain infrastructure investments offer secondary beachhead. Go-to-market through contract packaging organization pilot programs accelerates scale without GPO channel conflict. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across printed electronics sensor manufacturing as roll-to-roll fabrication achieves pharmaceutical-grade yield rates. Acquisition targets with NIST-traceable calibration laboratory networks and existing FDA master files offer defensible positioning. Watch for lithium supply contract renegotiations as inflection signal for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API standardization bypasses proprietary cloud lock-in threatening multi-site pharmaceutical operators. |
| Backward Integration | In-house lithium battery cell production secures allocation priority during supply scarcity periods. |
| Regulatory Certification Investment | FDA master file establishment accelerates validation timelines for wireless continuous monitoring systems. |
| Strategic Partnership | Calibration laboratory alliances address ISO 17025-accredited metrology expertise scarcity in distributed geographies. |
| Product Launch | Disposable printed thermistor formats collapse unit economics for single-use cold chain indicators. |
Study Parameters
The analysis maps wireless sensor networks, data logger validation protocols, infrared thermometer point-of-care applications, and thermocouple industrial process control, each validated through biomedical engineers, pharmaceutical cold chain logistics directors, GPO contracts managers, and calibration laboratory technical leads. Primary interview intelligence combines with FDA 483 inspection observations, EMA Good Distribution Practice guidance documents, ISO 13485 certification registries, and customs trade data for sensor component flows. Bottom-up device shipment modeling and top-down pharmaceutical cold chain expenditure estimates provide triangulation.
Assumptions held fixed include regulatory enforcement intensity for biologics temperature monitoring and lithium battery cell pricing trajectories; variables tested include Bluetooth protocol adoption rates and printed sensor yield improvements. Segmentation dimensions span device type, application category, connectivity architecture, and regional regulatory cluster. CAGRs derive from installed base growth and replacement cycle compression. Forecast inputs incorporate pharmaceutical third-party logistics provider capital expenditure plans and REACH mercury thermometer phase-out timelines.
Practitioners should monitor lithium supply contract renegotiations and FDA warning letter trends for biologics temperature excursions for early signals of forecast revision. Cross-checking against pharmaceutical cold chain insurance premium indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Sensor Bearing Market