
 Processor Chip Market | 2026-2036
Processor Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Processor Chip Market Insights
Automotive OEM demand is rebalancing processor chip procurement toward embedded systems for autonomous driving and in-vehicle infotainment. Nvidia dominates AI accelerator architecture for data centers and extends its software-coupled hardware strategy across cloud service providers. Intel sustains legacy x86 dominance in enterprise servers while competing aggressively in foundry services. TSMC anchors advanced node manufacturing at 3nm and below, controlling the majority of leading-edge capacity.
A processor chip is a semiconductor device containing integrated circuits that execute arithmetic, logic, and control instructions, typically fabricated on silicon wafers using photolithography with feature sizes now reaching 2-3 nanometers. Its primary purpose is to serve as the computational brain of electronic systems, from smartphones to supercomputers. Microprocessors command the largest revenue pool in personal computing and data center infrastructure, while embedded processors are capturing margin growth from automotive and industrial automation end users. FinFET technology remains the workhorse for sub-7nm production, though GaN is gaining traction in power-efficient radio frequency applications.
The U.S. CHIPS Act, EU Chips Act, and China's MIIT dual carbon goals are reshaping where fabrication capacity gets built and which equipment suppliers gain market access. FDA and NHTSA standards in the United States, plus EU automotive safety regulations, mandate functional safety certification for processors deployed in medical devices and autonomous vehicles. Stakeholders must monitor which regulatory jurisdictions secure pilot production lines first, as local content rules will determine supplier eligibility for public procurement and defense contracts.
Market Dynamics
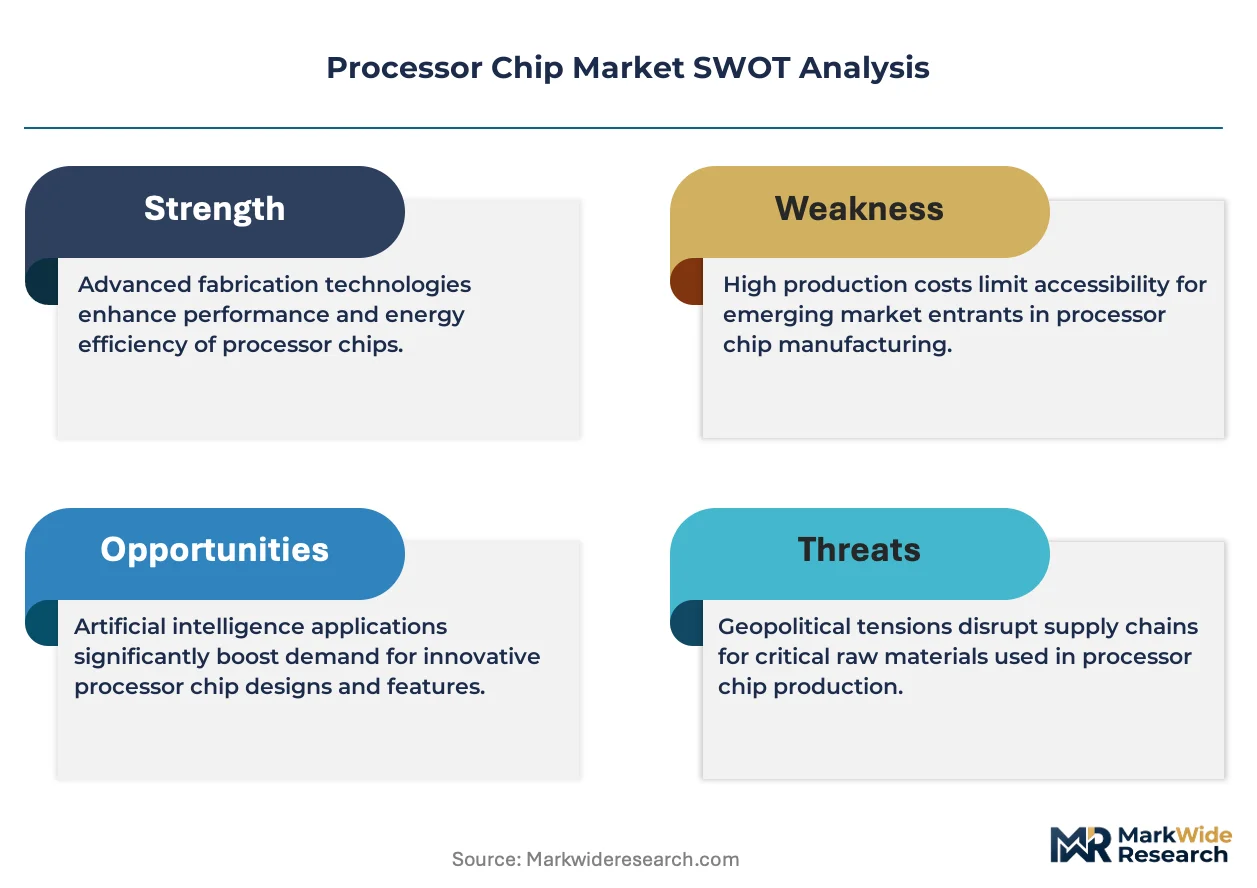
Advanced node fabrication capacity is concentrating among a handful of foundry operators, creating supply bottlenecks that force fabless designers into long-term capacity reservations and reshape competitive access to leading-edge silicon.
Growth Catalysts
- AI Training Infrastructure Buildout:Hyperscale data center operators are commissioning specialized accelerator clusters, pulling wafer starts toward high-margin logic dies.
- U.S. CHIPS Act Subsidies:Domestic fabrication incentives are redirecting capital expenditure toward Arizona, Texas, and Ohio greenfield sites.
- Automotive Functional Safety Mandates:NHTSA and EU automotive safety regulations are mandating ISO 26262-certified processors for autonomous driving subsystems.
Market Restraints
- Extreme Ultraviolet Lithography Dependency:Sub-5nm production requires ASML EUV equipment with 18-month lead times and single-source vulnerability.
- Advanced Substrate Cost Inflation:CoWoS and other 2.5D/3D packaging substrates face capacity constraints that inflate unit economics for AI accelerators.
- Export Control Friction:U.S. Bureau of Industry and Security restrictions on high-bandwidth memory and advanced GPU shipments to China are segmenting addressable demand.
Strategic Opportunities
- India Semiconductor Ecosystem:PLI scheme incentives and Gujarat-Vedanta-Foxconn joint ventures are creating captive demand for trailing-edge and mature-node capacity.
- Chiplets and Disaggregated Architecture:UCIe standardization is enabling heterogeneous integration that decouples process-node requirements from system performance.
- Edge AI Inference Deployment:Industrial automation and smart city infrastructure in Germany and Japan are creating distributed compute demand outside hyperscale concentration.
Industry Challenges
- Packaging Engineering Talent Scarcity:CoWoS, EMIB, and hybrid bonding expertise resides within a limited pool of TSMC, Intel, and Amkor specialists.
- Multi-Year Certification Cycles:Automotive and medical device processors require 24-36 month FDA and ISO 13485 validation timelines that compress product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processor Chip Market |
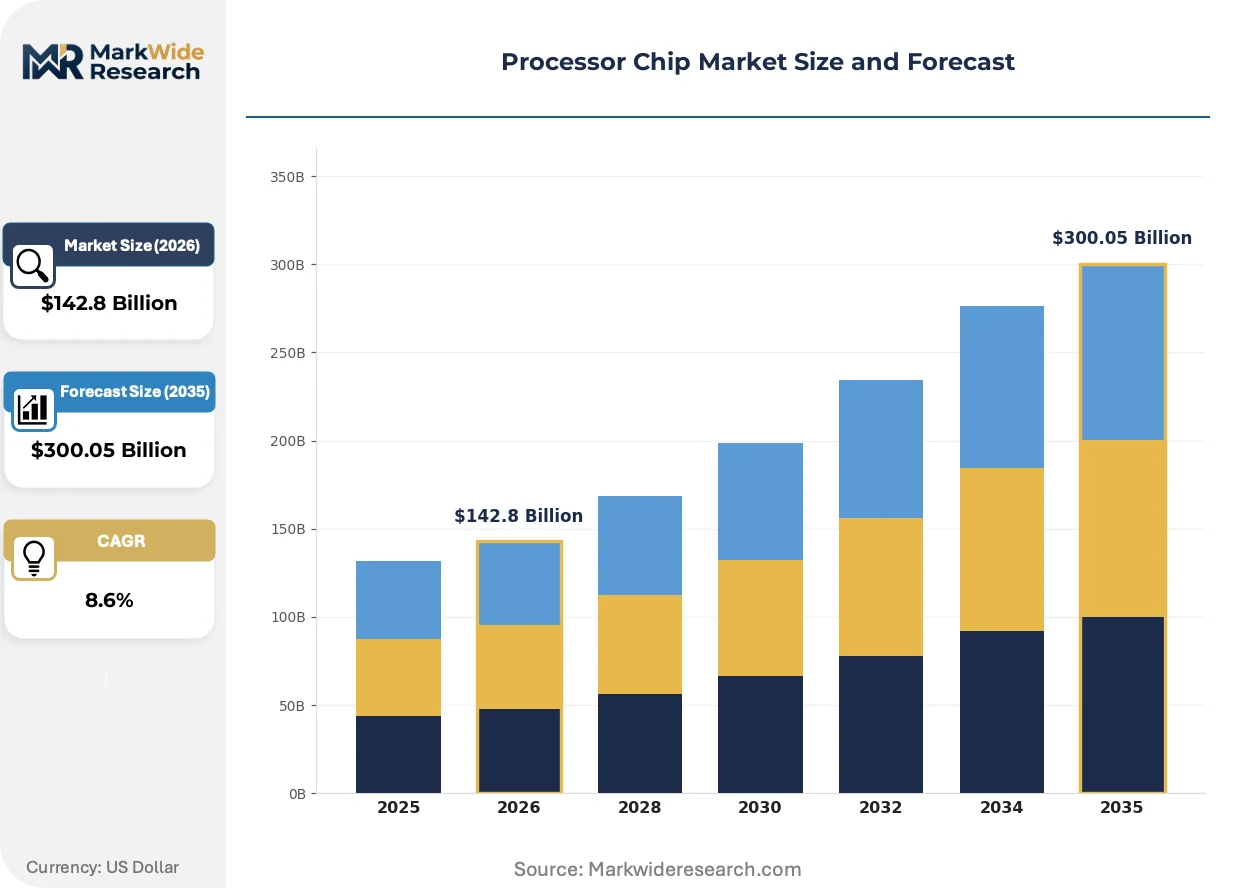
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $300.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Microprocessors, Digital Signal Processors, Embedded Processors Technology: CMOS, FinFET, SOI, GaN End User: Consumer Electronics, Automotive OEMs, Industrial Automation, Telecommunications Application: IoT Devices, Gaming Consoles, Servers, Workstations |
| Companies Covered | Nvidia, Intel, AMD, Qualcomm, MediaTek, Apple, TSMC, Samsung Electronics, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processor Chip Market Trends and Innovations
Silicon photonics co-packaging and backside power delivery are converging to redefine power-bandwidth-cost tradeoffs at the chip-package-system boundary. These shifts are compressing traditional roadmaps and forcing co-development across foundry, OSAT, and systems integrators.
Gate-all-around transistor architecture is overtaking FinFET as the dominant geometry for 2nm-class production. Samsung Foundry and TSMC are ramping GAA processes for mobile SoCs and data center CPUs in 2025-2026. This transition is enabling voltage scaling that FinFET could not deliver, though it demands new design-rule compliance and EDA tool requalification.
The EU AI Act risk-based classification system is imposing documentation and conformity assessment obligations on processors deployed in high-risk applications. Medical imaging and autonomous vehicle compute modules face mandatory CE marking with notified body involvement. European OEMs are responding by pre-integrating certified reference designs that accelerate downstream system validation.
Hyperscale buyers are consolidating procurement through direct foundry relationships that bypass traditional distributor channels. Cloud service providers in the United States and Taiwan are negotiating multi-year wafer supply agreements with capacity prepayment structures. This disintermediation is compressing margin pools for broadline semiconductor distributors and reallocating working capital requirements toward captive inventory positions.
Processor Chip Market Segmentation
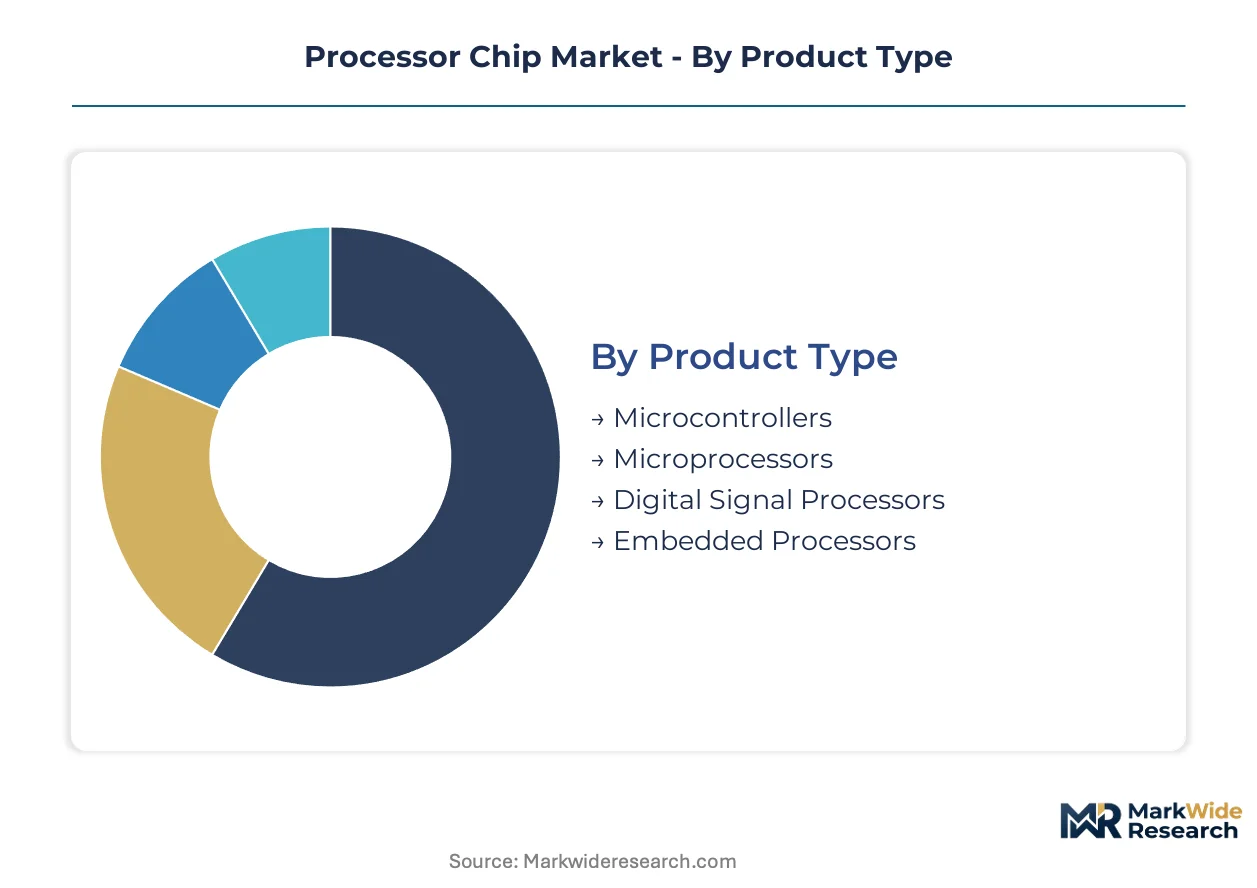
Processor chip procurement decisions hinge on power-performance-cost tradeoffs that vary dramatically across end-use contexts. Buyers in data centers prioritize thermal efficiency and parallel throughput, while automotive OEMs demand functional safety certification and extended temperature tolerance.
Product Type:
End-users select processor architectures based on computational intensity requirements and real-time constraint profiles.
- Microprocessors:General-purpose CPUs execute complex instruction sets across operating systems, dominating personal computing and enterprise server infrastructure. Intel and AMD x86 designs anchor data center procurement in the United States, though ARM-based alternatives are gaining traction in cloud-native deployments.
- Microcontrollers:Compact integrated systems combine processor core with memory and peripherals on single dies, enabling deterministic control in resource-constrained environments. Automotive body electronics and industrial motor controllers in Germany and Japan drive 8-bit and 32-bit MCU demand with ISO 26262 compliance requirements.
- Digital Signal Processors:Specialized architectures optimize multiply-accumulate operations for real-time data stream processing. Baseband processing in 5G infrastructure and audio processing in consumer devices constitute primary demand pools.
- Embedded Processors:Application-specific designs integrate hardware accelerators for targeted workloads. Smart factory edge nodes in Taiwan and South Korea deploy RISC-V and ARM-based embedded solutions for predictive maintenance analytics.
Volume sits with microprocessors; growth tilts toward microcontrollers.
Technology:
Process node selection determines power leakage characteristics and maximum clock frequencies achievable at given thermal envelopes.
- FinFET:Three-dimensional transistor geometry with raised channel fins enables superior electrostatic control over planar designs. TSMC's 5nm and 3nm FinFET variants supply Apple and Nvidia mobile and AI accelerator production.
- CMOS:Complementary metal-oxide-semiconductor remains the foundational fabrication approach for mature nodes above 28nm. Cost-sensitive IoT sensor hubs and automotive body controllers in India leverage CMOS processes for trailing-edge economics.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance for RF and radiation-hardened applications. Aerospace and satellite communication systems specify SOI-based processors for single-event upset immunity.
- GaN:Gallium nitride wide-bandgap semiconductors deliver superior electron mobility for high-frequency power conversion. 5G base station amplifiers and electric vehicle onboard chargers in China adopt GaN power processors for efficiency gains.
FinFET commands current wafer starts; GaN climbs the fastest in RF and power segments.
End User:
Customer procurement patterns diverge based on volume scale, certification burden, and software ecosystem lock-in.
- Automotive OEMs:Tier-1 suppliers and vehicle manufacturers specify processors for powertrain control, ADAS compute, and cabin infotainment. NHTSA and EU automotive safety regulations mandate ASIL-D certification for autonomous driving subsystems, extending qualification cycles.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs prioritize die size optimization and energy efficiency for battery-constrained devices. Apple, Samsung, and Xiaomi flagship launches drive annual demand spikes for leading-edge mobile SoCs.
- Industrial Automation:Factory automation vendors deploy edge processors for real-time control and machine vision. Siemens and Rockwell Automation specify extended-temperature processors for shop-floor programmable logic controllers.
- Telecommunications:Network equipment manufacturers source processors for baseband processing, routing, and optical transport. Ericsson and Nokia 5G radio unit deployments in Europe and North America consume specialized DSP and FPGA companion devices.
Consumer electronics absorbs highest unit volumes; automotive OEMs capture steepest margin expansion.
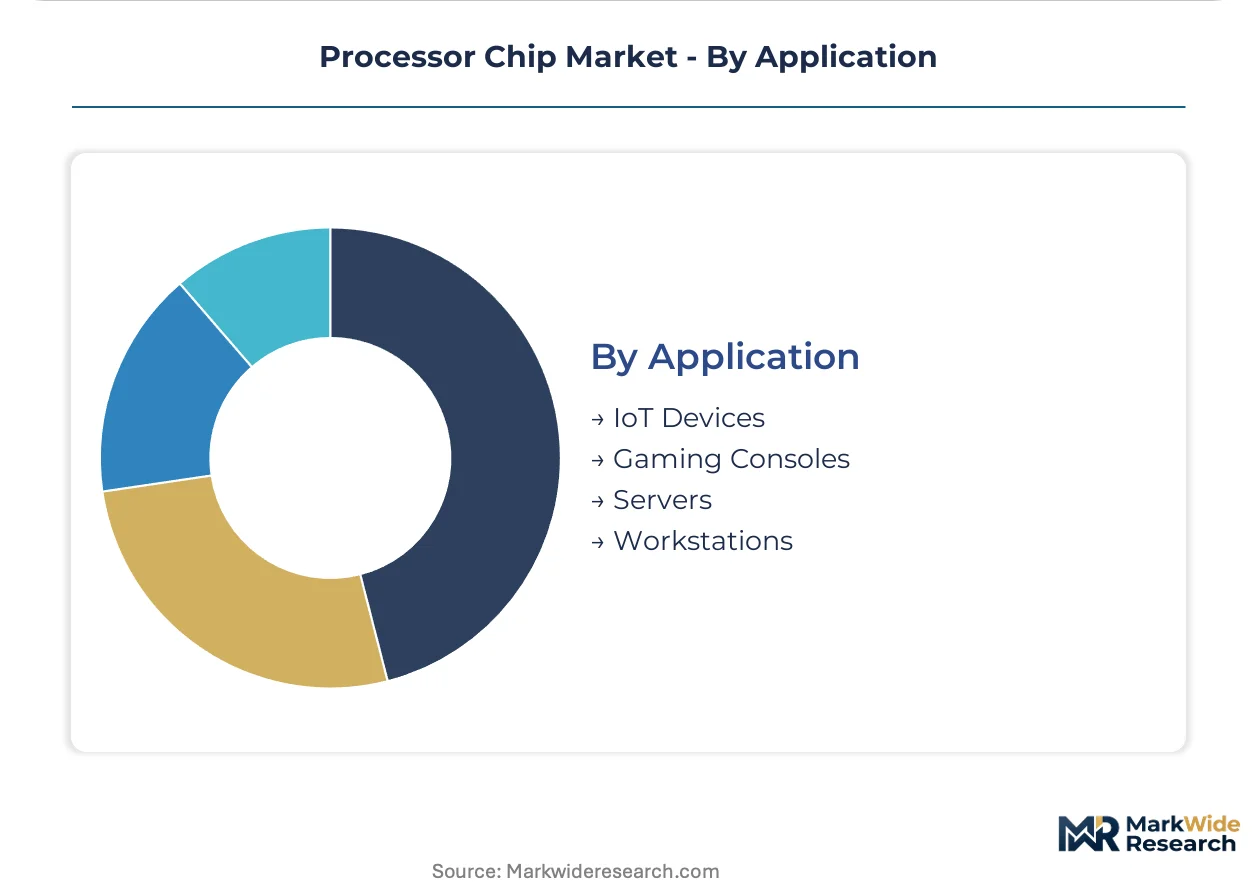
Application:
Workload characteristics dictate memory hierarchy design, I/O bandwidth requirements, and accelerator integration strategies.
- Servers:Data center compute nodes execute virtualization, database, and AI training workloads at massive scale. Hyperscale operators in the United States and Taiwan negotiate direct foundry relationships for custom CPU and AI accelerator silicon.
- IoT Devices:Distributed sensors and actuators require ultra-low-power processors with intermittent duty cycles. Smart city infrastructure in Japan and Germany deploys energy-harvesting edge processors for environmental monitoring.
- Gaming Consoles:Fixed-function graphics pipelines and unified memory architectures optimize for real-time rendering. Sony PlayStation and Microsoft Xbox generational launches concentrate procurement for 7nm-class semi-custom AMD processors.
- Workstations:Professional content creation and engineering simulation demand high-core-count processors with ECC memory support. Media production houses in California and visual effects studios in the United Kingdom specify Intel Xeon and AMD Threadripper configurations.
Servers dominate aggregate silicon area consumption; IoT devices expand most quickly in unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processor chip fabrication concentrates in East Asian foundry clusters, while consumption spreads across North American data centers, European automotive hubs, and Chinese device assembly lines. This geographic mismatch drives cross-border wafer shipments and shapes tariff exposure. Subsidy competition among Washington, Brussels, and Beijing is redirecting where new fabs rise.
United States
Hyperscale cloud operators in Virginia and Oregon drive demand for AI training accelerators and high-core-count server CPUs. The CHIPS Act directs $52 billion toward domestic fabrication, with Intel and TSMC breaking ground in Arizona and Ohio. Phoenix anchors emerging leading-edge capacity as foundry operators secure water rights and utility interconnections for 3nm-class production.
China
Domestic smartphone OEMs and EV manufacturers consume mature-node processors for infotainment and battery management systems. MIIT dual carbon goals and import substitution mandates steer procurement toward indigenous foundry capacity in Shanghai and Beijing. SMIC expands 28nm and 14nm output in Pudong despite equipment access constraints from Bureau of Industry and Security restrictions.
South Korea
Samsung Electronics and SK Hynix anchor memory-intensive processor packaging for AI accelerators, leveraging HBM3 supply advantages. Government tax credits under the K-Chips Act support $450 billion in private semiconductor investment through 2042. Pyeongtaek hosts the world's largest memory fab complex, with Samsung Foundry adding 3nm logic capacity for external customers.
Germany
BMW, Mercedes-Benz, and Volkswagen specify ASIL-D certified embedded processors for autonomous driving and powertrain control. The EU Chips Act identifies Dresden and Magdeburg as strategic fab locations, with Intel securing subsidies for leading-edge production. Saxony's Silicon Saxony cluster hosts Bosch, GlobalFoundries, and X-Fab operations serving automotive Tier-1 suppliers.
Taiwan
TSMC produces the majority of sub-5nm logic dies for Apple, Nvidia, and AMD at Hsinchu and Tainan facilities. The island's foundry dominance creates single-source vulnerability for advanced node access. Taichung hosts expanding CoWoS packaging capacity as AI accelerator demand outstips substrate supply, with government support for water recycling and renewable energy integration.
Processor Chip Market Competitive Landscape
Top-tier vendors anchor leading-edge logic and memory production, while mid-tier foundries compete on mature-node economics and specialty analog processes. The market structures around three strategic archetypes: integrated device manufacturers with captive fabs, pure-play foundries serving fabless designers, and fabless semiconductor houses controlling architecture and software ecosystems. Dominant competitive moves include multi-year wafer supply agreements with capacity prepayment structures, and heterogeneous integration partnerships spanning foundry, OSAT, and systems integrators.
Within the fabless architecture tier, Nvidia and AMD exemplify software-coupled hardware strategies that lock cloud service providers into proprietary ecosystems. TSMC occupies a position as the dominant pure-play foundry for advanced node production, with Samsung Electronics representing the integrated alternative combining memory, logic, and packaging capabilities. Intel anchors the IDM-plus-foundry hybrid model as it pursues external customer revenue while defending x86 server market position.
| Leading Market Players |
|---|
| Nvidia |
| Intel |
| AMD |
| Qualcomm |
| MediaTek |
| Apple |
| TSMC |
| Samsung Electronics |
| Broadcom |
| Others |
Pricing and Supply Chain Analysis
EUV scanner depreciation and photoresist chemistry costs cascade through foundry wafer pricing tiers, compressing margin structures for fabless designers at mature nodes while inflating premiums for sub-3nm capacity reservations.
Pricing Analysis
Cost-down pressure on trailing-edge microcontrollers accelerates because automotive OEMs in Germany and Japan are consolidating procurement volumes around qualified suppliers. Three-tier pricing structure across automotive-grade, industrial-grade, and commercial-grade certification levels separates ASIL-D validated silicon from standard temperature-range alternatives. Price differentiation hinges on ISO 26262 compliance tier and wafer volume commitment scale, with Tier-1 automotive buyers least sensitive to unit cost and IoT module makers most responsive to per-die economics.
Supply Chain Analysis
Packaging engineering talent shortages in Taiwan, South Korea, and Arizona constrain CoWoS and hybrid bonding throughput expansion. Advanced substrate supply draws from Japanese BT resin suppliers, Taiwanese ABF laminate manufacturers, and Korean organic substrate specialists. Single-source vulnerability concentrates in ASML EUV equipment access, with distribution running through direct foundry relationships that bypass traditional semiconductor distributors for hyperscale cloud operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced node fabrication economics are forcing consolidation among second-tier foundries, with capital intensity and EUV equipment access barriers eliminating subscale competitors.
For Market Incumbents: Anticipate margin compression in mature-node segments as Chinese foundries expand 28nm and 14nm output under MIIT import substitution mandates. Defend position through backward integration into CoWoS packaging capacity in Taiwan and Arizona, while accelerating R&D investment in gate-all-around transistor architecture to maintain process leadership against Samsung Foundry. For New Entrants and Emerging Players: RISC-V core IP licensing offers a technology-first wedge into industrial automation edge nodes in Germany and Japan, where deterministic control requirements and extended temperature specifications create qualification barriers for established ARM-based suppliers. Target smart factory predictive maintenance applications with application-specific embedded processors that bypass hyperscale cloud concentration. For Investors and Strategic Acquirers: Intel securing CHIPS Act subsidies for Ohio and Arizona greenfield sites is the leading indicator that IDM-plus-foundry hybrid models will capture external customer revenue previously flowing to pure-play alternatives. Long-term viability favors vertically integrated specialists with captive advanced packaging capabilities. Watch for TSMC capacity reservation prepayment structures as the signal that fabless designer working capital requirements are shifting toward captive inventory positions.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Node Capacity Expansion | TSMC and Intel Arizona fabs secure water rights and utility interconnections for 3nm-class production. |
| Heterogeneous Integration Partnership | UCIe standardization enables chiplets that decouple process-node requirements from system performance. |
| Direct Foundry Relationship Consolidation | Hyperscale buyers bypass distributors through multi-year wafer supply agreements with capacity prepayment. |
| Automotive Functional Safety Certification | ISO 26262 ASIL-D compliance extends qualification cycles and locks in Tier-1 supplier relationships. |
| Silicon Photonics Co-Packaging Investment | Backside power delivery convergence redefines power-bandwidth-cost tradeoffs at chip-package boundaries. |
Research Methodology
Independent corroboration across foundry operations executives, fabless semiconductor CTOs, and automotive Tier-1 procurement directors underwrites the qualitative findings. Primary interviews with TSMC and Intel supply chain managers, combined with secondary validation from SEC 10-K filings, SEMI equipment shipment data, and Bureau of Industry and Security export control notifications, anchor the analysis. Bottom-up wafer start projections and top-down semiconductor capex aggregation triangulate market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. The analytical framework models segmentation by product type, process node technology, end-user vertical, and geographic production cluster. CAGRs derive from foundry capacity expansion schedules, equipment lead time trajectories, and AI training infrastructure deployment curves reported by hyperscale cloud operators.
Several conditions sit outside the modeled scope, including unannounced export control expansions, abrupt foundry equipment delivery disruptions, and geopolitical events affecting Taiwan Strait logistics. Forecasts reflect assumptions about subsidy program continuity and water rights adjudication in Arizona. Material deviation in CHIPS Act funding disbursement timelines or EUV equipment access restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
VR Gaming Hardware Chipsets Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
5G Processor Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Edge Artificial Intelligence Chips Market